
 Automatic Webbing Cutting Machines Market | 2026-2036
Automatic Webbing Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Webbing Cutting Machines Market Insights
Aftermarket service revenue for blade refurbishment and calibration is fragmenting across regional service networks rather than concentrating with original manufacturers. Liba Maschinenfabrik GmbH anchors its position through proprietary hot-knife systems for technical textiles, while Wei Li Machine competes on cost-optimized mechanical blade platforms for Asian strap producers. Creissans SL differentiates through specialized ultrasonic cutting heads that reduce thermal deformation in synthetic webbing.
Automatic webbing cutting machines are industrial equipment designed to sever woven tapes, straps, and narrow fabrics with programmable length precision, typically achieving tolerances within one millimeter through servo-driven feed mechanisms and heated or mechanical cutting edges. These systems serve primary commercial purposes in safety-critical applications where consistent cut quality directly determines load-bearing certification of finished harnesses, slings, and restraint systems. Fully automatic platforms lead installed capacity across high-volume safety harness operations, while ultrasonic cutting technology captures expanding share in technical textile segments where sealed edges prevent synthetic fiber fraying. Programmable systems sustain premium positioning among manufacturers serving automotive seatbelt contracts with frequent changeover requirements.
OSHA workplace safety mandates and ANSI fall-protection standards shape product specifications by requiring traceable cut consistency in certified harness webbing, effectively filtering non-compliant equipment from North American procurement lists. The EU Machinery Directive and CE marking requirements enforce operator guarding and emergency-stop protocols that add engineering cost but create barrier to entry for uncertified Asian suppliers. Stakeholders must monitor evolving REACH restrictions on synthetic fiber coatings, as chemical compliance shifts will cascade into cutting process requirements for thermal and laser systems handling treated webbing materials.
Market Dynamics
Safety harness certification requirements from ANSI and OSHA are compressing equipment replacement cycles as manufacturers face audit pressure for traceable cut consistency in load-bearing webbing production.
Growth Catalysts
- OSHA Fall-Protection Mandates:Workplace safety enforcement in the United States requires documented cut precision in certified harness manufacturing, forcing equipment upgrades at domestic automotive and aerospace suppliers.
- Ultrasonic Sealing Technology:Synthetic fiber applications in technical textiles demand sealed edges to prevent fraying, expanding machine replacement demand among European belt and strap producers.
- China:Domestic textile machinery manufacturers scale automated cutting platforms to serve export-oriented safety equipment factories supplying global automotive seatbelt contracts.
Market Restraints
- CE Marking Compliance Costs:The EU Machinery Directive mandates operator guarding and emergency-stop protocols that add engineering expense, filtering uncertified Asian equipment from European procurement lists.
- Specialized Servo Component Supply:Precision feed mechanisms depend on concentrated German and Japanese motion control suppliers, creating vulnerability to extended lead times for replacement parts.
- Mechanical Blade Durability Limits:High-volume operations face thermal degradation of heated cutting edges in continuous runs, requiring frequent refurbishment cycles that interrupt production.
Strategic Opportunities
- India:The PLI scheme for technical textiles incentivizes domestic safety equipment manufacturing, creating first-mover advantage for automated cutting platform deployment in emerging strap and sling factories.
- REACH Chemical Compliance:Evolving restrictions on synthetic fiber coatings will cascade into thermal and laser cutting process requirements, favoring equipment suppliers with adaptive control systems.
- Aftermarket Service Networks:Blade refurbishment and calibration revenue is fragmenting across regional service providers rather than concentrating with original manufacturers, opening independent service territory.
Industry Challenges
- Mechatronics Integration Expertise:Servo-driven feed mechanisms and thermal control systems require cross-functional engineering talent scarce in traditional textile machinery maintenance workforces.
- ANSI Certification Timelines:Load-bearing harness manufacturers face extended validation periods for cut consistency documentation, delaying production line commissioning and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Webbing Cutting Machines Market |
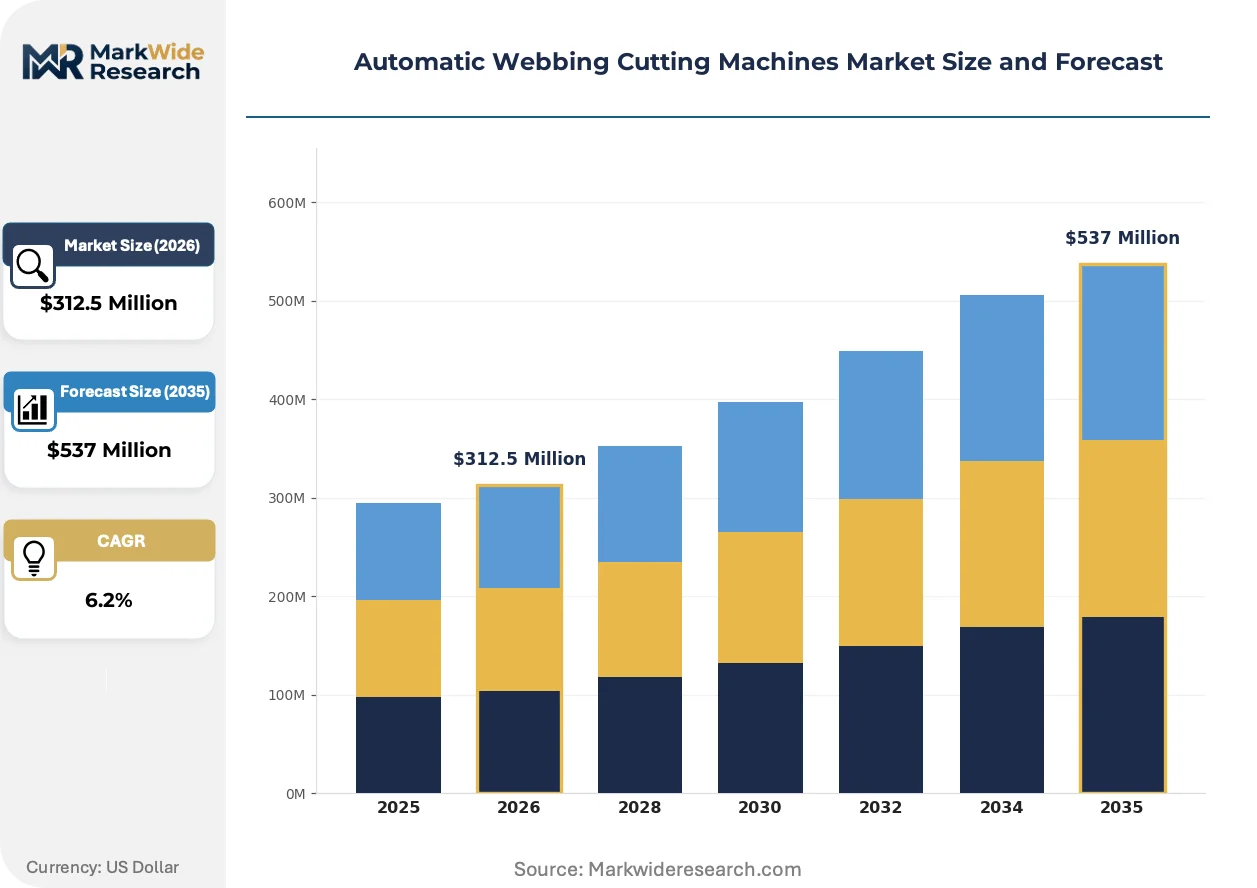
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $537 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi-Automatic, Programmable, Manual Assist Technology: Laser Cutting, Hot Knife, Ultrasonic Cutting, Mechanical Blade, Thermal Cutting Application: Strap Production, Textile Industry, Safety Harness, Furniture Manufacturing, Packaging Industry End User: Manufacturers, Textile Mills, Safety Equipment Providers, Upholstery Workshops |
| Companies Covered | Creissans SL, FIMIMACH, Heruik, KL-300, Leather Master Machine, Liba Maschinenfabrik GmbH, SM-360, SM-500, Wei Li Machine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Webbing Cutting Machines Market Trends and Innovations
Equipment architecture is converging around programmable platforms that accommodate frequent changeover requirements while thermal cutting technology faces displacement from ultrasonic and laser alternatives in technical textile segments.
Servo-driven mechanical cutting with integrated thermal edges remains the dominant platform for high-volume safety harness operations, but ultrasonic cutting heads are hybridizing with traditional feed mechanisms to serve synthetic webbing applications where sealed edges prevent fiber fraying. Automotive seatbelt manufacturers in Germany and the United States are piloting these hybrid systems for contracts requiring rapid material changeovers between polyester and aramid blends. The convergence is compressing pure mechanical blade market share in premium technical textile segments while extending equipment lifecycle value through modular upgrade paths.
REACH restrictions on per- and polyfluoroalkyl substances in synthetic fiber coatings are forcing thermal cutting equipment modifications to handle altered material thermal profiles without edge degradation. The European Chemicals Agency enforcement timeline is accelerating R&D investment among cutting head manufacturers serving EU-based strap and belt exporters. Technical textile producers in Italy and Portugal are retrofitting existing platforms with adaptive temperature control systems to maintain certification compliance without full equipment replacement.
Aftermarket service unbundling is disrupting traditional manufacturer-captive maintenance relationships as regional blade refurbishment specialists capture calibration and wear-part replacement revenue. Safety equipment producers in the United States are contracting independent service networks for scheduled maintenance rather than purchasing extended warranty packages from original equipment suppliers. The shift is most visible among mid-volume harness manufacturers in the southeastern automotive supply chain, where procurement teams prioritize uptime guarantees over brand-loyal service agreements.
Automatic Webbing Cutting Machines Market Segmentation
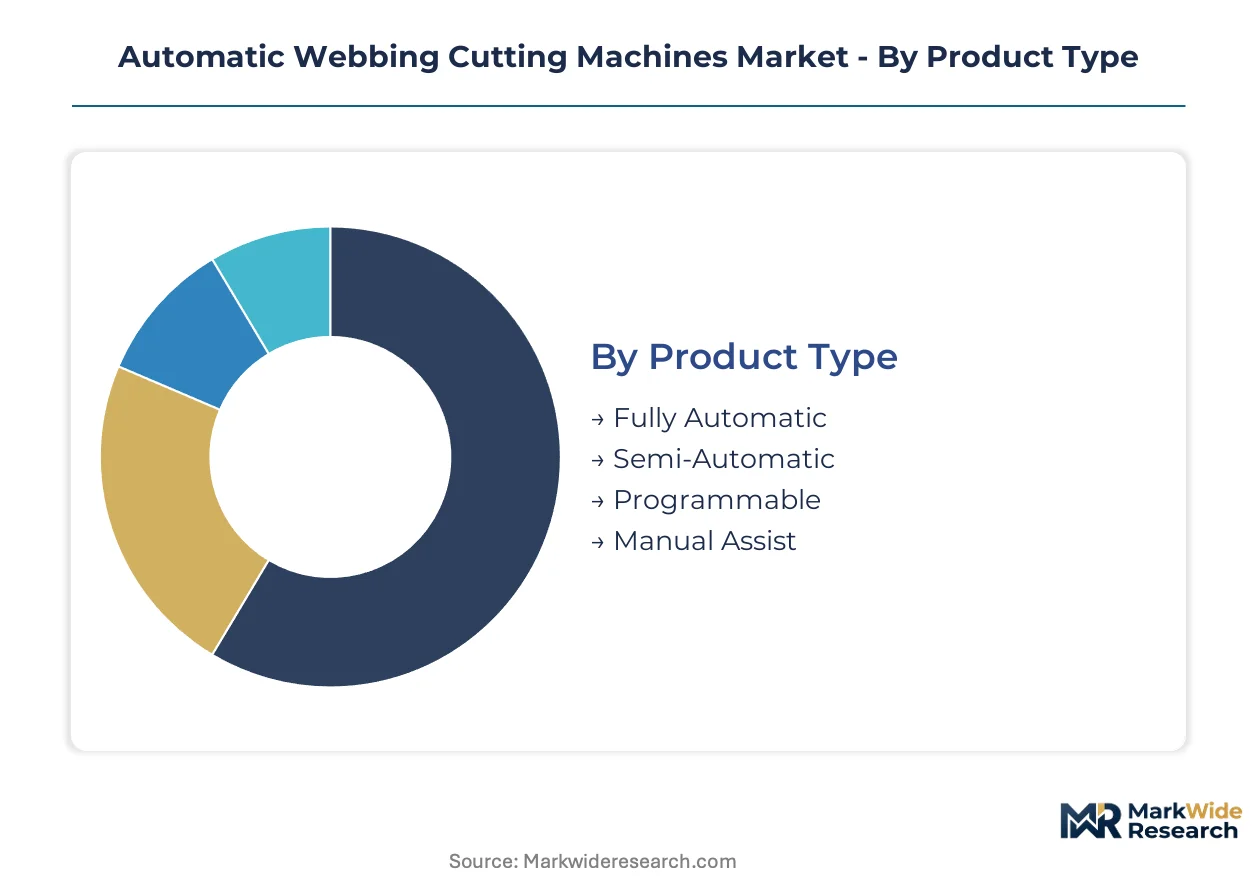
Segmentation in automatic webbing cutting machines determines service intensity, replacement cycles, and margin structures across distinct operational environments. Equipment configuration varies sharply between high-volume automotive safety harness operations and intermittent furniture upholstery workflows, creating divergent vendor strategies for aftermarket capture.
Product Type:
After-sales service intensity escalates with automation sophistication, as servo calibration and thermal edge refurbishment concentrate revenue in fully automatic installed bases.
- Fully Automatic:Servo-driven feed mechanisms achieve sub-millimeter length tolerances through programmable logic controllers with integrated heated or ultrasonic cutting heads. Demand concentrates among automotive seatbelt manufacturers in Germany and the United States facing ANSI certification audits for traceable cut consistency in load-bearing webbing production.
- Programmable:Modular platforms accommodate rapid material changeovers between polyester, aramid, and hybrid fiber specifications through stored cutting profiles. European technical textile producers in Italy and Portugal prioritize these systems for REACH-compliant strap exports requiring adaptive thermal control without full equipment replacement.
- Semi-Automatic:Operator-fed mechanisms with automated cutting cycles serve mid-volume safety equipment providers balancing throughput against capital constraints.
- Manual Assist:Basic motorized feed systems with hand-triggered cutting edges dominate upholstery workshops and small-scale packaging operations with intermittent production schedules.
By volume, Fully Automatic leads. By growth pace, Programmable is climbing the fastest.
Technology:
Cost tier stratification separates premium sealed-edge systems from commodity mechanical alternatives, with thermal management complexity driving maintenance contract pricing.
- Ultrasonic Cutting:High-frequency vibration welding seals synthetic fiber edges without thermal degradation, eliminating fraying in technical textile applications. Demand concentrates among European belt and strap producers serving automotive aramid blend contracts where fiber integrity determines load-bearing certification.
- Hot Knife:Heated blade systems sever thermoplastic webbing while simultaneously fusing cut edges through controlled temperature profiles. Chinese export-oriented strap factories scale these platforms for cost-optimized polyester safety harness production.
- Laser Cutting:Focused beam systems deliver non-contact severing with minimal material distortion for specialized technical textile geometries.
- Mechanical Blade:Physical shear mechanisms without thermal elements serve natural fiber applications and budget-constrained operations accepting higher edge fray rates.
- Thermal Cutting:Broad-category heated edge systems encompassing resistance-wire and conductive blade variants for mid-market synthetic webbing operations.
By installed base, Hot Knife dominates. By replacement demand, Ultrasonic Cutting is expanding most quickly.
Application:
Customer type concentration shapes regional equipment distribution, with safety-critical applications filtering procurement toward certified vendors and documented calibration protocols.
- Safety Harness:Fall-protection and restraint system manufacturing demands traceable cut precision under OSHA and ANSI mandates, compressing equipment replacement cycles among audited suppliers. North American automotive and aerospace contractors prioritize programmable platforms with documented calibration histories.
- Strap Production:Belt, sling, and tie-down manufacturing spans commodity polyester through high-performance aramid specifications. Indian technical textile producers under the PLI scheme deploy automated cutting capacity for emerging domestic safety equipment manufacturing.
- Textile Industry:Broad woven tape and narrow fabric operations serve apparel, industrial, and consumer goods supply chains with varying precision requirements.
- Furniture Manufacturing:Upholstery webbing and decorative strap cutting tolerates wider length variation, favoring manual assist and semi-automatic platforms.
- Packaging Industry:Polypropylene and polyester strapping production for logistics applications prioritizes throughput over edge sealing sophistication.
By revenue concentration, Safety Harness leads. By emerging market penetration, Strap Production is gaining share fastest.
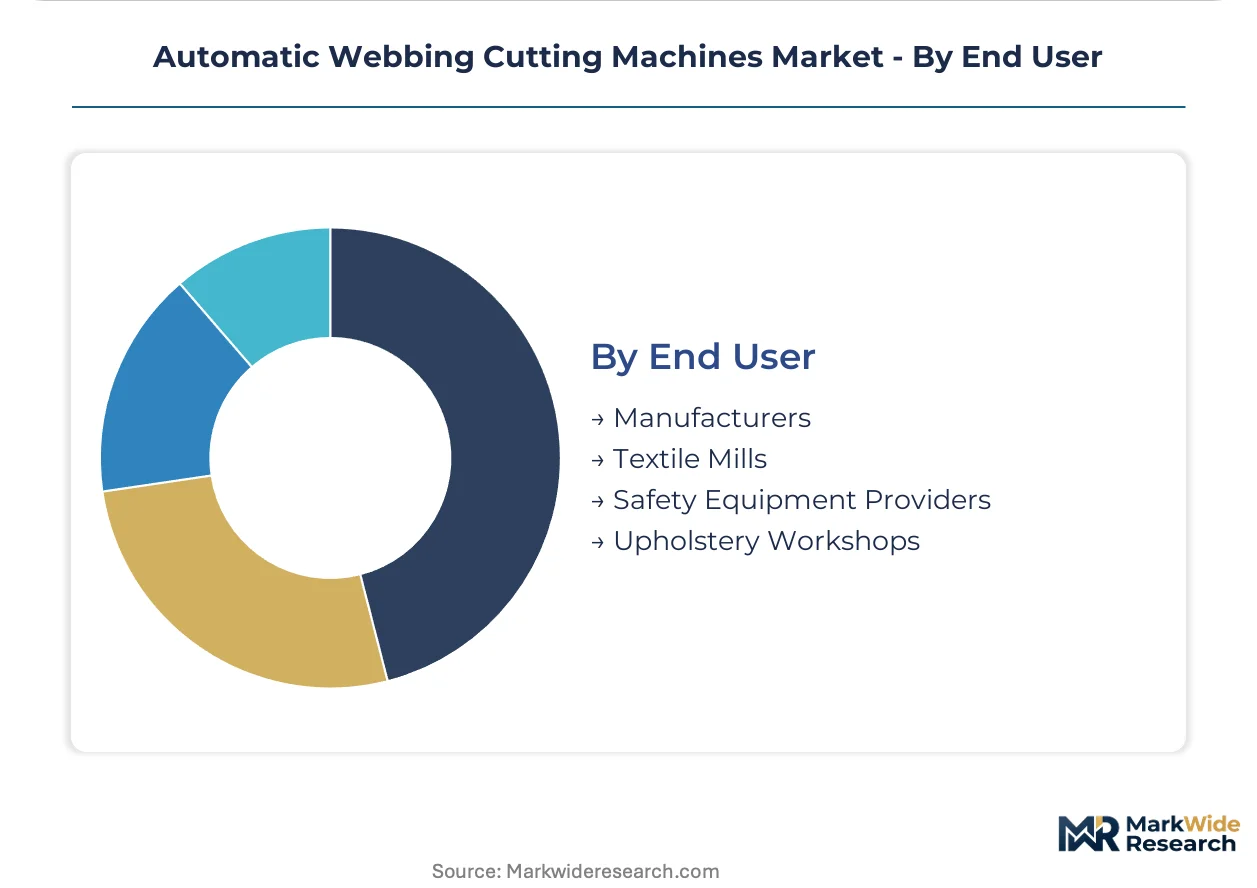
End User:
Volume scale and certification burden segment aftermarket profitability, with safety equipment providers generating disproportionate blade refurbishment and calibration service revenue.
- Safety Equipment Providers:Certified harness and restraint system manufacturers face mandatory audit documentation for cut consistency, creating captive demand for OEM-calibrated maintenance services. Southeastern United States automotive supply chain participants increasingly contract independent regional service networks for uptime guarantees.
- Manufacturers:Integrated producers of seatbelts, slings, and industrial straps balance in-house cutting capacity against outsourced webbing supply.
- Textile Mills:Narrow fabric producers supply intermediate webbing to downstream converters, prioritizing high-throughput fully automatic systems.
- Upholstery Workshops:Small-batch furniture and interior operations favor manual assist equipment with minimal maintenance requirements and low capital entry barriers.
By service revenue per installed unit, Safety Equipment Providers lead. By fleet expansion rate, Manufacturers are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. North American buyers prioritize OSHA-compliant programmable platforms for safety harness audits. European demand concentrates on REACH-adaptive ultrasonic systems. Asian procurement favors cost-optimized hot-knife capacity for export-oriented strap production.
United States
Automotive seatbelt manufacturers in Michigan and Tennessee drive demand for fully automatic servo systems with documented calibration histories. OSHA fall-protection enforcement compresses equipment replacement cycles among audited suppliers. The southeastern automotive supply chain increasingly contracts independent regional service networks for blade refurbishment and uptime guarantees.
Germany
Technical textile producers in Bavaria and Baden-Württemberg deploy hybrid ultrasonic-mechanical platforms for rapid material changeovers between polyester and aramid blends. CE marking requirements under the EU Machinery Directive filter uncertified Asian equipment from procurement lists. Stuttgart-area automotive suppliers pilot adaptive temperature control systems to maintain certification compliance.
China
Domestic textile machinery manufacturers scale automated cutting platforms for export-oriented safety equipment factories supplying global automotive contracts. MIIT industrial upgrading initiatives accelerate substitution of manual cutting capacity in Zhejiang and Jiangsu strap production clusters. Shanghai and Guangzhou belt exporters prioritize cost-optimized hot-knife systems for polyester safety harness production.
India
The PLI scheme for technical textiles incentivizes domestic safety equipment manufacturing in Gujarat and Tamil Nadu. CDSCO alignment with international standards shapes equipment specifications for emerging strap and sling factories. Mumbai-Pune industrial corridor producers deploy semi-automatic platforms balancing throughput against capital constraints.
Italy
REACH restrictions on synthetic fiber coatings force thermal cutting equipment modifications among Como and Prato technical textile exporters. ECHA enforcement timelines accelerate retrofit investment for adaptive temperature control systems. Northern Italian belt producers prioritize programmable platforms with modular upgrade paths over full equipment replacement.
Automatic Webbing Cutting Machines Market Competitive Landscape
Capability concentration sits with European specialists possessing proprietary hot-knife and ultrasonic integration expertise; scale advantage sits with Asian fabricators serving cost-optimized mechanical blade demand. The vendor base separates into three tiers: premium programmable platform suppliers, mid-market hybrid system providers, and commodity mechanical blade manufacturers. Strategic moves center on regional service network expansion and adaptive control system development for evolving chemical compliance requirements.
Within the European specialist tier, Liba Maschinenfabrik GmbH anchors proprietary thermal system expertise, while Creissans SL occupies a position in ultrasonic cutting head specialization. Wei Li Machine exemplifies the Asian scale-driven archetype. These three represent divergent competitive vectors: German engineering-intensive platforms, Spanish technical textile specialization, and Chinese cost-optimized mechanical systems.
| Leading Market Players |
|---|
| Creissans SL |
| FIMIMACH |
| Heruik |
| KL-300 |
| Leather Master Machine |
| Liba Maschinenfabrik GmbH |
| SM-360 |
| SM-500 |
| Wei Li Machine |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure between China and the United States compresses margin spreads across all equipment tiers while simultaneously reshaping supplier geography as manufacturers relocate final assembly to Vietnam and Mexico. This structural risk vector forces buyers toward longer contract terms to lock in component pricing, while OEMs absorb volatility through premium-tier bundling of calibration services with hardware.
Pricing Analysis
Long-term offtake agreements dominate procurement for high-volume automotive seatbelt manufacturers, insulating against servo component price volatility while spot purchasing persists among small-scale upholstery workshops. Three-tier pricing structure across premium programmable, standard semi-automatic, and economy manual-assist levels reflects certification grade and after-sales bundling intensity. Cost compression in mid-market hot-knife systems is intensifying because Chinese domestic producers scale export capacity. Safety equipment providers show least price sensitivity due to ANSI audit compliance requirements, while furniture manufacturers exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning as German and Japanese motion control suppliers concentrate precision servo production in single-source facilities. Component sourcing draws from Chinese steel fabrication, German sensor electronics, and Japanese servo motors. Single-source vulnerability in precision feed mechanism supply creates extended lead time exposure for North American harness manufacturers. Distribution runs through OEM-direct channels for fully automatic platforms and regional machinery distributors for semi-automatic equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as automotive safety harness capital expenditure rebounds from pandemic-depressed replacement cycles and OSHA audit intensity accelerates equipment refresh demand.
For Market Incumbents: Harden defensive positions by deepening backward integration into ultrasonic cutting head manufacturing and securing captive calibration service contracts with southeastern United States automotive suppliers. Liba Maschinenfabrik GmbH and Creissans SL should expand proprietary hot-knife and ultrasonic platform certification portfolios before REACH chemical compliance shifts alter thermal processing requirements. Regional service network density represents the critical lever against independent blade refurbishment specialists capturing aftermarket revenue. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-incentivized technical textile corridor by deploying cost-optimized semi-automatic platforms for emerging Gujarat and Tamil Nadu strap producers. White-space concentration sits in adaptive temperature control retrofits for Italian and Portuguese REACH-compliant exporters unwilling to undertake full equipment replacement. Go-to-market execution should emphasize modular upgrade paths and rapid deployment capabilities rather than premium positioning. For Investors and Strategic Acquirers: REACH enforcement timelines reshaping the acquisition landscape favor targets with adaptive thermal control R&D capabilities and established CE marking documentation. Long-term viability across the next decade rests on chemical compliance adaptability rather than pure mechanical cost positioning. The signal to watch is ECHA publication of restricted substance lists affecting synthetic fiber coating formulations, which will cascade immediately into cutting equipment specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Temperature Control Development | REACH compliance shifts in Italian technical textile exports require retrofit-ready thermal management systems. |
| Regional Service Network Expansion | Independent blade refurbishment specialists in the southeastern United States are capturing calibration revenue from OEMs. |
| Ultrasonic-Mechanical Hybrid Platform Launch | German automotive seatbelt manufacturers pilot these systems for rapid polyester-to-aramid changeovers. |
| Backward Integration into Servo Component Supply | Precision feed mechanism shortages from Japanese suppliers create vulnerability for high-volume harness producers. |
| India Manufacturing Footprint Establishment | PLI scheme incentives in Gujarat and Tamil Nadu create first-mover advantage for automated cutting deployment. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at safety harness manufacturers, procurement leads at automotive Tier 1 suppliers, aftermarket service heads at textile machinery distributors, and technical R&D directors at cutting head specialists, then refined against secondary validation from customs trade data, EU Machinery Directive enforcement records, SEC 10-K filings of exposed industrial equipment suppliers, and OSHA audit documentation requirements. Bottom-up equipment shipment tracking and top-down safety equipment production capacity estimates were triangulated to establish market sizing boundaries.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling across automation level, cutting technology type, end-use application, and geographic regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and capacity expansion announcements. Industry-specific forecast inputs included ANSI certification audit frequency trends and MIIT industrial upgrading initiative implementation timelines in Zhejiang and Jiangsu strap production clusters.
Stress conditions across tariff rate volatility, servo component lead time extension, and REACH chemical restriction enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OSHA mandate continuity and automotive seatbelt contract renewal patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Direct to Garment Printing Market
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Global Spinning Machinery Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market