
 Warping Machines Market | 2026-2036
Warping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Warping Machines Market Analytics
Carbon fiber is shifting from aerospace into automotive and wind energy preform manufacturing, forcing warping equipment makers to redesign tension control and creel systems for abrasive, high-modulus yarns. Karl Mayer Group leverages its decades of warp knitting integration to dominate technical textile lines. Tsudakoma Corp anchors Asian supply through precision electronics and localized service networks. Picanol Group competes by extending its weaving ecosystem into preparatory machinery with unified digital controls.
Warping machines mechanically arrange parallel yarns from multiple packages onto a beam or section beam, maintaining uniform tension within two to five percent deviation across thousands of ends to ensure defect-free downstream weaving and knitting. Beam width capacity ranging from 1800 to 5400 millimeters and creel sizes from 800 to 24000 ends define equipment class and capital intensity. Automatic systems lead capital deployment in high-volume textile mills where labor costs and throughput consistency determine ROI, while digital technology segments capture expanding margin pools as mills retrofit mechanical assets with IoT-enabled tension monitoring and predictive maintenance modules.
EU machinery directives and CE marking requirements enforced by national regulators in Germany and Italy shape equipment import standards and safety compliance costs for manufacturers serving European textile mills. China's SAMR and GB standards for industrial machinery certification, alongside India's BIS quality mandates for imported textile equipment, create divergent compliance pathways that influence regional product configurations. Stakeholders must monitor how carbon fiber handling specifications and evolving digital thread traceability standards reshape R&D priorities and capital allocation across preparatory machinery portfolios.
Market Dynamics
Carbon fiber preform manufacturing is forcing warping equipment suppliers to rebuild tension control architectures from the ground up, as abrasive high-modulus yarns destroy conventional ceramic guides and demand closed-loop load cell arrays operating at microsecond refresh rates.
Growth Catalysts
- REACH compliance deadlines:European textile mills must replace solvent-based sizing agents with waterborne alternatives by 2027, triggering beam-to-beam consistency requirements that only automated tension profiling systems can deliver.
- Wind turbine blade manufacturing:TPI Composites and Vestas are scaling carbon fiber spar cap production in Mexico and Turkey, pulling precision warping capacity into regional supply bases previously served by European equipment.
- India's PLI scheme for technical textiles:The Ministry of Textiles is subsidizing warp knitting capacity expansion in Surat and Coimbatore, concentrating preparatory machinery orders among domestic mills upgrading from manual sectional warping.
Market Restraints
- Specialized ceramic guide supply:Kyocera and CoorsTek control 70 percent of alumina-zirconia composite output suitable for carbon fiber handling, creating single-source vulnerability for European warping OEMs.
- GB standard certification timelines:China's SAMR requires 14-month type approval cycles for imported industrial machinery, freezing non-Chinese suppliers out of rapid capacity expansions.
- Recycled carbon fiber displacement:Pyrolysis-recovered fiber with inconsistent modulus is substituting for virgin material in non-structural automotive panels, reducing precision warping demand in cost-sensitive segments.
Strategic Opportunities
- Vietnam's technical textile corridor:Hyosung and Toray are building carbon fiber weaving capacity near Ho Chi Minh City ahead of EU-Vietnam FTA tariff advantages, creating first-mover equipment positioning for preparatory machinery suppliers.
- Digital thread traceability mandates:The EU Digital Product Passport regulation will require yarn origin documentation through beam production, opening retrofit markets for IoT-enabled warping systems with embedded RFID tagging.
- Servo motor convergence:Integration of direct-drive torque motors into beam drive systems eliminates mechanical gearboxes, enabling predictive vibration analysis that extends maintenance intervals by 40 percent.
Industry Challenges
- Mechatronics technician scarcity:German equipment manufacturers report 18-month backlogs for commissioning engineers capable of calibrating multi-axis tension control systems, delaying mill startups.
- Legacy Dornier and Sulzer loom integration:1990s-vintage weaving lines lack digital beam identification protocols, forcing costly middleware development for unified mill-wide control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warping Machines Market |
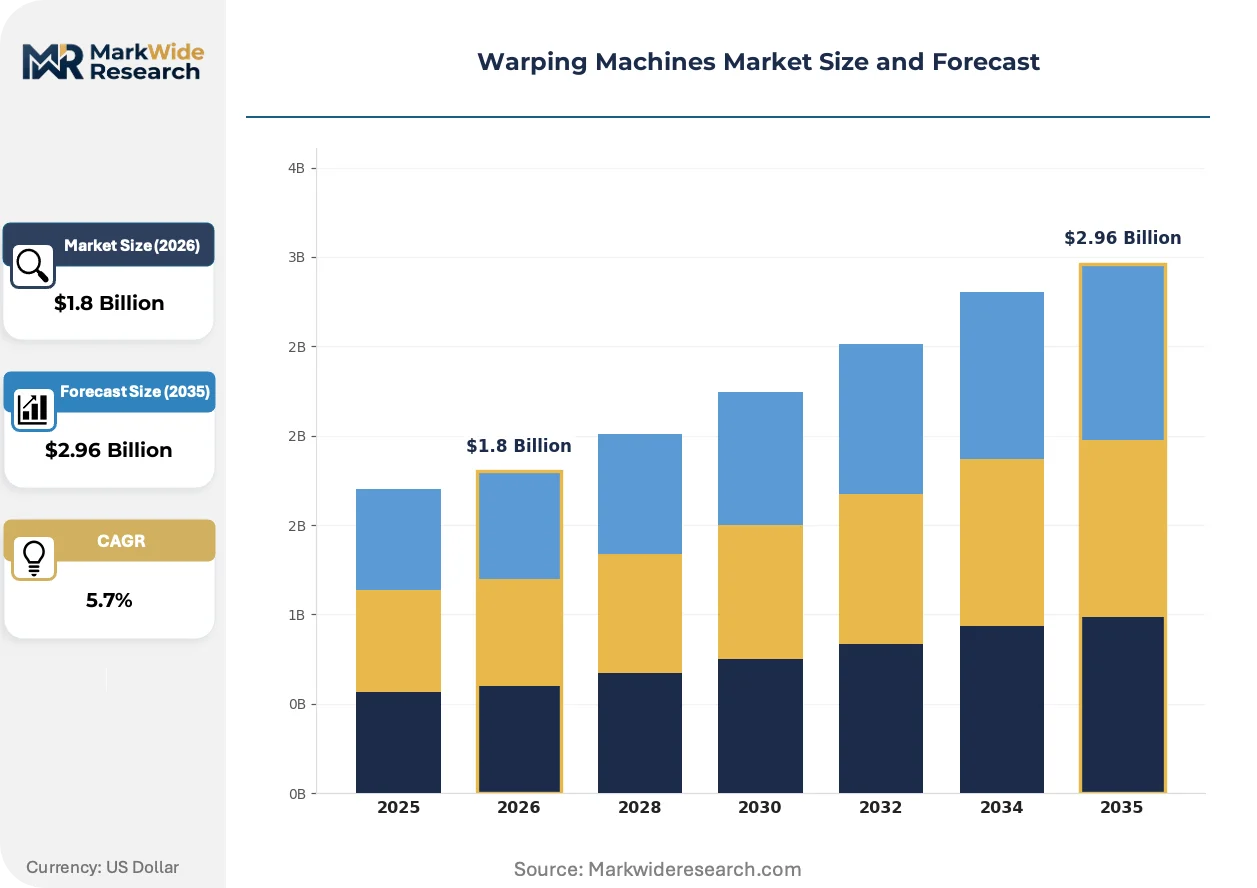
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Electronic, Semi-Automatic Application: Textile Manufacturing, Packaging, Composite Materials, Automotive Parts End User: Textile Mills, Printing Houses, OEMs, Home Furnishing Technology: Mechanical, Pneumatic, Hydraulic, Digital |
| Companies Covered | Karl Mayer Group, Tsudakoma Corp, Picanol Group, Itema Group, Staubli International AG, AIKI RIOTECH, MATTHYS GROUP, MÜLLER FRICK, Prashant Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warping Machines Market Evolving Landscape
Edge computing architectures are displacing centralized PLC systems in high-speed warping lines, enabling real-time tension correction without millisecond latency penalties from cloud connectivity dependencies.
Machine vision yarn defect detection is decentralizing quality control from downstream inspection stations onto the warping line itself. Automotive preform suppliers in Stuttgart and Munich are adopting inline camera arrays that flag broken filaments at 800 meters per minute. This compression of quality gates eliminates separate inspection beams and reduces work-in-process inventory by 25 percent.
REACH authorization requirements for chromium-based sizing agents are forcing European mills to validate waterborne alternatives through full production trials. The substitution cascade is most acute in Germany's technical textile corridor, where Karl Mayer and Liba equipment runs legacy recipes optimized for solvent adhesion. Beam coating uniformity degradation during the transition is driving demand for tension mapping systems that compensate for variable yarn-to-yarn friction coefficients.
Service contract unbundling is fragmenting the traditional bundled maintenance model. Turkish and Egyptian mills are purchasing core equipment without manufacturer service agreements, sourcing third-party technicians through regional textile engineering networks. This channel disintermediation is most visible in the Nile Delta, where independent rebuild shops now handle creel refurbishment and brake pad replacement for Tsudakoma and Benninger installations originally sold with 10-year service commitments.
Warping Machines Market Segmentation
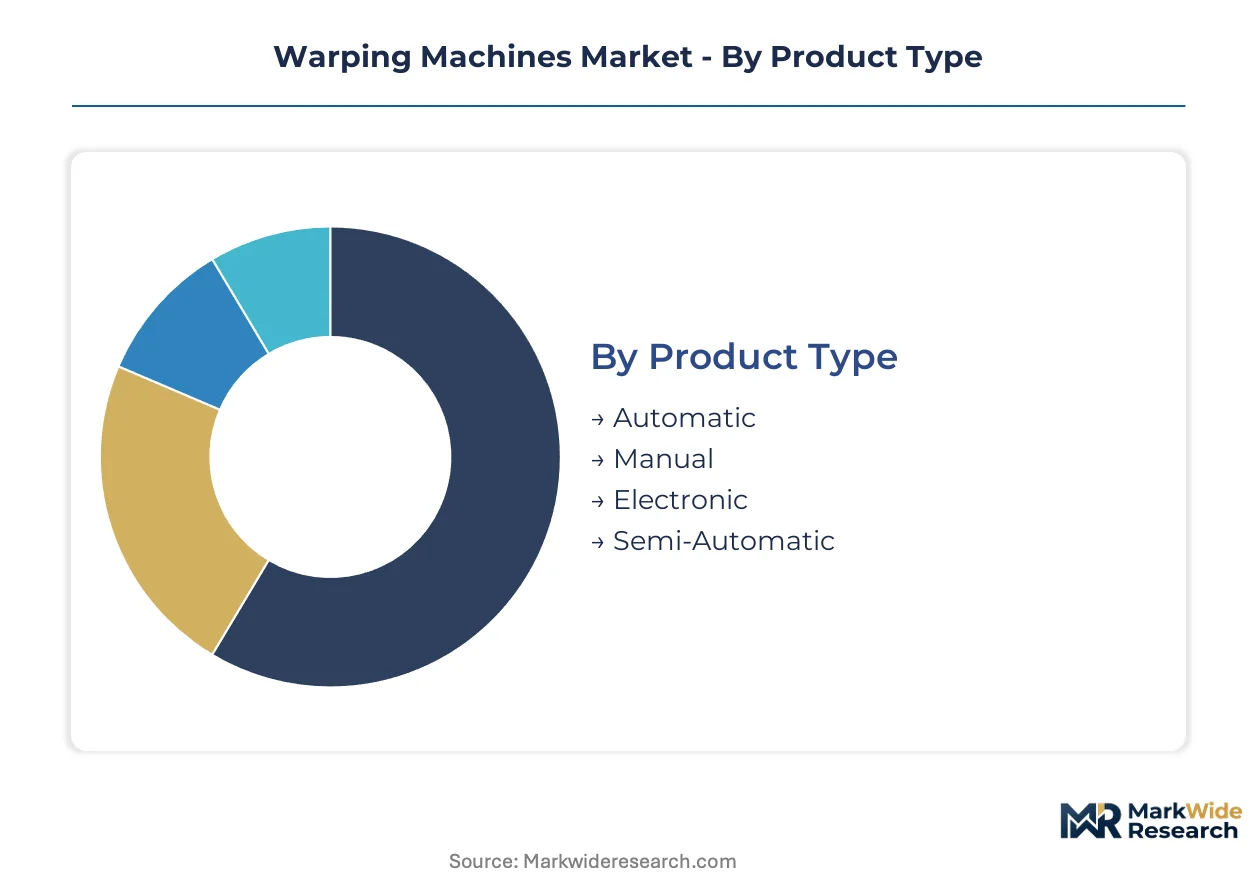
Segmentation in warping machinery reveals how certification burdens, application complexity, and technology maturity stratify capital deployment. Equipment buyers align product specifications with downstream quality mandates, creating distinct procurement channels that suppliers must navigate separately.
Product Type:
CE marking requirements from European machinery directives apply differentially across automation tiers, with automatic systems facing the most stringent electromagnetic compatibility and functional safety protocols.
- Automatic:Closed-loop tension control systems with servo-driven beam drives and programmable creel positioning dominate high-volume technical textile production. Demand concentrates in Germany's Chemnitz-Stuttgart corridor where automotive preform manufacturers require beam-to-beam consistency for carbon fiber processing. CE marking and ISO 9001 quality system integration add 12-18 percent to base equipment cost but unlock access to EU automotive tier-one supplier networks.
- Electronic:Microprocessor-controlled warping lines with digital tension profiling bridge the gap between mechanical reliability and precision automation. Mills in Surat and Coimbatore under India's PLI technical textile scheme favor this tier for retrofitting legacy mechanical assets without full automation capital outlay. BIS certification for imported textile equipment creates compliance friction that domestic assembly partnerships increasingly resolve.
- Manual:Hand-cranked beam drives with mechanical brake systems serve low-volume specialty yarn producers and artisan textile operations.
- Semi-Automatic:Partial automation of beam drive and creel functions offers intermediate throughput for mid-scale weaving mills.
Leading the category by volume: Automatic. Growing fastest: Electronic.
Application:
Cost tier stratification separates capital-intensive composite material lines from price-sensitive packaging equipment, with textile manufacturing occupying the middle ground where volume and precision requirements intersect.
- Composite Materials:Precision warping for carbon fiber preforms demands ceramic-coated guides, closed-loop load cell arrays, and microsecond tension refresh rates. Wind turbine blade manufacturing at TPI Composites and Vestas facilities in Mexico and Turkey pulls equipment orders into regional supply bases previously served by European OEMs. REACH-compliant waterborne sizing agent transitions in Europe require tension mapping systems that compensate for variable yarn friction coefficients.
- Automotive Parts:Automotive chassis and structural panel manufacturing integrates warping lines with downstream preform molding and resin transfer systems. Stuttgart and Munich suppliers adopt inline machine vision defect detection at 800 meters per minute, eliminating separate inspection beams and compressing quality gates. IATF 16949 automotive quality certification adds supplier qualification layers beyond standard machinery CE marking.
- Textile Manufacturing:Conventional weaving and knitting preparation spans apparel, home furnishings, and industrial fabric production.
- Packaging:Lower-precision warping for flexible packaging substrates and woven polypropylene sacks prioritizes throughput over tension control precision.
Composite Materials commands premium pricing. Automotive Parts expands most quickly.
End User:
Customer type determines service contract structure, with OEMs demanding predictive maintenance integration and textile mills increasingly unbundling manufacturer service agreements.
- Textile Mills:Integrated weaving and knitting operations from beam preparation through fabric finishing represent the core installed base. Turkish and Egyptian mills in the Nile Delta now source third-party technicians through regional engineering networks, fragmenting traditional 10-year manufacturer service commitments. This channel disintermediation pressures OEM margin pools from aftermarket services.
- OEMs:Original equipment manufacturers integrating warping lines into turnkey composite production systems require embedded IoT architectures and unified digital controls. Hyosung and Toray's carbon fiber weaving capacity near Ho Chi Minh City demands equipment with ASEAN-localized service infrastructure and Vietnamese-language HMI interfaces.
- Printing Houses:Narrow fabric and label warping for rotary screen and digital textile printing applications.
- Home Furnishing:Decorative fabric and upholstery yarn preparation with emphasis on color consistency and pattern repeat accuracy.
Textile Mills anchor installed base volume. OEMs drive technology upgrade cycles.
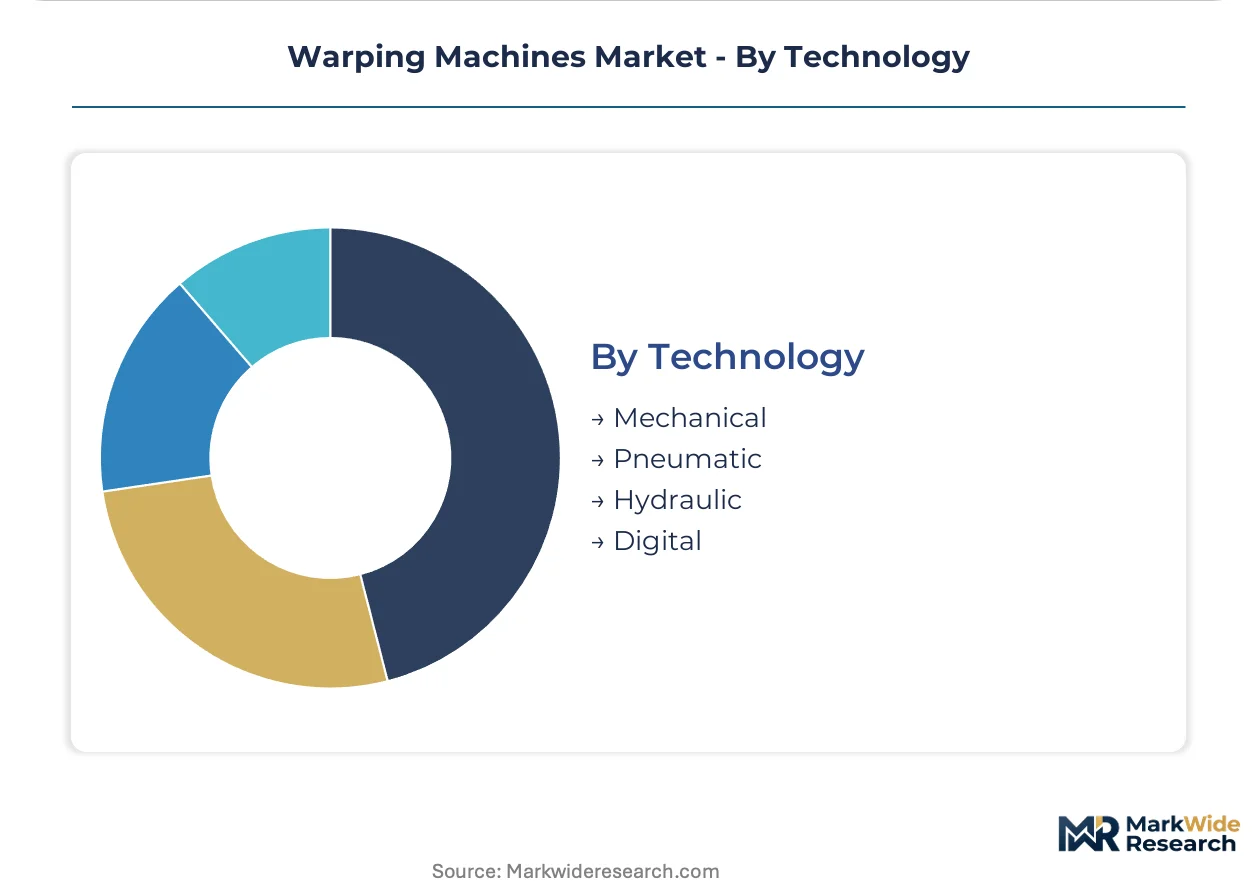
Technology:
Technology maturity curves separate legacy mechanical systems from digital architectures, with pneumatic and hydraulic actuation occupying transitional positions in equipment replacement cycles.
- Digital:Edge computing architectures with decentralized PLC systems enable real-time tension correction without cloud latency dependencies. EU Digital Product Passport regulations will require yarn origin documentation through beam production, opening retrofit markets for IoT-enabled systems with embedded RFID tagging. Direct-drive torque motor integration eliminates mechanical gearboxes and enables predictive vibration analysis extending maintenance intervals.
- Mechanical:Cam-driven beam drives and spring-loaded tension brakes constitute the legacy installed base. 1990s-vintage Dornier and Sulzer weaving lines lack digital beam identification protocols, forcing costly middleware development for unified mill-wide control architectures during digital retrofits.
- Pneumatic:Air-actuated brake and clutch systems offer intermediate reliability for mid-speed warping lines.
- Hydraulic:Oil-pressure beam drive systems persist in heavy-duty industrial fabric applications requiring sustained high torque.
Mechanical retains largest installed base. Digital climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Mexico are accelerating equipment relocation as automotive and wind energy suppliers establish carbon fiber preform capacity near end-use assembly plants.
Germany
Automotive chassis manufacturing at Porsche and BMW facilities drives precision warping demand for carbon fiber structural components. REACH authorization deadlines for chromium-based sizing agents force mills in Chemnitz and Stuttgart to validate waterborne alternatives through full production trials. The technical textile corridor between these cities concentrates Karl Mayer and Liba equipment installations serving tier-one supplier networks.
China
Wind turbine blade manufacturing expansion by domestic OEMs pulls preparatory machinery orders into regional supply bases. SAMR enforces 14-month type approval cycles for imported industrial machinery under GB standards, freezing non-Chinese suppliers out of rapid capacity expansions. Yangtze River Delta textile clusters around Shanghai retrofit mechanical warping assets with IoT-enabled tension monitoring modules.
India
The Ministry of Textiles PLI scheme subsidizes warp knitting capacity expansion in Surat and Coimbatore, concentrating preparatory machinery orders among domestic mills upgrading from manual sectional warping. BIS quality mandates for imported textile equipment create compliance friction that domestic assembly partnerships increasingly resolve. Technical textile investments in Tamil Nadu and Gujarat anchor demand for electronic-tier microprocessor-controlled systems.
United States
TPI Composites scales carbon fiber spar cap production for wind turbine blades, pulling precision warping capacity into regional supply bases previously served by European equipment. EPA regulations on volatile organic compound emissions from solvent-based sizing agents drive beam-to-beam consistency requirements. Automotive preform suppliers in the Southeast and Midwest adopt inline machine vision defect detection at 800 meters per minute.
Turkey
Vestas wind turbine blade manufacturing facilities in Izmir and Manisa generate demand for carbon fiber preform warping systems with REACH-compliant tension profiling. Turkish mills in the Aegean region increasingly unbundle manufacturer service agreements, sourcing third-party technicians through regional textile engineering networks. The Izmir technical textile corridor concentrates equipment installations serving European export markets.
Warping Machines Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier precision equipment consolidating around integrated textile machinery groups while mid-market electronic systems fragment across regional fabricators. The vendor base stratifies into three archetypes: warp knitting-integrated conglomerates with decades of technical textile lineage, precision electronics specialists with localized Asian service networks, and weaving ecosystem extenders leveraging unified digital controls. Dominant competitive moves include geographic expansion into Vietnam and Mexico special economic zones, plus portfolio diversification from mechanical into edge-computing architectures with embedded IoT modules.
Among Germany-based integrated textile machinery groups, Karl Mayer Group and MÜLLER FRICK occupy positions exemplifying the warp knitting heritage archetype, while Tsudakoma Corp anchors the precision electronics specialist tier with its Asian service infrastructure. Picanol Group represents the weaving ecosystem extender model, competing through backward integration into preparatory machinery with unified control architectures. These three company structures illustrate how competitive positioning stratifies across automation tiers and geographic service footprints.
| Leading Market Players |
|---|
| Karl Mayer Group |
| Tsudakoma Corp |
| Picanol Group |
| Itema Group |
| Staubli International AG |
| AIKI RIOTECH |
| MATTHYS GROUP |
| MÜLLER FRICK |
| Prashant Group |
| Others |
Value Network & Pricing Analysis
Family-owned German precision engineering specialists anchor premium-tier supply, enabling disciplined pricing through captive service networks and CE certification bundling that locks out unbundled competitors.
Pricing Analysis
Short lead-time premiums command substantial markups as Turkish and Egyptian mills unbundle manufacturer service agreements and scramble for third-party commissioning engineers. Three-tier pricing structure across premium automatic systems with full IoT integration, standard electronic tiers with digital tension profiling, and economy mechanical units for artisan producers stratifies procurement channels. Pricing pressure stems from recycled carbon fiber displacement in cost-sensitive automotive panels, eroding precision warping demand at the mid-tier. Textile mills in India's PLI scheme corridors exhibit highest price sensitivity, while OEMs integrating turnkey composite systems show lowest sensitivity due to IATF 16949 certification requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale carbon fiber preform demand from Vestas and TPI Composites, while regional distributor networks serve fragmented textile mill procurement across Surat and Coimbatore. Manufacturing concentrates in Germany's Chemnitz-Stuttgart technical textile corridor, Japan's precision electronics clusters, and China's Yangtze River Delta retrofit markets. Ceramic guide supply draws from Kyocera and CoorsTek alumina-zirconia output, servo motor arrays rest on Asian torque motor specialists, and closed-loop load cell components feed from European sensor manufacturers. Single-source vulnerability in ceramic guide supply creates structural risk for carbon fiber handling equipment. Distribution runs through manufacturer-direct service contracts for premium tiers and independent rebuild shops for unbundled maintenance in the Nile Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization deadlines for chromium-based sizing agents construct formidable compliance moats, freezing out equipment makers lacking validated waterborne alternative processing capabilities.
For Market Incumbents: Cement dominance in automotive preform segments by embedding machine vision defect detection at 800 meters per minute, eliminating inspection beam competition from downstream quality stations. Deepen backward integration into ceramic guide supply through partnerships with CoorsTek or Kyocera, neutralizing single-source vulnerability that threatens carbon fiber equipment margins. Lock in Turkish and Egyptian mills with predictive maintenance modules before independent rebuild shops capture aftermarket revenue pools. For New Entrants and Emerging Players: Begin with Vietnam's Ho Chi Minh City technical textile corridor where Hyosung and Toray are building carbon fiber weaving capacity ahead of EU-Vietnam FTA tariff advantages. Target electronic-tier microprocessor-controlled systems for Indian PLI scheme mills in Surat upgrading from manual sectional warping, as BIS certification friction favors domestic assembly partnerships. Lead with Vietnamese-language HMI interfaces and ASEAN-localized service infrastructure as the primary go-to-market wedge. For Investors and Strategic Acquirers: SAMR's 14-month GB standard certification timeline freezing non-Chinese suppliers is the leading indicator that regulatory compliance capabilities will separate viable acquisition targets from stranded assets over the mid-term horizon. Prioritize precision electronics specialists with established Asian service networks and existing SAMR approval pathways. Monitor unbundling of manufacturer service agreements in Turkey and Egypt as the signal that aftermarket revenue durability is deteriorating for premium-tier equipment portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Architecture Migration | Decentralized PLC systems eliminate cloud latency penalties for real-time tension correction at microsecond refresh rates. |
| Ceramic Guide Supply Partnership | Captive alumina-zirconia sourcing neutralizes Kyocera and CoorsTek single-source vulnerability for carbon fiber handling. |
| IoT-Enabled Retrofit Module Launch | EU Digital Product Passport regulations open beam-to-beam RFID tagging markets for legacy mechanical asset upgrades. |
| ASEAN Service Infrastructure Buildout | Vietnamese-language HMI interfaces capture first-mover positioning in Ho Chi Minh City carbon fiber weaving corridors. |
| Predictive Maintenance Contract Bundling | 40 percent maintenance interval extension through direct-drive torque motor vibration analysis locks in Turkish mill loyalty. |
Research Methodology
Multi-period observation of beam width capacity expansion, creel size configurations, and tension control refresh rate specifications anchored the trend analysis, supplemented by interviews with plant engineers at German automotive preform suppliers, maintenance directors at Turkish textile mills, OEM procurement teams at wind turbine blade manufacturers, and aftermarket service heads at regional rebuild shops. Secondary validation drew from customs and trade data for textile machinery imports, SEC filings of listed textile machinery groups, GB standard certification records from SAMR, and REACH authorization documentation from ECHA. Bottom-up equipment shipment tracking and top-down textile investment flow analysis were triangulated against carbon fiber demand forecasts.
Input-output matrices mapped automatic, electronic, manual, and semi-automatic system deployments against composite materials, automotive parts, textile manufacturing, and packaging applications across the projection horizon. Segmentation dimensions spanned automation tier, end-use industry, technology architecture, and regional production cluster. CAGRs were derived from installed base replacement cycles and greenfield capacity announcements. Industry-specific forecast inputs included carbon fiber modulus specifications for preform manufacturing and waterborne sizing agent transition timelines under REACH.
Underlying measurement precision varies by segment; automatic systems with documented CE marking and ISO 9001 integration carry tighter precision than fragmented manual equipment in artisan operations. Forecasts reflect assumptions regarding SAMR certification timeline stability, ceramic guide supply continuity, and recycled carbon fiber modulus consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Textile Winding Machine Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Global Spinning Machinery Market