
 Portable Fabric Canopies Market | 2026-2036
Portable Fabric Canopies Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Fabric Canopies Market Outlook
REACH compliance in Europe is broadening the cost-of-entry calculus for canopy manufacturers seeking to export polyester and PVC-based products. ShelterLogic Group leverages its vertical manufacturing footprint to sustain cost discipline across steel-frame production. International E-Z UP Inc. anchors its position through channel control in the North American event rental sector. ABCCANOPY competes aggressively on price while specializing in rapid-deployment pop-up formats for consumer segments.
Portable fabric canopies are engineered shelter structures comprising tensioned textile membranes—typically polyester denier ranging from 150D to 600D with polyurethane or PVC coatings—mounted on collapsible aluminum or steel frames, designed for temporary deployment at outdoor commercial, recreational, and emergency relief sites. The primary industrial purpose centers on delivering weather-resistant, rapidly deployable covered space without permanent foundation requirements. Pop-up canopies dominate volume due to their utility in trade shows and street fairs, while gazebos command margin pools through premium residential patio applications. Aluminum frame material leads commercial procurement for its weight-to-strength ratio, though steel persists in budget-tier and high-wind installations where structural rigidity outweighs portability concerns.
The US Consumer Product Safety Commission and EPA oversee chemical content and fire-safety labeling, while the EU's REACH and RoHS frameworks restrict hazardous substances in fabric coatings and frame alloys, effectively filtering non-compliant suppliers from transatlantic trade. China's GB standards and SAMR enforcement create a parallel compliance track for manufacturers serving domestic and export markets. Stakeholders must monitor evolving flammability test protocols and frame-load certification requirements as procurement specifications tighten across institutional buyers.
Market Dynamics
Flame-retardant certification mandates from NFPA 701 and CPAI-84 are restructuring procurement specifications across municipal and institutional buyers, forcing manufacturers to absorb testing costs or exit commercial channels entirely. This regulatory compression is filtering supplier bases faster than demand expansion can absorb displaced capacity.
Growth Catalysts
- Municipal park infrastructure:United States cities are accelerating canopy replacement cycles through dedicated outdoor recreation budgets, creating predictable demand pools for commercial-grade aluminum-frame products.
- REACH compliance:European chemical restrictions on polyester and PVC coatings are raising barriers for low-cost Asian exporters, protecting margin positions for certified regional manufacturers.
- Live entertainment rebound:Outdoor event management companies are expanding fleet inventories to service restored festival calendars and street fair circuits.
Market Restraints
- Steel price volatility:Raw material input swings for frame alloys compress margin predictability for budget-tier producers dependent on cost-plus pricing.
- Supplier concentration:Fabric coating capacity clusters in China's Zhejiang and Guangdong provinces, exposing buyers to single-geography disruption risks.
- Permanent structure substitution:Modular hard-shell pavilions are capturing long-term installation contracts that previously defaulted to fabric alternatives.
Strategic Opportunities
- Emergency relief applications:FEMA and international humanitarian agencies are formalizing rapid-deployment canopy stockpiling protocols for disaster response.
- Consumer direct channels:Amazon and specialty outdoor retailers are disintermediating traditional distributor networks for pop-up formats.
- EU Green Deal alignment:Recycled polyester content requirements are creating first-mover advantages for manufacturers with verified circular supply chains.
Industry Challenges
- NFPA 701 testing backlog:Third-party certification queues are extending lead times for new product introductions, freezing inventory planning cycles.
- Frame-load engineering talent:Structural analysis capabilities for wind-rating validations are concentrated among aging specialist consultants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Fabric Canopies Market |
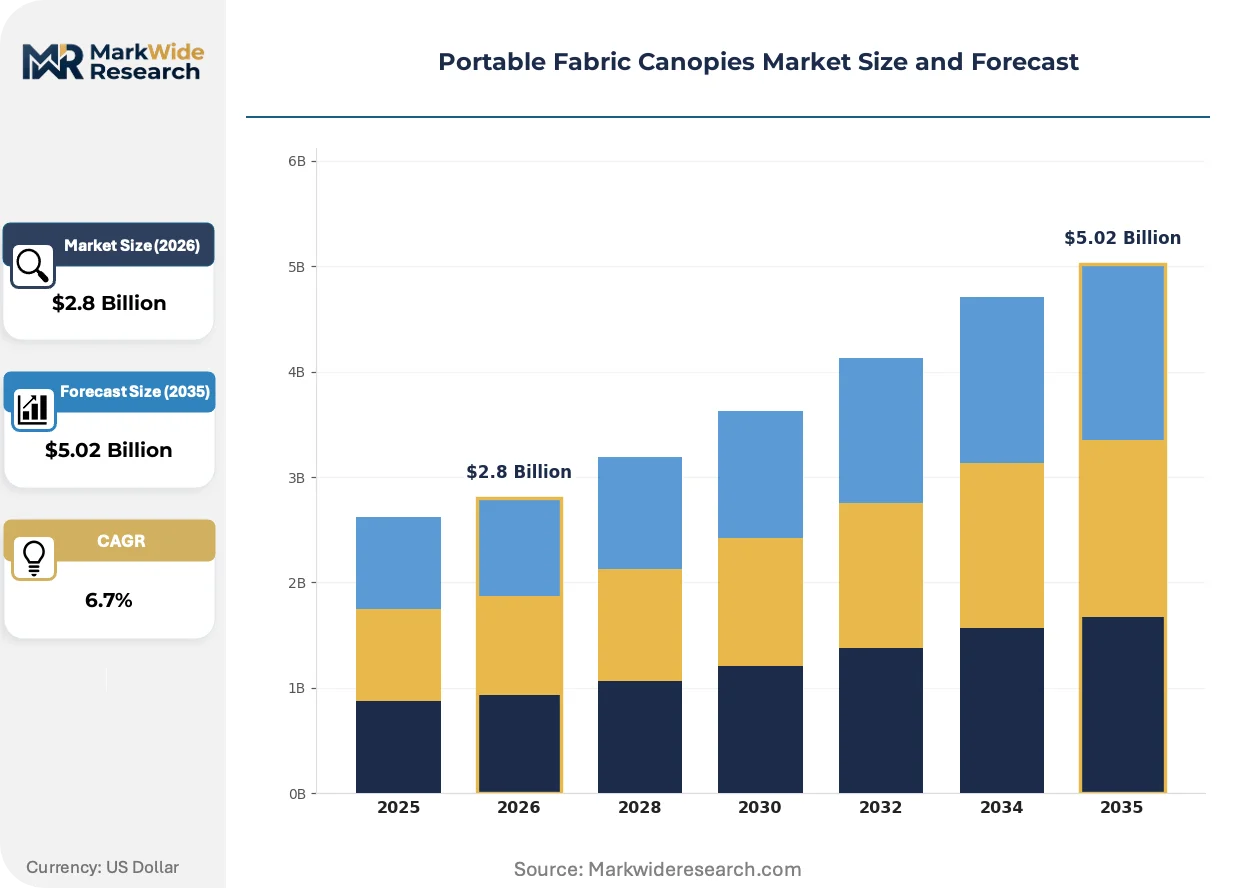
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pop-Up Canopies, Beach Canopies, Gazebos, Patio Canopies Usage: Outdoor Events, Camping, Trade Shows, Sports Frame Material: Aluminum, Steel, Fiberglass, Wood Fabric Type: Polyester, Canvas, PVC, Nylon |
| Companies Covered | ShelterLogic Group, International E-Z UP Inc., Eide Industries Inc., ABCCANOPY, KD Kanopy Inc., Eurmax Canopy Inc., Caravan Canopy, Coleman Company Inc., PIC America Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Fabric Canopies Market Strategic Shifts
Material science advances and certification protocol digitization are compressing product development cycles while fragmenting buyer segments into specification-sensitive niches. These shifts reward agile manufacturers with modular testing capabilities.
Modular tension-membrane systems with tool-free assembly are decentralizing deployment authority from specialized installation crews to end-users. Festival operators and municipal maintenance staff now configure complex multi-bay layouts without contractor involvement. This capability transfer is collapsing service revenue streams for traditional rental intermediaries.
ECHA's SCIP database requirements under REACH are forcing full material disclosure for fabric coatings and frame alloys entering European commerce. Manufacturers must now document substance-of-concern content across entire supply chains. Polyester-PVC laminate suppliers are responding by reformulating adhesive layers to eliminate SVHC-classified plasticizers.
Rental-to-purchase conversion is accelerating among small-event organizers who previously relied on third-party canopy services. These buyers now favor consumer-grade pop-up formats with rapid-deployment features over commercial rental contracts. The pattern is most visible in United States regional fair circuits where per-event economics favor ownership amortization.
Portable Fabric Canopies Market Segmentation
Portable fabric canopy buyers fragment sharply across deployment scenarios, frame durability requirements, and fabric performance specifications. Segmentation discipline separates volume-driven consumer purchases from margin-rich institutional contracts.
Product Type:
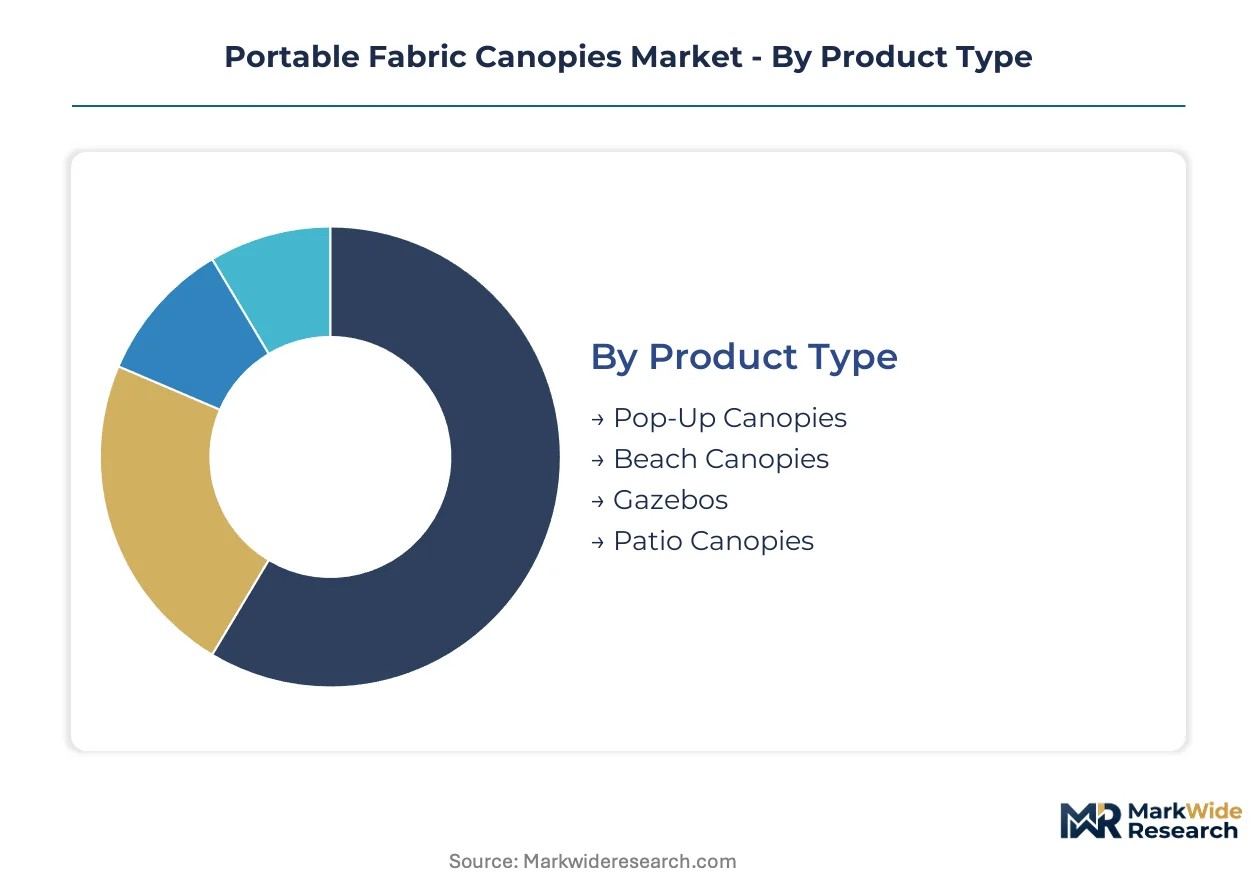
Supply concentration tilts heavily toward pop-up formats, where manufacturing scale and component standardization create defensive moats for incumbent producers.
- Pop-Up Canopies:Collapsible aluminum or steel frames with 150D-600D polyester canopies deploy without tools in under three minutes. Demand clusters with United States event rental companies and municipal park departments seeking rapid turnaround between deployments. NFPA 701 certification requirements are filtering uncertified imports from commercial channels.
- Gazebos:Permanent-installation tension structures with reinforced corner posts and vented double-tier roofs command premium residential patio segments. Margin pools concentrate in suburban United States markets where outdoor living space investments accelerated post-pandemic.
- Beach Canopies:Lightweight fiberglass-pole shelters with sand-anchor systems target coastal recreation consumers.
- Patio Canopies:Semi-permanent shade structures with steel or aluminum frames anchor residential deck and poolside applications.
Today's leader: Pop-Up Canopies. Tomorrow's challenger: Gazebos.
Usage:
Application-based purchasing patterns split between recurring-rental fleet operators and one-time ownership models, with divergent price sensitivity and specification rigor.
- Outdoor Events:Festival infrastructure, street fairs, and municipal gatherings drive commercial-grade aluminum-frame procurement with flame-retardant fabric mandates. United States cities including Austin, Nashville, and Denver are accelerating replacement cycles through dedicated outdoor recreation budgets.
- Trade Shows:Exhibitor-owned pop-up formats with custom graphic printing and rapid-deployment features displace traditional rental intermediaries. Small-event organizers favor ownership amortization over per-event rental economics.
- Camping:Recreational consumers prioritize pack weight and weather resistance over frame longevity.
- Sports:Sideline shelters and team bench covers target youth leagues and school athletic departments.
Outdoor Events anchor current volume. Trade Shows are expanding most quickly as ownership models displace rental dependency.
Frame Material:
Cost-tier stratification separates commercial buyers seeking weight-to-strength optimization from budget-conscious consumers tolerating corrosion trade-offs.
- Aluminum:6061-T6 and 6005-T5 alloys deliver superior weight-to-strength ratios for commercial deployment cycles. United States institutional buyers specify aluminum for municipal park installations where portability and corrosion resistance justify 40-60% price premiums over steel alternatives.
- Steel:Powder-coated carbon steel persists in budget-tier consumer segments and high-wind installations where structural rigidity outweighs weight penalties. Raw material price volatility compresses margin predictability for producers dependent on cost-plus pricing.
- Fiberglass:Flexible pole systems dominate beach and camping shelters where packed size constraints override frame longevity.
- Wood:Aesthetic-driven residential gazebos and permanent patio structures occupy niche premium positioning.
Aluminum commands commercial specification. Steel retains mass-market volume.
Fabric Type:
Material chemistry and coating technology determine weather resistance, fire safety compliance, and circular economy positioning across buyer segments.
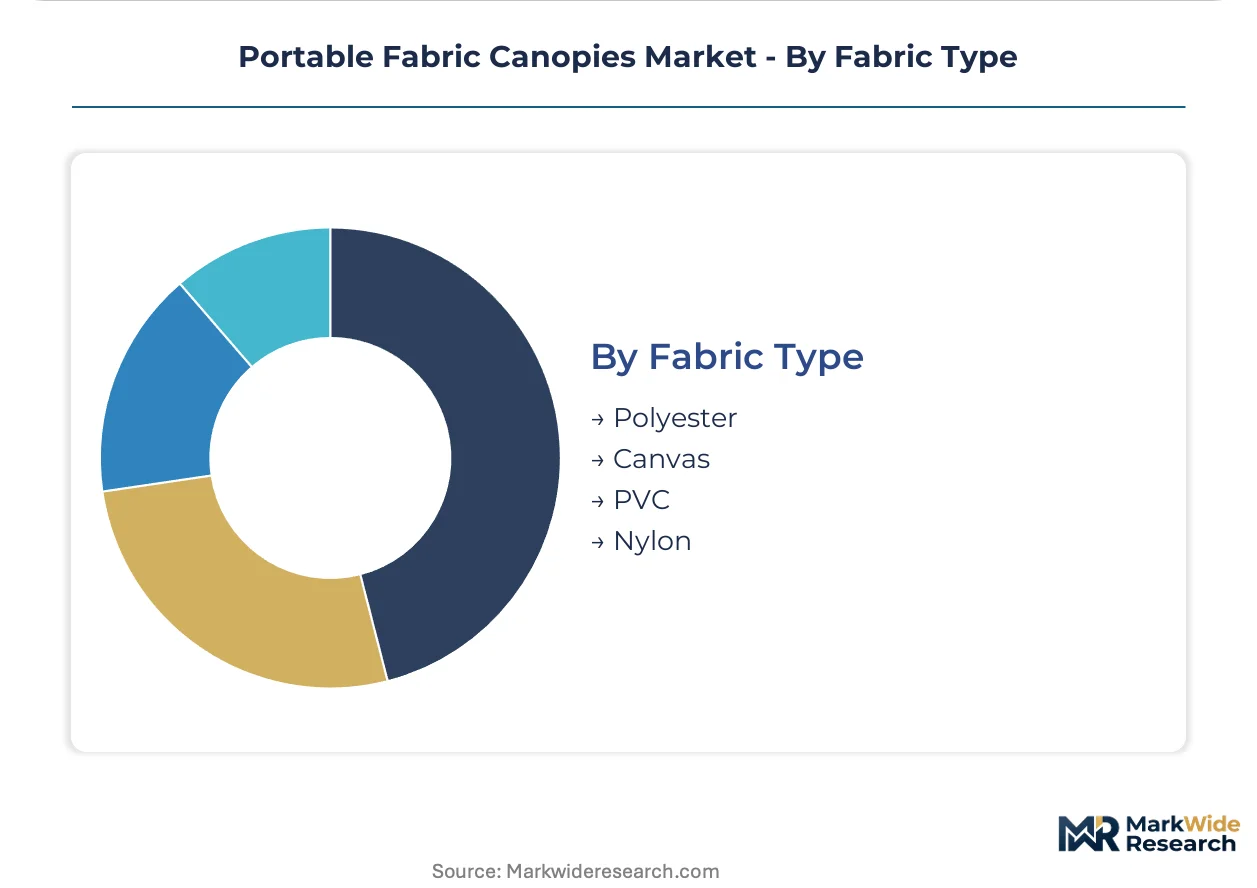
- Polyester:150D to 600D denier with polyurethane or PVC coatings dominates volume production due to cost efficiency and print compatibility. REACH compliance requirements under ECHA's SCIP database are forcing reformulation of adhesive layers to eliminate SVHC-classified plasticizers, raising barriers for uncertified Asian exporters.
- PVC:Heavy-duty laminated membranes command industrial and emergency relief applications where waterproofing and durability specifications are non-negotiable.
- Canvas:Cotton-polyester blends retain heritage aesthetic positioning in residential gazebo segments.
- Nylon:Ripstop weaves with silicone coatings target ultralight camping and backpacking shelters.
Polyester holds manufacturing scale. PVC maintains specification-critical niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent for frame-load analysis concentrates in aging specialist consultancies across industrial corridors, creating capability scarcity that shapes regional competitive positioning.
United States
Municipal park departments in Austin, Nashville, and Denver accelerate canopy replacement cycles through dedicated outdoor recreation budgets. The US Consumer Product Safety Commission enforces fire-safety labeling requirements that filter non-compliant imports. Fabric coating suppliers cluster in North Carolina's textile corridor, where flame-retardant certification testing facilities maintain NFPA 701 validation queues.
Germany
Commercial event infrastructure operators prioritize REACH-compliant polyester-PVC laminates for festival and trade show deployments. ECHA's SCIP database mandates full material disclosure for frame alloys and fabric coatings entering European commerce. Manufacturing engineering for tension-membrane systems concentrates in Baden-Württemberg, where automotive supplier networks provide precision metalworking capabilities.
China
Export-oriented fabricators in Zhejiang and Guangdong provinces face rising barriers from European chemical restrictions on plasticizer content. SAMR enforcement of GB standards creates parallel compliance tracks for domestic and export markets. Production gravity for polyester denier weaving and polyurethane coating sits in Shaoxing's chemical fiber industrial zone, where capacity expansion responds to displaced low-cost competitors.
United Kingdom
Outdoor hospitality operators drive specification-grade gazebo procurement for premium residential patio segments. RoHS frameworks restrict hazardous substances in collapsible frame alloys, affecting import sourcing decisions. Distribution logistics for pop-up formats concentrate in Midlands warehousing corridors serving Amazon and specialty outdoor retail channels.
Japan
Recreational consumers demand ultralight camping shelters with silicone-coated ripstop nylon specifications. METI oversees industrial standards for temporary structure wind-rating validations. Precision manufacturing for fiberglass pole systems clusters in Osaka's sporting goods supplier networks, where material science expertise supports modular tension-membrane development.
Portable Fabric Canopies Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered price and certification segments. Market structure tilts toward consolidation among vertically integrated frame-and-fabric producers capable of absorbing regulatory testing costs, while fragmented import assemblers retreat from commercial channels. Two strategic archetypes dominate: certified full-stack manufacturers controlling steel-frame production and coating formulation, and rapid-deployment specialists optimizing tool-free assembly for consumer direct channels. Competitive moves center on backward integration into aluminum alloy sourcing and geographic expansion through Amazon marketplace presence.
Within the certified manufacturer tier, ShelterLogic Group and International E-Z UP Inc. exemplify full-stack positioning with captive production capabilities. ABCCANOPY occupies a specialist position focused on rapid-deployment pop-up formats. These three entities represent divergent responses to NFPA 701 certification mandates: integrated testing infrastructure versus speed-to-market consumer segmentation.
| Leading Market Players |
|---|
| ShelterLogic Group |
| International E-Z UP Inc. |
| Eide Industries Inc. |
| ABCCANOPY |
| KD Kanopy Inc. |
| Eurmax Canopy Inc. |
| Caravan Canopy |
| Coleman Company Inc. |
| PIC America Ltd. |
| Others |
Value Chain & Pricing Dynamics
Frame-load engineering talent clustering in aging specialist consultancies across industrial corridors creates labor-cost differentials that widen pricing-tier spreads between certified commercial-grade and budget consumer segments. Manufacturers absorbing NFPA 701 testing costs in the United States command 40-60% premiums over steel-frame imports, while uncertified Asian assemblers compete on stripped-down pop-up formats for price-sensitive ownership models.
Pricing Analysis
Bundled installation services versus unbundled product-only sales split the market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels separates certified aluminum-frame systems with full after-sales support from stripped consumer formats. Price differentiation hinges on flame-retardant certification grade and geographic delivery cost to municipal buyers. Pricing pressure stems from steel price volatility compressing margin predictability for budget-tier producers. Small-event organizers exhibit highest price sensitivity, while institutional procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Container freight rate fluctuations from Zhejiang and Guangdong provinces to North American ports directly impact landed cost structures for polyester-coated fabric inputs. Supply draws from China for denier weaving and polyurethane coating, the United States for aluminum alloy extrusion, and Germany for precision tension-membrane engineering. Raw material dependencies center on 6061-T6 aluminum billet, PVC laminate adhesives, and powder-coated carbon steel. Single-geography concentration in Shaoxing's chemical fiber zone exposes buyers to disruption risks from SAMR enforcement actions. Distribution runs through Amazon marketplace channels and specialty outdoor retail networks for consumer formats, with direct municipal contracting dominating institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable fabric canopy manufacturing operates as a geographic-arbitrage play where REACH compliance costs in Europe and NFPA 701 testing queues in North America create protected margin pools for regional certified producers against low-cost Asian exporters.
For Market Incumbents: Deploy captive certification infrastructure to lock in municipal procurement channels. ShelterLogic Group and International E-Z UP Inc. anchor positions through backward integration into steel-frame production and coating formulation, absorbing regulatory testing costs that filter fragmented import assemblers. Channel control in the North American event rental sector defends against Amazon marketplace disintermediation threatening traditional distributor networks. For New Entrants and Emerging Players: Capture emergency relief stockpiling protocols formalizing at FEMA and international humanitarian agencies. The EU Green Deal's recycled polyester content requirements create first-mover white space for manufacturers with verified circular supply chains. Consumer direct channels through Amazon and specialty outdoor retailers offer the most penetrable go-to-market angle for rapid-deployment pop-up formats displacing rental dependency. For Investors and Strategic Acquirers: Outdoor event management companies are the most active acquirer in this space, consolidating fleet operators to service restored festival calendars. Long-term viability over a multi-year horizon favors vertically integrated frame-and-fabric producers capable of absorbing regulatory testing cost inflation. Watch for NFPA 701 testing backlog resolution as the inflection signal releasing frozen inventory planning cycles and accelerating new product introductions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Alloy Sourcing | Captive supply of 6061-T6 extrusion secures weight-to-strength specifications for municipal park installations. |
| REACH-Compliant Coating Reformulation | ECHA's SCIP database mandates eliminate SVHC-classified plasticizers, filtering uncertified competitors from European commerce. |
| Amazon Marketplace Presence Expansion | Direct-to-consumer channels disintermediate traditional distributor networks for rapid-deployment pop-up formats. |
| Emergency Relief Stockpile Certification | FEMA formalization of rapid-deployment protocols creates predictable demand pools for specification-grade inventory. |
| Modular Tension-Membrane Tool-Free Assembly | Capability transfer from specialized crews to end-users collapses service revenue streams for rental intermediaries. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal procurement officers, event rental fleet managers, fabric coating R&D directors, and tension-membrane engineering consultants with secondary validation. Customs records from USITC and Eurostat captured trade flow patterns for polyester-PVC laminates and aluminum frame components. SEC filings of diversified conglomerates, NFPA certification registries, and ECHA's SCIP database disclosures anchored supply-side assessment. Bottom-up unit economics for pop-up canopy production triangulated against top-down market size estimates from outdoor recreation budget allocations.
Historical reference periods spanning pre-pandemic festival infrastructure investment, live entertainment shutdown, and rebound recovery anchored the projection horizon. The analytical framework modeled segmentation across product type, frame material alloy specification, fabric denier and coating chemistry, and end-use deployment scenario. CAGRs derived from municipal replacement cycle acceleration, REACH compliance barrier effects, and rental-to-purchase conversion patterns among small-event organizers. Wind-rating validation protocols and flame-retardant certification queue lengths served as industry-specific forecast inputs.
Steel price volatility, third-party certification backlog extension, and permanent structure substitution by modular hard-shell pavilions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around live entertainment calendar stability and municipal outdoor recreation budget continuity. A model refresh is warranted upon material change in NFPA 701 testing capacity or ECHA SVHC classification updates for plasticizer content.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Compact Spinning Machine Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Saddle Stitching Machine Market