
 Europe Fabric Shavers Market | 2026-2036
Europe Fabric Shavers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fabric Shavers Market Insights
Premium-tier motor specifications and blade precision standards is unwinding across the European market, lifting average unit economics for manufacturers. Philips N.V. leverages its Benelux R&D infrastructure to sustain patent density in rotary blade systems. Steamery anchors the Nordic premium segment through design-forward positioning and direct-to-consumer channel control. Rowenta competes on manufacturing scale from its French production base, supplying major hypermarket chains across Western Europe.
A fabric shaver is a handheld electromechanical or manual device employing rotary or linear blade arrays typically operating at 3,000–8,000 RPM to sever protruding fiber pills from woven and knitted textile surfaces, restoring garment appearance and extending usable life. Electric models integrate rechargeable lithium-ion cells or AC motors with protective mesh guards to prevent fabric damage during operation. Battery-operated units lead volume sales among households seeking cordless convenience, while premium corded variants dominate repair shop and textile manufacturer procurement where continuous runtime matters. The mid-range price tier captures the fastest-growing margin pool as retailers shift shelf space toward feature-rich models with adjustable shave heights and detachable lint chambers.
CE marking requirements under the EU Low Voltage Directive and Ecodesign framework govern motor efficiency thresholds and electrical safety for corded and rechargeable fabric shavers sold across member states. REACH restrictions on substance concentrations in plastic housings and blade coatings shape material selection decisions for manufacturers serving the European Economic Area. ECHA substance evaluations and national market surveillance authorities in Germany and France enforce compliance through port-of-entry inspections and retail channel audits. Stakeholders must monitor upcoming EU battery regulation amendments affecting replaceable cell designs and end-of-life collection obligations.
Market Dynamics
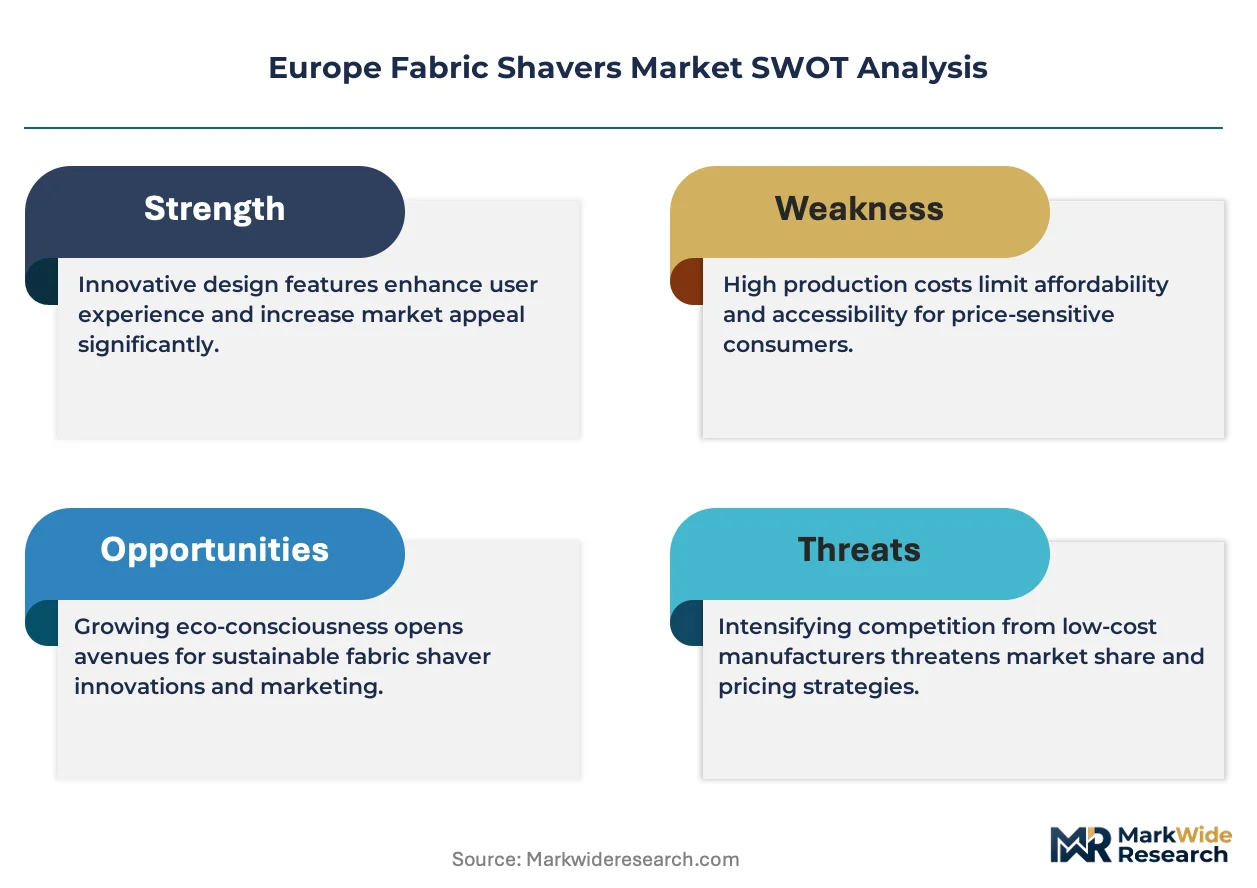
REACH substance restrictions and the EU Ecodesign Directive are compressing material choices for European fabric shaver manufacturers while elevating compliance costs across the value chain.
Growth Catalysts
- REACH compliance deadlines:Manufacturers accelerating reformulation of blade coatings and plastic housings ahead of ECHA evaluation windows, creating first-mover advantage for certified suppliers.
- Garment repair shops:Professional textile service providers in France and Germany upgrading to corded premium units as clothing alteration demand rises.
- Lithium-ion cell energy density:Improved battery chemistry enabling cordless runtime extension without weight penalties, unlocking replacement cycles among German households.
Market Restraints
- Copper motor winding costs:Commodity price volatility in electrical steel and copper concentrates squeezing margin on mid-tier electric models.
- Single-source mesh guard suppliers:Precision stamping capacity for stainless steel protective screens concentrates among three German tool-and-die specialists.
- Manual tool substitution:Low-cost lint rollers and sweater combs retaining price-sensitive household segments in Southern Europe.
Strategic Opportunities
- Polish and Romanian retail expansion:Underpenetrated hypermarket channels in Eastern Europe offering shelf space for feature-rich cordless units.
- EU battery regulation amendments:Replaceable cell mandates creating aftermarket revenue streams through authorized service networks.
- Direct-to-consumer subscription:Blade replacement programs bypassing traditional distributor markups in Nordic markets.
Industry Challenges
- CE marking timeline compression:Notified body backlogs for Low Voltage Directive testing extending product launch windows by four to six months.
- Cross-border waste collection:End-of-life lithium-ion recovery obligations under national transpositions complicating reverse logistics design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fabric Shavers Market |
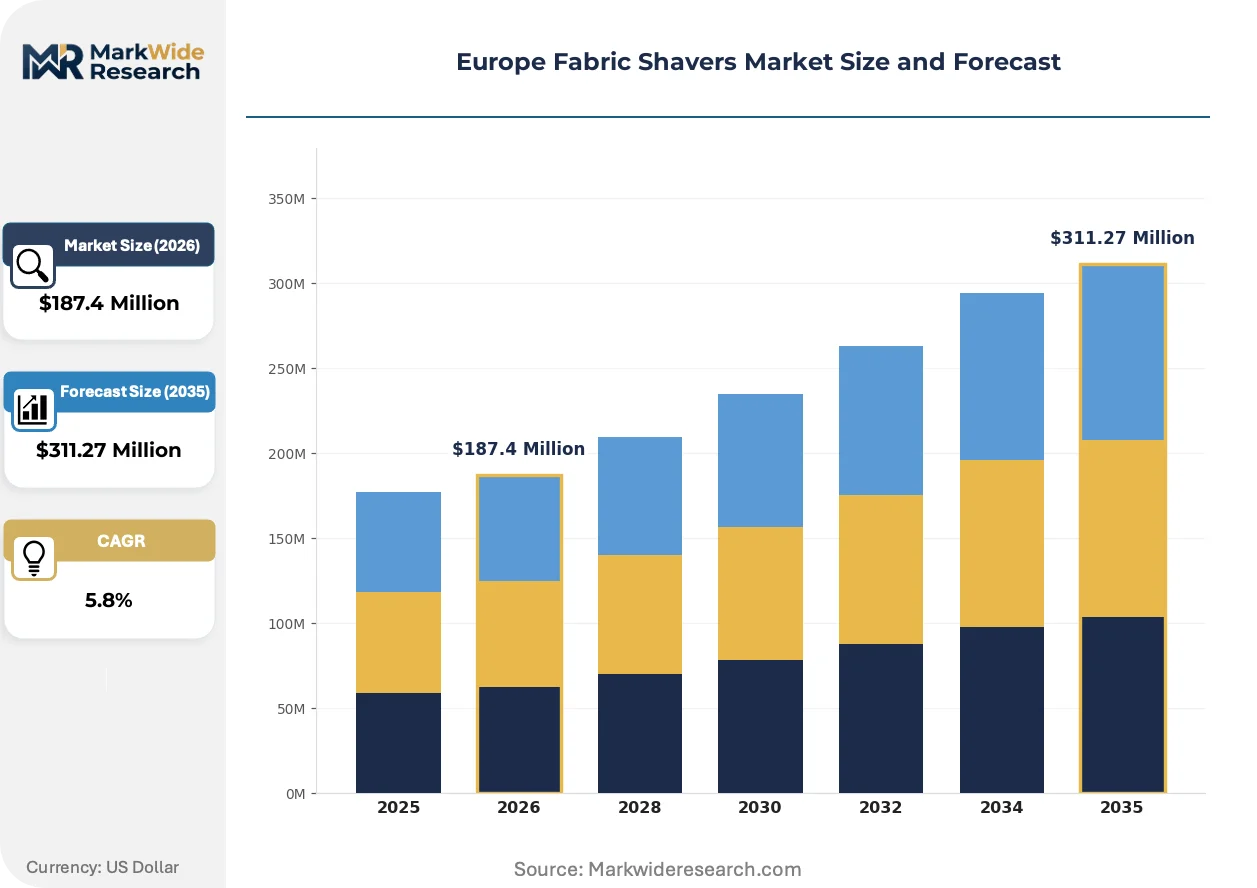
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Battery-Operated, Corded End User: Households, Retailers, Textile Manufacturers, Repair Shops Distribution Channel: Online Stores, Specialty Stores, Hypermarkets, Wholesalers Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Philips N.V., Conair Corporation, Remington Products Company, Steamery, Gleener, Xiaomi Corporation, Electrolux AB, BSH Hausgeräte GmbH, Rowenta, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fabric Shavers Market Trends and Innovations
Brushless DC motor architectures and smart battery management systems are redefining performance benchmarks across European fabric shaver portfolios. Manufacturers compete on runtime-to-weight ratios while navigating tightening substance restrictions.
Brushless DC motor technology replaces brushed commutator designs in premium cordless fabric shavers, eliminating carbon brush wear and enabling precision RPM control through electronic commutation. German household buyers and professional alteration services adopt these units despite twenty to thirty percent price premiums. The technology is miniaturizing motor housings while sustaining torque output, allowing ergonomic handle redesigns that expand addressable user demographics.
EU Ecodesign framework motor efficiency thresholds now mandate minimum performance coefficients for rechargeable appliances above seventy-five watts, effective across all member states. Manufacturers redesign winding configurations and magnetic circuits to meet standby power limits. Corded professional units face the strictest compliance burdens, pushing French and Italian producers toward modular motor platforms that scale across wattage classes.
Certification-driven purchasing now governs procurement decisions among institutional buyers in Scandinavian public sector textile services. Buyers require documented REACH compliance and CE marking traceability before contract award, displacing informal supplier relationships. This pattern concentrates demand among established brands with dedicated regulatory affairs functions, visible in Swedish municipal tender specifications.
Europe Fabric Shavers Market Segmentation
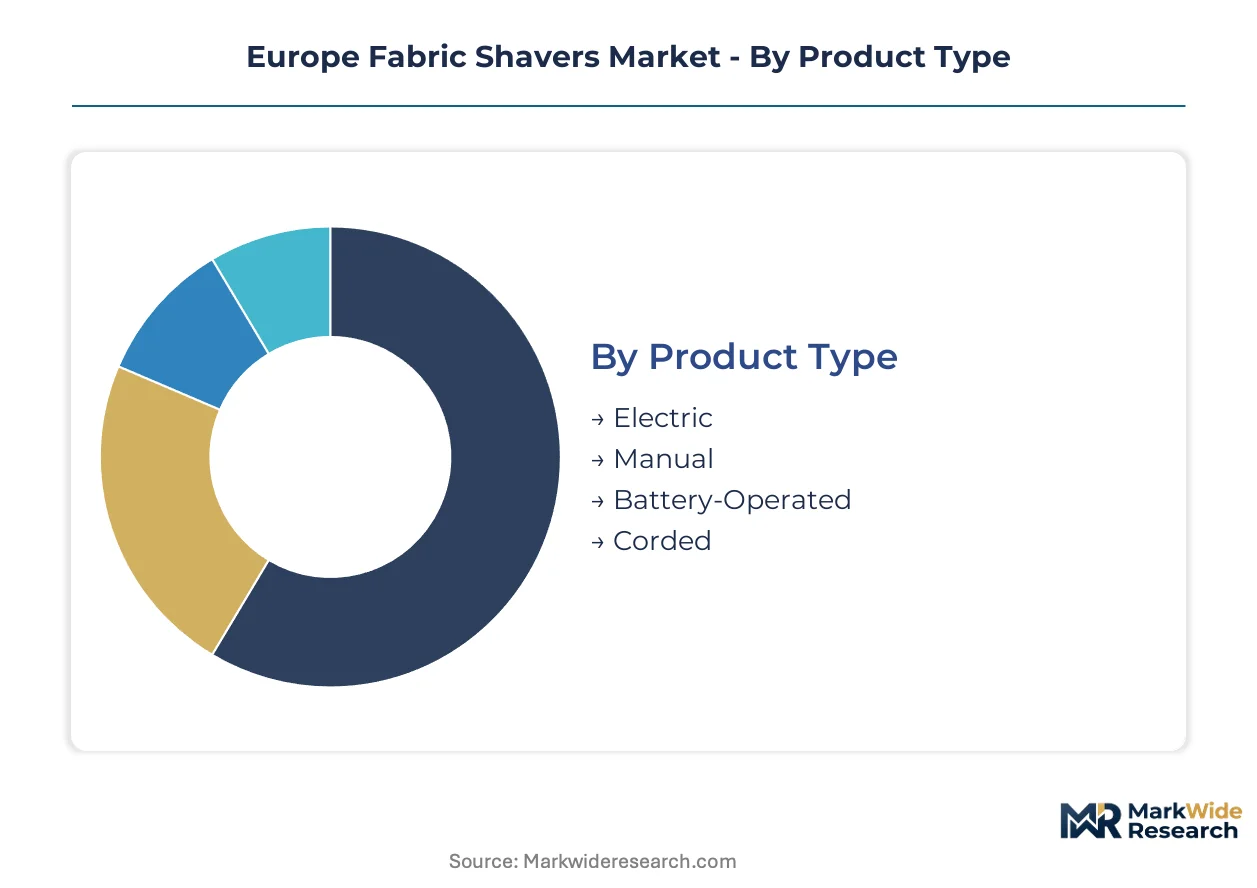
Segmentation in the Europe Fabric Shavers Market reveals how regulatory pressure and channel evolution fragment demand across distinct margin architectures. Manufacturers must align motor specifications, certification depth, and distribution investment to the precise requirements of each slice.
Product Type:
Margin pools concentrate in cordless electric architectures where lithium-ion cell integration and brushless DC motor miniaturization command price premiums.
- Electric:Brushless DC motor architectures with electronic commutation eliminate carbon brush wear and enable precision RPM control. German household buyers and French alteration services absorb twenty to thirty percent price premiums for these specifications.
- Battery-Operated:Rechargeable lithium-ion cells with improved energy density extend runtime without weight penalties, unlocking replacement cycles among German households seeking cordless convenience.
- Manual:Low-cost mechanical designs retain price-sensitive segments in Southern Europe where garment care budgets compress.
- Corded:Continuous runtime specifications serve professional textile service providers in France and Germany with elevated duty-cycle requirements.
The dominant share belongs to Battery-Operated, while Electric is closing the gap fastest.
End User:
Procurement sophistication varies sharply across this dimension, with institutional buyers demanding REACH traceability and CE marking documentation that household purchasers ignore.
- Households:German, French, and British buyers prioritize garment longevity and sustainable fashion alignment, driving replacement purchases toward feature-rich cordless units with adjustable shave heights.
- Repair Shops:Professional alteration services in France and Germany upgrade to corded premium units as clothing repair demand rises, requiring continuous runtime and mesh guard durability.
- Textile Manufacturers:Industrial procurement emphasizes motor efficiency compliance under EU Ecodesign Directive thresholds above seventy-five watts.
- Retailers:Hypermarket chains across Western Europe source mid-tier models with detachable lint chambers for shelf space optimization.
Households anchor volume demand, yet Repair Shops deliver the steepest margin expansion trajectory.
Distribution Channel:
Channel control determines pricing power, with direct-to-consumer platforms capturing margin that traditional wholesale structures surrender to distributor markups.
- Online Stores:Nordic premium brands leverage direct-to-consumer subscription models for blade replacement programs, bypassing traditional distributor economics.
- Hypermarkets:Major chains across Western Europe shift shelf space toward feature-rich mid-range cordless units, concentrating volume in Germany and France.
- Specialty Stores:Curated retail environments in urban centers showcase design-forward positioning and ergonomic handle innovations.
- Wholesalers:Eastern European penetration depends on Polish and Romanian retail expansion through established distribution networks.
Hypermarkets retain the largest volume position, though Online Stores are gaining share fastest.
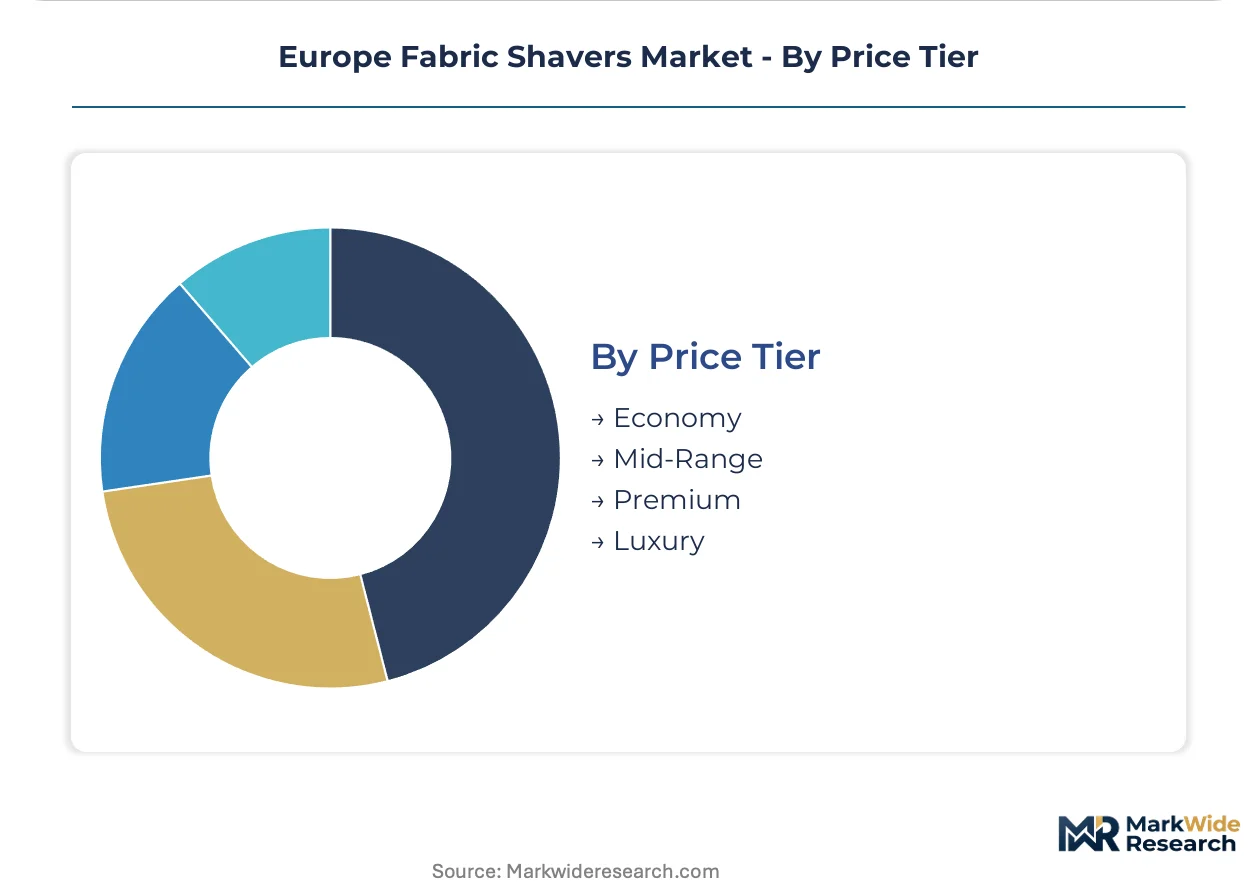
Price Tier:
Certification depth and material compliance costs stratify pricing, with REACH-compliant coatings and recyclable housings compressing economy-tier viability.
- Mid-Range:Feature-rich models with adjustable shave heights and detachable lint chambers capture the fastest-climbing margin pool as retailers reallocate shelf space.
- Premium:Brushless DC motor specifications and precision blade arrays serve German household buyers and professional services with documented runtime-to-weight performance.
- Economy:Basic motor configurations face margin compression from copper winding cost volatility and REACH reformulation expenses.
- Luxury:Design-forward positioning with extended warranties and subscription blade programs anchors Nordic market penetration.
Mid-Range commands the dominant revenue position, while Premium is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's fabric shavers trade flows show Germany and France as net exporters of premium electric units, while Southern European markets import mid-range cordless models from Central European assembly plants. Intra-EU supply chains concentrate motor winding and precision stamping in German industrial clusters, with final assembly spreading to lower-cost locations.
Germany
German households drive premium-tier adoption through garment longevity priorities and sustainable fashion alignment. The country's Federal Environment Agency enforces REACH compliance timelines that accelerate blade coating reformulations. Stuttgart and Munich host precision motor winding facilities supplying brushless DC architectures across Western Europe.
France
French alteration services and garment repair shops generate professional-grade demand for corded continuous-runtime units. ANSM and DGCCRF market surveillance authorities inspect retail channels for CE marking validity under the Low Voltage Directive. Lyon and Paris basin manufacturing bases supply hypermarket chains with mid-range detachable-chamber models.
United Kingdom
British consumers prioritize cordless convenience in urban households with limited storage space. Post-Brexit UKCA marking requirements run parallel to retained EU Ecodesign standards, creating dual certification burdens. London and Manchester distribution hubs channel online premium sales while Midlands warehousing supports retailer replenishment.
Italy
Italian textile manufacturers and luxury garment producers procure industrial-grade fabric shavers for quality control finishing. The country's national standardization body, UNI, participates in harmonizing EU motor efficiency test protocols. Milan and Turin industrial districts concentrate procurement decision-making for high-volume commercial applications.
Poland
Polish retail expansion offers penetration opportunities for feature-rich cordless units in underdeveloped hypermarket channels. The country's national market surveillance authority enforces CE marking compliance at eastern EU border entry points. Warsaw and Kraków retail clusters demonstrate rising mid-range price tier acceptance among emerging middle-class households.
Europe Fabric Shavers Market Competitive Landscape
Concentration sits with diversified appliance conglomerates and design-forward Nordic specialists. The vendor base splits between mass-market manufacturers with hypermarket scale advantages and premium positioning players controlling direct-to-consumer channels. Two strategic archetypes dominate: vertically integrated motor producers with captive component supply, and brand licensors outsourcing manufacturing to contract assemblers. Competitive moves center on brushless DC motor platform standardization and REACH-compliant supply chain certification.
Among Netherlands-based diversified electronics groups, Philips N.V. exemplifies patent-intensive rotary blade system development through Benelux R&D infrastructure. Swedish design specialists Steamery occupy a position within the Nordic premium segment through controlled direct-to-consumer distribution. French manufacturing scale players including Rowenta represent hypermarket supply archetypes with domestic production base advantages. Xiaomi Corporation anchors the value-engineered cordless tier through Chinese ecosystem manufacturing scale.
| Leading Market Players |
|---|
| Philips N.V. |
| Conair Corporation |
| Remington Products Company |
| Steamery |
| Gleener |
| Xiaomi Corporation |
| Electrolux AB |
| BSH Hausgeräte GmbH |
| Rowenta |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor substitution for brushed designs is redrawing procurement geography toward German precision winding facilities while compressing margin structures across mid-tier electric fabric shaver categories. REACH-compliant blade coating reformulations simultaneously elevate material costs and concentrate certified supplier relationships, tightening pricing flexibility for manufacturers serving French and German household buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification depth and motor architecture as primary differentiation drivers. Price erosion runs through the economy tier as copper winding cost volatility and REACH reformulation expenses compress viability. Household purchasers in Southern Europe exhibit highest price sensitivity, while professional alteration services in France absorb substantial premiums for continuous-runtime corded specifications.
Supply Chain Analysis
Inventory cycles for precision-stamped stainless steel mesh guards extend lead times by four to six months as capacity concentrates among three German tool-and-die specialists. Motor winding and electronic commutation components draw from German and Benelux industrial clusters, while final assembly spreads to Polish and Romanian facilities. Single-source vulnerability in mesh guard supply creates structural risk, with distribution running through hypermarket chains and direct-to-consumer platforms across Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory affairs capabilities have become the scarce asset separating contract winners from disqualification in Scandinavian public procurement, as REACH traceability and CE marking documentation displace informal supplier relationships. This capability gap shapes competitive outcomes across institutional buyer segments.
For Market Incumbents: Secure captive supply of precision-stamped mesh guards through backward integration or exclusive offtake agreements with German tool-and-die specialists, insulating against single-source vulnerability. Accelerate brushless DC motor platform standardization across wattage classes to capture Ecodesign compliance economies and defend against value-engineered cordless entrants from Chinese ecosystem manufacturers. For New Entrants and Emerging Players: Differentiate on replaceable cell architectures ahead of EU battery regulation amendments, building authorized service networks that capture aftermarket blade replacement revenue. Target Polish and Romanian hypermarket channels with feature-rich cordless units priced at mid-range tiers, exploiting underpenetrated shelf space and rising middle-class garment care budgets in Eastern European retail clusters. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors vertically integrated manufacturers with dedicated compliance functions and captive component supply. Long-term viability hinges on controlling precision motor production and certified coating supply chains. Watch ECHA substance evaluation windows as inflection indicators for supplier consolidation and certified capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Platform Standardization | Enables Ecodesign compliance scaling across French and German professional-grade product lines. |
| REACH-Compliant Supply Chain Certification | Unlocks Scandinavian municipal tender participation and institutional buyer contract awards. |
| Direct-to-Consumer Subscription Launch | Bypasses distributor markups in Nordic markets through controlled blade replacement programs. |
| Eastern European Retail Expansion | Captures underpenetrated Polish and Romanian hypermarket shelf space for cordless units. |
| Authorized Service Network Buildout | Positions for EU battery regulation replaceable cell mandates and aftermarket revenue capture. |
Research Methodology
Operator-level perspectives from textile service procurement managers, garment repair shop owners, hypermarket category buyers, and precision motor manufacturing engineers anchored the qualitative base. Primary fieldwork combined with secondary validation from ECHA substance evaluation databases, EU customs trade records, and national market surveillance authority inspection reports. Bottom-up unit economics modeling triangulated against top-down market sizing from appliance industry associations and retail audit data.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation timelines and copper commodity price scenarios. Segmentation dimensions modeled include product architecture, end-user procurement sophistication, distribution channel control, and price tier certification depth. CAGRs derived from trend extrapolation of motor technology adoption curves and replacement cycle dynamics, with brushless DC penetration rates and REACH compliance cost pass-through as key industry-specific inputs across the projection horizon.
Forecasts assume regulatory continuity in EU Ecodesign Directive and REACH enforcement regimes; material policy shifts affecting motor efficiency thresholds or substance restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Spools Market