
 Embroidery Equipment Market | 2026-2036
Embroidery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Embroidery Equipment Market Analysis
REACH chemical compliance is shifting the cost-of-entry calculus for European embroidery equipment purchasers by mandating traceable supply chains for textile finishing inputs. Tajima Industries Ltd. leverages its precision-engineered multi-head systems to dominate high-volume apparel production lines across East Asia. Brother Industries Ltd. anchors the mid-market segment through compact, digitally integrated machines that appeal to small commercial shops. Bernina International AG differentiates with Swiss-built mechanical reliability that commands premium positioning in educational and craft channels.
Embroidery equipment encompasses mechanical and electronic systems designed to stitch decorative thread patterns onto fabric substrates, typically operating at speeds of 750 to 1,200 stitches per minute with programmable needle positioning and automatic thread trimming. These systems serve commercial and industrial end users by enabling mass customization of apparel, home textiles, and promotional goods with repeatable precision. Computerized technology leads the equipment landscape due to its integration with design software and production management platforms, while digital connectivity features represent the fastest-growing capability cluster as shops adopt cloud-based job routing. The accessories segment captures significant aftermarket margin pools through recurring consumable demand for specialty threads, digitizing hoops, and replacement needle systems.
The US EPA regulates volatile organic compound emissions from textile coating operations, indirectly shaping equipment specifications for on-site finishing workflows. Japan's METI promotes manufacturing technology exports through standards harmonization that benefits JUKI Corporation and other domestic producers seeking overseas placement. China's GB standards for industrial sewing and embroidery machinery establish technical baselines that govern import eligibility and domestic product certification. Stakeholders must monitor evolving chemical compliance frameworks and digital interoperability standards as primary determinants of competitive access and equipment lifecycle value.
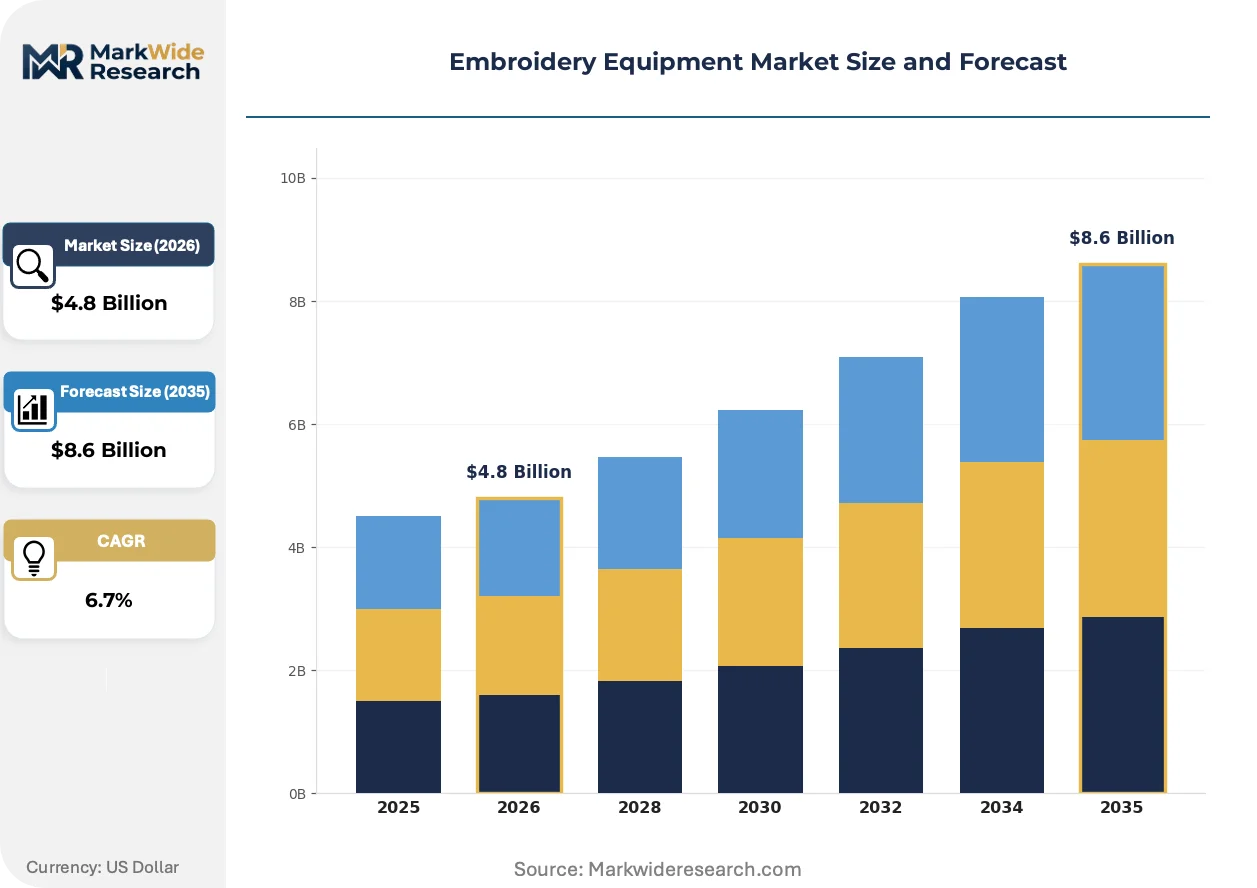
Market Dynamics
Short-run personalization orders from apparel decorators are compressing production batch sizes and forcing equipment vendors to optimize changeover speed and digital job routing capabilities.
Growth Catalysts
- Factory automation upgrades:Vietnam's garment manufacturing corridors are accelerating capital deployment as labor costs rise and export compliance tightens.
- REACH chemical compliance:European ECHA mandates on textile finishing chemicals are pushing buyers toward certified equipment vendors with traceable supply chains.
- Cloud-based job routing:Digitally connected embroidery systems enable real-time production scheduling that reduces downtime between small-batch orders.
Market Restraints
- Specialized component concentration:Precision servo motors and industrial-grade control systems concentrate among Japanese and German suppliers, creating single-source vulnerability.
- Volatile specialty thread costs:Polyester and rayon filament prices fluctuate with petrochemical feedstock markets, squeezing consumable margins for decorators.
- Technical speed ceilings:Mechanical thread tensioning systems face hard limits around 1,200 stitches per minute before quality degradation accelerates.
Strategic Opportunities
- Underpenetrated craft education:North American vocational schools and community colleges lack modern embroidery equipment for workforce training programs.
- Technical textile applications:Medical device manufacturers and aerospace suppliers require conductive thread embroidery for smart fabric integration.
- EU Green Deal alignment:Equipment vendors certifying energy-efficient motors and recyclable component designs gain preferential procurement status in public tenders.
Industry Challenges
- Digitizing technician shortage:Converting artwork to machine-readable stitch files requires specialized CAD skills that outpace vocational training output.
- Legacy system integration:Older mechanical embroidery machines lack data interfaces for modern production management platforms, forcing expensive retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embroidery Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embroidery Machines, Thread, Needles, Accessories Technology: Digital, Manual, Computerized, Semi-Automatic End User: Commercial, Industrial, Individual, Educational Application: Apparel, Home Textiles, Promotional Goods, Crafts |
| Companies Covered | Janome Sewing Machine Co. Ltd., Barudan Co. Ltd., Tajima Industries Ltd., ZSK Stickmaschinen GmbH, SWF (SunStar Co. Ltd.), Brother Industries Ltd., Bernina International AG, JUKI Corporation, Ricoma International Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embroidery Equipment Market Emerging Trajectories
Digital connectivity features represent the fastest-expanding capability cluster as commercial shops adopt cloud-native platforms for distributed production coordination and remote diagnostics.
Multi-head synchronization software is automating needle timing, thread tension adjustment, and color change sequencing across 12 to 24 head arrays. High-volume apparel producers in Bangladesh and Turkey are deploying these systems to reduce operator intervention and minimize defects across extended production runs. This automation is compressing labor cost differentials between established manufacturing centers and emerging competitors.
EPA volatile organic compound regulations on textile coating operations are forcing on-site finishing workflows to adopt closed-loop chemical recovery systems. Equipment specifications now incorporate integrated fume capture and solvent recycling modules as standard configurations for US-based decorators. California and New Jersey garment districts are retrofitting existing machine fleets to meet state-level air quality mandates ahead of federal enforcement timelines.
Subscription-based digitizing services are displacing perpetual-license software purchases among small commercial shops. Monthly fee structures bundle design conversion, cloud storage, and technical support that lower upfront capital barriers for new market entrants. This model is spreading fastest in UK and Australian decorator markets where equipment financing constraints limit traditional software procurement.
Embroidery Equipment Market Segmentation
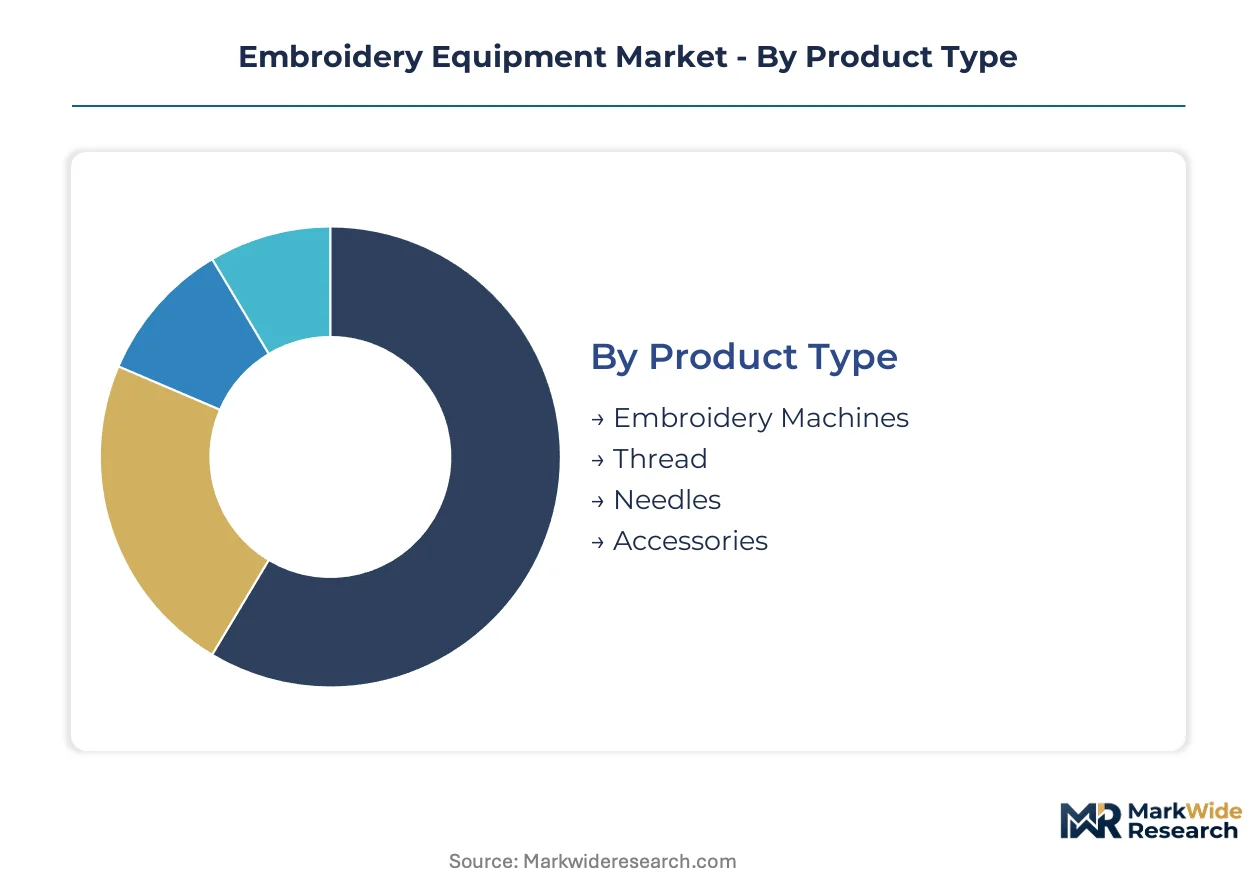
Equipment configuration and technology tier determine capital deployment patterns across embroidery operations. Segmentation reveals where margin pools concentrate and which buyer archetypes drive replacement cycles.
Product Type:
Supply concentration among precision component manufacturers shapes equipment availability and aftermarket parts accessibility.
- Embroidery Machines:Multi-head systems operating at 750 to 1,200 stitches per minute dominate high-volume apparel production in Vietnam's garment corridors. Factory automation upgrades accelerate capital deployment as labor costs rise and export compliance tightens.
- Thread:Polyester and rayon filaments constitute the primary consumable category with pricing tied to petrochemical feedstock volatility. REACH chemical compliance mandates in Europe push buyers toward certified suppliers with traceable supply chains.
- Needles:Industrial-grade replacement needle systems capture recurring aftermarket demand from continuous production environments. Specialty coatings and precision-ground points differentiate premium tiers.
- Accessories:Digitizing hoops, stabilizer materials, and thread management attachments round out the consumable ecosystem for commercial decorators.
Today's leader: Embroidery Machines. Tomorrow's challenger: Accessories.
Technology:
Cost tier stratification separates premium digitally integrated systems from entry-level mechanical alternatives.
- Computerized:Programmable needle positioning and automatic thread trimming integrate with design software and production management platforms. Cloud-based job routing capabilities represent the fastest-expanding feature cluster as commercial shops adopt distributed production coordination.
- Digital:Connectivity-enabled systems support remote diagnostics and real-time production scheduling that reduces downtime between small-batch personalization orders. Bangladesh and Turkey producers deploy these for multi-head synchronization across 12 to 24 head arrays.
- Semi-Automatic:Hybrid mechanical-electronic systems appeal to mid-market decorators balancing capital constraints with throughput requirements.
- Manual:Entry-level mechanical units serve hobbyist and educational channels with minimal electronic complexity and lower maintenance burden.
Computerized systems anchor current revenue. Digital connectivity features gain share fastest.
End User:
Customer type determines purchasing criteria from precision specifications to total cost of ownership calculations.
- Commercial:Small to medium decorators prioritize compact footprints and rapid changeover capabilities for short-run personalization orders. Subscription-based digitizing services lower upfront software barriers in UK and Australian markets.
- Industrial:High-volume apparel producers demand 24-head synchronization with automated needle timing and color change sequencing. Labor cost compression between manufacturing centers drives automation investment.
- Educational:North American vocational schools and community colleges lack modern equipment for workforce training programs, creating underpenetrated procurement channels.
- Individual:Hobbyist and craft segments favor mechanical reliability and Swiss-built precision for premium positioning.
Industrial buyers command volume. Educational institutions offer expansion runway.
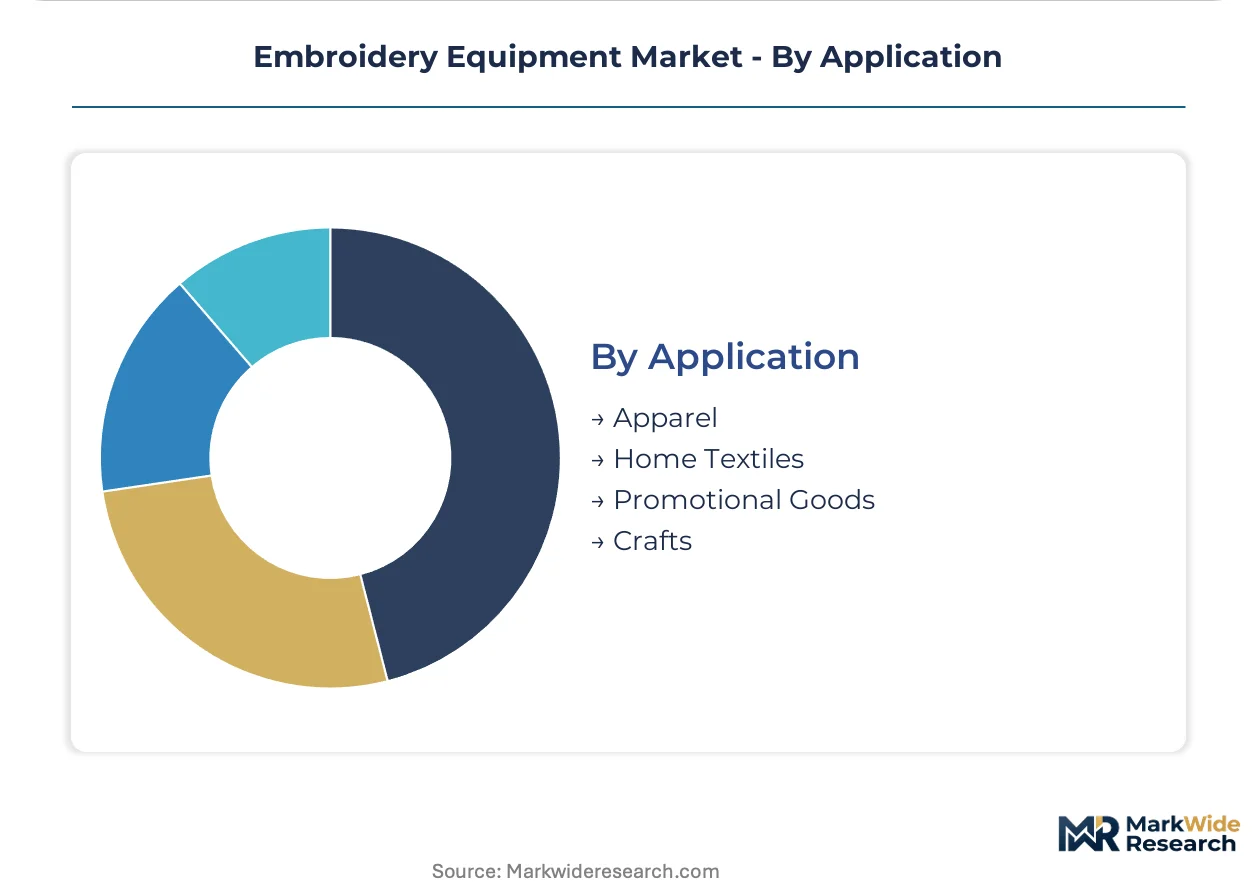
Application:
Volume concentration in apparel decoration shapes equipment specification standards across downstream categories.
- Apparel:Mass customization of uniforms, fashion garments, and sportswear drives the largest equipment deployment base. EPA volatile organic compound regulations force on-site finishing workflows toward closed-loop chemical recovery systems.
- Home Textiles:Decorative bedding, curtains, and upholstery applications require larger embroidery fields and specialized hooping systems.
- Promotional Goods:Corporate branding on bags, caps, and accessories generates consistent mid-volume demand with quick-turn requirements.
- Crafts:Artisan and specialty textile producers value mechanical precision for complex stitch patterns and mixed-media applications.
Apparel dominates current deployment. Technical textile applications in medical devices and aerospace emerge as expansion vectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled digitizing technicians cluster in Vietnam's garment manufacturing corridors and Turkey's textile engineering centers, anchoring equipment deployment decisions for multi-head system operators.
United States
Commercial decorators in Los Angeles and New York Metro drive demand for compact, digitally integrated machines. EPA volatile organic compound regulations on textile coating operations force on-site finishing workflows toward closed-loop chemical recovery systems. California's garment district retrofits existing fleets to meet state-level air quality mandates ahead of federal enforcement timelines.
Germany
Industrial apparel producers prioritize precision-engineered multi-head arrays for high-volume uniform production. ECHA REACH chemical compliance mandates on textile finishing chemicals push buyers toward certified equipment vendors with traceable supply chains. Baden-Württemberg's machinery engineering cluster supplies servo motor and control system components to domestic and export markets.
Vietnam
Factory automation upgrades accelerate as labor costs rise and export compliance tightens in Ho Chi Minh City and Hanoi manufacturing zones. GB standards alignment for machinery import eligibility governs equipment certification from Chinese suppliers. Dong Nai and Binh Duong provinces host the densest concentrations of garment exporters expanding machine fleets.
Japan
METI promotes manufacturing technology exports through standards harmonization benefiting domestic producers seeking overseas placement. Precision servo motor and industrial-grade control system suppliers concentrate in Nagoya and Osaka industrial corridors. JIS certification requirements establish technical baselines for domestic product quality and export market access.
Turkey
High-volume apparel producers in Istanbul and Bursa deploy multi-head synchronization systems to reduce operator intervention across extended production runs. EU Green Deal alignment pressures equipment vendors to certify energy-efficient motors and recyclable component designs for preferential procurement status. Gaziantep's textile hub automates to compress labor cost differentials with Asian competitors.
Embroidery Equipment Market Vendor Landscape
The competitive structure tilts toward precision-engineering specialists with multi-generational mechanical expertise. Consolidation pressure concentrates among Japanese and German component suppliers, creating single-source vulnerability for servo motors and control systems. Three archetypes dominate: precision-engineering heritage houses, digitally integrated platform providers, and compact-system specialists for small commercial shops. Capacity expansion and strategic partnerships represent the dominant competitive moves as vendors secure component supply and cloud-software integration.
Among Japanese manufacturers, Tajima Industries Ltd., Brother Industries Ltd., and JUKI Corporation occupy positions spanning industrial multi-head systems through compact commercial units. Tajima exemplifies the precision-engineering archetype with multi-generational mechanical expertise. Brother represents digitally integrated platform connectivity for mid-market decorators. JUKI sits within the industrial automation tier, leveraging METI export promotion frameworks for overseas placement. These three anchors demonstrate how geographic industrial policy shapes competitive positioning across equipment tiers.
| Leading Market Players |
|---|
| Janome Sewing Machine Co. Ltd. |
| Barudan Co. Ltd. |
| Tajima Industries Ltd. |
| ZSK Stickmaschinen GmbH |
| SWF (SunStar Co. Ltd.) |
| Brother Industries Ltd. |
| Bernina International AG |
| JUKI Corporation |
| Ricoma International Corp. |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock indices for polyester and rayon filaments cascade through embroidery equipment supply chains into three distinct pricing tiers segmented by automation level and certification grade. Equipment vendors absorb raw material volatility through differential bundling strategies that separate hardware from consumable and software service components.
Pricing Analysis
Subscription-based digitizing services are displacing perpetual-license software purchases among small commercial shops. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-built precision systems from mid-market digitally integrated units and entry-level mechanical alternatives. Price differentiation hinges on REACH certification tier and after-sales service bundling. Pricing pressure stems from volatile specialty thread costs tied to petrochemical markets. Commercial decorators exhibit highest price sensitivity; industrial high-volume producers prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
CE marking and REACH compliance certification gates access to European procurement channels for equipment vendors and component suppliers. Precision servo motors and industrial-grade control systems concentrate among Japanese and German manufacturers. Raw material dependencies include polyester filament, rayon thread, and specialty steel for needle systems. Single-source vulnerability in precision electronics creates supply chain risk. Distribution runs through authorized dealer networks and direct OEM relationships with large apparel producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embroidery equipment market functions as a geographic-arbitrage play where Vietnam's rising labor costs and tightening export compliance accelerate capital deployment that European REACH mandates simultaneously redirect toward certified vendors.
For Market Incumbents: Cement multi-head synchronization capabilities through backward integration into precision servo motor supply. Threats from cloud-native platform entrants and digitizing technician shortages demand defensive certification investments in EU Green Deal alignment for preferential tender access. Capacity addition in Vietnam's Dong Nai and Binh Duong provinces anchors regional production gravity. For New Entrants and Emerging Players: EU Green Deal alignment in Europe opens a window for energy-efficient equipment certification that incumbents have underinvested in. North American vocational schools and community colleges offer the most penetrable educational channel with minimal modern equipment presence. Go-to-market through subscription-based digitizing services lowers upfront capital barriers for small commercial decorators in UK and Australian markets. For Investors and Strategic Acquirers: Consolidation pressure builds where precision component manufacturing concentrates among Japanese and German suppliers. Long-term viability favors vendors controlling cloud-software integration and certified supply chain traceability. Acquisition targets include mid-tier digitally integrated platform specialists with established dealer networks. Signal to watch: METI export promotion framework expansion benefiting domestic producers seeking overseas placement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive supply of servo motors reduces single-source vulnerability from Japanese suppliers. |
| Cloud-Native Platform Development | Remote diagnostics and real-time scheduling compress downtime between small-batch orders. |
| REACH Certification Investment | Traceable supply chain compliance unlocks European public tender procurement channels. |
| Educational Channel Penetration | North American vocational school partnerships build workforce pipeline and brand loyalty. |
| Energy-Efficient Motor Certification | EU Green Deal alignment secures preferential status in sustainability-mandated tenders. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with equipment manufacturer executives, apparel decorator procurement leads, vocational school program directors, and aftermarket service heads. Secondary validation draws from EPA regulatory filings, ECHA REACH substance databases, METI export promotion disclosures, and customs machinery import records. Bottom-up equipment shipment data triangulates against top-down apparel production capacity estimates.
Granularity-level modeling segments by technology tier, end-user archetype, and application category with regional production cluster differentiation. Value outputs across the analysis window derive from capital expenditure patterns and replacement cycle timing. CAGRs emerge from equipment deployment trajectories in Vietnam's garment corridors and automation upgrade intensity in Turkey's textile hubs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price spikes or REACH compliance scope expansion. Forecasts reflect assumptions around labor cost trajectories and regulatory enforcement timelines. A model refresh is warranted upon material change in EU chemical compliance frameworks or Vietnam's export tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Braiding Machine Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market