
 Compact Spinning Machine Market | 2026-2036
Compact Spinning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Spinning Machine Market Outlook
Technical textile manufacturing is rebalancing toward premium apparel and performance fabric segments as mills upgrade from conventional ring frames. Rieter Holding AG leverages its Swiss engineering heritage to dominate high-speed compact spinning configurations for combed yarn. Lakshmi Machine Works Ltd. anchors South Asian demand through localized assembly and aftermarket service density. Saurer AG differentiates via digital control integration across its Autocoro platform, competing on energy metrics rather than speed alone.
A compact spinning machine condenses drafted fiber ribbons before twist insertion, typically operating at spindle speeds exceeding 20,000 rpm while reducing hairiness and improving yarn tenacity by 15-25% compared to standard ring spinning; its primary purpose is producing superior-quality yarn for fine-count fabrics and technical textiles with minimal pilling. Ring spinning occupies the mature volume base where replacement cycles sustain aftermarket revenue, while vortex spinning captures growth in blended-fiber applications requiring reduced processing stages. IoT integration represents the fastest-expanding technology segment as mills pursue real-time quality monitoring and predictive maintenance to compress downtime.
EPA efficiency benchmarks in the United States and REACH chemical compliance in Europe constrain lubricant formulations and machine coatings, pushing OEMs toward water-based alternatives and sealed bearing systems. China's SAMR enforces GB energy-labeling standards that disqualify older compact spinning architectures from state-backed mill modernization subsidies. Stakeholders must monitor regulatory divergence between Asian efficiency mandates and European chemical restrictions when configuring product portfolios for export markets.
Market Dynamics
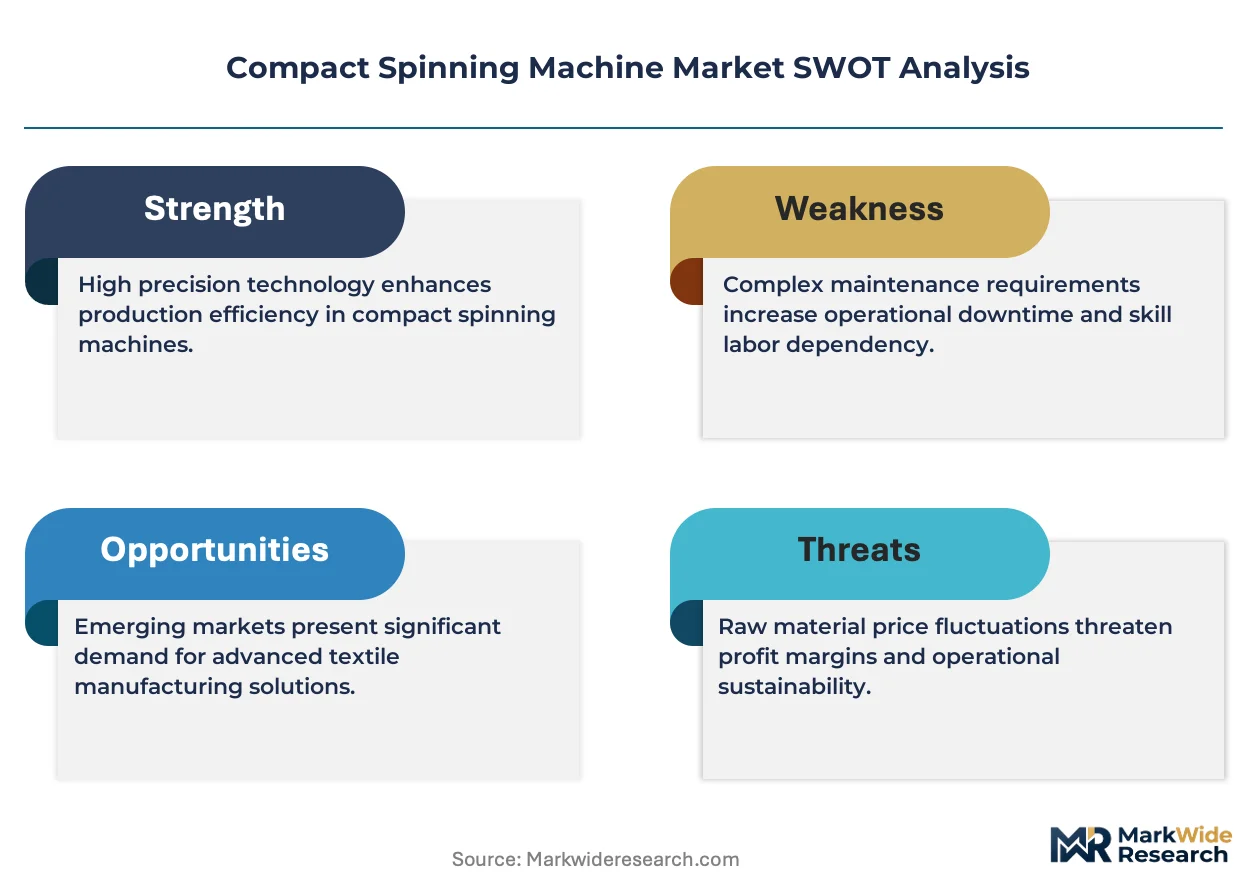
Mill modernization cycles are compressing as technical textile specifications tighten and energy-efficiency mandates from China's SAMR and India's BIS force premature replacement of installed ring frames with compact spinning architectures.
Growth Catalysts
- Technical textile specifications:High-tenacity yarn requirements from automotive airbag and industrial geotextile producers are pulling compact spinning adoption into non-apparel segments previously served by conventional ring systems.
- India's PLI scheme for textiles:Capital subsidy structures covering 10-15% of machinery investment are accelerating mill modernization timelines in Tamil Nadu and Gujarat spinning clusters.
- REACH chemical compliance:European lubricant formulation restrictions are disqualifying older machine architectures, creating replacement pull for sealed-bearing compact systems that eliminate oil-mist emissions.
Market Restraints
- Specialized component concentration:Precision spindle assemblies and compacting-zone pneumatic elements rely heavily on German and Swiss precision engineering suppliers, exposing buyers to euro-denominated input volatility.
- Vortex spinning substitution:Murata's vortex technology captures blended-fiber applications at 20-30% lower capital intensity per installed spindle, constraining compact spinning's addressable market in polyester-cotton segments.
- GB energy-labeling disqualification:China's SAMR standards retroactively classify pre-2018 compact architectures as non-compliant, stranding installed base value and depressing resale markets.
Strategic Opportunities
- Vietnam's export quota expansion:EU-Vietnam FTA tariff advantages are driving greenfield mill construction around Ho Chi Minh City and Binh Duong, creating first-mover positioning for compact spinning OEMs establishing local service density.
- IoT-predictive maintenance convergence:Real-time spindle vibration monitoring combined with AI-driven failure prediction enables mills to compress downtime and unbundle service contracts from hardware procurement.
- Carbon border adjustment mechanisms:EU CBAM pilot phase inclusion of textile imports is incentivizing South Asian mills to document energy-efficient production methods, favoring compact spinning's 15-25% power reduction over ring frames.
Industry Challenges
- Mechatronics skill scarcity:Compact spinning maintenance requires simultaneous competence in pneumatic systems, servo controls, and yarn physics, a combination rarely found in legacy ring-frame technician pools.
- Legacy DCS integration friction:Brownfield installations face protocol incompatibility between 1990s-era mill-wide control systems and modern compact spinning PLCs, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Spinning Machine Market |
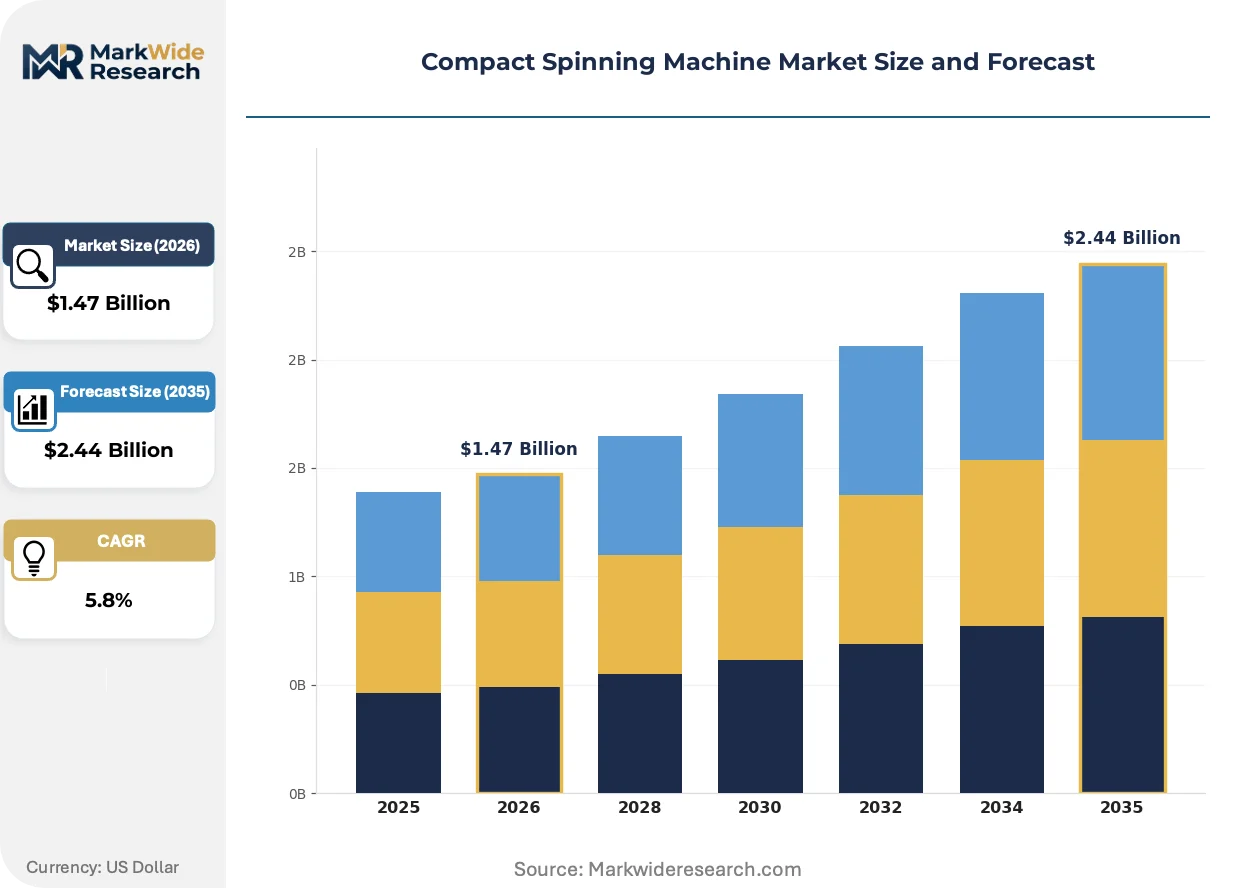
| Market Size in 2026 | $1.47 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ring Spinning, Open-End Spinning, Air Jet Spinning, Vortex Spinning Application: Textile Manufacturing, Carpet Industry, Non-Woven Fabrics, Geotextiles Technology: Automation, IoT Integration, Digital Control, Energy Efficient End User: Textile Mills, Clothing Manufacturers, Upholstery Producers, Industrial Users |
| Companies Covered | Murata Machinery Ltd., Lakshmi Machine Works Ltd., Rieter Holding AG, Jingwei Textile Machinery Co., Ltd., Marzoli Spinning Solutions, Saurer AG, Truetzschler Group, Zhejiang Taitan Co., Ltd., Toyota Industries Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Spinning Machine Market Strategic Shifts
Digital thread control and real-time quality feedback loops are displacing manual intervention as the primary mechanism for yarn consistency, compressing the skill premium previously commanded by master spinners.
Autoleveling draw frames with integrated spectroscopic trash detection are integrating directly into compact spinning delivery lines, eliminating separate process stages. Technical textile producers in Germany and Japan are adopting these configurations fastest, with automotive airbag yarn specifications driving the tightest tolerance requirements. The technology is integrating quality assurance into the spinning process itself rather than treating it as a downstream checkpoint.
China's GB energy-efficiency labeling standards now mandate disclosed power consumption per kilogram of yarn produced, with SAMR enforcement disqualifying older architectures from state-backed modernization subsidies. This regulatory pressure is compressing replacement cycles for installed ring frames in Shandong and Jiangsu provinces. Domestic Chinese OEMs are responding with simplified compact spinning designs that sacrifice maximum speed for lower capital cost and easier maintenance access.
After-sales service unbundling is accelerating as mill procurement teams separate hardware acquisition from maintenance contracts, comparing lifecycle cost models rather than upfront capital expenditure. Large spinning groups in India and Bangladesh are centralizing spare parts inventory and cross-training technicians across multiple OEM platforms. This behavioral shift is most visible in Tiruppur and Dhaka, where consolidated procurement functions now dominate capital allocation decisions.
Compact Spinning Machine Market Segmentation
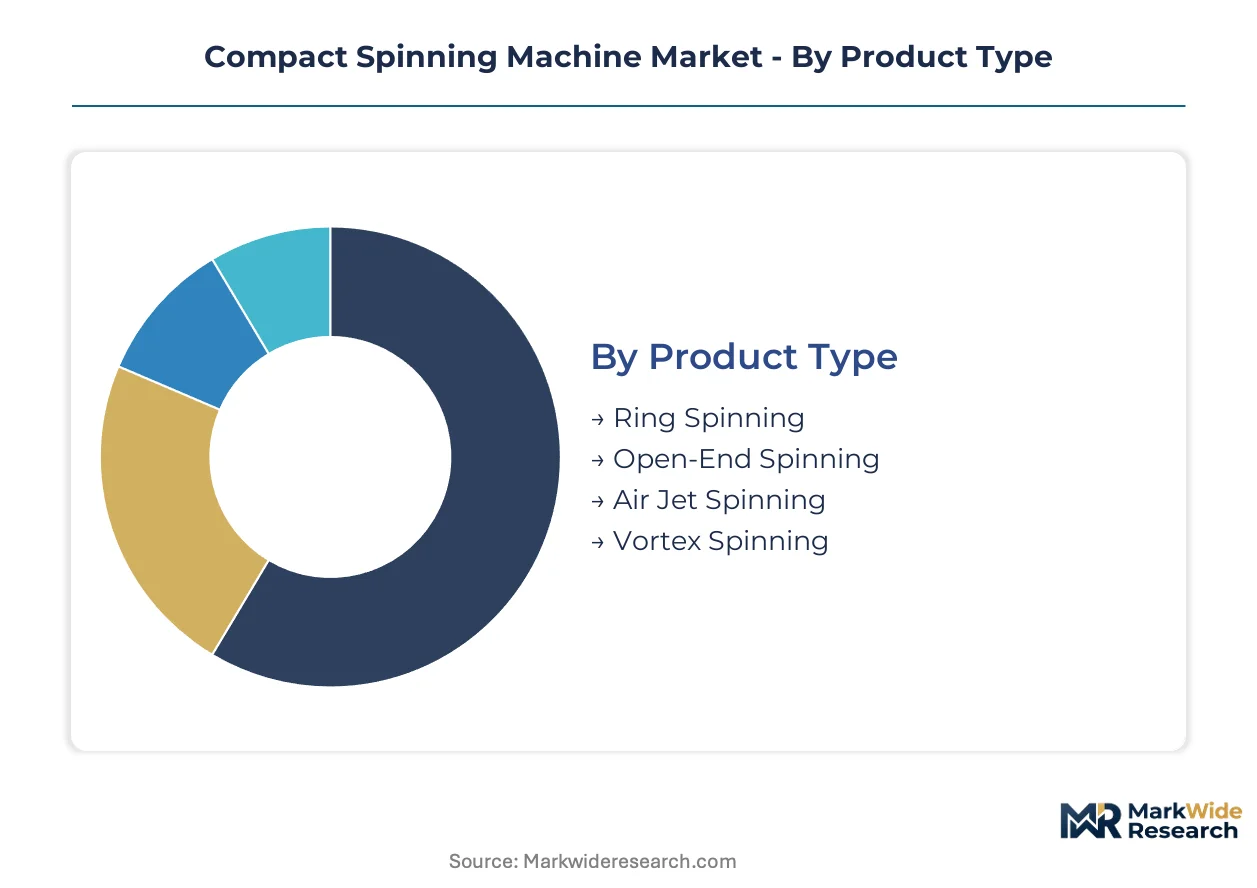
Compact spinning machine segmentation reveals divergent investment logic across spinning architectures and end-use specifications. Product type and application splits expose where capital concentrates versus where technology premiums command pricing power.
Product Type:
Ring spinning dominates installed volume while vortex and air jet technologies capture growth in blended-fiber and speed-sensitive applications.
- Ring Spinning:The foundational compact spinning architecture condenses fiber ribbons before twist insertion at spindle speeds exceeding 20,000 rpm. Demand concentrates in India and Vietnam where domestic apparel export expansion drives mill modernization from conventional ring frames to compact configurations.
- Vortex Spinning:Murata's proprietary technology eliminates roving stages entirely, processing polyester-cotton blends at 20-30% lower capital intensity per spindle. Adoption clusters in Bangladesh and Indonesia where cost-sensitive synthetic blend production dominates export contracts.
- Open-End Spinning:Rotor-based systems serve coarse-count yarn requirements with minimal maintenance overhead.
- Air Jet Spinning:Pneumatic twist insertion enables high-speed processing of man-made fibers in technical textile applications.
Mature deployment sits with ring spinning. Newer deployment is concentrated in vortex configurations.
Application:
Technical textile specifications are pulling compact spinning adoption beyond traditional apparel into industrial and performance segments.
- Textile Manufacturing:Premium apparel and fine-count fabric production remains the core revenue base, with automotive airbag yarn and industrial geotextile specifications driving tolerance tightening. Germany and Japan lead adoption of integrated autoleveling draw frames with spectroscopic trash detection.
- Geotextiles:High-tenacity yarn requirements for civil engineering applications demand compact spinning's 15-25% tenacity improvement over conventional ring systems. China's Shandong province anchors demand as infrastructure investment accelerates.
- Carpet Industry:Bulky yarn production favors open-end and air jet alternatives for pile height consistency.
- Non-Woven Fabrics:Direct web formation bypasses traditional spinning for disposable hygiene and filtration media.
Volume concentration rests with textile manufacturing. Margin expansion is steepest in geotextiles.
Technology:
Digital integration layers determine competitive differentiation as hardware commoditizes across OEM platforms.
- IoT Integration:Real-time spindle vibration monitoring combined with AI-driven failure prediction enables mills to compress downtime and unbundle service contracts from hardware procurement. Large spinning groups in India and Bangladesh centralize spare parts inventory around these predictive capabilities.
- Energy Efficient:China's SAMR enforces GB energy-labeling standards that disqualify older architectures from state-backed modernization subsidies, forcing premature replacement cycles in Jiangsu province mills.
- Automation:Autoleveling draw frames eliminate separate process stages in premium yarn configurations.
- Digital Control:PLC integration faces protocol friction against 1990s-era mill-wide control systems in brownfield installations.
Regulatory compliance drives energy-efficient retrofits. IoT integration commands the steepest expansion trajectory.
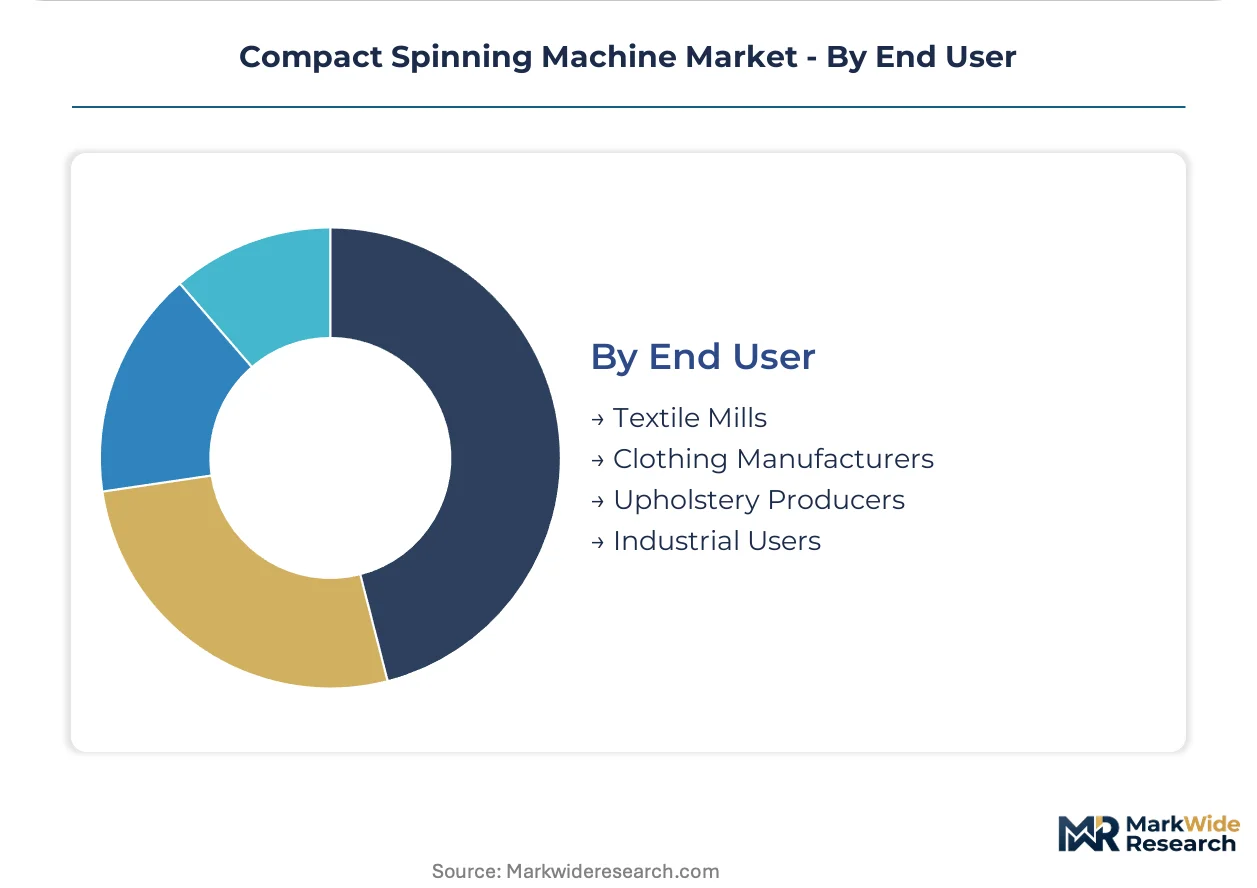
End User:
Procurement centralization separates consolidated spinning groups from fragmented upholstery and industrial operators.
- Textile Mills:Integrated spinning-weaving-knitting operations in Tamil Nadu and Gujarat leverage India's PLI scheme capital subsidies covering 10-15% of machinery investment to accelerate compact spinning adoption from conventional ring frames.
- Clothing Manufacturers:Brand-owned vertical operations in Vietnam's Binh Duong province prioritize compact spinning for EU-Vietnam FTA tariff advantages and CBAM-compliant carbon documentation.
- Upholstery Producers:Small-batch furniture textile manufacturers favor lower-speed compact configurations for design flexibility.
- Industrial Users:Technical textile producers for automotive and aerospace applications specify tightest tolerance requirements.
Consolidated procurement sits with textile mills. First-mover positioning concentrates in clothing manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of compact spinning machinery while India and Vietnam absorb the largest share of new installations. Production concentrates in coastal industrial zones serving export-oriented textile mills. Consumption patterns diverge between state-subsidized modernization in Asia and regulatory-driven replacement cycles in Europe.
China
Shandong and Jiangsu provinces house the densest concentrations of ring frame replacement activity as mills respond to SAMR's GB energy-labeling standards. The national regulator retroactively disqualifies pre-2018 compact architectures from state-backed modernization subsidies, forcing premature equipment turnover. Domestic OEMs in Zhengzhou and Qingdao now optimize designs for lower capital cost rather than maximum spindle speed.
India
Tamil Nadu and Gujarat spinning clusters leverage BIS efficiency mandates alongside PLI scheme capital subsidies covering machinery investment. The national standards body tightens energy-performance thresholds for textile equipment eligibility. Tiruppur mills centralize procurement functions to negotiate unbundled service contracts separate from hardware acquisition.
Germany
REACH chemical compliance restricts lubricant formulations and machine coatings, pushing mills toward sealed-bearing compact systems that eliminate oil-mist emissions. ECHA enforcement creates replacement pull for architectures compatible with water-based alternatives. Technical textile producers in Baden-Württemberg adopt integrated autoleveling configurations for automotive airbag yarn specifications.
Vietnam
Binh Duong and Ho Chi Minh City greenfield construction accelerates as mills exploit EU-Vietnam FTA tariff advantages for export quota expansion. The country's national textile regulator aligns local efficiency standards with European carbon border documentation requirements. First-mover OEMs establish service density to capture recurring maintenance revenue from consolidated spinning groups.
Switzerland
Swissmedic-adjacent precision engineering suppliers dominate spindle assembly and compacting-zone pneumatic component manufacturing. The country's reputation for high-speed compact spinning configurations sustains premium positioning despite euro-denominated input volatility. Winterthur and St. Gallen industrial corridors concentrate R&D activity for digital control integration.
Compact Spinning Machine Market Competitive Environment
Top-tier vendors anchor high-speed premium configurations, while mid-tier fabricators compete on localized assembly and aftermarket density. The vendor base stratifies across three functional tiers: precision engineering heritage players, regional volume specialists, and digital-integrated platform providers. Strategic moves concentrate on geographic expansion into Vietnam and Bangladesh, plus technology licensing arrangements that transfer compact spinning know-how to domestic Chinese OEMs.
Among Swiss and German precision engineering groups, Rieter Holding AG and Saurer AG occupy positions exemplifying the heritage-plus-digital archetype. Lakshmi Machine Works Ltd. represents the regional volume specialist model through South Asian assembly and service network density. Murata Machinery Ltd. anchors the alternative-technology vector with vortex spinning platforms that compete on capital intensity rather than yarn quality metrics.
| Leading Market Players |
|---|
| Murata Machinery Ltd. |
| Lakshmi Machine Works Ltd. |
| Rieter Holding AG |
| Jingwei Textile Machinery Co., Ltd. |
| Marzoli Spinning Solutions |
| Saurer AG |
| Truetzschler Group |
| Zhejiang Taitan Co., Ltd. |
| Toyota Industries Corporation |
| Others |
Value Chain & Pricing Dynamics
Precision spindle assemblies originating from Swiss and German engineering corridors feed downstream through three-tier pricing structures across premium, standard, and economy levels, with euro-denominated input volatility compressing margins for buyers locked into long-term service contracts.
Pricing Analysis
Cost-down pressure on mid-tier configurations accelerates because domestic Chinese OEMs in Zhengzhou and Qingdao optimize designs for lower capital cost rather than maximum spindle speed. Pricing stratifies across premium, standard, and economy tiers based on spindle speed capability and after-sales service bundling. India's PLI scheme capital subsidies covering machinery investment intensify price competition among regional volume specialists. Fragmented upholstery producers exhibit highest price sensitivity, while integrated textile mills in Tamil Nadu prioritize lifecycle cost models over upfront expenditure.
Supply Chain Analysis
Direct-to-OEM channels handle consolidated spinning group demand in India and Vietnam, while distributor networks serve fragmented industrial users across Bangladesh and Indonesia. Manufacturing concentrates in China, Switzerland, and Germany, with precision pneumatic components and sealed-bearing assemblies drawing from Swissmedic-adjacent suppliers. Specialized spindle assemblies rest on single-source vulnerability given limited alternative suppliers for compacting-zone elements. Distribution runs through OEM-captive service networks that unbundle maintenance contracts from hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around OEMs with established service density, as China's SAMR retroactive disqualification of pre-2018 architectures strands weaker players with depressed resale inventories.
For Market Incumbents: Cement aftermarket service density in Vietnam's Binh Duong province to capture recurring maintenance revenue from greenfield mill construction. Deepen backward integration into precision spindle assembly manufacturing to mitigate euro-denominated input volatility. Lock in long-term service contracts before procurement centralization in Tiruppur and Dhaka completes. For New Entrants and Emerging Players: AI-driven predictive maintenance platforms offer the most penetrable wedge against established OEMs, targeting large spinning groups in India and Bangladesh that centralize spare parts inventory. Focus initial deployment on brownfield installations facing legacy DCS integration friction, where protocol compatibility gaps extend commissioning timelines and create service intervention opportunities. For Investors and Strategic Acquirers: SAMR's expansion of GB energy-labeling disqualification criteria is the leading indicator that replacement cycle acceleration will concentrate market share among compliant OEMs. Target mid-tier fabricators with localized assembly capabilities and established regulatory compliance pathways. Watch for BIS efficiency mandate tightening in India as the signal for next-phase consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing to Domestic OEMs | Transfers compact spinning know-how to Zhengzhou and Qingdao manufacturers seeking speed-cost tradeoff optimization. |
| Geographic Expansion into Vietnam | Establishes first-mover service density around Ho Chi Minh City greenfield construction exploiting EU-Vietnam FTA advantages. |
| IoT Platform Integration | Enables real-time spindle vibration monitoring for Tiruppur mills pursuing unbundled service contract procurement. |
| Backward Integration into Precision Components | Reduces exposure to euro-denominated volatility from Swiss and German spindle assembly suppliers. |
| Regulatory Compliance Certification Investment | Secures eligibility for India's PLI scheme capital subsidies and China's SAMR modernization funding. |
Study Parameters
Trade publications, customs records, and OEM technical documentation formed the secondary backbone, cross-referenced against primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across India, Vietnam, and China. Bottom-up spindle installation counts and top-down mill modernization expenditure estimates were triangulated to validate market sizing.
Historical trendline analysis of ring frame replacement cycles and compact spinning adoption rates informed projection modeling across the analysis window. Segmentation dimensions included spinning architecture, end-use application, technology integration level, and regional regulatory cluster. CAGRs were derived from equipment shipment trajectories and capital expenditure patterns, with specific inputs from SAMR subsidy eligibility changes and BIS efficiency threshold tightening.
Several conditions sit outside the modeled scope, including vortex spinning technology substitution rates and potential REACH lubricant formulation expansion beyond current European boundaries. Forecasts reflect assumptions about continued PLI scheme funding continuity and stable euro-Swiss franc exchange rate bands. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Direct to Garment Printing Market