
 Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market | 2026-2036
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market Foresight
Rare-disease project finance and milestone-based venture structures are reshaping which developers can sustain multi-year gene-therapy programs. Origin Biosciences leverages its enzyme-replacement specialization to anchor early commercial traction in Mocod-A. BridgeBio Pharma sustains portfolio breadth across rare metabolic conditions while competing for capital against larger platforms. Ultragenyx dominates the broader molybdenum cofactor landscape through its manufacturing scale and regulatory navigation experience.
Molybdenum Cofactor Deficiency Type-A treatment addresses a fatal autosomal recessive disorder caused by mutations in the MOCS1 gene, where defective molybdenum cofactor biosynthesis prevents sulfite oxidase activity and leads to severe neonatal encephalopathy; therapeutic intervention aims to restore cofactor function or bypass the metabolic block before irreversible neurological damage occurs. Enzyme replacement therapy occupies the leading revenue position due to its established regulatory pathway and near-term commercial viability, while gene therapy represents the fastest-expanding segment as developers advance durable one-time interventions. Intravenous delivery maintains clinical dominance in hospital settings, though subcutaneous formulations are gaining developer attention for their potential to shift administration toward home healthcare environments.
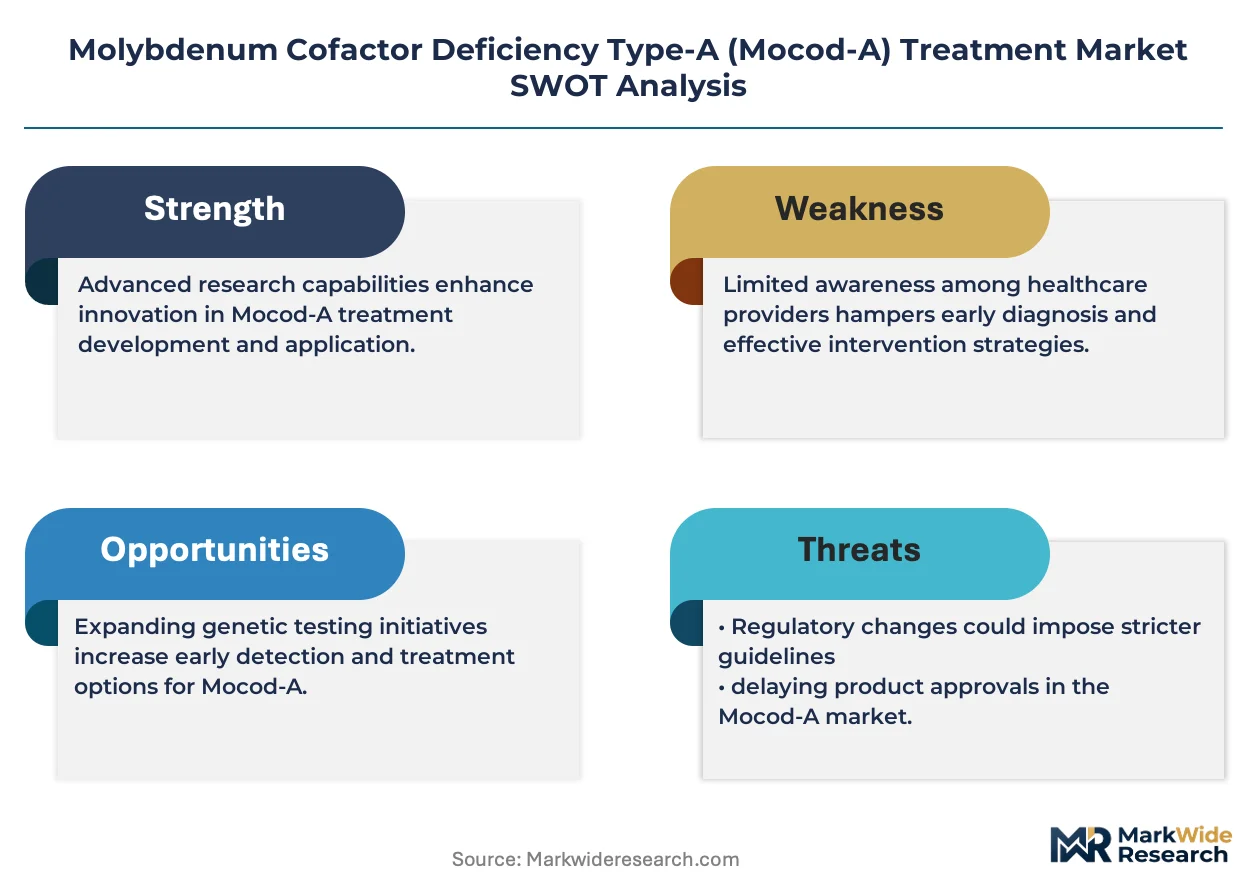
FDA orphan drug incentives and EMA priority medicines frameworks jointly determine which Mocod-A programs secure accelerated review and market exclusivity, while national newborn screening policies in Germany, Japan, and the United States directly govern patient identification rates and treatment addressability. The European F-Gas Regulation and corresponding FDA containment standards impose specific manufacturing requirements on gene-therapy production facilities, shaping capital deployment decisions for developers building commercial-scale supply. Stakeholders must monitor how reimbursement negotiations for ultra-rare therapies evolve across single-payer and multi-payer systems, as these decisions will determine which delivery modes and care settings achieve sustainable adoption.
Market Dynamics
Gene therapy manufacturing scale-up is compressing development timelines for Mocod-A interventions while simultaneously intensifying capital requirements for commercial readiness. This technological inflection is restructuring competitive entry barriers and partnership strategies across the therapeutic landscape.
Growth Catalysts
- FDA Orphan Drug Designation:Developers securing this status gain seven years of market exclusivity and tax credits for clinical trials, accelerating program viability for ultra-rare indications.
- Expanded Newborn Screening:State-level mandates in the United States and national programs in Germany and Japan are expanding the identifiable patient pool before irreversible neurological damage occurs.
- Enzyme Replacement Formulation:Intravenous-to-subcutaneous delivery advances are enabling outpatient administration and reducing hospital dependency for chronic therapy management.
Market Restraints
- Plasmid DNA Supply Concentration:Gene therapy developers face bottleneck risks from limited qualified suppliers of GMP-grade plasmid DNA, predominantly concentrated in North American and European contract manufacturing networks.
- European F-Gas Regulation:Cold-chain and cryopreservation requirements for biologics face escalating compliance costs and equipment retrofit mandates under phased fluorinated gas restrictions.
- Single-Payer Reimbursement Compression:National health technology assessment bodies in Germany and Japan apply incremental cost-effectiveness thresholds that ultra-rare therapies frequently exceed, limiting market access.
Strategic Opportunities
- Home Healthcare Infusion:Subcutaneous enzyme formulations enable shift from hospital-based to home administration, capturing value from reduced site-of-care costs and improved patient compliance.
- EMA Priority Medicines Pathway:Accelerated assessment and enhanced regulatory engagement support earlier market entry for therapies addressing unmet pediatric neurological needs.
- Companion Diagnostic Integration:MOCS1 mutation screening platforms paired with therapeutic development create integrated care pathways and streamline payer evidence requirements.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Viral vector production and analytical development for AAV-based candidates require specialized skill sets with limited trained personnel availability.
- Multi-Year Clinical Endpoint Validation:Neurodevelopmental outcome measurement in neonatal populations demands extended follow-up periods, complicating trial design and regulatory submission timelines.
- Cross-Border Cold Chain Integrity:Temperature-controlled distribution of temperature-sensitive biologics across fragmented European logistics networks introduces product stability risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market |
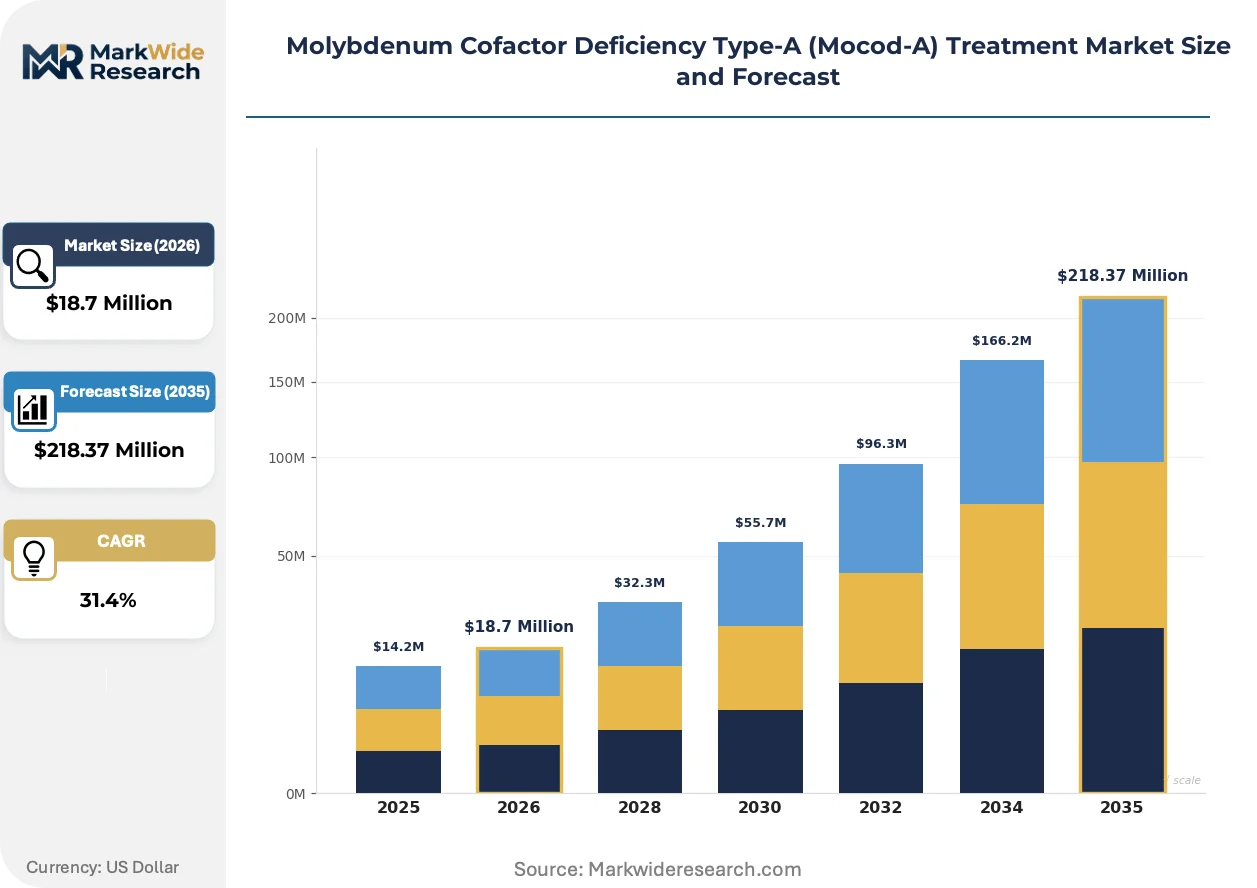
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Nutritional Supplements, Supportive Care Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Pediatric Clinics, Hospitals, Home Healthcare, Research Institutions Therapy Area: Metabolic Disorders, Genetic Conditions, Neurological Impairments, Rare Diseases |
| Companies Covered | Origin Biosciences, BridgeBio Pharma, Recordati Rare Diseases, Sentynl Therapeutics, Takeda Pharmaceuticals, WuXi AppTec, Ultragenyx, Orphatech Pharmaceuticals, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market Shifts & Advancements
Digital biomarker capture and real-world evidence generation are transforming how Mocod-A therapy developers demonstrate clinical value to payers and regulators. These capabilities are compressing traditional evidence-generation timelines while expanding the data assets available for market access negotiations.
AAV-mediated gene delivery is digitizing patient monitoring protocols through integrated wearable sensors and remote data transmission. Pediatric metabolic centers in the United States are piloting these connected care platforms to track neurodevelopmental trajectories between clinical visits. The technology is compressing the interval between intervention and observable outcome assessment, enabling adaptive trial designs.
EMA's F-Gas Regulation is forcing refrigeration infrastructure upgrades across gene therapy manufacturing facilities in the European Union. Developers are responding by qualifying alternative cryogenic systems and redesigning cold-chain logistics to maintain compliance without compromising product stability. The policy is accelerating capital deployment into sustainable manufacturing technologies ahead of implementation deadlines.
Site-of-care economics are reshaping procurement negotiations between metabolic disease centers and therapy developers. Hospital pharmacy directors in Germany and Japan are unbundling drug acquisition from infusion services, creating separate contracting streams for product and administration. This fragmentation is most pronounced in pediatric networks managing complex chronic conditions across multiple specialties.
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market Segmentation
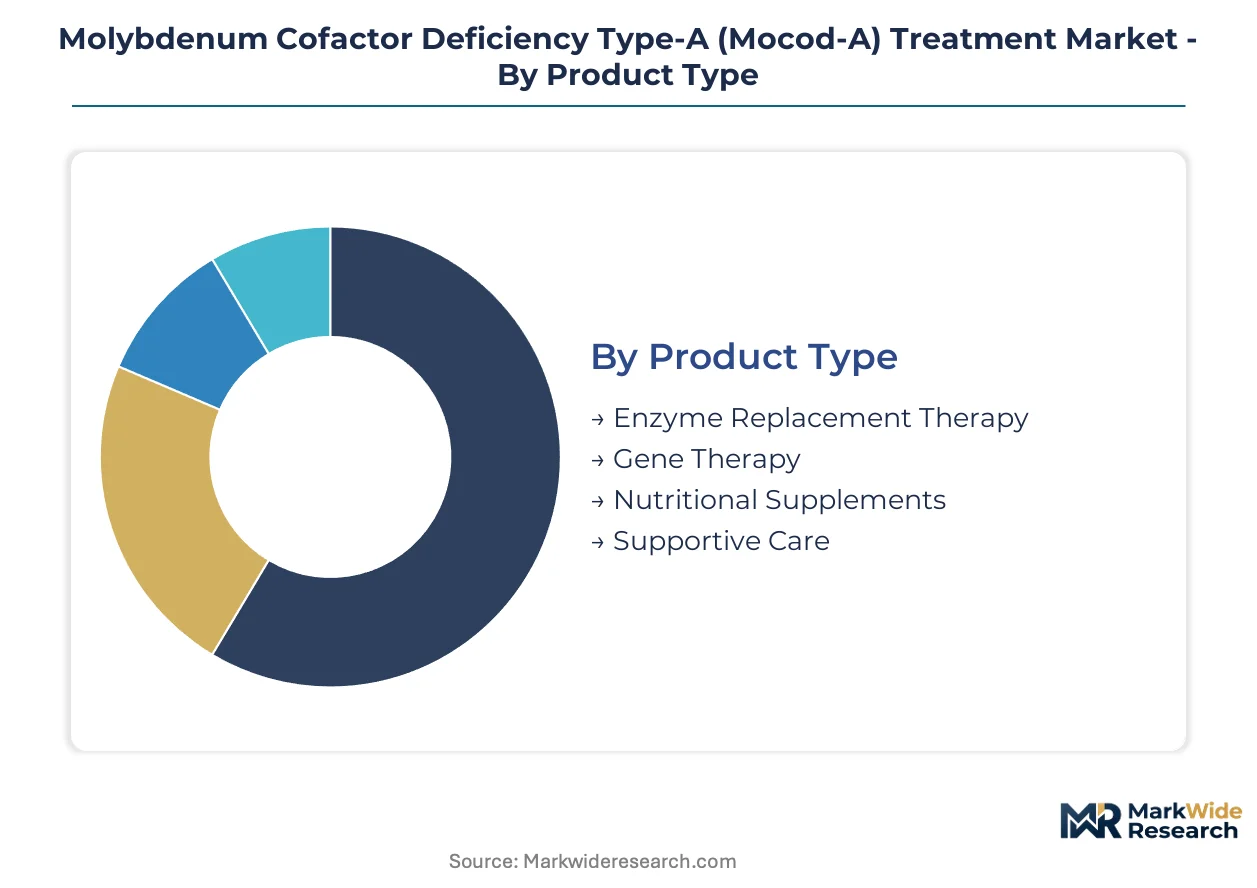
Mocod-A treatment segmentation reveals distinct commercialization timelines across therapeutic modalities. Cycle-time differentials between established enzyme platforms and emerging gene therapies reshape capital allocation and partnership strategies for developers.
Product Type:
Enzyme replacement platforms cycle through regulatory review fastest, while gene therapy development extends across multi-year manufacturing scale-up phases.
- Enzyme Replacement Therapy:Parenteral formulations deliver recombinant sulfite oxidase or cofactor precursors to bypass defective biosynthesis. Demand concentrates in pediatric metabolic centers across Germany, Japan, and the United States where newborn screening infrastructure enables early intervention before irreversible neurological damage.
- Gene Therapy:AAV-mediated MOCS1 gene delivery targets durable correction of the underlying genetic defect. Manufacturing complexity and extended follow-up requirements lengthen development cycles, though one-time administration potential attracts premium pricing frameworks in multi-payer reimbursement systems.
- Nutritional Supplements:Cofactor precursors and metabolic support compounds address residual pathway function.
- Supportive Care:Symptom management for seizure control and neuroprotection.
Enzyme replacement dominates installed base. Gene therapy is where expansion concentrates.
Delivery Mode:
Cost tier stratification separates hospital-based infusion services from emerging outpatient and home administration models.
- Intravenous:Hospital-administered infusion maintains clinical dominance for enzyme replacement and acute gene therapy delivery. German and Japanese pediatric metabolic centers anchor demand due to specialized nursing protocols and reimbursement structures favoring site-of-care billing.
- Subcutaneous:Formulation advances enable patient or caregiver administration outside institutional settings. Home healthcare economics and reduced hospital dependency drive development investment, particularly for chronic enzyme replacement requiring repeated dosing.
- Oral:Cofactor precursor bioavailability challenges limit therapeutic efficacy.
- Inhalation:Pulmonary delivery remains investigational for neurological metabolic indications.
Intravenous delivery captures highest reimbursement rates. Subcutaneous administration is climbing the fastest.
End User:
Customer type fragmentation creates distinct procurement patterns across institutional and emerging distributed care settings.
- Pediatric Clinics:Specialized metabolic disease centers coordinate multidisciplinary care for confirmed Mocod-A diagnoses. United States academic medical centers and German university hospitals lead adoption due to integrated genetics, neurology, and nutrition services.
- Hospitals:Tertiary facilities manage acute presentations and gene therapy administration.
- Home Healthcare:Subcutaneous formulation availability shifts chronic therapy management toward residential settings.
- Research Institutions:Natural history studies and clinical trial execution.
Pediatric clinics dominate installed base. Home healthcare is gaining share fastest.
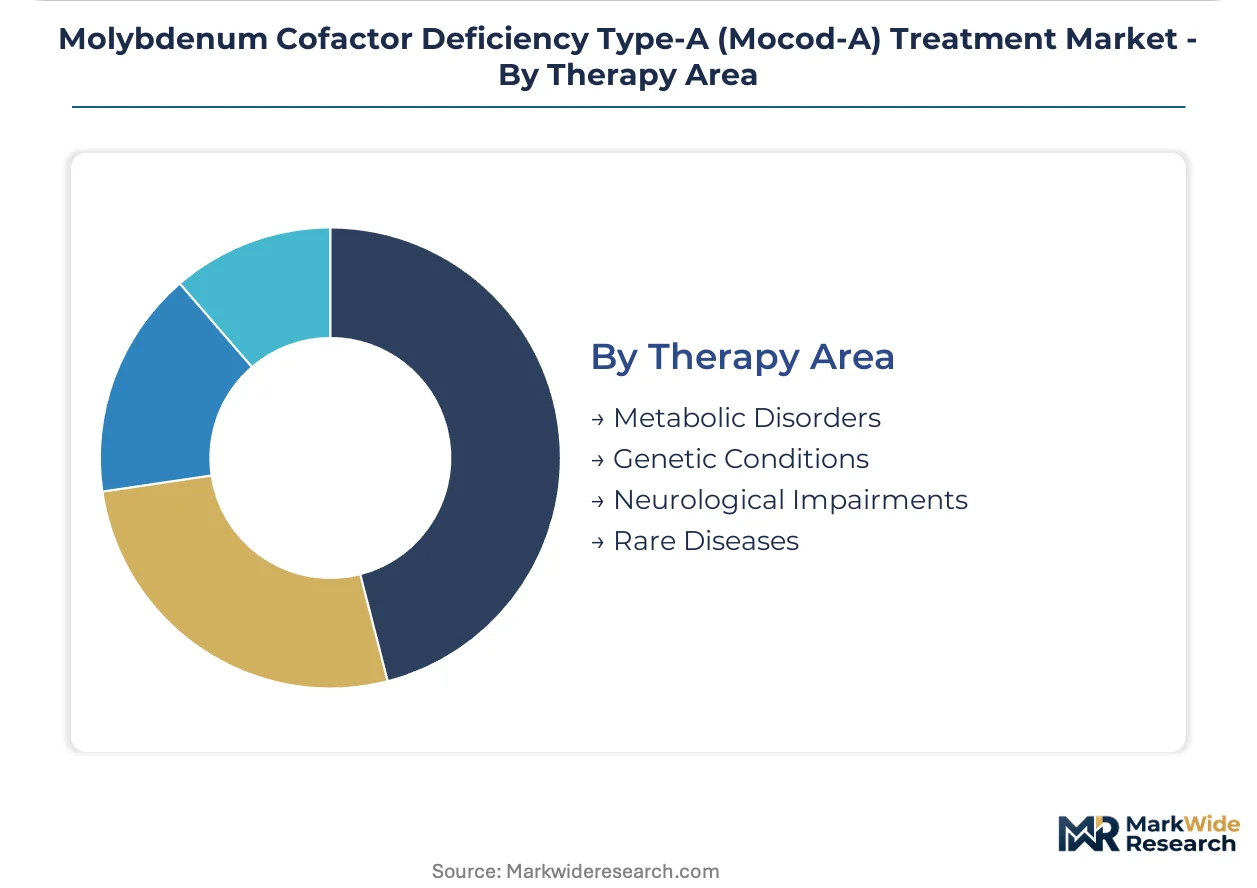
Therapy Area:
Maturity gradients separate well-characterized metabolic pathways from emerging genetic intervention frameworks.
- Metabolic Disorders:Established clinical understanding of molybdenum cofactor biosynthesis enables targeted therapeutic design. Enzyme replacement and cofactor supplementation address defined biochemical deficits with measurable biomarker endpoints.
- Rare Diseases:Orphan drug incentives and priority regulatory pathways accelerate program timelines. FDA and EMA designations reshape developer economics through tax credits, market exclusivity, and accelerated assessment procedures.
- Genetic Conditions:Gene therapy approaches target root-cause correction.
- Neurological Impairments:Neurodevelopmental outcome measurement complicates trial design.
Metabolic disorders anchor clinical development. Rare disease designation frameworks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric metabolic centers and newborn screening infrastructure determine where Mocod-A treatment demand materializes first. The United States, Germany, and Japan concentrate specialized care capacity and regulatory pathways that accelerate patient identification.
United States
Academic medical centers in Boston and Philadelphia anchor clinical trial enrollment for enzyme replacement and gene therapy candidates. State-level newborn screening expansion mandates in California and New York widen the addressable patient pool. FDA orphan drug designations provide seven-year market exclusivity and tax credits that reshape developer economics for ultra-rare indications.
Germany
University hospitals in Munich and Heidelberg coordinate multidisciplinary care for confirmed Mocod-A diagnoses through integrated genetics and neurology services. The national newborn screening program enables presymptomatic detection before irreversible neurological damage occurs. EMA priority medicines pathways accelerate assessment timelines for therapies addressing unmet pediatric needs.
Japan
Pediatric metabolic centers in Tokyo and Osaka manage acute presentations and chronic therapy administration through specialized nursing protocols. PMDA's orphan drug framework provides regulatory incentives analogous to FDA pathways. METI's healthcare innovation programs support domestic manufacturing scale-up for gene therapy production.
United Kingdom
Specialized metabolic networks in London and Manchester concentrate diagnostic expertise and therapeutic access for rare inherited disorders. NHS England's specialized commissioning frameworks determine reimbursement for ultra-orphan therapies through separate budget mechanisms. MHRA's post-Brexit regulatory autonomy enables accelerated access schemes distinct from EMA timelines.
Switzerland
Pediatric university hospitals in Zurich and Geneva serve as referral hubs for Alpine-region metabolic disease management. Swissmedic's streamlined orphan drug procedures align with EMA standards while maintaining independent assessment capacity. The country's pharmaceutical manufacturing infrastructure supports contract production for gene therapy viral vectors.
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players for access to pediatric metabolic centers and newborn screening networks. The market structure concentrates around developers with regulatory navigation experience in ultra-rare diseases and manufacturing scale for biologics production. Three archetypes dominate: enzyme-replacement specialists advancing parenteral formulations, gene-therapy platforms building durable one-time interventions, and diversified rare-disease portfolios spreading development risk. Competitive moves center on manufacturing partnerships for viral vector supply and companion diagnostic integration to streamline payer evidence requirements.
Within the enzyme-replacement tier, Origin Biosciences anchors early commercial traction through metabolic disorder specialization. BridgeBio Pharma occupies a diversified rare-disease position spanning multiple genetic conditions. Ultragenyx represents the manufacturing-scale archetype with established regulatory navigation experience across the broader molybdenum cofactor landscape.
| Leading Market Players |
|---|
| Origin Biosciences |
| BridgeBio Pharma |
| Recordati Rare Diseases |
| Sentynl Therapeutics |
| Takeda Pharmaceuticals |
| WuXi AppTec |
| Ultragenyx |
| Orphatech Pharmaceuticals |
| Bayer AG |
| Others |
Supply & Pricing Matrix
North American and European contract manufacturing networks for GMP-grade plasmid DNA concentrate upstream supply, anchoring margin pools with developers who have secured long-term viral vector partnerships. Pricing power downstream hinges on exclusivity windows and manufacturing scale rather than commodity competition.
Pricing Analysis
Certification level (FDA-grade versus non-GMP) creates the primary spread between commercial-ready and investigational therapies. Value-based pricing anchored to neurological outcome preservation dominates reimbursement negotiations, with gene therapy commanding premium positioning against chronic enzyme replacement. Cost compression in standard-tier enzyme formulations is intensifying as subcutaneous delivery options expand patient administration flexibility. Pediatric metabolic centers demonstrate lowest price sensitivity due to orphan drug exclusivity and limited therapeutic alternatives, while hospital procurement committees in single-payer systems apply incremental cost-effectiveness scrutiny.
Supply Chain Analysis
Plasmid DNA feedstock and recombinant enzyme production concentrate in the United States, Germany, and Switzerland where specialized biologics infrastructure clusters. Viral vector manufacturing draws from qualified contract development organizations with AAV platform expertise, while sulfite oxidase enzyme production rests on mammalian cell culture capacity. Single-source vulnerability in plasmid supply creates bottleneck exposure for gene therapy developers advancing toward commercial scale. Distribution runs through hospital pharmacy networks and specialized metabolic centers rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pediatric metabolic center networks that coordinate multidisciplinary care and control patient referral pathways. Hospital system consolidation in the United States and Germany is reducing the number of independent procurement decision points.
For Market Incumbents: Build regulatory exclusivity moats through companion diagnostic integration and newborn screening platform partnerships. Origin Biosciences and Ultragenyx should deepen manufacturing partnerships for viral vector supply security against emerging AAV platform competitors. EMA F-Gas Regulation compliance investments in sustainable cold-chain infrastructure will differentiate supply reliability. For New Entrants and Emerging Players: Home healthcare administration of subcutaneous enzyme formulations represents the most penetrable entry point for differentiated delivery technology. Japanese pediatric metabolic centers offer favorable reimbursement pathways for novel administration modes. A go-to-market strategy anchored to site-of-care economics and reduced hospital dependency will resonate with pharmacy directors unbundling procurement streams. For Investors and Strategic Acquirers: Capital is best deployed toward gene therapy platforms with demonstrated manufacturing scale-up capability and durable one-time administration profiles. Long-term viability favors developers with integrated MOCS1 mutation screening and therapeutic development pipelines. The signal to watch is EMA Priority Medicines designation velocity as an indicator of regulatory pathway efficiency and premium pricing potential.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Streamlines payer evidence requirements through MOCS1 mutation screening paired with therapeutic access. |
| Subcutaneous Formulation Development | Enables home healthcare administration and reduces hospital dependency for chronic enzyme replacement. |
| Viral Vector Manufacturing Scale-Up | Secures supply capacity for AAV-mediated gene therapy candidates approaching commercial readiness. |
| Newborn Screening Platform Expansion | Expands addressable patient pool through presymptomatic detection in California and New York state mandates. |
| EMA Priority Medicines Pathway Engagement | Accelerates assessment timelines for therapies addressing unmet pediatric neurological needs in European markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, EMA submissions, ClinicalTrials.gov records, and formulary databases. Primary interviews engaged drug development executives, regulatory affairs leads at rare disease specialists, hospital pharmacy directors in pediatric metabolic centers, and payer access specialists across single-payer and multi-payer systems. Bottom-up patient identification rates from newborn screening programs were triangulated against top-down market size estimates from therapy pricing and dosing frequency assumptions.
Forecast inputs include treatment modality segmentation, delivery mode transition rates, regional regulatory pathway velocity, and site-of-care economics evolution. The analytical framework models enzyme replacement and gene therapy adoption curves across the projection horizon, with CAGR derivation incorporating manufacturing scale-up timelines and reimbursement negotiation patterns. Patient population estimates incorporate geographic screening penetration differentials and diagnostic confirmation rates.
Practitioners should monitor EMA F-Gas Regulation implementation deadlines, plasmid DNA supplier qualification expansions, and single-payer incremental cost-effectiveness threshold adjustments for early signals of forecast revision. Cross-checking against external benchmarks from analogous ultra-rare disease therapy launches is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Chronic Smell and Flavor Loss Treatment Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market