
 Canned Wine Market | 2026-2036
Canned Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Wine Market Intelligence
The EU Green Deal is restructuring packaging compliance priorities across beverage manufacturing, compelling wineries to evaluate aluminum can recyclability and carbon footprint metrics. Constellation Brands leverages its diversified beverage portfolio to sustain shelf-space negotiations with major retail chains. Archer Roose differentiates through premium positioning in the single-serve wine segment, while Union Wine Company anchors its operations in Oregon's Willamette Valley winegrowing region.
Canned wine denotes wine products packaged in aluminum containers, typically in 187 mL to 375 mL formats, sealed under modified atmosphere conditions to preserve flavor stability and prevent oxidation during distribution. The format serves outdoor recreation, travel hospitality, and casual consumption occasions where glass bottle weight and breakage risk create functional barriers. Sparkling wine commands attention for its higher per-unit pricing and technical complexity in can conditioning, while standard aluminum cans dominate volume throughput due to established filling infrastructure across North American and European contract packagers. Retail consumers represent the core volume pool, though events and hospitality channels offer faster velocity for seasonal and limited-release SKUs.
FDA labeling requirements and TTB (Alcohol and Tobacco Tax and Trade Bureau) standards govern alcohol content disclosure and health warning placement on canned wine sold in the United States, while REACH compliance in Europe governs coating materials that contact beverage surfaces. The California Department of Alcoholic Beverage Control enforces additional state-level distribution restrictions that shape direct-to-consumer shipping permissions for canned formats. Stakeholders must monitor evolving extended producer responsibility legislation across multiple jurisdictions, as deposit-return schemes and recycled-content mandates will determine which packaging configurations maintain cost-competitive market access.
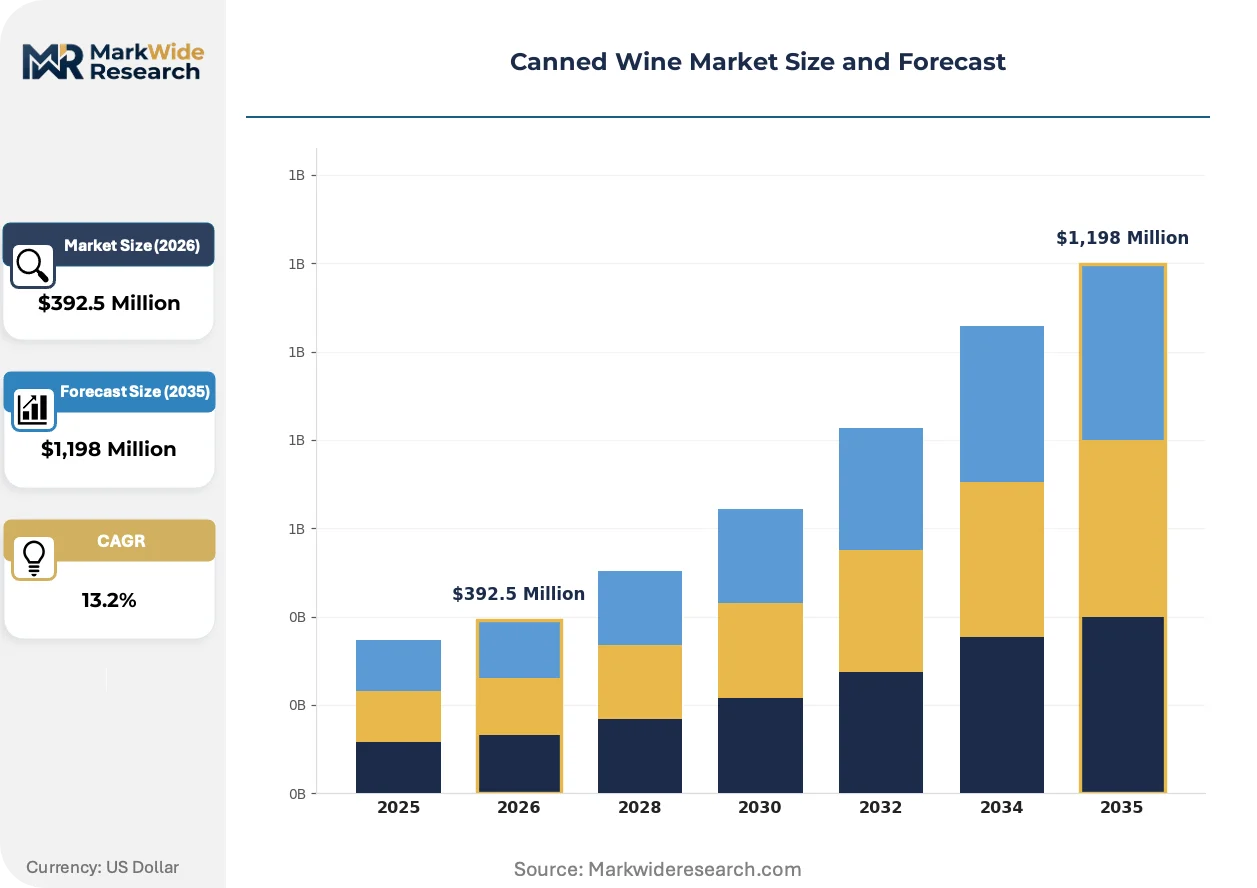
Market Dynamics
Aluminum can recyclability mandates under the EU Green Deal are restructuring packaging compliance priorities across beverage manufacturing, compelling wineries to evaluate carbon footprint metrics and circular supply chain integration.
Growth Catalysts
- EU Green Deal packaging targets:The EU Green Deal's sustainability requirements are pressuring producers to adopt recyclable aluminum formats and eliminate plastic use in wine packaging.
- Outdoor recreation demand:Festival attendance and camping participation in the United States are expanding the consumer base for portable wine formats that eliminate glass breakage risk.
- Single-serve convenience preference:Younger consumers in the United States favor convenience-oriented beverage formats that support on-the-go consumption occasions.
Market Restraints
- Aluminum input cost volatility:Primary aluminum pricing fluctuations create margin compression for can manufacturers and contract packagers.
- Supply concentration in contract filling:North American and European contract packagers dominate established filling infrastructure, limiting producer flexibility.
- Technical limitation in can conditioning:Sparkling wine requires modified atmosphere sealing complexity that elevates per-unit production costs.
Strategic Opportunities
- Underpenetrated travel hospitality:Airlines and rail operators in the United States represent untapped channels for single-serve wine formats.
- Deposit-return scheme expansion:Extended producer responsibility legislation across multiple jurisdictions creates competitive advantage for aluminum-can configurations.
- Technology convergence:Modified atmosphere sealing combined with smart packaging QR codes enables provenance tracking and consumer engagement.
Industry Challenges
- TTB compliance timeline:Alcohol content disclosure and health warning placement requirements create label redesign cycles that delay product launches.
- Skill gap in can conditioning:Sparkling wine technical complexity requires specialized expertise that remains scarce among contract packagers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Wine Market |
| Market Size in 2026 | $392.5 Million |
| Market Size in 2035 | $1,198 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Rosé, Sparkling Wine Packaging Type: Aluminum Cans, Eco-friendly Cans, Printed Cans, Standard Cans Customer Type: Retail Consumers, Restaurants, Events, Online Buyers Distribution Channel: Supermarkets, Liquor Stores, E-commerce, Direct Sales |
| Companies Covered | Constellation Brands, E. & J. Gallo Winery, Archer Roose, Usual Wines, Nomadica, Sans Wine Co., Maker Wine Company, Union Wine Company, Canned Wine Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Wine Market Strategic Shifts & Innovations
Active packaging technologies and regulatory compliance automation are reshaping how wine producers approach format selection and market access.
Modified atmosphere sealing technology preserves flavor stability in aluminum containers through controlled oxygen displacement and inert gas injection. Premium producers are adopting this technology to extend shelf life and support wider distribution reach. This advancement is rewriting quality perception thresholds for canned wine across retail and hospitality channels.
The EU Green Deal's packaging sustainability targets are mandating recycled-content minimums and carbon footprint disclosure for beverage containers sold in European markets. Wineries must now document aluminum sourcing and end-of-life recovery rates to maintain market access. Sparkling wine producers face the steepest compliance burden due to higher material specifications and conditioning requirements.
Direct-to-consumer shipping permissions are fragmenting across state-level regulators, forcing producers to maintain multiple distribution strategies. California Department of Alcoholic Beverage Control restrictions shape fulfillment options for canned formats differently than glass bottles. Younger buyers in the United States are gravitating toward subscription and seasonal release models that bypass traditional retail gatekeepers.
Canned Wine Market Segmentation
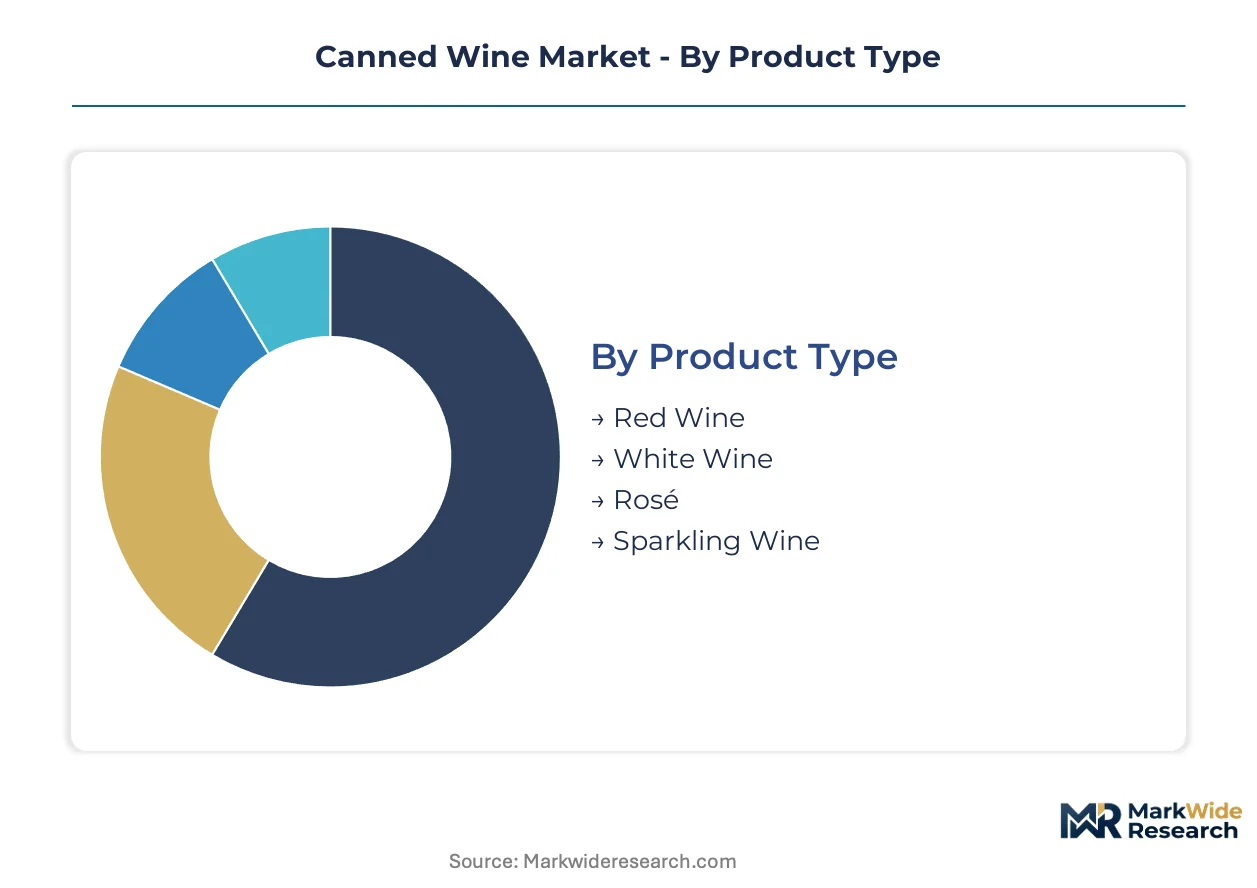
Format specifications and consumption occasions dictate distinct competitive dynamics across the canned wine market. Segmentation reveals where aluminum packaging technology intersects with channel economics and regulatory exposure.
Product Type:
Still wine formulations differ in can conditioning requirements and oxygen sensitivity profiles.
- Red Wine:Tannin structure and phenolic stability demand modified atmosphere sealing with nitrogen flushing. Demand concentrates in United States camping and festival venues where glass prohibition policies apply.
- White Wine:Higher acidity and lower phenolic load reduce oxidation risk during can storage. United States coastal markets show concentration for beach and boating consumption where temperature fluctuation tolerance matters.
- Rosé:Seasonal release cycles align with United States summer outdoor recreation peaks. Color stability under UV exposure requires specialized can lining specifications.
- Sparkling Wine:Carbonation retention demands pressure-rated can walls and precision crimp sealing. Technical complexity elevates per-unit production costs and limits contract packager availability.
Red wine leads on scale; sparkling wine leads on momentum.
Packaging Type:
Material specifications and surface treatments segment cost structures and compliance pathways.
- Aluminum Cans:Standard alloy compositions with epoxy-phenolic internal coatings. United States retail channels dominate volume through established beverage distributor relationships.
- Eco-friendly Cans:Recycled-content aluminum certified under EU Green Deal circular economy frameworks. European markets drive specification adoption as extended producer responsibility schemes expand.
- Printed Cans:Direct-to-metal digital printing enables short-run customization for limited releases. United States craft producers leverage this for seasonal and collaboration SKUs with faster design turnaround.
- Standard Cans:Undecorated or label-applied formats using existing beverage industry tooling. Contract packagers in United States and European manufacturing clusters optimize throughput for these specifications.
Standard cans anchor volume throughput; eco-friendly cans are climbing the fastest on regulatory tailwinds.
Customer Type:
Purchase context determines packaging size preferences and price elasticity thresholds.
- Retail Consumers:Individual and multi-pack purchases through grocery and convenience channels. United States younger demographics drive trial through single-serve 187 mL formats.
- Restaurants:By-the-glass program alternatives and outdoor patio service where glass breakage liability concerns apply. United States casual dining chains evaluate canned formats for labor efficiency.
- Events:Festival operators and sports venues with explicit glass prohibition policies. United States outdoor concert and camping event organizers represent high-velocity seasonal demand.
- Online Buyers:Direct-to-consumer subscription and seasonal release purchasers. United States state-level shipping permission fragmentation shapes fulfillment strategy complexity.
Retail consumers provide baseline demand; events generate the steepest expansion trajectory during peak seasons.
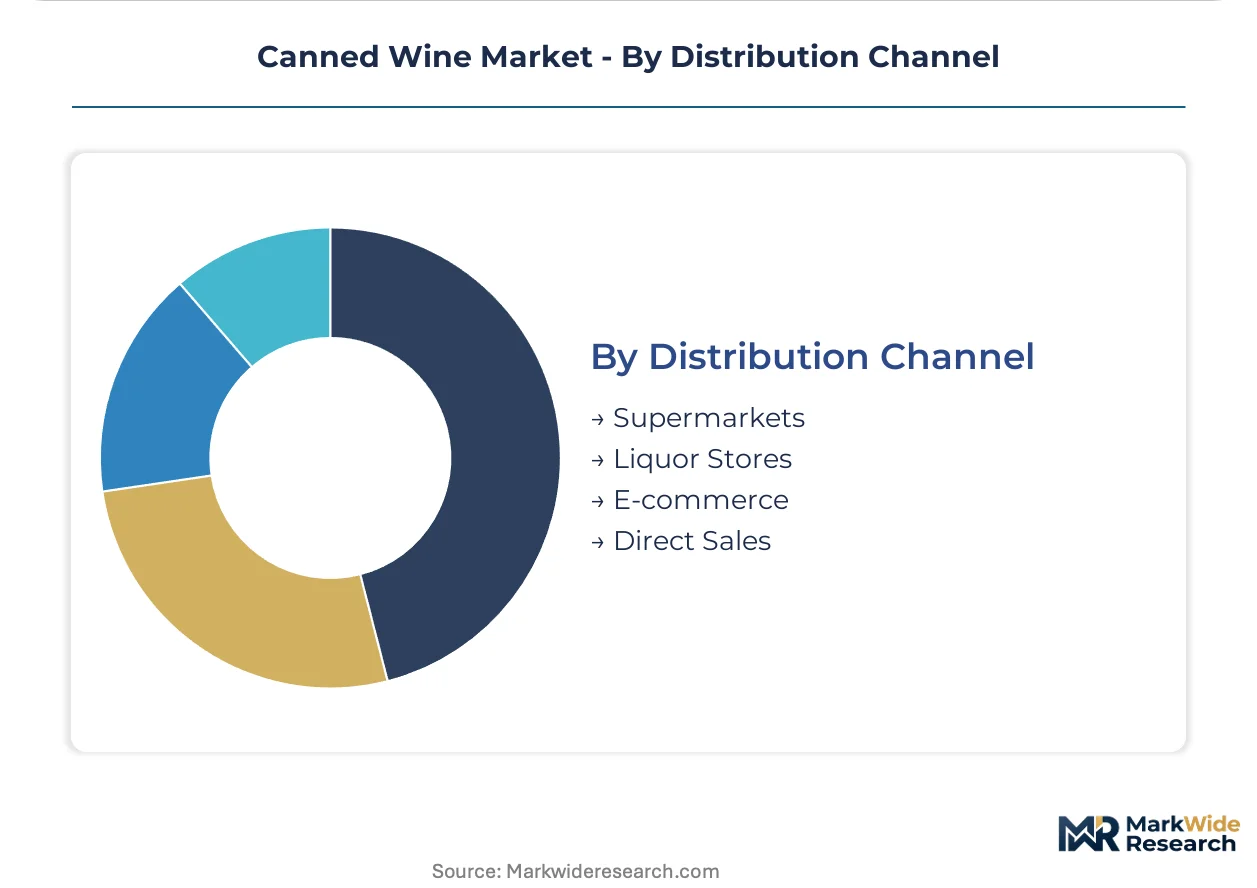
Distribution Channel:
Channel control determines margin capture and TTB compliance burden allocation.
- Supermarkets:Mass retail placement requires slotting fee negotiations and standardized case configurations. United States chains demand proof of supply chain scalability for category entry.
- Liquor Stores:Specialized alcohol retailers with established wine buyer relationships. United States independent operators offer faster listing decisions for local and regional producers.
- E-commerce:Platform-mediated sales requiring age verification integration and state-specific shipping compliance. United States fulfillment networks face California Department of Alcoholic Beverage Control and multi-state regulator fragmentation.
- Direct Sales:Producer-controlled channels including tasting room and subscription fulfillment. United States wineries leverage this for margin retention and customer data capture.
Supermarkets dominate absolute volume; e-commerce gains share fastest on logistics infrastructure maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The canned wine format emerged from United States West Coast wineries seeking portable alternatives to glass for outdoor recreation markets, with early scaling concentrated in Oregon and California winegrowing regions before European adoption accelerated under sustainability mandates.
United States
Camping participation and music festival attendance in the Pacific Northwest and Southeast drive single-serve format demand where glass prohibitions apply. TTB labeling standards govern alcohol content disclosure and health warning placement for interstate commerce. Oregon's Willamette Valley hosts contract packager clusters that service West Coast wineries with modified atmosphere sealing infrastructure.
Germany
Sparkling wine technical expertise in Baden-Württemberg and Rhineland-Palatinate supports can conditioning for premium formats. REACH compliance governs internal coating materials that contact beverage surfaces in aluminum containers. Bavarian beverage distributors are integrating canned wine into summer outdoor event logistics alongside established beer portfolios.
United Kingdom
London's hospitality sector evaluates canned formats for riverside and rooftop service applications where breakage liability concerns apply. Extended producer responsibility schemes mandate recycled-content minimums for packaging placed on market. English wine producers in Kent and Sussex are piloting canned releases for domestic tourism channels.
Australia
Beach and boating consumption in Queensland and Western Australia favors temperature-tolerant aluminum over glass for coastal markets. The country's national packaging regulator enforces sustainability disclosure requirements for beverage containers. South Australian wineries near Adelaide are retrofitting bottling lines for can filling to capture export demand from Asia-Pacific travel retail.
France
Provence rosé producers are testing canned formats for airline and rail hospitality channels serving summer tourism corridors. EU Green Deal circular economy frameworks require documentation of aluminum sourcing and end-of-life recovery rates. Languedoc-Roussillon cooperatives are evaluating short-run printed can capabilities for limited seasonal releases targeting festival circuits.
Canned Wine Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the canned wine market, with integrated wineries maintaining in-house canning lines while specialist brands outsource to contract packagers. The vendor base spans multinational beverage conglomerates, regional wine producers, and venture-backed format innovators. Three archetypes dominate: diversified alcohol portfolios, single-serve specialists, and terroir-rooted regional wineries. Capacity expansion and strategic retail partnerships constitute the primary competitive moves, with slotting fee negotiations determining supermarket placement access.
Within the diversified portfolio tier, Constellation Brands and E. & J. Gallo Winery occupy positions that leverage existing distributor relationships for category entry, while Union Wine Company exemplifies the terroir-rooted archetype with Willamette Valley operational concentration. Archer Roose represents the premium single-serve specialist model that targets convenience-oriented younger consumers through direct and retail channels.
| Leading Market Players |
|---|
| Constellation Brands |
| E. & J. Gallo Winery |
| Archer Roose |
| Usual Wines |
| Nomadica |
| Sans Wine Co. |
| Maker Wine Company |
| Union Wine Company |
| Canned Wine Co. |
| Others |
Cost & Logistics Intelligence
Modified atmosphere sealing technology is compressing cost economics for sparkling wine conditioning while simultaneously concentrating supply among North American and European contract packagers with certified nitrogen-flushing infrastructure. This technical transition elevates per-unit production costs for premium formats while locking out smaller wineries from in-house canning capabilities, reshaping competitive access across retail and hospitality channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sparkling wine with pressure-rated can walls from still wine in standard alloy compositions from private-label festival formats. Price differentiation rests on modified atmosphere certification, Oregon Willamette Valley terroir designation, and direct-to-consumer subscription bundling. Cost compression in the standard tier is intensifying because aluminum input volatility feeds through contract packager pricing. Festival operators and camping retailers exhibit highest price sensitivity; airline hospitality buyers accept premium positioning for breakage-elimination value.
Supply Chain Analysis
Workforce availability constraints in Oregon's Willamette Valley and Germany's Baden-Württemberg are tightening access to specialized can conditioning technicians for sparkling wine formats. Supply concentrates in the United States, Germany, and Australia, drawing from primary aluminum smelters, epoxy-phenolic coating suppliers, and nitrogen gas infrastructure providers. Single-source vulnerability runs through concentrated contract packager clusters in Portland and Stuttgart. Distribution runs through beverage distributors with established TTB compliance infrastructure and slotting fee negotiation leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canned wine market compounds steadily as EU Green Deal packaging mandates permanently shift format preference toward aluminum recyclability, embedding structural demand growth regardless of cyclical consumption patterns.
For Market Incumbents: Hedge aluminum cost exposure through long-term supply agreements with primary smelters before REACH and EU Green Deal recycled-content mandates tighten specification requirements. Secure capacity reservations at certified contract packagers in Oregon and Germany to defend against emerging single-serve specialists capturing festival and airline channels. Prioritize TTB label pre-approval pipelines to accelerate seasonal SKU turnaround. For New Entrants and Emerging Players: Airline and rail hospitality buyers represent the most penetrable channel given explicit glass prohibition policies and concentrated procurement decision-making. Target United States coastal markets with beach and boating consumption occasions where temperature fluctuation tolerance drives format preference. Lead with printed can customization capabilities for limited-release collaboration SKUs that bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among terroir-rooted regional wineries with retrofitting bottling lines for can filling and existing direct-to-consumer subscription bases. Long-term viability frames around 5-10 year format substitution curves in outdoor recreation and travel hospitality. Watch deposit-return scheme expansion across United States state legislatures as the inflection signal for aluminum-can competitive advantage crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| Contract Packager Capacity Reservation | Secures modified atmosphere sealing access ahead of EU Green Deal compliance deadlines. |
| Direct-to-Consumer Subscription Launch | Bypasses California Department of Alcoholic Beverage Control shipping restrictions through owned fulfillment. |
| Eco-Friendly Can Certification | Documents recycled-content aluminum sourcing for European extended producer responsibility schemes. |
| Airline Hospitality Partnership | Captures breakage-elimination value in United States travel channels with glass prohibition policies. |
| Printed Can Customization Investment | Enables short-run seasonal releases for festival circuits without slotting fee negotiations. |
Research Approach
Direct dialogue with contract packager operations managers, Oregon winery supply chain directors, airline beverage procurement officers, and TTB regulatory compliance specialists grounded qualitative findings. Secondary validation drew from FDA labeling guidance documents, EU Green Deal circular economy framework texts, aluminum industry association production data, and United States camping participation surveys. Bottom-up SKU volume aggregation and top-down category spend estimation triangulated market sizing across the analysis window.
Segment-level outputs modeled product type, packaging specification, customer purchase context, and distribution channel control simultaneously. CAGRs derived from elasticity-adjusted volume projections against aluminum price scenario bands and regulatory adoption curve assumptions. Forecast inputs incorporated TTB label approval timeline distributions and EU Green Deal implementation phase transitions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum tariff regimes, deposit-return scheme legislative adoption rates, and sparkling wine can conditioning technical breakthroughs. Forecasts reflect documented assumptions about outdoor recreation participation trends and sustainability mandate enforcement intensity. Material deviation in United States state-level shipping permission fragmentation or primary aluminum supply concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Japanese Whisky Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Europe Alcoholic Beverage Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market