
 Global Bitumen Membranes Market | 2026-2036
Global Bitumen Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bitumen Membranes Market Foresight
Wholesale distributor networks across Europe is tilting toward direct contractor relationships as project scale intensifies. SOPREMA S.A.S leverages its polymer-modification expertise to sustain specification dominance in French civil infrastructure. BASF SE anchors supply security through backward integration into styrene-butadiene rubber feedstocks. IKO PLC competes aggressively in North American residential re-roofing through regional manufacturing density.
Bitumen membranes comprise asphalt-saturated organic or synthetic carrier sheets, polymer-modified with atactic polypropylene or styrene-butadiene-styrene to achieve elastomeric performance across temperature ranges from minus twenty to plus ninety degrees Celsius, serving primarily as waterproofing barriers in building envelopes and civil structures. SBS Modified Bitumen dominates commercial roofing specifications where thermal cycling demands superior flexibility, while Self-Adhesive Membranes represent the fastest-growing installation category as labor scarcity drives contractor preference for cold-applied systems. Foundation Protection applications command premium pricing in urban densification projects where hydrostatic pressure resistance determines warranty terms.
REACH compliance through ECHA governs polymer additive formulations in European supply chains, while EPA stormwater regulations in the United States shape specification requirements for below-grade waterproofing in commercial developments. India's BIS certification mandates for roofing materials are tightening import quality gates across South Asian project markets. Stakeholders must monitor how building energy codes in multiple jurisdictions are elevating membrane reflectivity and insulation-composite requirements beyond traditional waterproofing performance.
Market Dynamics
Polymer-modified bitumen formulations are displacing conventional oxidized asphalt membranes as thermal cycling performance becomes the decisive specification criterion across commercial roofing procurement. The shift toward cold-applied installation systems is compressing demand for torch-down equipment and certified hot-work crews.
Growth Catalysts
- EU Green Deal building renovation targets:The directive mandates deep energy retrofits across existing commercial stock, expanding specification-grade waterproofing volumes in Germany, France, and Poland.
- SBS polymer modification:Styrene-butadiene-styrene elastomeric blends enable membranes to maintain flexibility across temperature ranges from minus forty to plus one hundred twenty degrees Celsius.
- India's infrastructure corridors:Dedicated freight corridors and industrial smart cities are generating concentrated demand for foundation protection and bridge deck waterproofing systems.
Market Restraints
- Crude oil price volatility:Bitumen derives from vacuum distillation of heavy crude fractions, exposing membrane producers to feedstock cost swings that compress margin predictability.
- Polymer additive supply concentration:Atactic polypropylene and SBS modifier production clusters in Northeast Asian petrochemical complexes, creating import dependency for European and North American compounders.
- Thermoplastic polyolefin substitution:TPO single-ply membranes are capturing specification share in low-slope commercial roofing where reflectivity and heat-welded seams outweigh bitumen's durability advantages.
Strategic Opportunities
- Self-adhesive cold-applied systems:Labor scarcity across French and German roofing contractors is accelerating specification migration toward peel-and-stick membranes that eliminate torch hazards and insurance premiums.
- Urban densification foundation protection:Below-grade waterproofing for deep basements and podiums in London, Mumbai, and São Paulo commands warranty-backed premium pricing.
- Photovoltaic-integrated roofing:BIPV mounting systems require compatible membrane substrates, creating specification partnerships between waterproofing and solar racking suppliers.
Industry Challenges
- Certified torch-applied installer scarcity:Insurance liability and fire safety regulations are shrinking the pool of qualified hot-work crews, constraining project velocity in torch-dependent segments.
- REACH SVHC compliance timelines:ECHA's candidate list expansion for Substances of Very High Concern forces reformulation cycles that disrupt multi-year specification approvals.
- Legacy built-up roofing replacement complexity:Removal of aged multi-ply systems containing asbestos or coal tar pitch requires hazardous material handling protocols that extend project durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bitumen Membranes Market |
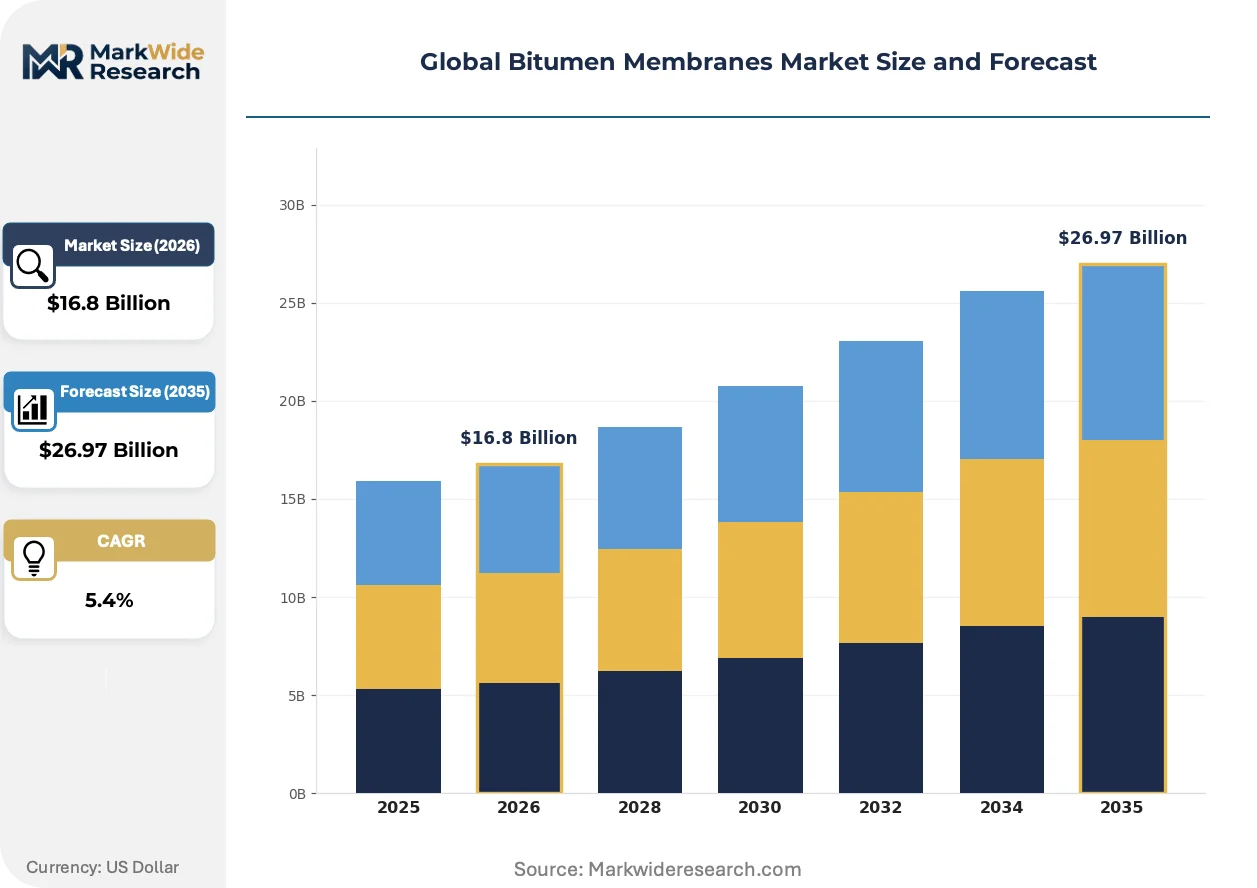
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: APP Modified Bitumen, SBS Modified Bitumen, Self-Adhesive Membranes, Bitumen Torch-On, Elastomeric Membranes Application: Roof Waterproofing, Wall Insulation, Foundation Protection, Balcony Waterproofing, Tunnel Lining Installation Method: Torch Application, Cold Application, Hot Application, Self-Adhesive, Mechanically Fastened End User Industry: Construction Contractors, Building Developers, Infrastructure Firms, Civil Engineering Services, Facility Managers |
| Companies Covered | Sika AG, BASF SE, SOPREMA S.A.S, BMI Group, Firestone Building Products Company LLC, IKO PLC, Johns Manville, TotalEnergies, Carlisle Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bitumen Membranes Market Shifts & Advancements
Installation methodology is overtaking material composition as the primary axis of product differentiation, with contractor labor economics and site safety constraints driving specification decisions ahead of raw performance metrics.
Self-adhesive membranes with factory-applied release films are rendering obsolete conventional torch-down application for low-slope commercial re-roofing. Mid-size contractors across the Netherlands and Belgium are specifying cold-applied systems exclusively to eliminate hot-work permits and reduce crew certification overhead. The shift is compressing demand for propane torches, fire extinguishers, and specialized insurance riders that previously structured contractor economics.
REACH authorization requirements for polymer plasticizers are tightening formulation disclosure across European supply chains. ECHA's scrutiny of phthalate alternatives is forcing compounders to validate substitute chemistries through extended migration testing. SBS-modified membrane producers serving German civil infrastructure are responding by accelerating bio-based plasticizer pilot programs to preempt regulatory exclusion.
Direct procurement relationships between membrane manufacturers and large-scale roofing contractors are disintermediating traditional two-step distribution across North American metropolitan markets. National contractors with annual membrane volumes exceeding five hundred thousand square meters are negotiating specification lock-ins and dedicated inventory positions. The pattern is most visible in Texas and Florida where storm-driven re-roofing cycles concentrate demand among regional roofing consolidators.
Global Bitumen Membranes Market Segmentation
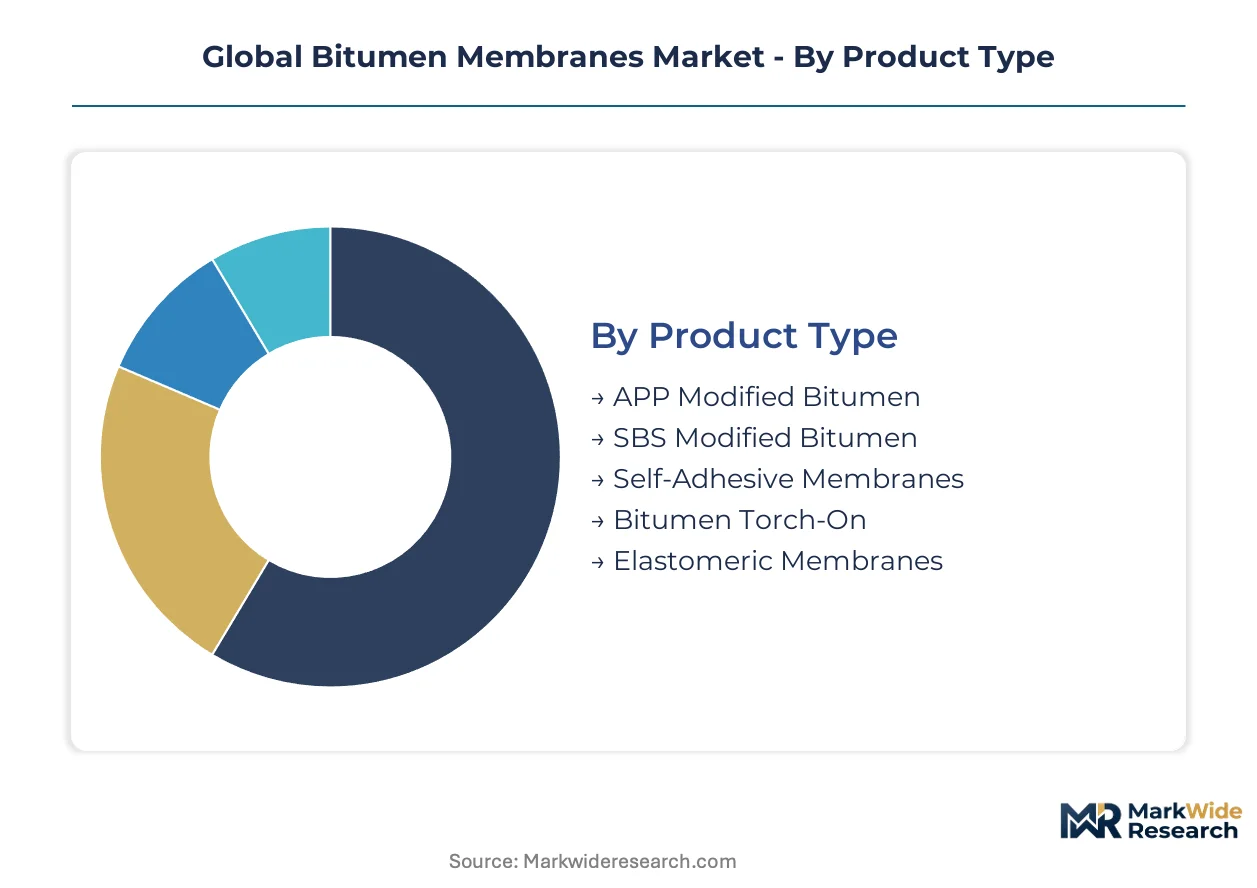
Bitumen membrane specifications diverge sharply across thermal performance requirements, installation constraints, and structural exposure conditions. Contractors select polymer modification chemistry and application method based on project scale, labor availability, and regulatory environment rather than material cost alone.
Product Type:
Product differentiation centers on elastomeric modification chemistry and factory-applied adhesive layers that determine field installation economics.
- SBS Modified Bitumen:Styrene-butadiene-styrene block copolymers impart rubber-like elasticity across temperature extremes from minus forty to plus one hundred twenty degrees Celsius. German commercial roofing specifications favor SBS for high-thermal-cycling climates where membrane flexibility preserves seal integrity.
- Self-Adhesive Membranes:Factory-applied pressure-sensitive adhesive layers with silicone release films eliminate torch hazards and hot-work permitting. Labor scarcity across French and Belgian contractor markets is accelerating specification migration toward peel-and-stick systems that reduce crew certification overhead and insurance premiums.
- APP Modified Bitumen:Atactic polypropylene modification enhances high-temperature flow resistance for hot-climate applications.
- Bitumen Torch-On:Conventional oxidized asphalt membranes require propane torch application and certified hot-work crews.
- Elastomeric Membranes:High-performance formulations combining SBS with proprietary plasticizer packages for extreme durability specifications.
Established volume favors SBS Modified Bitumen; emerging adoption favors Self-Adhesive Membranes.
Application:
Structural exposure determines membrane thickness, reinforcement scrim density, and warranty duration requirements.
- Roof Waterproofing:Low-slope commercial roofing demands multi-ply systems with polyester or fiberglass reinforcement to accommodate structural movement. India's infrastructure corridor projects specify SBS-modified membranes for bridge deck and station roof applications where monsoon thermal cycling exceeds sixty degrees Celsius daily.
- Foundation Protection:Below-grade waterproofing for deep basements and podiums requires hydrostatic pressure resistance up to seven bar. London's urban densification projects command premium pricing for membrane systems with thirty-year warranty backing against groundwater intrusion.
- Wall Insulation:Vertical envelope applications integrate membranes with exterior insulation and finish systems.
- Balcony Waterproofing:Pedestrian traffic-bearing membranes with slip-resistant mineral surfacing.
- Tunnel Lining:Shotcrete-compatible membranes for underground civil infrastructure.
Above-grade specifications concentrate in Roof Waterproofing; below-grade premium volumes are climbing the fastest in Foundation Protection.
Installation Method:
Application technology selection reflects labor market conditions, site safety constraints, and project schedule pressure.
- Cold Application:Solvent-based or water-based adhesives eliminate torch hazards in confined spaces. Dutch and Belgian mid-size contractors are specifying cold-applied systems exclusively to bypass hot-work permits and reduce crew certification requirements.
- Self-Adhesive:Peel-and-stick installation compresses project duration and eliminates propane equipment logistics. The method is expanding most quickly where insurance liability for torch-applied work has restricted contractor pool availability.
- Torch Application:Conventional propane torch bonding remains specified where substrate conditions demand heat-welded seams.
- Hot Application:Mopped hot bitumen bonding for built-up roofing restoration.
- Mechanically Fastened:Securement systems for high-wind zones and lightweight structural decks.
Contractor liability costs favor Self-Adhesive; substrate compatibility requirements sustain Torch Application in renovation segments.
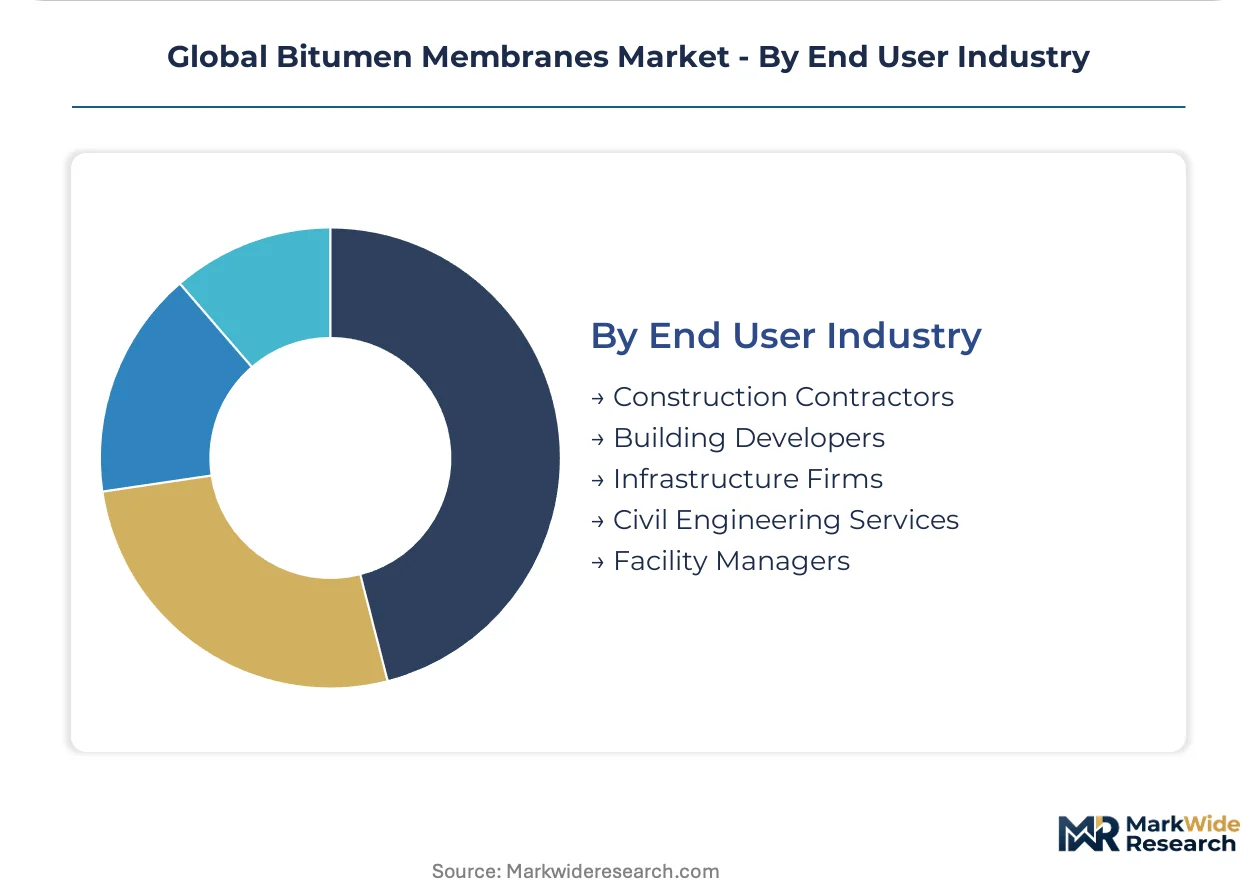
End User Industry:
Procurement scale and specification authority determine pricing structure and supply relationship intensity.
- Construction Contractors:Regional roofing specialists with annual membrane volumes exceeding five hundred thousand square meters negotiate specification lock-ins and dedicated inventory positions. Texas and Florida storm-driven re-roofing cycles concentrate demand among roofing consolidators with direct manufacturer relationships.
- Infrastructure Firms:State-backed project developers in India's dedicated freight corridors generate concentrated demand for foundation protection and bridge deck systems with decade-long performance warranties.
- Building Developers:Commercial real estate owners specifying membranes as part of envelope performance guarantees.
- Civil Engineering Services:Design-build contractors for transportation and water infrastructure.
- Facility Managers:Maintenance-driven procurement for existing building stock renovation.
Project scale economics favor Construction Contractors; public infrastructure volume is expanding most quickly through Infrastructure Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contractors command 15-20% pricing premiums over Indian project bids for specification-grade SBS membranes, reflecting divergent labor cost structures and compliance burden differentials.
United States
Storm-driven re-roofing cycles in Texas and Florida concentrate demand among regional roofing consolidators with direct manufacturer relationships. EPA stormwater regulations shape below-grade waterproofing specifications for commercial developments. Metropolitan Dallas and Houston anchor procurement volumes where annual membrane consumption exceeds five hundred thousand square meters per major contractor.
Germany
Commercial retrofit contractors scale specification-grade waterproofing systems under EU Green Deal building renovation mandates. ECHA REACH compliance governs polymer additive formulations across supply chains. The Rhine-Ruhr industrial corridor generates concentrated demand for foundation protection in urban densification projects with thirty-year warranty requirements.
India
Dedicated freight corridors and industrial smart cities drive foundation protection and bridge deck waterproofing procurement. BIS certification mandates tighten import quality gates across South Asian project markets. Maharashtra's infrastructure corridor projects specify SBS-modified membranes for station roof applications where monsoon thermal cycling exceeds sixty degrees Celsius daily.
France
Labor scarcity across roofing contractors accelerates specification migration toward self-adhesive cold-applied systems. ANSM and CNIL oversight complements EU-wide chemical regulations for construction materials. The Paris metropolitan area commands premium pricing for below-grade waterproofing in deep basement and podium developments.
United Kingdom
London's urban densification projects drive demand for hydrostatic pressure-resistant membrane systems with extended warranty backing. Building energy codes elevate reflectivity and insulation-composite requirements beyond traditional waterproofing performance. The Thames Gateway development zone anchors specification volumes for multi-ply commercial roofing systems.
Global Bitumen Membranes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying polymer modifiers and reinforcement scrims. The market structure consolidates around multinational chemical conglomerates with backward integration into SBS and APP feedstocks, mid-size European membrane fabricators with specification relationships, and regional roofing distributors disintermediated by direct contractor procurement. Three archetypes dominate: petrochemical-backed formulators, specialized waterproofing manufacturers, and construction-material conglomerates. Competitive moves center on captive supply of styrene-butadiene rubber feedstocks and cold-applied product line expansion.
Among European specialists, SOPREMA S.A.S exemplifies the polymer-modification expertise archetype, while IKO PLC represents North American manufacturing density strategies. BASF SE anchors the petrochemical-integrated tier with upstream control over SBS modifier production. These three occupy distinct positioning vectors—specification dominance in French civil infrastructure, aggressive residential re-roofing competition, and supply security through feedstock integration—rather than direct price competition.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| SOPREMA S.A.S |
| BMI Group |
| Firestone Building Products Company LLC |
| IKO PLC |
| Johns Manville |
| TotalEnergies |
| Carlisle Companies Inc. |
| Others |
Supply & Pricing Matrix
Northeast Asian petrochemical complexes in Ulsan and Yeosu anchor global SBS and APP modifier production, concentrating pricing power among integrated compounders who control elastomeric blend formulations. This supply concentration translates into premium capture for specification-grade membranes in German and North American markets, while Indian and Southeast Asian buyers face import dependency premiums.
Pricing Analysis
Configured-to-order pricing for project-specific SBS formulations commands spreads of 20-35% above standard catalog grades, with differentiation resting on thermal performance certification and warranty duration. Three-tier pricing structure across premium, standard, and economy levels segments the market: premium tiers bundle 30-year hydrostatic warranties for foundation protection, while economy grades serve residential re-roofing with 10-year coverage. Cost compression in standard-grade torch-applied membranes is intensifying because TPO substitution erodes specification share in low-slope commercial roofing. Infrastructure firms exhibit lowest price sensitivity due to decade-long performance guarantees, whereas residential roofing consolidators in storm-recovery markets negotiate aggressively on volume.
Supply Chain Analysis
Contract manufacturing for bitumen membrane fabrication clusters in Germany, the United States, and India, with regional plants serving 300-500 kilometer distribution radii to minimize logistics costs. Feedstock supply draws from vacuum distillation residues concentrated in Middle Eastern and Russian crude streams, with polymer modifiers sourced from South Korean and Chinese petrochemical complexes. Single-source vulnerability in atactic polypropylene supply creates exposure to Northeast Asian export restrictions. Distribution runs through direct manufacturer-contractor relationships in North American metropolitan markets, while European wholesale networks retain two-step structures for mid-size contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-grade waterproofing is shifting toward platform economics as BIPV-integrated roofing systems demand membrane-solar mounting interoperability. This ecosystem inflection rewards suppliers who control both substrate chemistry and racking partnership networks.
For Market Incumbents: Build specification lock-in moats through backward integration into SBS feedstocks and exclusive BIPV mounting partnerships. BASF SE's captive styrene-butadiene rubber production demonstrates this defensive posture. Counter TPO substitution by accelerating cold-applied product line expansion to capture labor-scarce contractor segments. Prioritize REACH-compliant bio-based plasticizer R&D to preempt ECHA authorization disruptions. For New Entrants and Emerging Players: Mid-market commercial buildings in Poland and the Czech Republic represent the most penetrable entry point, as EU Green Deal renovation targets concentrate demand among contractors seeking alternatives to established French and German suppliers. Self-adhesive membrane gaps in Southeast Asian infrastructure corridors offer second-wave expansion potential. Partner with regional roofing consolidators for specification trials rather than competing through distributor channels. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because polymer-modified bitumen formulation expertise concentrates in mid-size European specialists vulnerable to feedstock cost volatility. Target acquisition archetypes: SBS compounding specialists with civil infrastructure specification relationships in Germany or France. Watch for inflection in Indian BIS certification enforcement tightening import quality gates and accelerating domestic manufacturing investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SBS Feedstocks | BASF SE's captive styrene-butadiene rubber production insulates margin predictability against crude volatility. |
| Cold-Applied Product Line Expansion | Self-adhesive membrane launches capture French and Belgian contractors facing certified installer scarcity. |
| BIPV Mounting Partnership Network | Membrane-solar racking specification partnerships unlock photovoltaic-integrated roofing procurement channels. |
| Bio-Based Plasticizer R&D Investment | REACH-compliant formulation development preempts ECHA SVHC exclusion risks for German civil projects. |
| Direct Contractor Procurement Relationships | Texas and Florida roofing consolidators with 500,000+ square meter annual volumes negotiate specification lock-ins. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase: commercial roofing contractors, waterproofing specification engineers, polymer compounding plant managers, and wholesale distribution channel heads provided field-level input. Secondary validation drew from ECHA REACH registration databases, BIS certification records, EPA stormwater compliance filings, and customs trade data for bitumen and SBS modifier flows. Bottom-up project pipeline analysis across India's dedicated freight corridors and EU Green Deal retrofit programs was triangulated against top-down petrochemical feedstock demand modeling.
Calibration against historical specification-grade membrane volumes and polymer modifier consumption patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product modification chemistry, installation methodology, application exposure condition, and regional regulatory cluster. CAGRs were derived through elasticity-adjusted demand projection, with inputs from construction activity indices and crude fraction price correlation analysis. Industry-specific forecast inputs incorporated EU building renovation target implementation rates and Indian infrastructure corridor project award timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, construction labor availability, or ECHA authorization timelines would shift the trajectory. Quarterly review of polymer modifier import volumes, roofing contractor certification counts, and BIS enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Membrane Skinners Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Global Medical Membranes Market