
 Spinal Osteosynthesis Units Market | 2026-2036
Spinal Osteosynthesis Units Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Osteosynthesis Units Market Outlook
Implant maintenance and long-term surveillance services is consolidating around hardware vendors, blurring the traditional split between device sale and post-operative care. Medtronic leverages its integrated spine platform to capture recurring revenue through patient monitoring ecosystems. Stryker anchors its competitive stance with robotics-assisted surgical workflows that tie hardware placement to software-defined outcomes. Globus Medical differentiates through specialized expandable interbody devices that command premium positioning in complex deformity cases.
Spinal osteosynthesis units are mechanical fixation assemblies comprising rods, screws, hooks, and connectors manufactured from titanium alloys or polyetheretherketone composites, designed to stabilize vertebral segments through rigid internal fixation until bony fusion or motion preservation occurs. Fusion devices dominate procedural volume in degenerative indications, while non-fusion devices represent the fastest-growing structural category as motion-preserving alternatives gain surgical acceptance. Robotic assistance technology concentrates margin pools through capital equipment placement and disposable instrument attach rates, whereas traditional surgery still occupies the majority of global procedure volume due to capital constraints in emerging systems.
The FDA 510(k) clearance framework and the EU Medical Device Regulation together shape product development roadmaps, with the former emphasizing substantial equivalence and the latter demanding clinical evidence portfolios that extend timelines for market access. ISO 13485 quality management standards govern manufacturing consistency across production sites, directly influencing supplier qualification for hospital procurement tenders. Stakeholders must monitor how reimbursement shifts toward bundled episode payments reshape the economic viability of premium implant technologies versus standard fixation constructs.
Market Dynamics
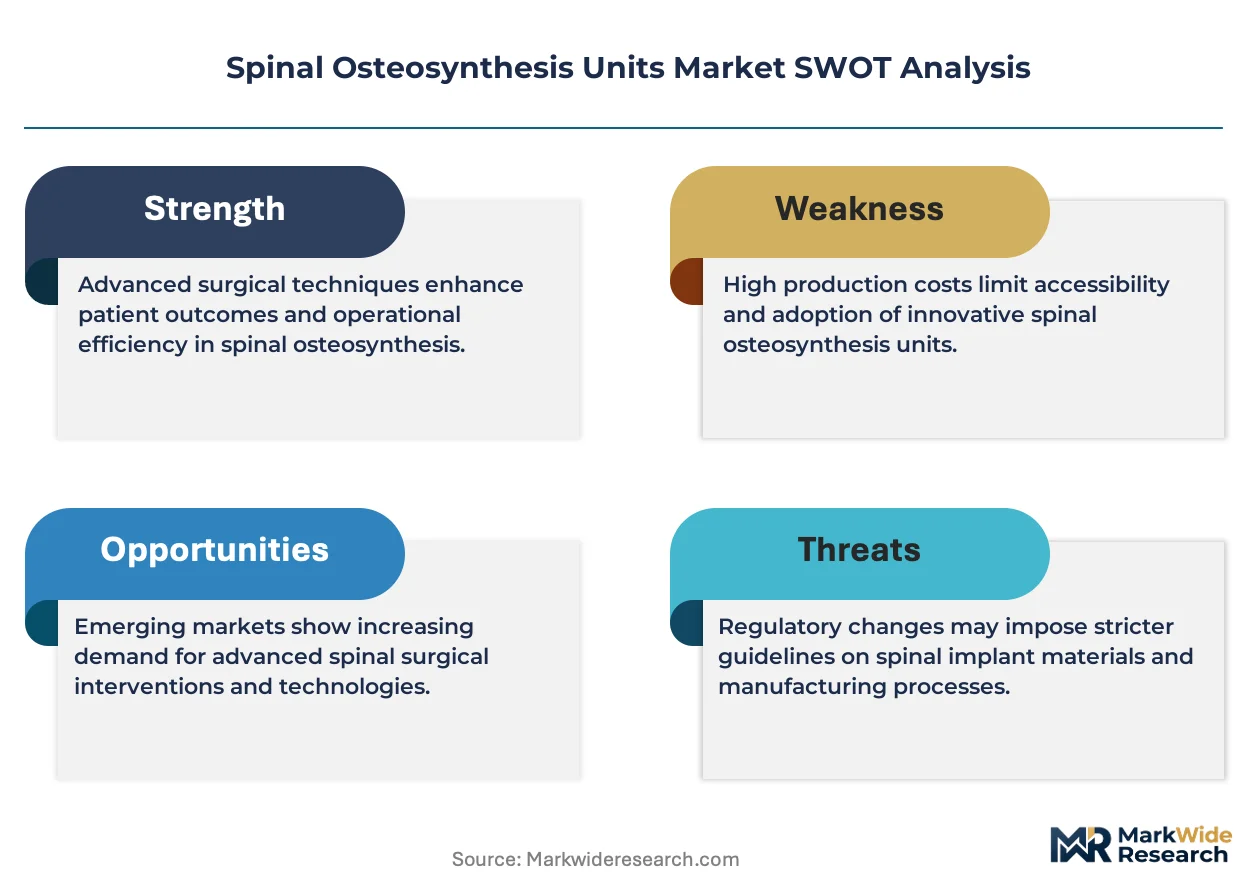
Robotic assistance is rewriting surgical economics by concentrating procedure value in capital equipment ecosystems rather than discrete implant sales, forcing hardware vendors to restructure revenue models around disposable attach rates and software subscriptions.
Growth Catalysts
- Aging demographics in Japan:The country's super-aged population generates sustained procedural volume for degenerative spine conditions, with METI incentives accelerating hospital robotics adoption.
- FDA 510(k) pathway efficiency:Substantial equivalence determinations compress commercialization timelines for titanium alloy fixation systems compared to PMA routes.
- Expandable interbody devices:These specialized constructs command premium positioning in complex deformity corrections through minimal access approaches.
Market Restraints
- Titanium alloy supply concentration:Primary sponge production concentrates in China and Russia, exposing manufacturers to geopolitical input volatility and export restriction risk.
- EU MDR clinical evidence demands:The regulation's expanded documentation requirements extend market access timelines by 18-24 months for novel fixation constructs.
- Motion-preserving disc arthroplasty:Cervical and lumbar artificial discs substitute fusion procedures in select indications, compressing addressable volume for traditional osteosynthesis.
Strategic Opportunities
- Brazil's underserved spine market:ANVISA regulatory harmonization with IMDRF standards creates streamlined entry for established manufacturers, with private hospital chains driving premium device uptake.
- Patient monitoring ecosystems:Hardware vendors can capture recurring revenue through post-operative surveillance services that blur the device-care boundary.
- AI-assisted preoperative planning:Convergence of machine learning segmentation with robotic navigation enables personalized screw trajectory optimization.
Industry Challenges
- Robotics technician scarcity:Hospital systems struggle to recruit and retain specialists capable of calibrating and troubleshooting surgical navigation platforms.
- ISO 13485 audit intensity:Notified body scrutiny of quality management systems has tightened, with non-conformances delaying supplier qualification for tenders.
- Legacy EMR integration:Surgical workflow software faces interoperability friction with established hospital information systems, complicating data capture for outcomes tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Osteosynthesis Units Market |
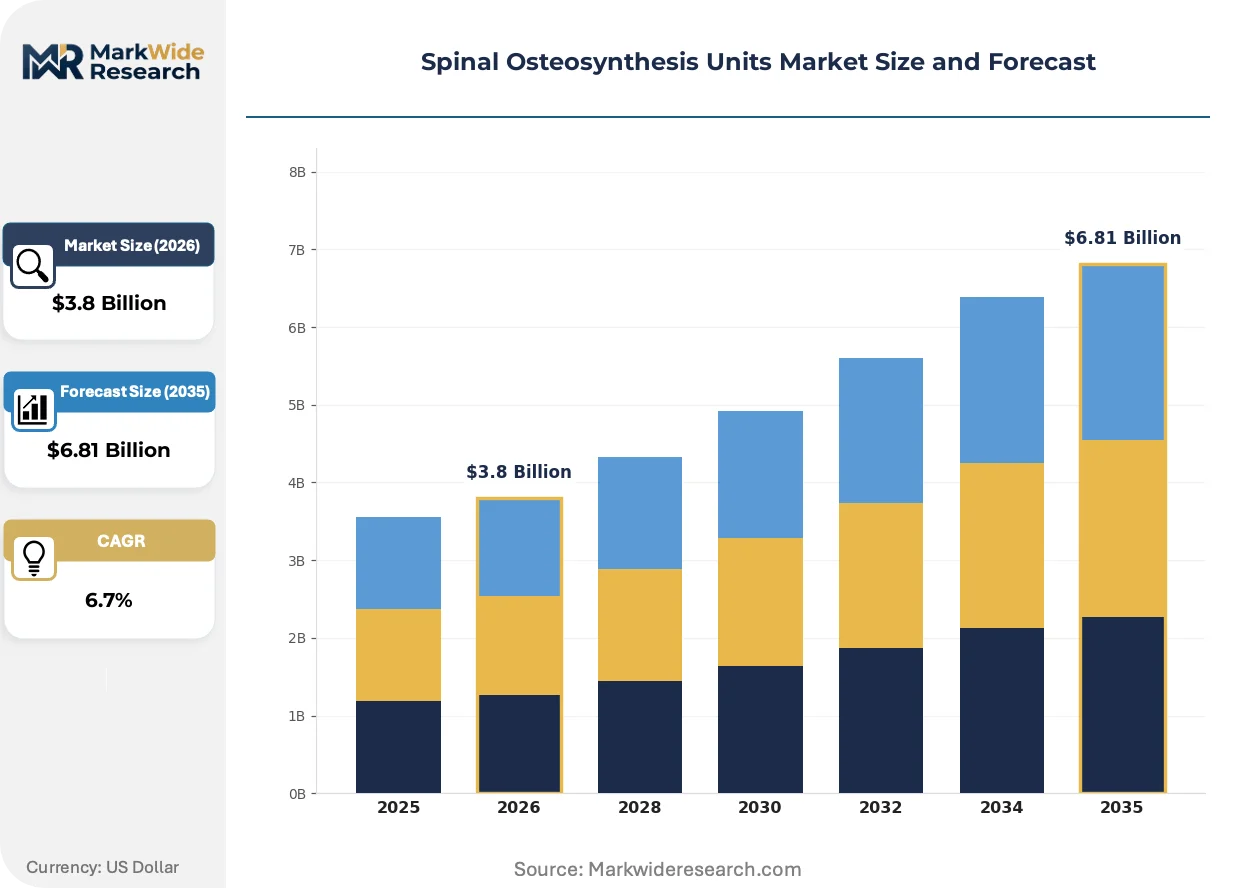
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
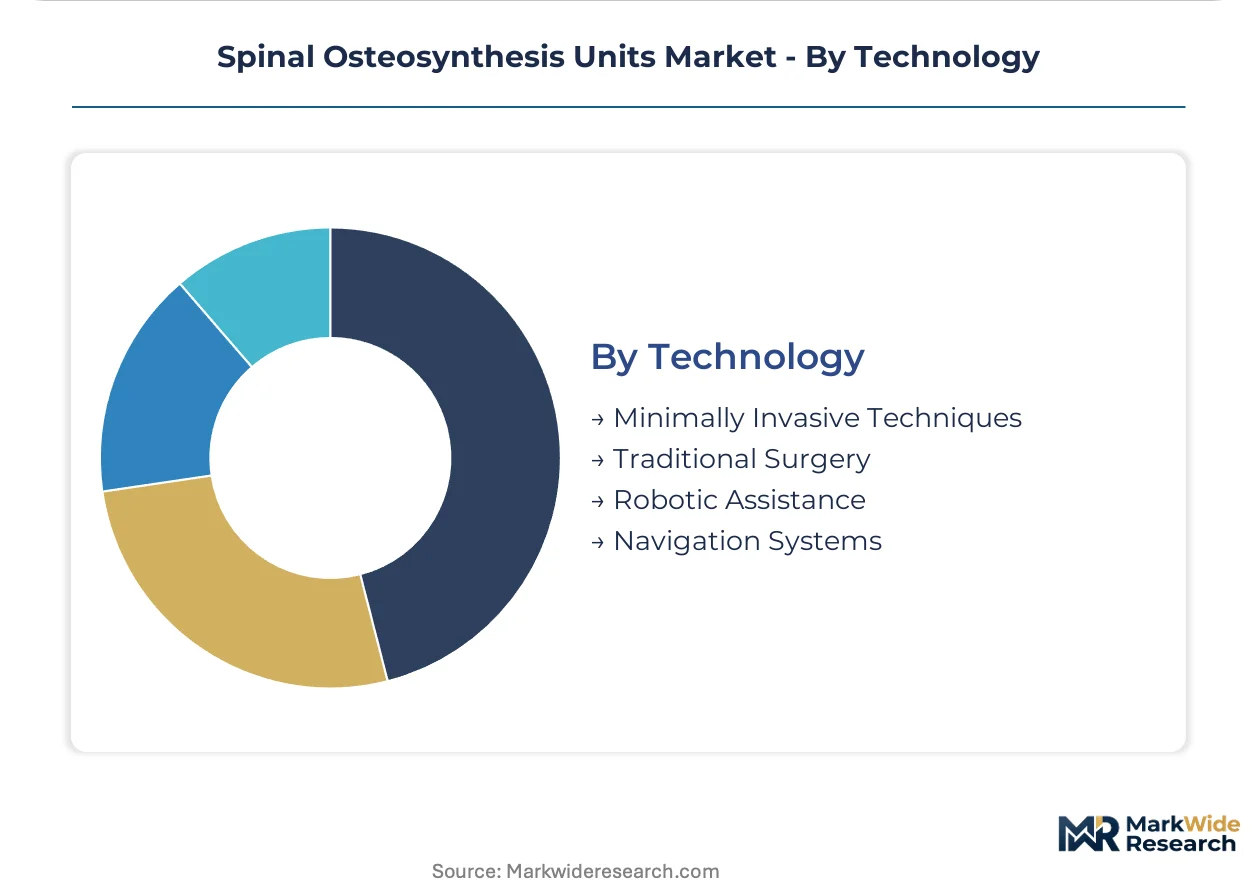
| Segmentation | Product Type: Fusion Devices, Non-Fusion Devices, Bone Spacers, Rods End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Outpatient Surgical Centers Material: Titanium, Stainless Steel, Polyetheretherketone, Carbon Fiber Technology: Minimally Invasive Techniques, Traditional Surgery, Robotic Assistance, Navigation Systems |
| Companies Covered | Medtronic, Johnson & Johnson, Stryker, Zimmer Biomet, NuVasive, Globus Medical, B. Braun, Orthofix, Alphatec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Osteosynthesis Units Market Strategic Shifts
Spinal osteosynthesis is undergoing platformization, where hardware placement becomes inseparable from software-defined outcomes, navigation accuracy, and longitudinal patient data capture.
Patient-specific 3D-printed titanium interbody cages are rewriting anatomical matching standards. These constructs integrate porous architectures that mimic trabecular bone stiffness. Academic medical centers in Germany and the United States are adopting these devices for complex revision cases. The technology is compressing revision rates and shifting competitive advantage toward manufacturers with captive additive manufacturing capabilities.
The EU Medical Device Regulation's post-market surveillance requirements are forcing systematic clinical follow-up infrastructure. Manufacturers must now maintain active implant registries and periodic safety update reporting. Small and mid-sized firms without dedicated regulatory affairs teams face disproportionate compliance burden, accelerating consolidation toward integrated spine platforms.
Hospital procurement committees are unbundling device selection from surgeon preference cards. Value analysis teams now dominate implant vendor selection, with standardization committees mandating limited SKU contracts across health systems. This behavioral shift is most visible in United States integrated delivery networks, where orthopedic service line administrators negotiate system-wide pricing tiers that override individual surgeon requests.
Spinal Osteosynthesis Units Market Segmentation
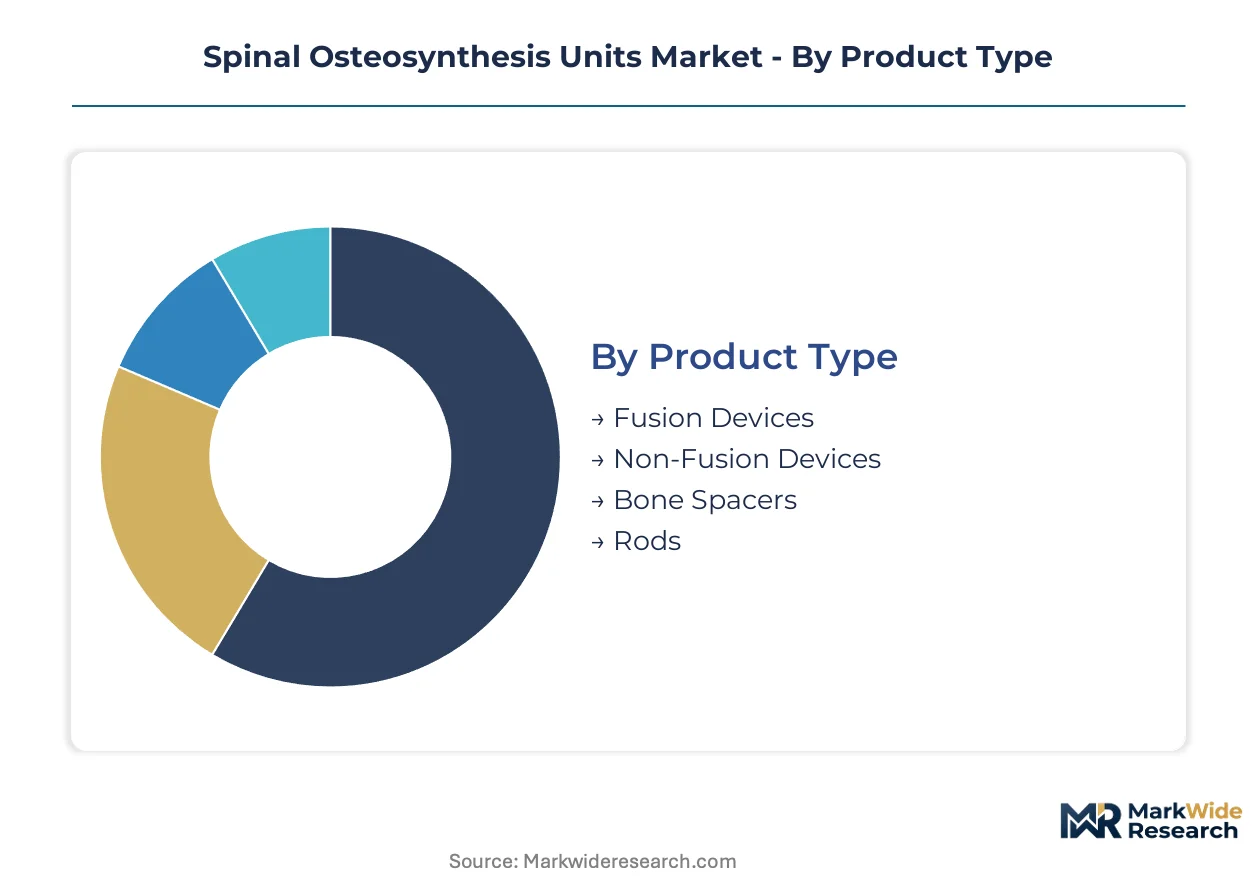
Spinal osteosynthesis units fragment across multiple technical and commercial axes that determine pricing power, regulatory pathway complexity, and procurement committee leverage. Manufacturers must align portfolio depth with specific hospital service line economics rather than pursuing undifferentiated coverage.
Product Type:
Structural fixation categories diverge sharply in reimbursement intensity and surgical training requirements, with fusion dominance now contested by motion-preserving alternatives.
- Fusion Devices:Rigid titanium alloy constructs incorporating pedicle screws, rods, and interbody cages achieve permanent vertebral segment immobilization until bony union completes. German spine centers and Japanese university hospitals drive procedural volume for degenerative indications, with bundled payment structures favoring standardized construct kits over modular component selection.
- Non-Fusion Devices:Dynamic stabilization systems and interspinous spacers preserve segmental motion through flexible tethering or distraction mechanics, appealing to younger patient cohorts seeking functional preservation. These systems command premium positioning in select European markets where motion-preserving alternatives gain surgeon acceptance ahead of United States adoption curves.
- Bone Spacers:Interbody cages manufactured from PEEK or titanium maintain disc space height and promote fusion mass formation.
- Rods:Longitudinal titanium or cobalt-chrome members connect screw anchors to distribute mechanical loads across multiple vertebral levels.
Fusion Devices lead on scale; Non-Fusion Devices lead on momentum.
End User:
Site-of-care economics reshape vendor engagement models, with capital equipment bundling now penetrating ambulatory settings previously served by implant-only transactions.
- Hospitals:Academic medical centers and community hospital systems concentrate high-complexity deformity and revision procedures, capturing robotics-assisted surgery platforms through capital lease arrangements. United States integrated delivery networks and German maximum-care hospitals dominate procurement volume, leveraging value analysis committees to extract system-wide pricing concessions.
- Orthopedic Clinics:Specialized spine practices perform selective decompressions and single-level fusions outside hospital walls, driving demand for streamlined instrument sets compatible with limited sterilization infrastructure. Brazil's private clinic chains and India's corporate hospital-affiliated centers represent emerging volume concentrations.
- Rehabilitation Centers:Post-acute facilities manage implant surveillance and physical therapy protocols.
- Outpatient Surgical Centers:Ambulatory settings capture migrating lumbar decompression and anterior cervical discectomy volumes.
Hospitals lead on scale; Outpatient Surgical Centers lead on momentum.
Material:
Biocompatibility profiles and radiolucency characteristics determine imaging compatibility and long-term implant survivability in weight-bearing spinal applications.
- Titanium:Ti-6Al-4V and commercially pure titanium grades dominate load-bearing applications through favorable strength-to-weight ratios and osseointegration capacity. Supply concentration in Chinese and Russian sponge production exposes manufacturers to export restriction risk, with Japanese and German fabricators maintaining strategic inventory buffers.
- Stainless Steel:316L surgical grade retains cost advantages in emerging markets where procurement committees prioritize acquisition expense over long-term corrosion resistance.
- Polyetheretherketone:Radiolucent polymer cages enable artifact-free postoperative imaging.
- Carbon Fiber:Composite-reinforced constructs offer modulus matching to native bone stiffness.
Titanium leads on scale; Polyetheretherketone leads on momentum.
Technology:
Surgical approach selection determines capital intensity, disposable attach rates, and the balance between surgeon autonomy and algorithmic guidance.
- Minimally Invasive Techniques:Tubular retractor systems and percutaneous screw placement reduce paraspinal muscle disruption, shortening hospital length-of-stay metrics that dominate United States bundled payment calculations. German and South Korean training programs now mandate MIS proficiency certification.
- Robotic Assistance:Navigation platforms concentrate margin pools through capital equipment placement and procedure-specific disposable instrument sales. METI incentives accelerate hospital adoption in Japan, while United States systems struggle with technician recruitment and retention.
- Traditional Surgery:Open approaches with direct visualization retain majority procedure volume.
- Navigation Systems:Optical and electromagnetic tracking enables real-time instrument localization.
Traditional Surgery leads on scale; Robotic Assistance leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan diverge in procurement intensity despite comparable procedural sophistication, with German spine centers standardizing construct kits under bundled payments while Japanese university hospitals accelerate robotics adoption through METI incentives.
United States
Integrated delivery networks concentrate high-complexity deformity volume, with value analysis committees overriding surgeon preference cards to mandate limited SKU contracts. FDA 510(k) substantial equivalence determinations compress commercialization timelines for titanium alloy fixation systems. The Cleveland Clinic and Mayo Clinic anchor robotics-assisted surgery adoption, deploying navigation platforms through capital lease arrangements that reshape vendor economics.
Germany
Maximum-care hospitals drive procedural volume for degenerative indications, with specialized spine centers commanding premium positioning for expandable interbody devices. EU MDR clinical evidence demands extend market access timelines by 18-24 months for novel fixation constructs. The Rhine-Ruhr and Bavarian medical clusters concentrate additive manufacturing capabilities for patient-specific 3D-printed titanium cages.
Japan
Super-aged demographics generate sustained volume for degenerative spine conditions, with university hospitals capturing motion-preserving alternative adoption ahead of other markets. METI incentives accelerate hospital robotics adoption, concentrating margin pools in capital equipment ecosystems. Tokyo and Osaka academic centers anchor training program mandates for minimally invasive surgery proficiency certification.
Brazil
Private hospital chains drive premium device uptake in an underserved spine market where procedural penetration lags demographic need. ANVISA regulatory harmonization with IMDRF standards creates streamlined entry for established manufacturers. São Paulo and Rio de Janeiro corporate hospital-affiliated centers concentrate ambulatory surgical migration for selective decompressions.
China
Domestic titanium sponge production concentrates supply chain gravity, exposing foreign manufacturers to export restriction risk while local fabricators build strategic inventory buffers. NMPA regulatory pathways emphasize clinical evidence portfolios for novel constructs. Beijing and Shanghai medical centers anchor robotics platform placement, though capital constraints in tier-two cities sustain traditional open procedure dominance.
Spinal Osteosynthesis Units Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated spine platforms capturing recurring revenue through patient monitoring ecosystems while component suppliers compete on manufacturing scale. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with captive robotics ecosystems, pure-play spine specialists commanding premium positioning in complex deformity cases, and regional fabricators serving emerging markets through cost-optimized construct kits. Competitive dynamics center on M&A consolidation toward integrated platforms and backward integration into titanium alloy supply.
Within the diversified conglomerate tier, Medtronic and Stryker occupy positions that exemplify platformization strategy, anchoring competitive stance through robotics-assisted surgical workflows and software-defined outcome capture. Globus Medical represents the pure-play specialist archetype, differentiating through focused portfolio depth in expandable interbody devices.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Stryker |
| Zimmer Biomet |
| NuVasive |
| Globus Medical |
| B. Braun |
| Orthofix |
| Alphatec |
| Others |
Value Chain & Pricing Dynamics
Hospital value analysis committees in United States integrated delivery networks are mandating limited SKU contracts that override surgeon preference cards, forcing manufacturers to consolidate implant portfolios and absorb cost compression through standardized construct kit pricing rather than modular component premiums.
Pricing Analysis
Capacity additions in Chinese titanium sponge production are reshaping price floors for raw material inputs, though Japanese and German fabricators maintain strategic inventory buffers that insulate premium-tier pricing. Pricing stratifies across premium robotic-integrated systems, standard navigation-enabled constructs, and economy open-surgery kits. Price differentiation hinges on FDA 510(k) clearance tier and capital equipment bundling intensity. Cost compression in standard fixation tiers is intensifying because Brazilian and Indian procurement committees prioritize acquisition expense over long-term corrosion resistance. Orthopedic clinics in emerging markets exhibit highest price sensitivity; academic medical centers in Germany and Japan show lowest.
Supply Chain Analysis
China's domestic content mandates for critical medical device components are reshaping sourcing patterns for foreign manufacturers seeking NMPA market access. Titanium sponge production concentrates in China and Russia, with Japanese fabricators drawing from Australian ore concentrates. Raw material dependencies span titanium alloys, polyetheretherketone polymer feedstock, and cobalt-chrome rod stock. Single-source vulnerability in Chinese sponge exports exposes manufacturers to geopolitical restriction risk. Distribution runs through hospital procurement committees and GPO contracts in developed markets, direct sales to private clinic chains in Brazil and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spinal osteosynthesis market functions as a stable compounder anchored by irreversible demographic aging in Japan and Germany that sustains procedural volume regardless of cyclical healthcare spending fluctuations.
For Market Incumbents: Cement platform dominance through captive robotics ecosystem integration and backward integration into titanium alloy supply. Motion-preserving disc arthroplasty substitution threatens fusion volume; defend through patient monitoring ecosystem lock-in that blurs device-care boundaries and captures recurring surveillance revenue. For New Entrants and Emerging Players: ANVISA regulatory harmonization with IMDRF standards in Brazil opens a window for streamlined entry into Latin America's most penetrable premium device market. Target São Paulo private hospital chains with cost-optimized construct kits; leverage direct sales bypassing GPO intermediaries as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play spine specialists commanding premium positioning in expandable interbody devices and patient-specific 3D-printed titanium cages. Five-to-ten year viability favors manufacturers with captive additive manufacturing capabilities and dedicated EU MDR regulatory affairs teams. Watch METI robotics adoption incentive extensions as the inflection signal for capital equipment ecosystem concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Platform Integration | Stryker and Medtronic concentrate margin pools through navigation platform placement and disposable attach rates. |
| Patient Monitoring Ecosystem Development | Hardware vendors capture recurring revenue through post-operative surveillance services that extend device-care boundaries. |
| Additive Manufacturing Capability Buildout | German and United States academic centers adopt patient-specific 3D-printed titanium cages for complex revision cases. |
| EU MDR Regulatory Affairs Investment | Clinical evidence portfolios extend market access timelines, favoring integrated spine platforms with dedicated compliance teams. |
| Brazil Direct Sales Channel Establishment | ANVISA harmonization enables streamlined entry for manufacturers targeting São Paulo private hospital chains. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down titanium alloy supply tracking forms the analytical core of this study. Primary interviews with spine surgeons, hospital value analysis committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and METI robotics adoption disclosures. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map procedure volume by technology type, material grade, and site-of-care economics across the projection horizon. Segmentation dimensions span fusion versus non-fusion construct categories, robotic-assisted versus traditional surgical approaches, titanium versus polyetheretherketone material platforms, and academic medical center versus ambulatory surgical center end-use settings. CAGRs derive from surgical volume elasticity to aging demographics and capital equipment replacement cycles. Forecast inputs incorporate bundled payment penetration rates and robotics technician labor availability constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or Chinese titanium export restriction scenarios. Forecasts reflect documented assumptions regarding procedural migration to outpatient settings and motion-preserving alternative substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Europe Otoscope Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Critical Care Devices Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Global Bone Screw System Market
Medical Devices
Antibiotic-Loaded Bone Cement Market