
 Spicy Dairy Products Market | 2026-2036
Spicy Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Spicy Dairy Products Market Intelligence
Food service operators are collapsing the distance between ethnic condiments and mainstream dairy aisles, pulling spicy cream cheese and pepper-laced yogurt into quick-service and fast-casual channels. Fonterra Cooperative Group Ltd. leverages its dairy ingredient platform to supply heat-stable milk proteins for industrial sauce applications. Nestle SA anchors retail penetration through chilled dairy portfolios that normalize capsaicin flavor profiles for mass-market consumers. Inner Mongolia Yili Industrial Group Co. Ltd. dominates Asia-Pacific production scale, converting regional chili consumption into packaged spicy yogurt formats.
Spicy dairy products denote milk-derived formulations infused with capsaicin-containing extracts, fermented chili pastes, or oleoresin blends, typically processed at pH ranges of 4.0–4.6 for cultured variants and standardized to Scoville-referenced heat units for batch consistency. These products function as flavor-intense condiments, cooking bases, and snacking components that bridge dairy nutrition with sensory heat delivery. Spicy cheese occupies the largest margin pool among product types, sustained by premium aged formats with embedded pepper flakes and smoke-dried chili rubs. Flavored yogurt represents the fastest-expanding application vector, as breakfast and snacking occasions absorb heat-forward dairy into daily routines. The sauces segment within application categories captures disproportionate food service volume, where jalapeño cream cheese and sriracha-infused spreads command line-item placement on commercial menus.
FDA standards for acidified and low-acid canned foods govern heat-processed spicy dairy sauces in the United States, while FSSAI labeling mandates and microbial load specifications shape product approval pathways for Indian manufacturers. EFSA Novel Food evaluations and EU hygiene regulations constrain capsaicin extract concentrations and dairy additive combinations across European markets. Stakeholders must monitor evolving thresholds for natural flavor claims and capsaicin tolerance limits as regulatory bodies reconcile traditional dairy frameworks with emerging heat-infused categories.
Market Dynamics
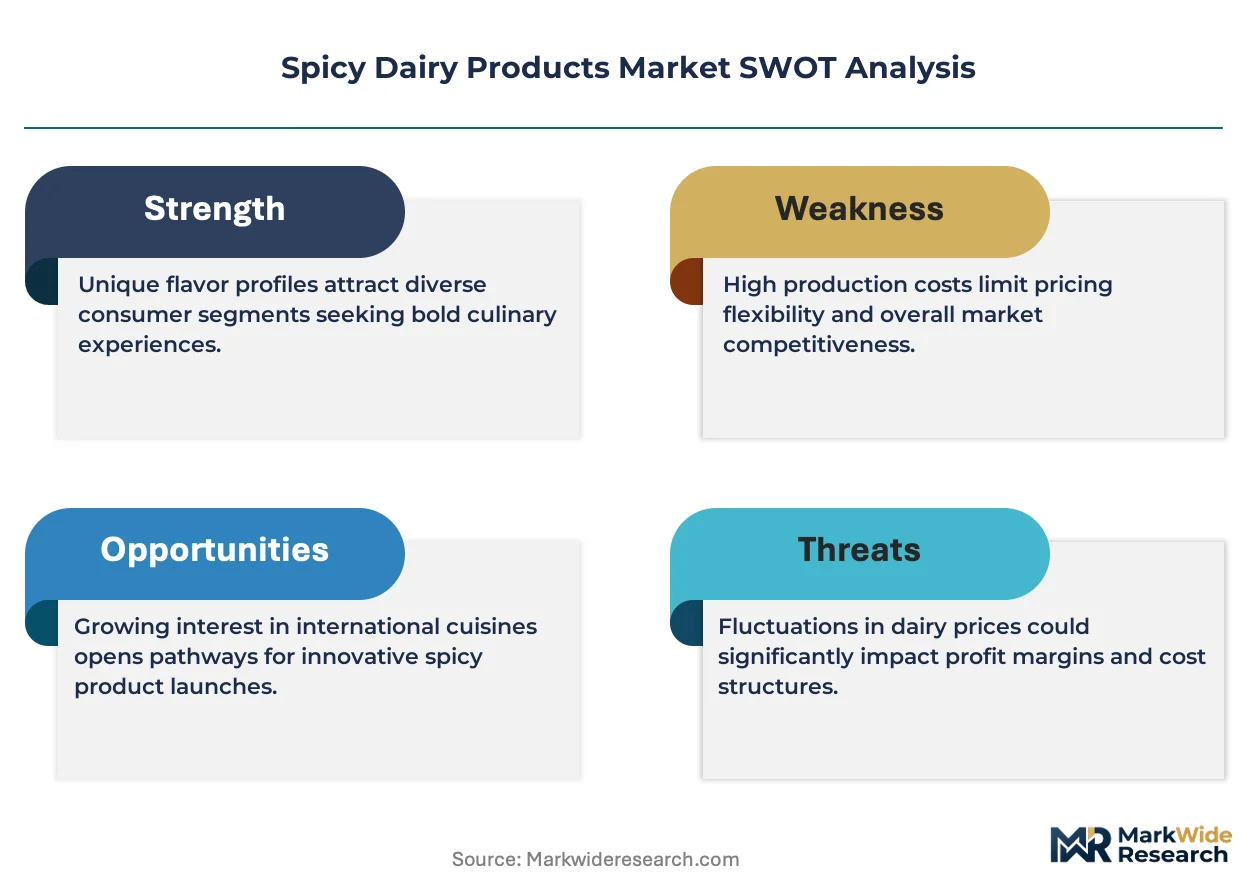
Capillary stabilization technology is restructuring competitive advantage in spicy dairy formulation, as manufacturers race to prevent capsaicin precipitation during shelf-life extension while maintaining clean-label positioning.
Growth Catalysts
- Capsaicin microencapsulation advances:Lipid-shell and cyclodextrin complexation methods now enable heat-stable infusion into high-pH dairy matrices, opening industrial sauce applications previously closed to capsaicin due to protein denaturation and fat separation.
- Quick-service menu expansion:Fast-casual chains in the United States and India are standardizing jalapeño cream cheese and sriracha yogurt as permanent line items rather than limited-time offers, creating predictable offtake for contract dairy processors.
- FSSAI streamlined approval pathways:India's 2023 amendment to proprietary food regulations reduced microbial testing timelines for fermented chili-dairy blends from 90 to 45 days, accelerating new product introductions for domestic manufacturers.
Market Restraints
- Chili oleoresin supply concentration:Over 70% of food-grade capsaicin extracts originate from concentrated processing clusters in India and China, exposing formulators to weather-driven harvest volatility and geopolitical trade friction.
- pH-heat incompatibility:Capsaicin's hydrophobicity creates insoluble complexes when combined with calcium-rich dairy above pH 5.2, forcing costly acidification or emulsifier additions that compromise clean-label claims.
- EFSA Novel Food evaluations:European manufacturers face 12-18 month assessment windows for new capsaicin extract sources or dairy additive combinations, delaying launch timelines relative to markets with mutual recognition agreements.
Strategic Opportunities
- African retail expansion:Urban supermarket growth in Nigeria and Kenya is creating first-mover openings for UHT spicy cheese spreads and chili-laced drinking yogurt, with local dairy cooperatives seeking international formulation partners.
- Precision fermentation-derived capsaicin:Biosynthetic production of non-pungent capsaicin analogues through microbial cell factories promises to decouple heat delivery from agricultural supply chains, pending regulatory acceptance.
- Direct-to-foodservice platforms:Specialized distributors are bypassing traditional retail consolidation by connecting artisanal spicy dairy producers directly to independent restaurants and ghost kitchen operators.
Industry Challenges
- Sensory panel calibration:Maintaining Scoville unit consistency across batch production requires trained human tasters and instrumental validation, creating bottlenecks as production scales beyond pilot volumes.
- Cross-contamination protocols:Shared dairy processing equipment demands rigorous CIP (clean-in-place) sequencing to prevent capsaicin residue carryover into conventional product runs, extending changeover downtime.
- Refrigerated last-mile infrastructure:Cold chain gaps in emerging markets limit spicy yogurt distribution to urban centers, constraining penetration into heat-aligned regional cuisines in rural areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spicy Dairy Products Market |
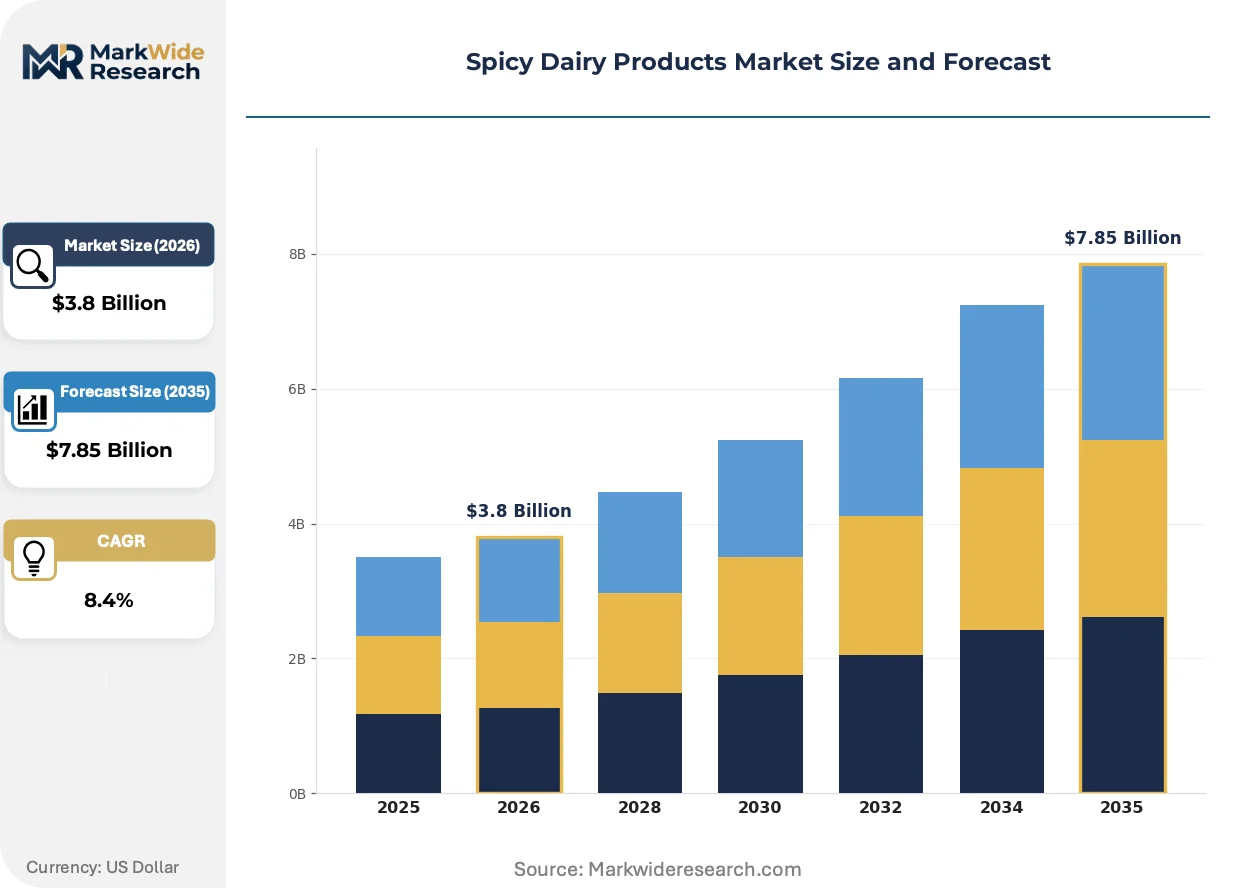
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spicy Cheese, Flavored Yogurt, Hot Sauce, Jalapeño Cream Cheese Application: Snacks, Dishes, Sauces, Spreads Packaging Type: Containers, Pouches, Tubs, Bottles End User: Restaurants, Households, Food Service, Retail Outlets |
| Companies Covered | Arla Foods amba, Fonterra Cooperative Group Ltd., Nestle SA, Inner Mongolia Yili Industrial Group Co. Ltd., Saputo Inc., Danone SA, China Mengniu Dairy Co. Ltd., Chobani, LLC, Groupe Lactalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spicy Dairy Products Market Strategic Shifts & Innovations
Heat-infused dairy is migrating from ethnic specialty positioning toward functional snacking and meal-component categories, driven by formulation advances that reconcile capsaicin bioactivity with extended shelf stability.
Microencapsulation via spray-dried whey protein matrices is fragmenting the traditional tradeoff between heat intensity and processing tolerance. Industrial sauce manufacturers in the United States are adopting lipid-shell technologies at accelerating rates, compressing the performance gap between fresh and shelf-stable spicy cream bases. This capability expansion is enabling regional dairy processors to supply national quick-service chains without building dedicated clean-room facilities.
EFSA's 2024 guidance on novel capsaicin extract specifications is tightening concentration thresholds for dairy additive combinations across European markets. Manufacturers must now submit extended toxicological dossiers for oleoresin sources exceeding established Scoville-equivalent baselines, extending approval timelines. German and Dutch dairy cooperatives are responding by investing in in-house biosynthetic research to bypass agricultural extract dependency.
Breakfast and snacking occasions are absorbing heat-forward yogurt into daily routines at the expense of traditional sweet-fruit positioning. Indian consumers in tier-2 cities are shifting from occasional festive purchase to weekly stock-up patterns for chili-laced dahi variants. This behavioral pivot is compressing product development cycles, as manufacturers abandon seasonal limited-edition formats in favor of permanent SKU expansion.
Spicy Dairy Products Market Segmentation

Heat intensity, shelf stability, and usage occasion create distinct competitive arenas across spicy dairy categories. Substitution threats from plant-based alternatives and ethnic condiments vary sharply by product format, reshaping where manufacturers concentrate R&D investment.
Product Type:
Plant-based cheese analogues and fermented vegetable pastes exert the strongest substitution pressure on aged formats, while fresh cultured products defend position through probiotic positioning and breakfast occasion capture.
- Spicy Cheese:Aged and fresh curd formulations embed capsain through surface rubs, internal flake distribution, or brine infusion, with calcium-protein matrices requiring pH modulation below 5.0 to prevent oleoresin precipitation. Demand concentrates in United States specialty retail and Indian urban modern trade, where premium positioning justifies price multiples over conventional cheese. FDA standards for acidified foods and FSSAI microbial specifications govern approval pathways in these markets.
- Flavored Yogurt:Fermented milk bases at pH 4.0–4.6 incorporate chili pastes, oleoresin emulsions, or crushed pepper suspensions, with viscosity stabilization through modified starch or clean-label pectin systems. Indian tier-2 cities and United States fast-casual breakfast channels absorb volume fastest, converting occasional ethnic purchase into weekly stock-up behavior.
- Hot Sauce:Acidified dairy emulsions or whey-based carriers deliver capsaicin heat as pourable condiments, competing directly with vinegar-based vegetable sauces on price and heat consistency.
- Jalapeño Cream Cheese:High-fat fresh cheese matrices suspend pepper particulates and oleoresin for spreadable texture, dominating United States bagel chains and deli channels.
Spicy Cheese anchors the volume base while Flavored Yogurt gains share at the steepest rate.
Application:
Food service procurement specifications drive margin differentiation across usage occasions, with commercial kitchen requirements for heat stability and portion control separating premium from commodity supply tiers.
- Snacks:Portable formats include cheese sticks with embedded pepper flakes, yogurt cups with chili swirl layers, and single-serve spread portions for on-premise consumption. United States convenience retail and Indian airport lounge channels concentrate demand, where impulse purchase triggers override price sensitivity.
- Dishes:Cooking bases encompass paneer marinated in chili-yogurt blends, cheese sauces for pasta and casserole applications, and cultured cream reductions for curry enrichment. Indian home kitchens and United States meal-kit services drive formulation complexity, requiring freeze-thaw stability and extended simmer tolerance.
- Sauces:Industrial and food service formats supply jalapeño cheese sauce for nacho applications, sriracha cream for burger assembly, and chili-laced béchamel for frozen entrée manufacturing.
- Spreads:Retail and deli channels stock tub formats for sandwich construction, cracker pairing, and appetizer plating, with texture specifications varying by climate zone for spreadability at refrigerated temperatures.
Dishes command the highest per-kilogram value realization while Snacks expand most quickly through convenience channel penetration.
Packaging Type:
Cold chain infrastructure maturity and retail format density determine viable packaging economics, with urban supermarket penetration enabling premium formats unavailable in traditional trade.
- Containers:Rigid plastic or glass jars with wide mouths accommodate spoonable yogurt and chunky cheese spreads, dominating Indian modern retail and United States club store channels where multi-serve units reduce per-gram packaging cost.
- Pouches:Flexible laminated films with spout or tear-notch closures deliver squeezeable sauces and drinkable yogurt, penetrating Nigerian and Kenyan supermarket growth corridors where refrigeration space constraints favor ambient-stable formats.
- Tubs:Injection-molded polypropylene with tamper-evident lidding dominates fresh cheese and thick yogurt segments across United States deli counters and Indian dairy cooperatives.
- Bottles:PET or HDPE formats with precision dispensing closures serve pourable hot sauces and cultured cream dressings, concentrated in United States mass retail and food service distributor inventories.
Containers capture the largest installed base while Pouches climb the fastest through emerging market retail expansion.
End User:
Procurement scale and specification stringency fragment the customer base, with national chain contracts demanding batch traceability and sensory consistency unavailable to artisanal suppliers.
- Restaurants:Independent and chain operators specify Scoville-calibrated heat levels, portion-controlled formats, and HACCP documentation for liability coverage. United States fast-casual chains and Indian quick-service pizza networks standardize jalapeño cream cheese and chili-laced paneer as permanent menu items.
- Households:Retail purchasers select formats for home cooking, snacking, and entertaining occasions, with Indian tier-2 city consumers shifting from festive to weekly purchase patterns for spicy dahi variants.
- Food Service:Institutional caterers, airline kitchens, and corporate dining contractors procure industrial-scale units with extended shelf life and thaw-stable performance specifications.
- Retail Outlets:Supermarkets, convenience stores, and specialty grocers curate assortments by demographic targeting, with United States natural channel retailers demanding clean-label fermentation protocols and EFSA-compliant capsaicin sourcing documentation for European import lines.
Restaurants anchor procurement volume while Households demonstrate the steepest expansion trajectory through modern trade penetration.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian chili oleoresin processors supply capsaicin extracts to United States sauce manufacturers and European dairy cooperatives, creating a trade corridor that concentrates formulation expertise near raw material sources while consumption clusters in developed cold-chain markets.
United States
Fast-casual chains standardize jalapeño cream cheese and sriracha yogurt as permanent menu items, converting limited-time novelty into predictable procurement. FDA acidified food standards govern heat-processed spicy dairy sauces, mandating pH monitoring and thermal processing documentation. Wisconsin and California dairy processing clusters host contract manufacturers supplying national quick-service networks with Scoville-calibrated heat-stable formats.
India
Tier-2 city consumers shift from festive to weekly purchase patterns for chili-laced dahi variants, compressing product development cycles toward permanent SKU expansion. FSSAI's 2023 proprietary food regulation amendment reduced microbial testing timelines from 90 to 45 days for fermented chili-dairy blends. Gujarat and Maharashtra dairy cooperatives convert regional chili consumption into packaged spicy yogurt formats for modern retail penetration.
Germany
Dutch and German dairy cooperatives invest in biosynthetic capsaicin research to bypass agricultural extract dependency and EFSA novel food evaluation delays. EFSA's 2024 guidance tightened concentration thresholds for dairy additive combinations, extending toxicological dossier requirements. Bavaria-based ingredient suppliers develop precision fermentation-derived capsaicin analogues pending regulatory acceptance.
China
Inner Mongolia Yili Industrial Group dominates Asia-Pacific production scale, converting regional chili consumption into packaged formats for domestic and export markets. SAMR dairy additive regulations and GB standards for fermented milk products shape capsaicin inclusion thresholds and labeling requirements. Yangtze River Delta processing corridors concentrate UHT spicy cheese spread manufacturing for urban supermarket expansion.
Nigeria
Urban supermarket growth in Lagos and Abuja creates first-mover openings for UHT spicy cheese spreads and chili-laced drinking yogurt, with local dairy cooperatives seeking international formulation partners. The country's national food safety authority maintains evolving standards for dairy-chili blends as modern trade penetration accelerates. Flexible pouch packaging dominates distribution where refrigeration space constraints favor ambient-stable formats.
Spicy Dairy Products Market Key Industry Players
Listed leaders compete with private specialists across scale and specialization dimensions, creating a tiered structure where multinational dairy platforms anchor volume while regional cooperatives defend margin through ethnic format expertise. Strategic archetypes include diversified dairy conglomerates with chilled portfolio depth, cooperative-owned processors with ingredient supply leverage, and emerging-market specialists converting local consumption patterns into packaged formats. Dominant competitive moves center on capsaicin stabilization technology licensing and direct-to-foodservice distribution platform construction.
Within the diversified dairy conglomerate tier, Nestle SA and Danone SA exemplify multinational platform strategies that normalize capsaicin flavor profiles through mass-market chilled portfolio penetration. Fonterra Cooperative Group Ltd. occupies a distinct position as a cooperative-owned ingredient supplier leveraging milk protein platforms for industrial sauce applications. Inner Mongolia Yili Industrial Group Co. Ltd. represents emerging-market scale specialists converting regional chili-dairy traditions into packaged formats for Asia-Pacific expansion.
| Leading Market Players |
|---|
| Arla Foods amba |
| Fonterra Cooperative Group Ltd. |
| Nestle SA |
| Inner Mongolia Yili Industrial Group Co. Ltd. |
| Saputo Inc. |
| Danone SA |
| China Mengniu Dairy Co. Ltd. |
| Chobani, LLC |
| Groupe Lactalis |
| Others |
Cost & Logistics Intelligence
FDA acidified food standards gate both supplier qualification and price differentiation in United States spicy dairy markets, mandating pH monitoring and thermal processing documentation that separates certified contract manufacturers from uncertified commodity processors. FSSAI microbial specifications in India create parallel tiering, where reduced testing timelines under 2023 amendments reward compliant domestic manufacturers with faster product cycles and pricing power over import-dependent competitors.
Pricing Analysis
Prior-generation capsaicin stabilization via acidification and emulsifier addition now trades at commodity margins, while current-generation lipid-shell microencapsulation commands premium positioning, and next-generation biosynthetic capsaicin analogues await regulatory acceptance to reset price floors. Three-tier pricing structure across premium aged cheese with embedded pepper flakes, standard fresh curd formats, and economy UHT spreads separates buyers by certification grade and cold-chain access. Pricing pressure stems from chili oleoresin harvest volatility concentrated in Indian and Chinese processing clusters. Food service procurement offices exhibit lowest price sensitivity due to menu standardization requirements, while emerging market retail purchasers face highest elasticity as ambient-stable formats compete with traditional condiments.
Supply Chain Analysis
Gujarat and Maharashtra dairy cooperative processing clusters in India function as the dominant chokepoint for fermented chili-dairy blend supply, converting regional chili consumption into packaged formats for domestic modern retail and export sauce manufacturing. Raw material dependencies center on chili oleoresin extracts, heat-stable milk protein isolates, and modified starch or pectin viscosity systems. Supply chain risk concentrates in weather-driven agricultural volatility across Indian oleoresin harvests and geopolitical friction affecting Chinese extract exports. Distribution runs through cold-chain dependent chilled dairy networks in developed markets and ambient-stable UHT formats via flexible pouch packaging in emerging African and Southeast Asian corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spicy dairy market fragmentation creates multiple specialization niches as food service procurement specifications diverge from retail clean-label demands, with quick-service chains standardizing heat-calibrated formats while natural channel retailers demand fermentation protocol transparency.
For Market Incumbents: Fortify supply security through backward integration into Indian oleoresin processing or captive chili sourcing partnerships, insulating margin from agricultural volatility. Nestle SA and Danone SA should accelerate in-house biosynthetic capsaicin research to bypass EFSA novel food evaluation delays threatening European portfolio expansion. Capacity concentration in Wisconsin and California dairy clusters anchors United States quick-service contracts through Scoville-calibrated batch consistency. For New Entrants and Emerging Players: Direct-to-foodservice platform infrastructure represents the most penetrable service-layer gap, as incumbent distributors under-serve independent restaurants and ghost kitchen operators with artisanal format flexibility. Nigerian and Kenyan urban supermarket expansion offers white-space entry for UHT spicy cheese spreads and chili-laced drinking yogurt via local dairy cooperative partnerships. Precision fermentation-derived capsaicin positioning creates differentiation pending regulatory acceptance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional dairy cooperatives in India and Southeast Asia holding ethnic format expertise but lacking international distribution scale. Five-to-ten year viability hinges on capsaicin stabilization technology licensing revenue and food service contract renewal rates. Monitor EFSA guidance evolution on biosynthetic capsaicin thresholds as inflection indicator for European manufacturing asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Capsaicin Microencapsulation Licensing | Fonterra Cooperative Group Ltd. supplies heat-stable milk proteins to industrial sauce manufacturers seeking clean-label positioning. |
| Direct-to-Foodservice Platform Launch | Specialized distributors connect artisanal spicy dairy producers to ghost kitchen operators bypassing retail consolidation. |
| Precision Fermentation R&D Partnership | German and Dutch dairy cooperatives invest in biosynthetic capsaicin to bypass Indian and Chinese agricultural extract dependency. |
| African Retail Format Expansion | UHT spicy cheese spreads in flexible pouches penetrate Nigerian and Kenyan supermarkets where refrigeration constraints favor ambient stability. |
| FSSAI Compliance Certification Investment | Domestic Indian manufacturers leverage reduced microbial testing timelines to accelerate new product introductions versus import competitors. |
Research Approach
A spread of perspectives from dairy processing plant managers, quick-service chain procurement officers, FSSAI regulatory affairs specialists, and chili oleoresin extraction facility operators converged on the working assumptions for supply concentration and pricing tier boundaries. Primary interview data combined with secondary validation from FDA acidified food filings, FSSAI proprietary food regulation amendments, EFSA novel food evaluation databases, and customs trade records for chili extract imports. Bottom-up volume modeling across product type, application, packaging format, and end user segments triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include heat intensity tier, shelf stability requirement, usage occasion, and regional cold-chain infrastructure maturity across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessments for breakfast occasion capture and food service menu standardization. Industry-specific forecast inputs encompass Scoville unit calibration consistency rates and capsaicin microencapsulation technology adoption curves.
Forecasts assume regulatory continuity in FDA acidified food standards, FSSAI proprietary food frameworks, and EFSA novel food evaluation protocols; material policy shifts would require re-modeling supply qualification timelines and price tier boundaries. Practitioners should keep alternative scenarios live as biosynthetic capsaicin regulatory acceptance and Indian oleoresin harvest volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Condensed Whey Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
China Milk Protein Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Lactic Butter Market
Dairy Products
Global Dairy Cream Market
Dairy Products
North America Yogurt Market
Dairy Products
Emmental Cheese Market