
 Asia-Pacific Flavored Milk Market | 2026-2036
Asia-Pacific Flavored Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Flavored Milk Market Outlook
Plant-based protein isolates is broadening formulation options for lactose-free flavored milk variants across Southeast Asian markets. China Mengniu Dairy Co. Ltd. leverages its Inner Mongolia raw milk base to anchor premium UHT flavored milk supply chains. Inner Mongolia Yili Industrial Group Co. Ltd. dominates refrigerated distribution networks through direct-store-delivery systems in China's northern provinces. Gujarat Co-operative Milk Marketing Federation Ltd. (Amul) competes on ultra-low price points via its farmer-cooperative procurement model.
Asia-Pacific flavored milk denotes heat-treated dairy beverages incorporating sweeteners, natural or artificial flavoring agents, and stabilizers, typically processed through ultra-high-temperature treatment or pasteurization to achieve shelf stability or refrigerated durability. Chocolate formulations command the largest volume share due to entrenched consumer preference across all age cohorts, while tetra pack packaging captures margin pools through extended shelf life and reduced cold-chain dependency. Online retailers represent the fastest-growing distribution channel as last-mile delivery infrastructure matures in India's metropolitan corridors and Indonesia's Java-based urban clusters.
FSSAI's dairy fortification guidelines in India and China's GB 25190 national food safety standards govern protein content claims and additive permissibility across the region. Australia's FSANZ nutrition labeling requirements and Japan's JIS packaging material standards further segment compliance obligations by destination market. Stakeholders must monitor evolving sugar taxation proposals in Thailand, Malaysia, and the Philippines that threaten to recalibrate formulation economics for sweetened dairy beverages.
Market Dynamics
China's SAMR dairy labeling standards and Australia's FSANZ fortification rules are forcing simultaneous reformulation across heat-treated dairy beverages, compressing product development timelines while creating compliance-driven segmentation between shelf-stable and refrigerated variants.
Growth Catalysts
- FSSAI dairy fortification guidelines:India's mandatory micronutrient enrichment mandates drive institutional procurement volumes through school nutrition programs in Uttar Pradesh, Madhya Pradesh, and Rajasthan.
- Plant-based protein isolates:Lactose-free formulation options broaden addressable consumer bases across Southeast Asian markets with rising dairy intolerance prevalence.
- Cold-chain infrastructure penetration:Direct-store-delivery systems expand refrigerated flavored milk reach into India's tier-two cities, unlocking new consumption occasions.
Market Restraints
- Raw milk input volatility:Inner Mongolia's seasonal production fluctuations constrain premium UHT supply chain stability for northern China processors.
- Sugar taxation proposals:Thailand, Malaysia, and the Philippines threaten recalibration of sweetened dairy beverage economics through excise frameworks under legislative review.
- GB 25190 additive restrictions:China's national food safety standards limit permissibility of certain stabilizers and artificial flavoring agents, constraining formulation flexibility.
Strategic Opportunities
- Last-mile delivery infrastructure:Online retailers capture fastest-growing distribution channel share in India's metropolitan corridors and Indonesia's Java-based urban clusters.
- Farmer-cooperative procurement models:Ultra-low price point positioning through Gujarat's cooperative structure offers replicable templates for Vietnam and Indonesia market entry.
- JIS packaging material compliance:Japan's standards for aseptic carton barriers create premium export positioning for tetra pack manufacturers meeting dual FSANZ-JIS certification.
Industry Challenges
- Refrigerated distribution network complexity:Temperature-controlled logistics requirements in tropical Southeast Asian climates demand capex-heavy cold-chain investments that compress margins.
- Dual certification timelines:Simultaneous FSSAI and SAMR compliance documentation creates product launch delays for pan-Asia-Pacific portfolio strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flavored Milk Market |
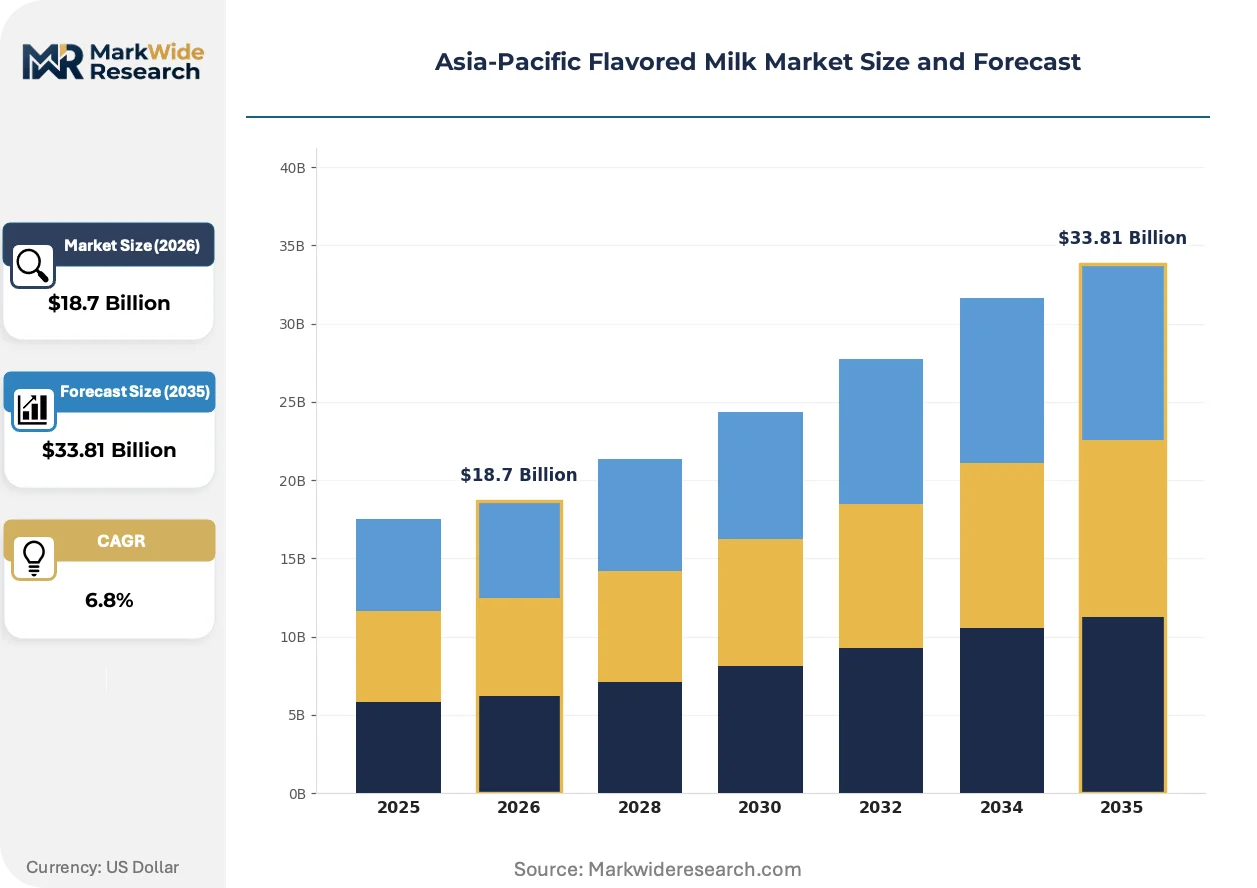
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Strawberry, Vanilla, Others End User: Children, Teenagers, Adults, Seniors Packaging Type: Bottles, Tetra Packs, Cartons, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores |
| Companies Covered | China Mengniu Dairy Co. Ltd., Inner Mongolia Yili Industrial Group Co. Ltd., Gujarat Co-operative Milk Marketing Federation Ltd. (Amul), Nestlé S.A., Danone S.A., Saputo Inc., Hershey's, Meiji Holdings Co. Ltd., Lactalis Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flavored Milk Market Strategic Shifts
Formulation science and packaging engineering are converging to reshape competitive positioning across shelf-stable and chilled flavored milk segments, with regulatory compliance emerging as a primary innovation driver rather than constraint.
Aseptic carton barrier technology is modularizing product architecture across the Asia-Pacific flavored milk landscape. Inner Mongolia processors deploy multi-layer polymer laminates to extend shelf life without cold-chain dependency. This modularizing capability enables simultaneous premium positioning in China's northern provinces and export-grade compliance for Australian FSANZ markets.
China's SAMR enforcement of GB 25190 protein content claims is compressing formulation tolerance bands for heat-treated dairy beverages. Industrial consequence manifests in accelerated R&D cycles as manufacturers validate amino acid profiles against label declarations. Refrigerated flavored milk segments in Shanghai and Beijing absorb highest compliance costs through third-party laboratory verification protocols.
Chocolate flavor preference concentration across all age cohorts is fragmenting into occasion-specific sub-segments. School nutrition programs in India and Vietnam prioritize portion-controlled sachets over family-size tetra packs. This behavioral pivot concentrates volume share in institutional procurement channels while metropolitan convenience retail shifts toward single-serve premium variants in Jakarta and Ho Chi Minh City.
Asia-Pacific Flavored Milk Market Segmentation
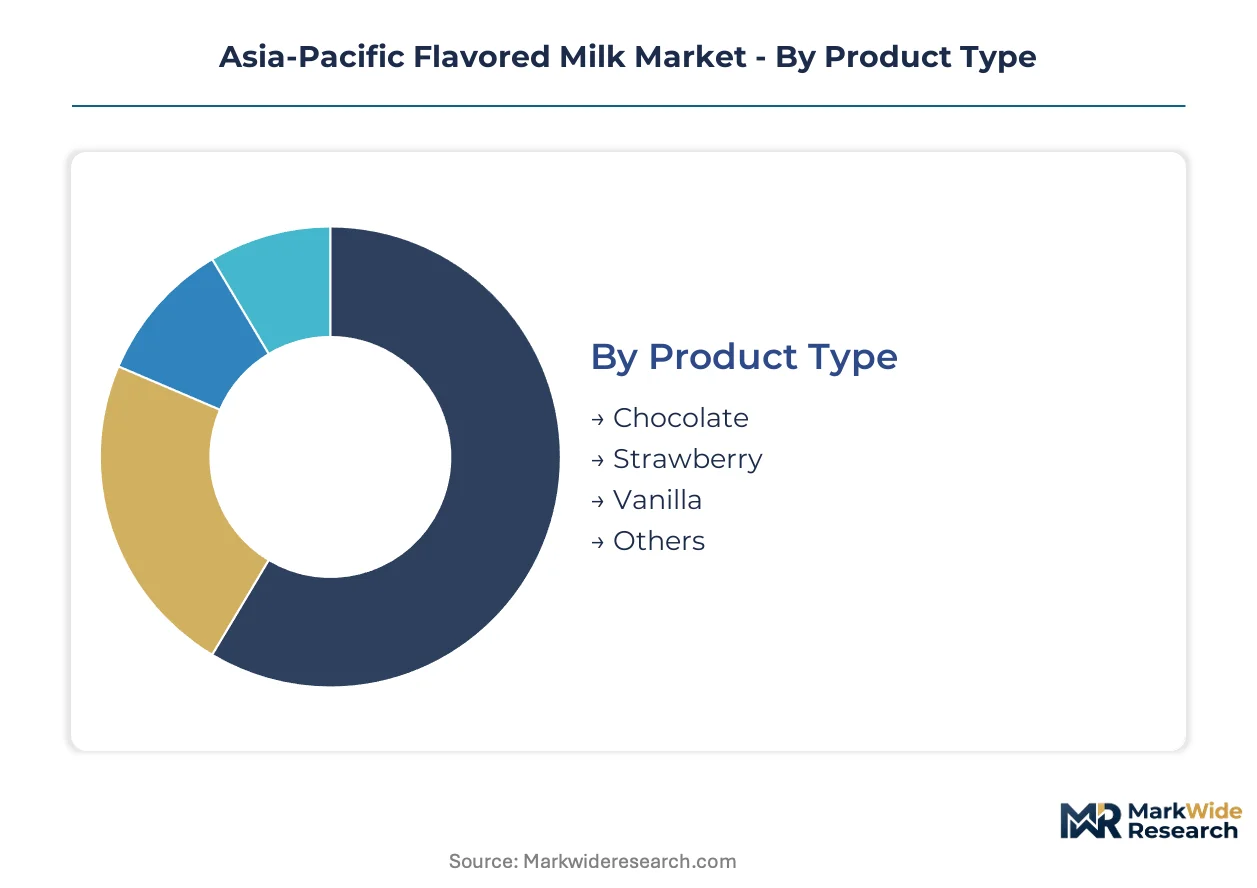
Flavored milk segmentation across Asia-Pacific reflects divergent capital requirements across manufacturing, cold-chain logistics, and retail infrastructure. Product formulation choices cascade through packaging technology decisions and distribution network investments, creating distinct margin profiles by segment combination.
Product Type:
Chocolate formulations demand the heaviest upfront investment in cocoa powder supply contracts and flavor stability R&D, while vanilla and strawberry variants require less specialized ingredient sourcing.
- Chocolate:Heat-treated dairy beverages incorporating cocoa powder and stabilizers achieve shelf stability through UHT processing. School nutrition programs in Uttar Pradesh and Madhya Pradesh concentrate procurement volumes here, driven by entrenched preference across all age cohorts and FSSAI fortification compliance requirements.
- Strawberry:Fruit-flavored variants utilize natural or artificial strawberry flavoring agents with color additives requiring GB 25190 additive permissibility verification. Demand clusters in Indonesia's Java-based urban clusters where metropolitan convenience retail favors single-serve premium variants.
- Vanilla:Classic flavor profile with lower ingredient complexity and broader formulation tolerance bands.
- Others:Emerging flavors including mango, coffee, and taro targeting niche consumption occasions in Southeast Asian markets.
Most installed capacity flows through Chocolate. Expansion is steepest in Others.
End User:
Children and teenagers generate the highest per-capita consumption frequency, though adults and seniors command premium pricing through functional fortification positioning.
- Children:Institutional procurement through school nutrition programs drives volume concentration. Portion-controlled sachets dominate in India and Vietnam, with FSSAI micronutrient enrichment mandates shaping product specifications.
- Teenagers:Convenience-oriented consumption patterns favor single-serve bottles and tetra packs in metropolitan corridors. Online retailers capture fastest-growing channel share for this cohort in Jakarta and Ho Chi Minh City.
- Adults:Functional positioning around protein content and reduced sugar formulations.
- Seniors:Lactose-free variants utilizing plant-based protein isolates address dairy intolerance prevalence.
Volume concentrates in Children. Premium pricing potential sits with Seniors.
Packaging Type:
Tetra packs and aseptic cartons require the steepest capital deployment in multi-layer polymer laminate technology, while pouches offer lowest barrier investment entry points.
- Bottles:PET and HDPE formats suit refrigerated distribution networks with shorter shelf life requirements. Direct-store-delivery systems in China's northern provinces favor this format for premium positioning.
- Tetra Packs:Multi-layer aseptic cartons extend shelf life without cold-chain dependency. Inner Mongolia processors deploy this technology for simultaneous domestic premium positioning and Australian FSANZ export compliance.
- Cartons:Gable-top refrigerated formats with lower barrier specifications than tetra packs.
- Pouches:Flexible packaging with minimal material cost, dominant in institutional sachet programs.
Margin pools concentrate in Tetra Packs. Volume throughput peaks in Pouches.
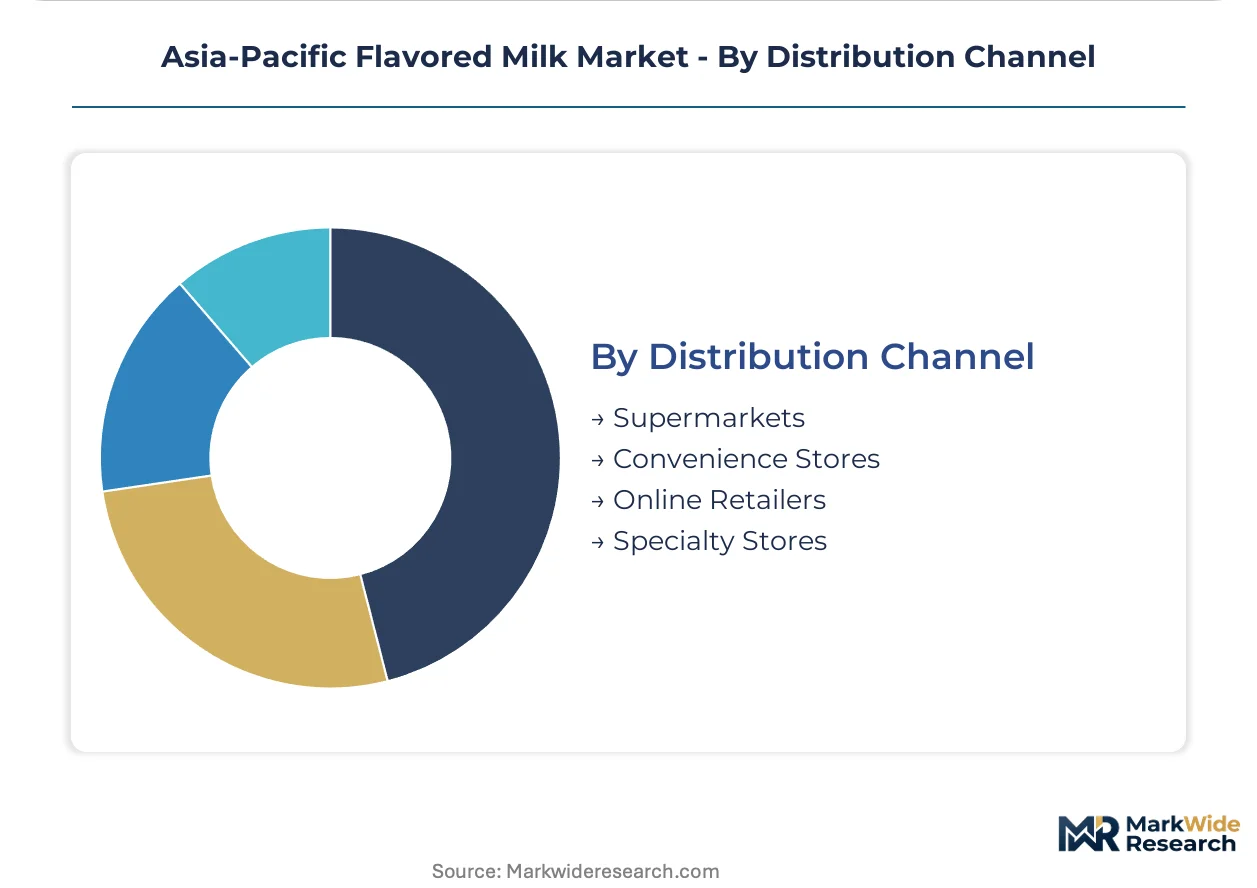
Distribution Channel:
Online retailers and specialty stores demand differentiated logistics infrastructure, while supermarkets and convenience stores compete on footprint density and cold-chain reliability.
- Supermarkets:Multi-brand shelf space allocation requires trade investment and promotional spending. India's tier-two city penetration depends on cold-chain infrastructure maturation into Rajasthan and Madhya Pradesh.
- Convenience Stores:High-frequency impulse purchase occasions favor single-serve formats. Temperature-controlled logistics in tropical Southeast Asian climates compress margins through capex-heavy refrigeration requirements.
- Online Retailers:Last-mile delivery infrastructure maturation enables fastest-growing channel expansion in India's metropolitan corridors and Indonesia's Java-based urban clusters.
- Specialty Stores:Premium positioning through curated assortment and experiential retail.
Revenue per transaction peaks in Specialty Stores. Scale economics favor Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inner Mongolia's raw milk belt anchors heat-treated dairy beverage supply chains serving northern China's premium UHT segment. Cold-chain infrastructure maturation and institutional procurement programs drive divergent growth vectors across the region's major markets.
China
SAMR enforcement of GB 25190 protein content claims compresses formulation tolerance bands for UHT processors. Shanghai and Beijing absorb highest compliance costs through third-party laboratory verification protocols. Yangtze River Delta metropolitan clusters shift toward single-serve premium refrigerated variants.
India
FSSAI dairy fortification guidelines mandate micronutrient enrichment driving school nutrition program volumes. Uttar Pradesh, Madhya Pradesh, and Rajasthan institutional procurement concentrates demand for portion-controlled chocolate sachets. Gujarat's farmer-cooperative procurement model anchors ultra-low price point positioning.
Indonesia
Java-based urban clusters generate fastest-growing online retailer channel share for convenience-oriented teenagers. Last-mile delivery infrastructure maturation unlocks metropolitan corridor penetration. Sugar taxation proposals under legislative review threaten sweetened dairy beverage economics.
Vietnam
School nutrition programs prioritize institutional procurement of fortified flavored milk in portion-controlled formats. Cold-chain infrastructure penetration remains nascent outside Ho Chi Minh City and Hanoi metropolitan areas. Replicable cooperative templates from Indian market entry strategies attract local dairy federation interest.
Australia
FSANZ fortification rules and nutrition labeling requirements govern export-grade compliance for tetra pack manufacturers. Multi-layer aseptic carton barrier technology enables simultaneous domestic premium positioning and regional export certification. Queensland and New South Wales processing clusters specialize in dual FSANZ-JIS standard production.
Asia-Pacific Flavored Milk Market Competitive Environment
Global majors compete with regional champions across formulation compliance and cold-chain distribution networks. The vendor base stratifies into three tiers: multinational dairy conglomerates with pan-Asia-Pacific portfolios, national champions leveraging raw milk belt proximity, and cooperative federations optimizing farmer-procurement economics. Dominant competitive moves include backward integration into captive raw milk supply and direct-store-delivery system deployment for refrigerated network control.
Within the cooperative federation archetype, Gujarat Co-operative Milk Marketing Federation Ltd. (Amul) exemplifies ultra-low price point positioning through farmer-owned supply structures. Among Inner Mongolia-based processors, China Mengniu Dairy Co. Ltd. and Inner Mongolia Yili Industrial Group Co. Ltd. occupy positions anchoring premium UHT supply chains through raw milk belt proximity. These three entities represent the dominant competitive vectors shaping procurement economics and distribution infrastructure investment across the region.
| Leading Market Players |
|---|
| China Mengniu Dairy Co. Ltd. |
| Inner Mongolia Yili Industrial Group Co. Ltd. |
| Gujarat Co-operative Milk Marketing Federation Ltd. (Amul) |
| Nestlé S.A. |
| Danone S.A. |
| Saputo Inc. |
| Hershey's |
| Meiji Holdings Co. Ltd. |
| Lactalis Group |
| Others |
Value Chain & Pricing Dynamics
FSSAI micronutrient enrichment mandates in India's school nutrition programs compress formulation tolerance bands and force supply-side recalibration toward portion-controlled sachet production. This procurement preference cascade tightens margin pools for processors unable to achieve economies in high-volume, low-unit-cost manufacturing.
Pricing Analysis
Raw milk input volatility from Inner Mongolia's seasonal production fluctuations passes through directly to UHT flavored milk price bands. Three-tier pricing structure across premium, standard, and economy levels separates Inner Mongolia Yili's direct-store-delivery refrigerated networks from Gujarat Co-operative Milk Marketing Federation's ultra-low cooperative pricing. Price differentiation hinges on cold-chain dependency and fortification compliance depth. Pricing pressure stems from sugar taxation proposals under legislative review in Thailand, Malaysia, and the Philippines. Institutional procurement channels exhibit highest price sensitivity; premium single-serve variants in Shanghai and Jakarta show lowest.
Supply Chain Analysis
Reverse-logistics flows for aseptic carton returns and multi-layer laminate recycling remain underdeveloped across Southeast Asian markets, constraining circular economy positioning. Supply concentrates in China, India, and Australia for heat-treated dairy beverage manufacturing. Raw material dependencies center on Inner Mongolia raw milk belts, cocoa powder supply contracts, and multi-layer polymer laminates for barrier packaging. Single-source vulnerability sits with Inner Mongolia's seasonal production fluctuations. Distribution runs through direct-store-delivery systems in northern China and farmer-cooperative procurement networks in Gujarat.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
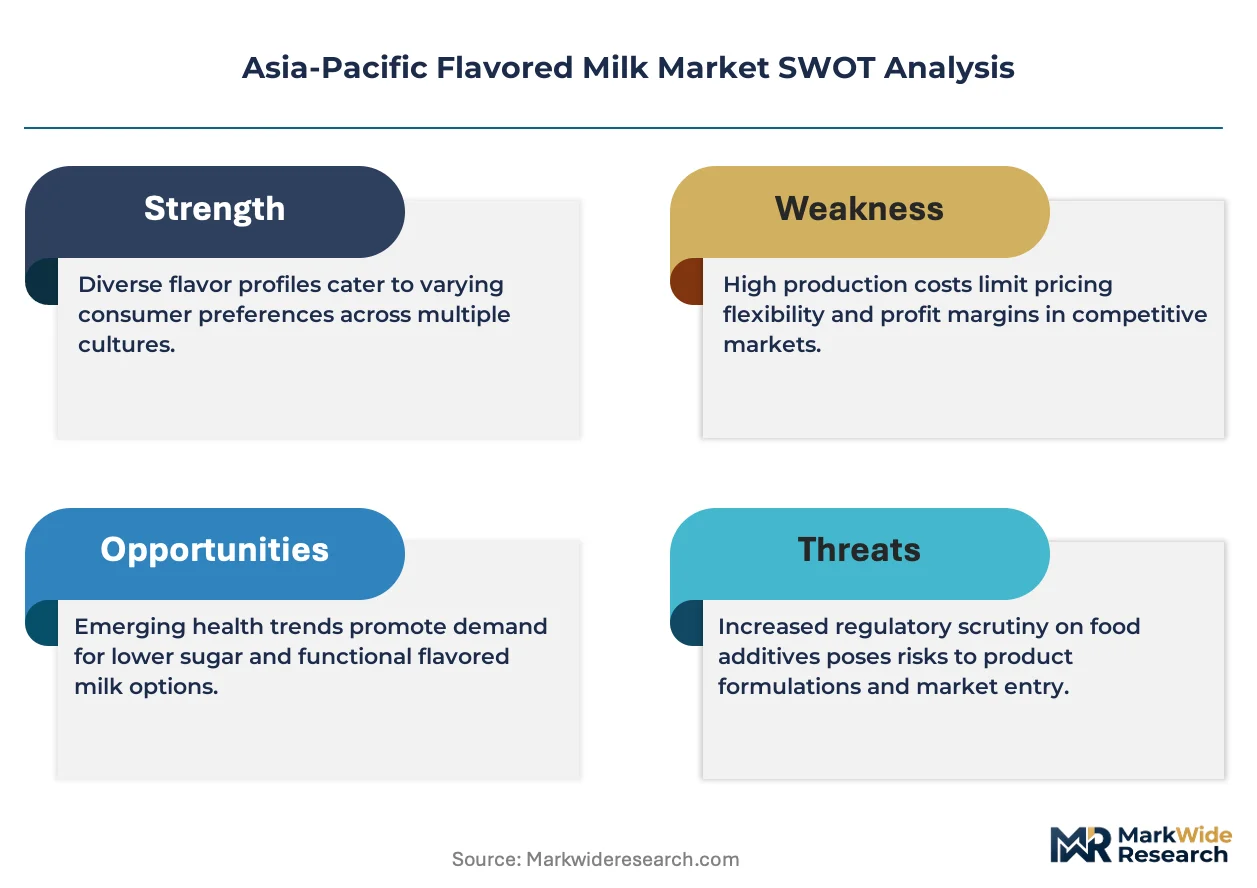
Margin expansion in Asia-Pacific flavored milk rests on cold-chain infrastructure cost-down curves penetrating India's tier-two cities and premium-tier shifts toward functional fortification positioning.
For Market Incumbents: Acquire captive cold-chain distribution assets in Uttar Pradesh, Madhya Pradesh, and Rajasthan to defend against cooperative federation price undercutting. Backward integration into multi-layer aseptic carton manufacturing reduces barrier material cost exposure. Prioritize dual FSSAI-SAMR certification pipelines to compress product launch timelines against pan-Asia-Pacific competitors.
For New Entrants and Emerging Players: Vietnam's dairy federations represent an underserved buyer archetype receptive to replicable cooperative templates from Indian market entry strategies. White-space concentration sits in Java-based urban clusters for online retailer channel partnerships and in lactose-free formulation gaps across Southeast Asian markets. Go-to-market execution should anchor on last-mile delivery infrastructure partnerships rather than capex-heavy refrigerated network buildouts.
For Investors and Strategic Acquirers: Asymmetric upside sits with processor-proximate packaging technology specialists holding dual FSANZ-JIS certification capabilities. Long-term viability over a multi-year horizon favors entities with backward integration into raw milk supply and modular aseptic carton barrier engineering. Acquisition target archetype: mid-cap processors in Queensland and New South Wales with export-grade production infrastructure. Monitor sugar taxation legislative progression in Thailand, Malaysia, and the Philippines as inflection indicator for sweetened dairy beverage economics recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Direct-store-delivery systems in India's tier-two cities unlock new consumption occasions and margin pools. |
| Dual Certification Investment | Simultaneous FSSAI and SAMR compliance documentation accelerates pan-Asia-Pacific product launch velocity. |
| Farmer-Cooperative Procurement Model | Gujarat's ultra-low price point structure offers replicable templates for Vietnam and Indonesia market entry. |
| Aseptic Carton Barrier Technology | Multi-layer polymer laminates enable premium positioning and Australian FSANZ export compliance simultaneously. |
| Functional Fortification Repositioning | FSSAI micronutrient enrichment mandates drive institutional procurement volumes through school nutrition programs. |
Study Parameters
Coverage spans China, India, Indonesia, Vietnam, and Australia, with primary inputs from each market's dairy processing clusters. The analysis combines structured interviews with dairy procurement managers, cold-chain logistics operators, regulatory affairs specialists at FSSAI and SAMR, and school nutrition program administrators. Secondary validation draws from FSSAI fortification guidelines, SAMR GB 25190 standards, FSANZ nutrition labeling requirements, customs trade data for dairy imports, and Nielsen retail audit data. Bottom-up volume modeling and top-down market sizing triangulate to produce segment-level outputs.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models flavored milk segments by product type, end user, packaging format, and distribution channel, with additional dimensioning by regional regulatory cluster. CAGRs derive from trend-line extrapolation of historical procurement volumes adjusted for cold-chain infrastructure penetration curves and institutional program expansion. Industry-specific forecast inputs include Inner Mongolia raw milk production cycles and Java-based urban cluster online retail growth trajectories.
Inputs from FSSAI, SAMR, and FSANZ regulatory filings were available through the study window; gaps in real-time school nutrition program procurement data introduce uncertainty bands around India volume estimates. Forecasts reflect assumptions about sugar taxation legislative timelines and cold-chain capex deployment rates. Practitioners should monitor GB 25190 additive restriction amendments and ASEAN sugar tax harmonization proposals for early signals of formulation economics shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Africa Yogurt Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Kefir Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Ultra High Temperature Sterilized Milk Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
Filled Cheese Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
North America Flavored Milk Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Goat Milk Products Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
United States Dairy Market
Dairy Products
South America Dairy Market