
 Electric Soldering Iron Gun Market | 2026-2036
Electric Soldering Iron Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Soldering Iron Gun Market Foresight
The gap between premium temperature-controlled stations and commodity fixed-wattage irons is repositioning procurement patterns across the channel. Weller leverages its heritage in precision thermal management to anchor the professional tier where rework accuracy commands price premiums. Hakko competes through deep tip compatibility ecosystems that lock technicians into recurring consumable purchases. X-Tronic occupies the value segment with direct-to-workbench distribution that undercuts traditional industrial distributors on landed cost.
An electric soldering iron gun is a hand-held thermal joining tool that converts electrical energy into concentrated heat through a resistive metal alloy element, typically operating at tip temperatures between 300°C and 480°C to melt tin-lead or lead-free solder alloys for permanent electrical and mechanical bonds. The device serves electronics fabrication, repair, and prototype assembly where localized, controllable heat application prevents thermal damage to sensitive semiconductor packages. Temperature-controlled units lead in margin contribution because closed-loop sensor feedback justifies sustained premium pricing against basic fixed-wattage alternatives. Cordless variants represent the fastest-expanding product type as lithium-ion cell energy density improvements enable runtime parity with corded equivalents in field service environments. Industrial-grade 100W and 150W models dominate throughput in high-volume contract manufacturing where tip recovery speed directly determines line efficiency.
Regulators across multiple geographies shape product compliance: the EPA enforces restrictions on lead-content solder in US consumer electronics, REACH governs substance restrictions in European-sold units, and China's GB standards mandate electrical safety certification for mains-powered tools sold domestically. These frameworks elevate compliance costs for entrants while favoring incumbents with established testing infrastructure and regional certification portfolios. Stakeholders must monitor how RoHS exemptions for specific alloy compositions evolve, as material formulation shifts could obsolete existing tip plating chemistries and force accelerated R&D cycles across the supplier base.
Market Dynamics
Miniaturization standards in automotive PCB assembly are forcing tool procurement upgrades as trace widths shrink below 0.1mm and thermal precision becomes non-negotiable for yield rates. This structural pressure cascades through contract manufacturers, rework service providers, and field maintenance operations, compressing replacement cycles for legacy fixed-wattage equipment.
Growth Catalysts
- RoHS solder mandates:REACH and EPA restrictions on lead-content alloys accelerate demand for temperature-controlled stations capable of processing higher-melting-point lead-free formulations without thermal damage to sensitive components.
- Automotive electronics densification:EV powertrain inverters and ADAS sensor modules require finer-pitch soldering, pulling precision thermal tools into tier-2 and tier-3 supplier workshops previously served by commodity equipment.
- Lithium-ion energy density gains:Cordless soldering tools now achieve runtime parity with corded units in 60W-80W classes, unlocking mobility-dependent applications in aerospace MRO and telecom field service.
Market Restraints
- Copper and nickel price volatility:Resistive heating elements and tip plating chemistries expose manufacturers to London Metal Exchange fluctuations that compress margin on mid-tier product lines.
- Tip ecosystem lock-in:Hakko-compatible consumable dominance creates switching costs that deter technicians from adopting alternative platforms, freezing market share distribution.
- REACH substance restrictions:ECHA candidate list expansions threaten existing chrome and nickel plating formulations, forcing reformulation R&D before current inventory amortizes.
Strategic Opportunities
- India electronics manufacturing:PLI scheme subsidies for semiconductor and component fabrication create first-mover advantage for tool vendors establishing local calibration and certification infrastructure.
- Induction heating convergence:Combination of resonant inductive cores with closed-loop thermocouple feedback enables sub-5-second tip recovery, compressing cycle times in high-volume SMT rework.
- Direct-to-workbench distribution:E-commerce platforms bypass industrial distributor markups for small-lot procurement by prototype labs and independent repair technicians.
Industry Challenges
- Micro-soldering skill scarcity:Surface-mount rework at 0201 and 01005 package scales requires hand-eye coordination and thermal judgment that vocational programs have not scaled to meet demand.
- Multi-certification timelines:Simultaneous GB standard, CE marking, and UL listing requirements for a single SKU extend product launch windows by 8-14 months.
- Legacy station integration:New temperature-controlled units must interface with existing fume extraction and ESD grounding infrastructure without full bench replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Soldering Iron Gun Market |
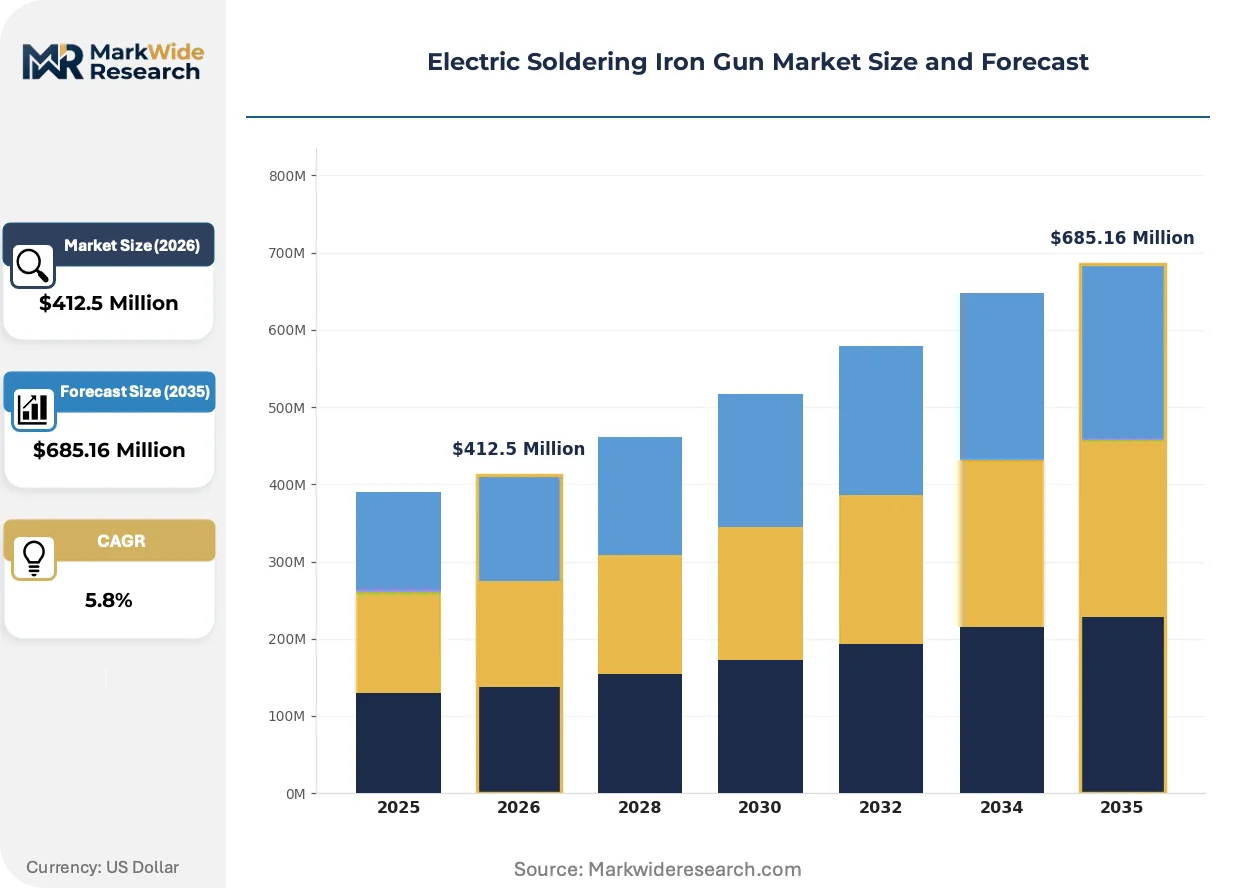
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Temperature-Controlled, Cordless, Industrial End User: Electronics Manufacturers, Hobbyists, Technicians, Educational Institutions Power Rating: 30W, 60W, 100W, 150W Feature: Adjustable Temperature, Fast Heating, Ergonomic Design, Replaceable Tips |
| Companies Covered | Weller, Hakko, Metcal, American Hakko Products, JBC Tools, PACE Worldwide, Kurtz Ersa North America, American Beauty Tools, X-Tronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Soldering Iron Gun Market Shifts & Advancements
Active infrared sensing and machine-learning tip temperature prediction are compressing thermal overshoot to under 2°C, enabling processing of temperature-sensitive MEMS and optical components that previously required rework outsourcing.
Induction heating cores with resonant frequency tuning are rewriting thermal response benchmarks in professional-grade equipment. Automotive tier-1 suppliers adopting these stations for inverter module repair report 40% reduction in pad delamination. The technology is compressing the performance gap between 150W industrial stations and portable 80W units.
EPA enforcement of TSCA Section 6(h) restrictions on persistent organic pollutants in solder flux formulations is forcing reformulation of no-clean and water-soluble chemistries. Electronics assemblers in the United States are qualifying new flux-solder combinations that demand narrower process windows, pulling premium temperature stability into mid-market procurement specifications.
Buyer consolidation through integrated MRO procurement platforms is disintermediating traditional industrial distributors. German automotive suppliers now source soldering equipment through consolidated indirect materials contracts that bundle calibration, tip replenishment, and ESD audit services, compressing vendor counts and favoring suppliers with captive consumable ecosystems.
Electric Soldering Iron Gun Market Segmentation
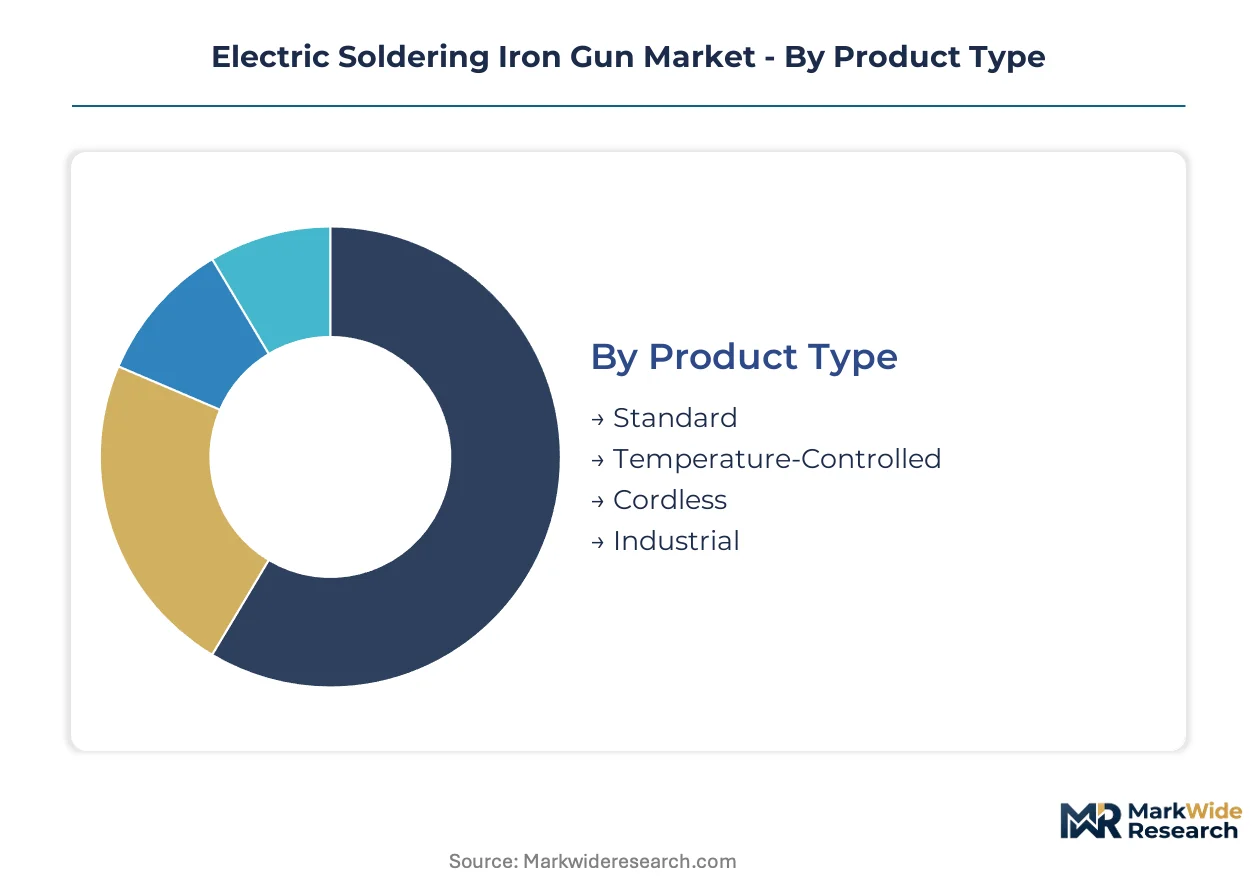
Segmentation in the electric soldering iron gun market reveals how thermal precision requirements, workspace constraints, and operator skill levels fragment demand across incompatible equipment tiers. Procurement patterns diverge sharply between volume manufacturing, precision rework, and intermittent hobby use.
Product Type:
Temperature stability and power delivery architecture distinguish competitive positioning across equipment classes.
- Temperature-Controlled:Closed-loop sensor feedback maintains tip temperature within 5°C of setpoint, essential for lead-free solder processing in automotive PCB assembly. Demand concentrates in Germany and the United States where EV powertrain manufacturers enforce thermal precision protocols.
- Cordless:Lithium-ion cell packs enable 60W-80W output without mains tethering, unlocking aerospace MRO and telecom field service applications where workspace mobility determines throughput. Runtime parity with corded units has accelerated procurement in China.
- Standard:Fixed-wattage resistive elements without feedback control serve intermittent repair and educational use where capital cost dominates specification.
- Industrial:100W-150W transformer-based stations with rapid thermal recovery dominate high-volume contract manufacturing lines where tip recovery speed directly determines line efficiency.
Mature deployment sits with Standard units in vocational training environments. Newer deployment is concentrated in Cordless configurations for field service mobility.
End User:
Volume scale and thermal precision requirements create distinct procurement specifications across operator categories.
- Electronics Manufacturers:High-volume SMT lines and contract assembly operations demand 150W industrial stations with sub-10-second thermal recovery. Tier-1 automotive suppliers in Germany specify temperature logging capabilities for process traceability compliance.
- Technicians:Independent repair operations and OEM service centers prioritize tip ecosystem compatibility and rapid tip change mechanisms to minimize job-to-job setup time.
- Hobbyists:Intermittent use patterns favor 30W-60W entry-level stations with basic temperature indication, sourced through direct-to-consumer e-commerce channels that bypass industrial distributor markups.
- Educational Institutions:Vocational programs and university engineering labs procure fixed-wattage irons in volume, prioritizing durability and simplified maintenance over precision control.
Procurement volume clusters with Electronics Manufacturers. Margin contribution peaks with Technician-class equipment where consumable attachment rates sustain recurring revenue.
Power Rating:
Thermal mass and recovery dynamics align wattage classes to specific joint geometries and production cadences.
- 150W:Heavy-gauge cable termination and large thermal mass components in industrial power electronics. Demand localizes to China where electric vehicle inverter production scales.
- 100W:Mid-volume assembly lines processing mixed through-hole and surface-mount joints. Preferred rating for automotive tier-2 suppliers qualifying lead-free process windows.
- 60W:General-purpose rework and prototype assembly where joint size varies but thermal precision remains necessary. Dominant rating in United States independent repair shops.
- 30W:Fine-pitch SMT work on 0402 and smaller components, plus delicate trace repair where excessive thermal mass risks pad lift.
Process qualification favors 100W stations for regulatory compliance documentation. Steepest expansion trajectory belongs to 150W units tracking EV powertrain manufacturing growth.
Feature:
Operator efficiency and process repeatability drive feature prioritization across use cases.
- Replaceable Tips:Interchangeable plating geometries and thermal profiles enable single-station coverage of diverse joint types. Hakko-compatible tip ecosystems dominate technician preference and create switching cost barriers.
- Fast Heating:Ceramic heating elements and induction cores compress cold-start to operating temperature below 30 seconds, reducing non-productive time in high-mix repair environments.
- Adjustable Temperature:Dial or digital setpoint control spans 200°C-480°C range to accommodate tin-lead, lead-free, and specialized alloy formulations under RoHS and REACH mandates.
- Ergonomic Design:Weight distribution, grip geometry, and cable strain relief reduce repetitive strain injury incidence in high-volume manual assembly operations.
Specification frequency ranks Replaceable Tips highest across all user categories. Fast Heating is gaining specification fastest in time-sensitive field service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors procurement volume for precision thermal tools as Guangdong Province scales EV inverter and consumer electronics module production. Contract manufacturers in the Pearl River Delta cluster now specify temperature-controlled stations for lead-free process compliance.
China
Domestic PCB fabrication capacity expansion in Jiangsu and Sichuan provinces drives industrial-grade station procurement. MIIT enforces GB standard electrical safety certification for mains-powered tools sold domestically. Suzhou industrial parks host tier-1 automotive suppliers qualifying 150W stations for powertrain inverter rework.
Germany
EV powertrain manufacturers in Baden-Württemberg enforce thermal precision protocols for ADAS sensor module assembly. REACH substance restrictions govern chrome and nickel plating formulations in European-sold units. Munich-area automotive tier-1 suppliers specify temperature logging capabilities for process traceability compliance.
United States
EPA enforcement of TSCA Section 6(h) restrictions on persistent organic pollutants forces flux formulation changes that narrow process windows. Independent repair shops in Texas and California prioritize 60W stations with rapid tip change mechanisms. Aerospace MRO operations in Seattle-Tacoma corridor adopt cordless lithium-ion tools for airframe field service.
Japan
Precision electronics manufacturers in Kansai region demand sub-5°C temperature stability for MEMS component processing. METI oversees JIS standards compliance for industrial thermal equipment. Osaka-area SMT rework facilities specify induction heating cores with resonant frequency tuning for pad delamination reduction.
India
PLI scheme subsidies for semiconductor fabrication create first-mover opportunity for tool vendors establishing calibration infrastructure. BIS mandates electrical safety certification for domestically sold equipment. Karnataka's Electronics City cluster attracts contract manufacturers qualifying temperature-controlled stations for export-bound module assembly.
Electric Soldering Iron Gun Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal precision and consumable ecosystem dimensions. The vendor base stratifies into three tiers: heritage precision thermal management specialists, deep tip compatibility ecosystem operators, and direct-to-workbench value distributors. Consolidation pressure concentrates at the mid-tier where copper and nickel price volatility compresses returns. Dominant competitive moves include captive consumable ecosystem construction and induction heating technology licensing.
Among heritage precision specialists, Weller and Hakko exemplify divergent archetype strategies. Weller occupies a position anchored in professional-tier rework accuracy where closed-loop sensor feedback justifies sustained premium pricing. Hakko exemplifies the consumable lock-in model through deep tip compatibility ecosystems that create switching costs deterring technician platform migration. JBC Tools represents the induction heating convergence tier where resonant core technology compresses thermal recovery benchmarks.
| Leading Market Players |
|---|
| Weller |
| Hakko |
| Metcal |
| American Hakko Products |
| JBC Tools |
| PACE Worldwide |
| Kurtz Ersa North America |
| American Beauty Tools |
| X-Tronic |
| Others |
Supply & Pricing Matrix
Captive consumable ecosystems anchor both supply position and pricing power in the electric soldering iron gun market, with Hakko-compatible tip dominance creating switching costs that protect margin tiers across the channel. This backward integration into consumable manufacturing insulates premium vendors from commodity price swings while forcing mid-tier competitors to absorb copper and nickel volatility on core hardware.
Pricing Analysis
Throughput-based pricing anchors professional-tier procurement, where tip recovery speed and thermal stability translate directly into line efficiency and rework yield. Three-tier pricing structure across premium, standard, and economy levels separates temperature-controlled stations with closed-loop feedback from fixed-wattage alternatives and entry-level hobby units. Pricing pressure stems from lithium-ion cell cost compression in cordless configurations, which is forcing premium vendors to justify sensor-based premiums against runtime-parity challengers. Hobbyists and educational institutions exhibit highest price sensitivity, while automotive tier-1 suppliers prioritize thermal precision over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for resistive heating elements and ceramic cores mandate multi-supplier qualification among contract manufacturers, compressing single-source leverage. Manufacturing concentrates in China, Germany, and Japan, with Shenzhen and Suzhou anchoring PCB assembly tool procurement while Osaka and Stuttgart host precision thermal equipment fabrication. Supply chains draw from copper and nickel feedstock exposed to London Metal Exchange volatility, plus lithium-ion cell supply tethered to cathode chemistry constraints. Single-source vulnerability in Hakko-compatible tip plating creates lock-in risk. Distribution runs through industrial MRO platforms consolidating calibration and consumable replenishment services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric soldering iron gun market is becoming a vertical-integration race, with vendors pursuing captive consumable ecosystems to defend margin contribution against hardware commoditization.
For Market Incumbents: Lock in technician loyalty through expanded tip geometry portfolios and rapid-change mechanisms that increase switching costs. Deepen backward integration into resistive alloy and plating chemistry production to buffer London Metal Exchange volatility. Defend against induction heating convergence by licensing resonant core technology or acquiring specialists in sub-5-second thermal recovery. For New Entrants and Emerging Players: PLI scheme subsidies in India open a window for establishing local calibration infrastructure ahead of semiconductor fabrication scale-up. Target Karnataka's Electronics City cluster and Gujarat's Dholera semiconductor zone with temperature-controlled stations qualified for export-bound module assembly. Bypass industrial distributor markups through direct-to-workbench e-commerce channels serving prototype labs and independent repair technicians. For Investors and Strategic Acquirers: Exit pathways concentrate in consumable ecosystem roll-ups and induction heating technology licensing. Long-term viability favors vendors with captive tip manufacturing and regional certification portfolios spanning GB standards, CE marking, and UL listing. Watch induction heating adoption rates in automotive tier-1 supplier workshops as the inflection signal for technology displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Consumable Ecosystem Expansion | Deep tip compatibility portfolios lock technicians into recurring purchases across Hakko-compatible platforms. |
| Induction Heating Technology Licensing | Resonant core patents enable sub-5-second thermal recovery for automotive inverter module rework. |
| Regional Certification Infrastructure | Simultaneous GB standard, CE marking, and UL listing capabilities compress product launch windows by 8-14 months. |
| Direct-to-Workbench Distribution | E-commerce platforms bypass industrial distributor markups for small-lot procurement by prototype labs. |
| Backward Integration into Tip Plating | In-house nickel and chrome plating chemistry production buffers REACH substance restriction compliance costs. |
Research Methodology
SEC filings, MIIT production databases, and ECHA substance restriction registers formed the secondary backbone, supplemented by customs records tracking copper and nickel alloy trade flows. Primary interviews with electronics manufacturing procurement leads, thermal equipment R&D directors, automotive tier-1 supplier quality engineers, and industrial MRO platform category managers validated demand assumptions and price sensitivity thresholds. Bottom-up unit shipment estimates across temperature-controlled, cordless, standard, and industrial product tiers were cross-referenced against top-down electronics fabrication capacity expansion data.
Bottom-up modeling segmented demand by power rating, end-user category, and feature configuration, with projections calibrated to EV powertrain manufacturing scale and ADAS sensor module densification trends. CAGRs were derived from triangulating equipment replacement cycle compression, lithium-ion energy density improvement curves, and lead-free solder mandate enforcement timelines. Induction heating adoption rates and cordless runtime parity milestones served as technology-specific forecast inputs across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for resonant induction heating would alter the outlook if automotive tier-1 suppliers accelerate qualification beyond current replacement cycles. Deviation in copper and nickel price volatility or REACH substance restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
CO2 Laser Market
Industrial Equipment
Jet Dispenser Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Electric Actuator Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Electric Cartridge Heaters Market