
 Pneumatic Strippers Market | 2026-2036
Pneumatic Strippers Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Strippers Market Analytics
The pneumatic strippers market is rebalancing between premium precision units and commodity-grade alternatives as aerospace and data communication buyers demand tighter tolerance control. Henkel Adhesives Technologies India Private Limited leverages its chemical coatings expertise to protect pneumatic cylinder components from corrosive stripping environments. PPG Industries, Inc. anchors its position through industrial coatings that extend tool life in high-cycle manufacturing settings. FUCHS competes with specialized lubrication formulations that reduce friction in pneumatic stripping mechanisms.
Pneumatic strippers are air-powered tools that use compressed gas to drive reciprocating blade mechanisms for removing insulation from electrical conductors, typically operating at pressures between 6-8 bar and achieving strip tolerances within ±0.05 mm for precision applications. Their primary industrial purpose centers on high-volume wire processing where repeatability and operator ergonomics outweigh manual tool flexibility. The automatic strippers segment dominates factory-floor deployments where throughput requirements justify capital investment, while battery-powered alternatives capture mobile maintenance applications lacking compressed air infrastructure. Wire processing applications lead absolute volume as automotive harness manufacturers standardize on pneumatic equipment for multi-core cable preparation.
OSHA standards governing electrical worker protection shape insulated tool requirements for US-market pneumatic strippers, while IEC 60900 certification demands constrain European product design. REACH chemical restrictions affect stripping blade coatings and pneumatic lubricant formulations across EU member states. The EU AI Act's emerging machine-safety provisions will likely influence smart pneumatic tool development with integrated force-feedback sensors. Stakeholders must monitor how evolving electrical safety harmonization between OSHA and IEC frameworks affects cross-border product certification costs and design standardization timelines.
Market Dynamics
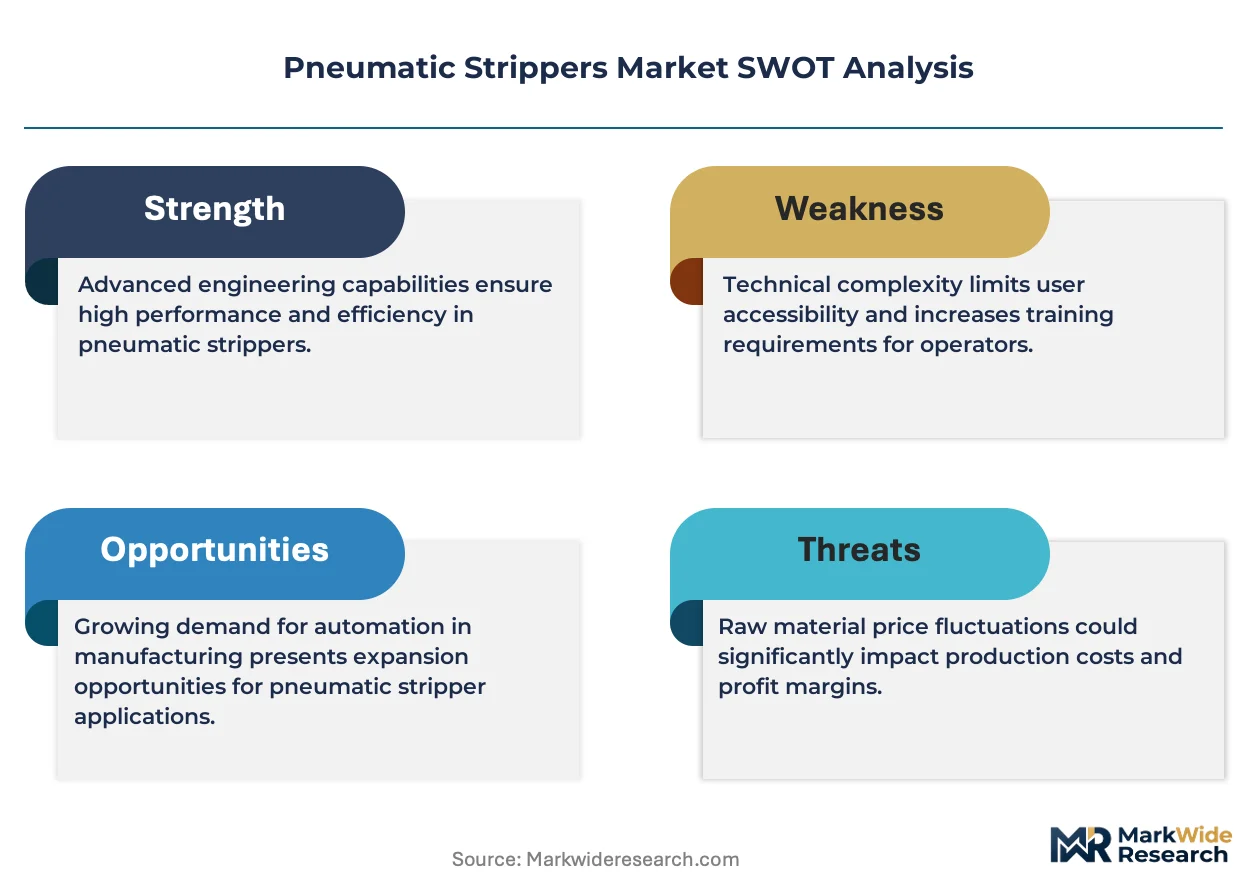
Pneumatic strippers face mounting pressure from IEC 60900 certification mandates that force redesign cycles, while aerospace MRO procurement standardization concentrates buyer power among fewer qualified suppliers.
Growth Catalysts
- Aerospace MRO standardization:Wire harness overhaul facilities in Germany's industrial automation corridor are mandating pneumatic equipment for multi-core cable preparation, locking in repeat procurement cycles.
- OSHA electrical safety enforcement:Tighter insulated tool requirements for US electrical worker protection are disqualifying manual alternatives and accelerating factory-floor pneumatic adoption.
- REACH-compliant coating advances:Chemical reformulations for stripping blade surfaces are extending operational lifespans in corrosive industrial environments, reducing total cost of ownership.
Market Restraints
- Compressed air infrastructure dependency:Battery-powered stripping tools capture mobile maintenance applications lacking 6-8 bar pneumatic supply, capping addressable market in field-service segments.
- European certification friction:IEC 60900 and evolving EU AI Act machine-safety provisions impose multi-year compliance timelines that delay product launches and inflate development costs.
- Pneumatic lubricant input volatility:Specialized friction-reduction formulations face feedstock pressure from petrochemical supply concentration, squeezing margin structures on precision units.
Strategic Opportunities
- Smart sensor convergence:Force-feedback integration with pneumatic mechanisms is integrating predictive maintenance capabilities, opening premium pricing tiers in high-cycle manufacturing settings.
- Data communication cable surge:Fiber-optic and high-speed copper harness production lines are specifying sub-±0.05 mm tolerance pneumatic strippers for emerging telecommunications infrastructure builds.
- Aftermarket service unbundling:Blade refurbishment and calibration subscriptions are creating recurring revenue streams independent of original equipment sales in established industrial bases.
Industry Challenges
- Pneumatic mechanic skill scarcity:Compressed air system troubleshooting expertise is concentrating among aging technician cohorts, constraining deployment velocity at new facilities.
- Legacy control integration complexity:Retrofitting force-feedback sensors into existing pneumatic architectures requires custom PLC programming, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Strippers Market |
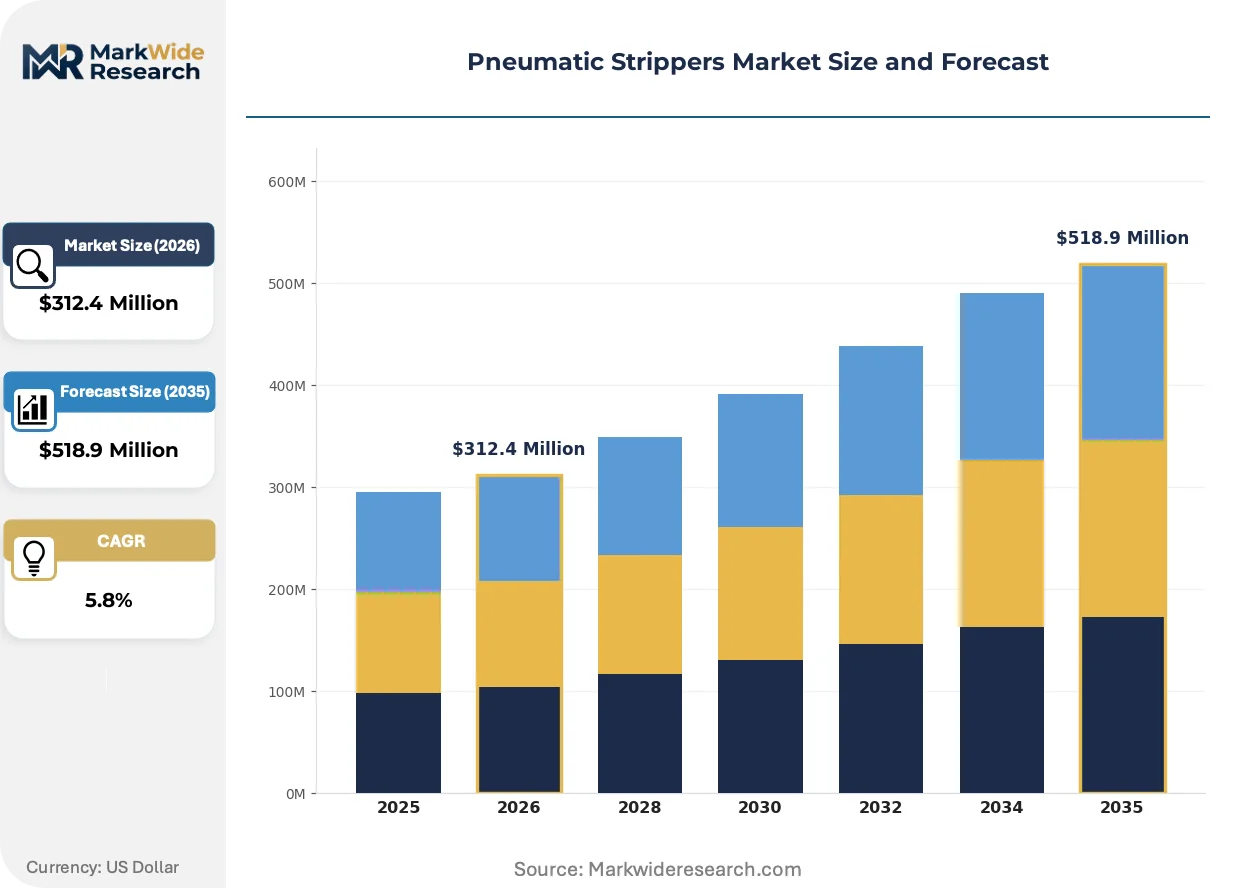
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Strippers, Automatic Strippers, Battery-Powered Strippers, Pneumatic Strippers End User: Aerospace, Manufacturing, Construction, Electrical Application: Cable Assembly, Wire Processing, Automotive, Data Communication Feature: Adjustable Cutting Depth, Ergonomic Design, Multi-Functional, Safety Mechanism |
| Companies Covered | Henkel Adhesives Technologies India Private Limited, Quaker Chemical Corporation, PPG Industries, Inc., FUCHS, Akzo Nobel N.V., The Sherwin-Williams Company, Harris International Laboratories, Inc., Northern Technologies International Corporation, Chempace Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Strippers Market Evolving Landscape
Force-feedback sensor technology is compressing the gap between pneumatic precision and adaptive control, while regulatory harmonization pressures and procurement consolidation reshape competitive positioning.
Smart pneumatic strippers are integrating piezoelectric force sensors that enable real-time blade pressure adjustment during insulation removal. Automotive harness manufacturers in Stuttgart and Wolfsburg are piloting these units for multi-material cable processing. The technology is integrating predictive maintenance alerts that reduce unplanned downtime in 24/7 production environments.
REACH chemical restrictions are forcing reformulation of blade coatings and pneumatic lubricants across EU member states. Industrial coatings suppliers must now validate corrosion resistance under stricter substance authorization protocols. German tool builders are responding by accelerating in-house lubricant development to insulate supply chains from ECHA regulatory delays.
Buyer concentration among tier-one aerospace MRO providers is compressing supplier negotiation cycles and demanding outcome-based performance guarantees. Tier-two wire processors are losing direct access to OEM technical support as distributors consolidate value-added service capabilities. This channel shift is most visible in France and Italy, where ANSM safety documentation requirements favor established distributor relationships over direct procurement.
Pneumatic Strippers Market Segmentation
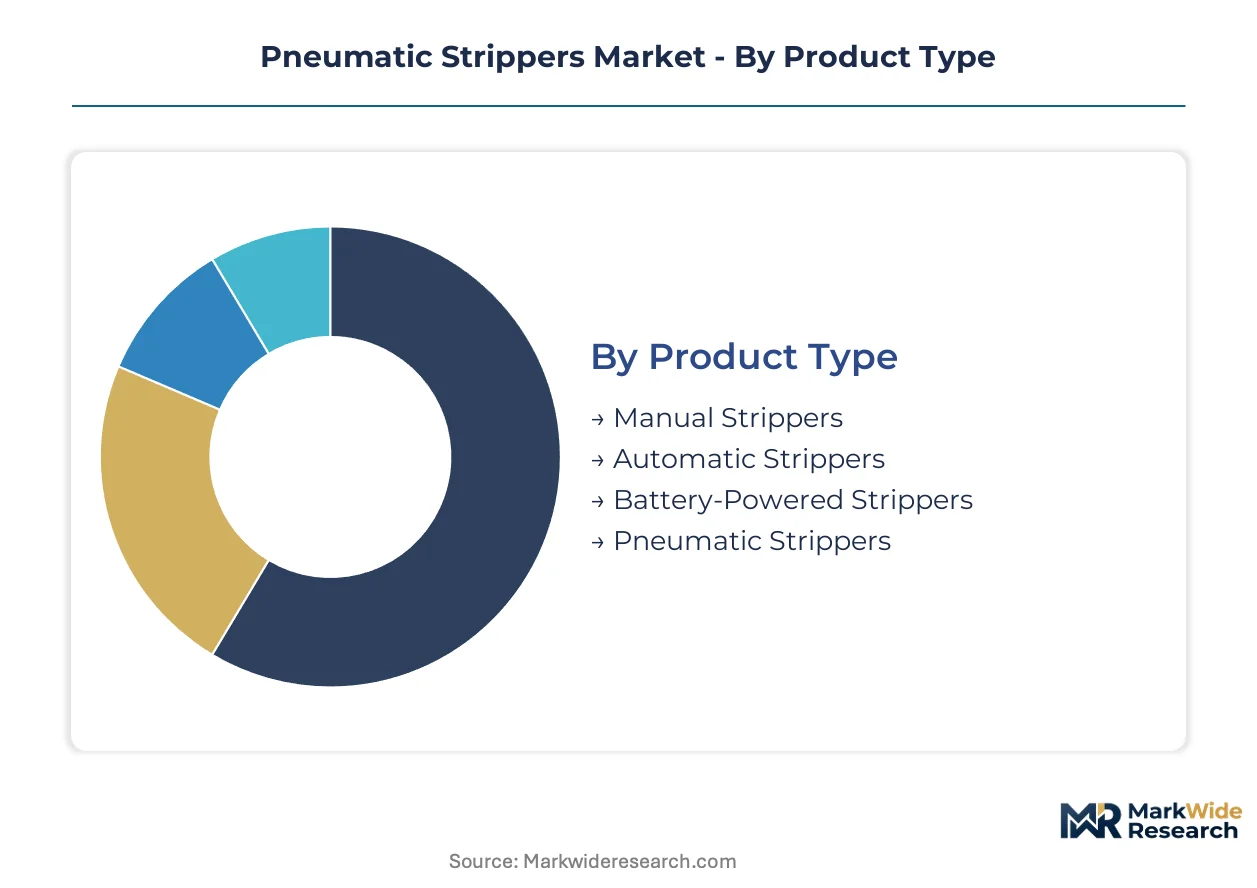
Pneumatic stripper segmentation reveals distinct procurement patterns between integrated factory-floor systems and portable field-service equipment. Aerospace harness manufacturers and automotive tier-one suppliers drive divergent specification requirements across product categories.
Product Type:
Integration depth separates standalone portable units from embedded production-line systems, with compressed air infrastructure availability determining deployment feasibility.
- Pneumatic Strippers:These compressed-air tools operate at 6-8 bar pressure with reciprocating blade mechanisms achieving ±0.05 mm strip tolerances. German automotive harness manufacturers in Stuttgart and Wolfsburg standardize on these units for 24/7 multi-core cable processing lines where repeatability outweighs capital cost.
- Automatic Strippers:Programmable feed-and-cut systems integrate directly into cable assembly lines with minimal operator intervention. Aerospace MRO facilities in France and Italy mandate these for wire harness overhaul cycles, locking in multi-year procurement contracts with performance guarantees.
- Manual Strippers:Hand-operated tools serve low-volume prototyping and field repair scenarios lacking compressed air infrastructure.
- Battery-Powered Strippers:Cordless lithium-ion units capture mobile maintenance applications in construction sites and remote electrical installations.
Volume placements concentrate in automatic strippers; the faster expansion belongs to pneumatic strippers.
End User:
Cost-tier stratification separates precision-specification buyers from price-sensitive procurement, with certification requirements widening the gap between premium and standard segments.
- Manufacturing:High-volume automotive and electronics producers deploy pneumatic and automatic strippers in integrated cable assembly cells. OSHA electrical safety enforcement in US-based facilities is disqualifying manual alternatives and accelerating factory-floor pneumatic adoption.
- Aerospace:MRO providers and OEM harness shops demand IEC 60900-certified insulated tools with documented calibration traceability. German tool builders face multi-year compliance timelines for EU AI Act machine-safety provisions, delaying product launches.
- Electrical:Contract electricians and utility maintenance crews prioritize portable battery-powered and manual strippers for field-service flexibility.
- Construction:Building wiring contractors favor durable manual and battery-powered units resistant to jobsite contamination.
Revenue concentration sits with manufacturing; aerospace climbs the fastest on MRO standardization mandates.
Application:
Application segmentation tracks tolerance requirements, with sub-millimeter precision specifications commanding premium positioning against general-purpose wire preparation.
- Wire Processing:Multi-core cable preparation for automotive harnesses and industrial control systems drives the largest absolute volume. REACH-compliant coating advances on stripping blades are extending operational lifespans in corrosive environments.
- Data Communication:Fiber-optic and high-speed copper production lines specify sub-±0.05 mm tolerance pneumatic strippers for emerging telecommunications infrastructure builds.
- Automotive:EV battery pack wiring and charging cable assemblies require specialized strip geometries for crimp termination reliability.
- Cable Assembly:Contract manufacturers serving multiple end-markets favor adjustable automatic strippers with quick-change tooling.
Shipment volumes cluster in wire processing; data communication gains share fastest on telecommunications infrastructure investment.
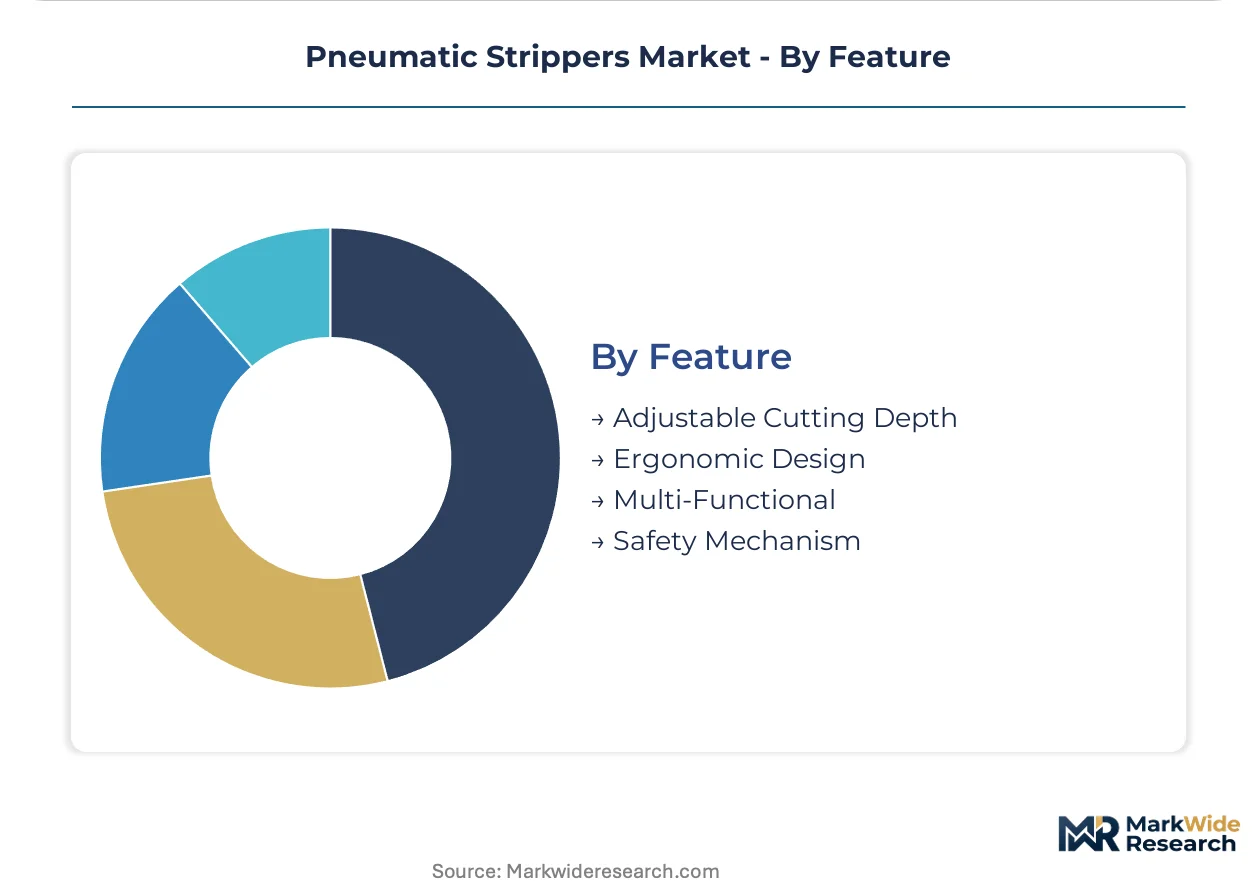
Feature:
Feature segmentation reflects operator safety priorities and ergonomic regulatory pressure, with integrated protection mechanisms becoming baseline rather than differentiator.
- Safety Mechanism:Blade guards, interlocks, and insulated handles address OSHA electrical worker protection standards and IEC 60900 certification requirements. US-market pneumatic strippers face tightening insulated tool mandates.
- Ergonomic Design:Vibration-dampened grips and balanced weight distribution reduce repetitive strain injuries in high-cycle manufacturing settings. Aging technician cohorts drive demand for reduced-fatigue tool designs.
- Adjustable Cutting Depth:Micrometer-adjustable blade positioning accommodates varying insulation thicknesses without tool changes.
- Multi-Functional:Combined stripping, cutting, and crimping heads reduce tool changeover time in mixed-product assembly environments.
Specification frequency leads with safety mechanisms; ergonomic design expands most quickly on workforce demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors pneumatic stripper procurement intensity through Volkswagen and Porsche harness manufacturing clusters, where 24/7 multi-core cable processing lines demand sub-±0.05 mm tolerance equipment.
Germany
Automotive harness manufacturers in Wolfsburg and Stuttgart standardize on pneumatic equipment for EV battery pack wiring assemblies. IEC 60900 certification mandates from the KBA shape insulated tool procurement requirements. Bavaria's industrial automation corridor concentrates MRO facility expansion for aerospace wire overhaul operations.
United States
OSHA electrical safety enforcement accelerates factory-floor pneumatic adoption across Michigan and Ohio automotive belt manufacturing. Tighter insulated tool requirements for electrical worker protection disqualify manual alternatives. Detroit-area tier-one suppliers lock in multi-year procurement contracts for automated cable assembly cells.
France
Aerospace MRO providers in Toulouse mandate automatic strippers with documented calibration traceability for wire harness overhaul cycles. ANSM safety documentation requirements favor established distributor relationships over direct procurement. The Île-de-France region concentrates buyer power among consolidated tier-one maintenance facilities.
China
Telecommunications infrastructure builds in Shenzhen and Dongguan drive demand for sub-±0.05 mm tolerance pneumatic strippers in fiber-optic production lines. GB standards and MIIT equipment certification shape product design requirements. The Pearl River Delta anchors high-speed copper harness manufacturing for 5G deployment.
Japan
Precision electronics manufacturers in Nagoya specify force-feedback integrated pneumatic units for multi-material cable processing. METI industrial equipment standards govern machine-safety provisions for smart tool development. The Chubu region concentrates aging technician cohorts demanding ergonomic tool designs for reduced-fatigue operation.
Pneumatic Strippers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and coating technology differentiation. The vendor base stratifies between integrated coatings-lubricants specialists and standalone pneumatic equipment fabricators. Three archetypes dominate: chemical formulation leaders extending into tool protection, industrial coatings providers leveraging corrosion resistance expertise, and precision mechanics specialists integrating smart sensor capabilities. Competitive moves concentrate on REACH-compliant reformulation cycles and force-feedback technology licensing.
Among coatings and chemical specialists, Henkel Adhesives Technologies India Private Limited, PPG Industries, Inc., and FUCHS occupy positions that exemplify divergent strategic anchors. Henkel leverages chemical coatings expertise to protect pneumatic cylinder components from corrosive stripping environments. PPG anchors its position through industrial coatings that extend tool life in high-cycle manufacturing settings. FUCHS competes with specialized lubrication formulations that reduce friction in pneumatic stripping mechanisms.
| Leading Market Players |
|---|
| Henkel Adhesives Technologies India Private Limited |
| Quaker Chemical Corporation |
| PPG Industries, Inc. |
| FUCHS |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| Harris International Laboratories, Inc. |
| Northern Technologies International Corporation |
| Chempace Corporation |
| Others |
Value Network & Pricing Analysis
REACH chemical authorization timelines gate qualified supply for premium-tier pneumatic strippers, forcing German tool builders to absorb extended certification costs or surrender margin to commodity competitors lacking EU market access.
Pricing Analysis
Outcome-based pricing tied to documented strip tolerance achievement and unplanned downtime reduction anchors premium-tier pneumatic stripper contracts. Three-tier pricing structure across precision-certified, standard industrial, and economy-grade levels separates aerospace MRO procurement from automotive volume buyers from field-service contractors. Cost compression in economy-grade battery-powered alternatives is intensifying because cordless lithium-ion technology erodes pneumatic infrastructure advantages in mobile applications. Automotive harness manufacturers in Stuttgart exhibit lowest price sensitivity due to 24/7 throughput requirements, while construction contractors face acute margin pressure from commoditized manual tool alternatives.
Supply Chain Analysis
Compressed air system technician scarcity in Germany, Japan, and the United States constrains deployment velocity at new manufacturing facilities and extends commissioning timelines for smart sensor retrofits. Precision blade coatings draw from petrochemical feedstocks concentrated in Belgian and Dutch chemical clusters, while piezoelectric force sensors source from Japanese electronics suppliers. Single-source vulnerability in REACH-compliant lubricant formulations exposes margin structures to ECHA regulatory delays. Distribution runs through consolidated industrial distributors in France and Italy, with tier-one aerospace MRO providers increasingly bypassing channel partners for direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pneumatic stripper competition has become a vertical-integration race, with coatings-lubricants specialists acquiring precision mechanics capabilities to capture margin pools previously reserved for standalone tool fabricators.
For Market Incumbents: Anticipate force-feedback sensor commoditization by locking exclusive licensing agreements with Japanese piezoelectric component suppliers before patent cliffs erode differentiation. Defend position against battery-powered substitute technologies by embedding predictive maintenance subscriptions that create switching costs in high-cycle manufacturing accounts. Prioritize backward integration into REACH-compliant lubricant formulation to insulate supply chains from ECHA authorization delays. For New Entrants and Emerging Players: The price-point gap between IEC 60900-certified premium units and uncertified economy alternatives creates white-space opportunity in tier-two wire processing shops serving automotive subcontractors. Target data communication cable manufacturers in China's Pearl River Delta specifying sub-±0.05 mm tolerance equipment for 5G infrastructure builds. Pursue distributor partnership routes in France and Italy where ANSM documentation requirements favor established channel relationships over direct technical engagement. For Investors and Strategic Acquirers: Force-feedback sensor pilot deployments at Volkswagen and Porsche harness facilities are the leading indicator that smart pneumatic tool penetration is crossing from experimental to standardized procurement. Position for five-to-ten year holding periods centered on precision mechanics specialists with captive coatings development capabilities. Monitor EU AI Act machine-safety provision implementation timelines as the critical inflection signal for compliance-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| In-House Lubricant Development | German tool builders accelerate captive formulation to bypass ECHA regulatory delays on REACH-compliant coatings. |
| Force-Feedback Sensor Licensing | Piezoelectric component partnerships with Nagoya electronics manufacturers compress technology access gaps. |
| Aftermarket Service Unbundling | Blade refurbishment subscriptions create recurring revenue independent of original equipment sales in Stuttgart. |
| Direct MRO Procurement Channels | Toulouse aerospace facilities bypass distributors for automatic stripper contracts with documented calibration traceability. |
| Battery-Powered Product Line Extension | Cordless lithium-ion units capture construction and field-electrical segments lacking 6-8 bar compressed air infrastructure. |
Research Methodology
Multi-period observation of pneumatic stripper procurement cycles at Volkswagen and Porsche facilities anchored the trend analysis, supplemented by interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Secondary validation drew from SEC 10-K filings of coatings suppliers, customs and trade data for pneumatic component imports, ACC industrial equipment reports, and KBA automotive production statistics. Bottom-up segment sizing triangulated against top-down market value estimates derived from tier-one aerospace MRO contract disclosures.
Input-output matrices modeled relationships between compressed air infrastructure investment, wire processing throughput requirements, and certification compliance timelines across the projection horizon. Segmentation dimensions included product integration depth, end-user cost tier, application tolerance specification, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking capital expenditure plans at automotive harness manufacturers. Industry-specific forecast inputs incorporated REACH chemical authorization timelines and EU AI Act machine-safety provision implementation schedules.
Underlying measurement precision varies by segment; aerospace MRO procurement data carries tighter precision than fragmented construction contractor estimates due to consolidated buyer concentration. Forecasts reflect assumptions regarding OSHA electrical safety enforcement continuity, IEC 60900 certification harmonization progress, and petrochemical feedstock price stability. Material deviation in REACH authorization timelines or force-feedback sensor adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Pin Insertion Machine Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Digital Servo Press Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Pin Marking Machine Market