
 Global Industrial Centrifuges Market | 2026-2036
Global Industrial Centrifuges Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Centrifuges Market Foresight
Digital twin integration is fragmenting traditional centrifuge procurement patterns as operators demand predictive maintenance architectures alongside mechanical hardware. ALFA LAVAL leverages its marine and industrial separation heritage to anchor high-margin aftermarket service contracts across European process industries. GEA Group Aktiengesellschaft sustains engineering-intensive positions in dairy and brewery applications where hygienic design standards exceed commodity offerings. ANDRITZ competes aggressively in mining and minerals tailings recovery, where bowl durability under abrasive loads determines equipment selection cycles.
Industrial centrifuges are rotating separation devices that exploit density differentials between immiscible phases through controlled centrifugal force, typically generating relative centrifugal forces from hundreds to tens of thousands of g for continuous or batch processing of slurries, suspensions, and emulsions. Their primary commercial purpose is to reduce liquid volumes, recover solids, or purify process streams across continuous manufacturing environments where gravitational settling proves economically unviable. Decanter centrifuge deployments dominate wastewater treatment and oilfield solids control owing to their tolerance for high feed solids concentrations and continuous discharge capability. Disc stack configurations lead pharmaceutical purification and beverage clarification where phased separation efficiency and clean-in-place compatibility command premium positioning.
The US EPA enforces effluent limitation guidelines that compel chemical manufacturers and petroleum extractors to upgrade legacy separation infrastructure, while the EU F-Gas Regulation constrains refrigerant-based cooling systems integrated with temperature-controlled centrifuge operations. China's MEE implements dual carbon goals that tighten energy efficiency thresholds for industrial equipment above specified power ratings. Stakeholders must monitor how REACH chemical restrictions and evolving ISO machinery safety standards reshape material specifications for wetted components in pharmaceutical and food-contact applications.
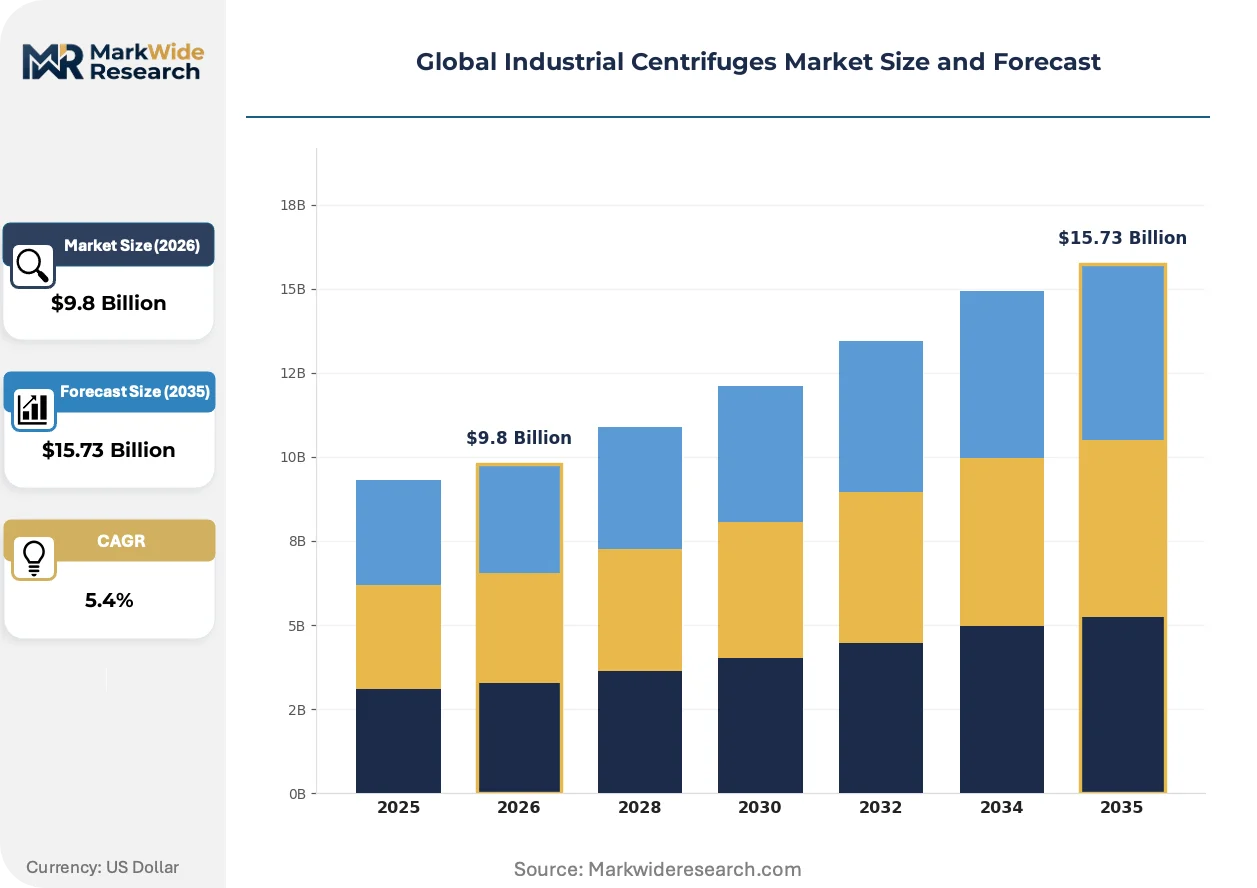
Market Dynamics
Digital twin architectures are fragmenting traditional centrifuge procurement as operators bundle predictive maintenance software with mechanical hardware, compressing vendor selection cycles and elevating service contract margins above equipment sales.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:Tightening discharge standards for chemical and food processors in Germany and France are mandating decanter and disc stack upgrades across legacy wastewater infrastructure.
- India's pharmaceutical manufacturing corridors:Domestic purification capacity scaling around Hyderabad and Ahmedabad is concentrating demand for GMP-compliant disc stack centrifuges with clean-in-place validation.
- China's dual carbon goals:MEE energy efficiency thresholds for industrial equipment above specified power ratings are accelerating replacement of aging high-consumption separation units.
Market Restraints
- Specialized alloy input volatility:Duplex stainless steel and superalloy bowl materials face price instability from nickel and molybdenum supply concentration in Indonesian and Russian mining operations.
- EU F-Gas Regulation constraints:Refrigerant-based cooling systems integrated with temperature-controlled centrifuge operations face phase-down schedules that complicate equipment specification for pharmaceutical cold-chain applications.
- Membrane filtration substitution:Cross-flow microfiltration and ultrafiltration systems are capturing share in beverage clarification and bioprocessing where lower shear tolerance permits.
Strategic Opportunities
- Brazilian mining tailings recovery:Underpenetrated installed base for high-abrasion decanter units serving iron ore and phosphate processing offers expansion potential for bowl durability specialists.
- US EPA effluent limitation guidelines:Chemical manufacturers and petroleum extractors face compelled upgrades to legacy separation infrastructure, creating mandated replacement demand.
- Digital twin-predictive maintenance convergence:Vibration monitoring AI and physics-based modeling are enabling outcome-based service contracts that capture lifecycle value beyond initial equipment sale.
Industry Challenges
- ASME and PED certification timelines:Pressure vessel design approvals for high-g pharmaceutical applications extend lead times and strain project delivery schedules.
- Legacy DCS integration complexity:Brownfield installations in chemical processing require custom communication protocols to bridge centrifuge automation with existing distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Centrifuges Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bowl Centrifuge, Tubular Centrifuge, Decanter Centrifuge, Disc Stack Centrifuge, Peeler Centrifuge Technology: Solid Bowl, Pusher, Scroll, Basket, Horizontal, Vertical Application: Chemicals Processing, Food & Beverage Separation, Pharmaceuticals Purification, Wastewater Treatment, Oil & Gas Extraction End User Industry: Chemical Manufacturers, Beverage Producers, Pharmaceutical Companies, Environmental Agencies, Petroleum Extractors |
| Companies Covered | ALFA LAVAL, GEA Group Aktiengesellschaft, ANDRITZ, FLSmidth A/S, Flottweg SE, Mitsubishi Kakoki Kaisha, Ltd., SPX FLOW, Inc., Ferrum AG, SIEBTECHNIK TEMA GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Centrifuges Market Shifts & Advancements
Active reshaping of the centrifuge market centers on three vectors: mechanical design evolution toward condition-monitoring integration, regulatory compression of refrigerant-dependent cooling architectures, and buyer-side unbundling of aftermarket service relationships.
Magnetic bearing technology is migrating from aerospace and turbomachinery heritage into high-speed decanter and disc stack applications, eliminating lubrication contamination risks in pharmaceutical and dairy processing. European hygienic design specialists are adopting magnetic suspension for clean-in-place validation, compressing maintenance intervals and enabling sealed-system operation that reduces product loss. This migration from conventional oil-lubricated bearing housings is enabling premium pricing for hermetic configurations in aseptic applications.
REACH chemical restrictions and evolving ISO machinery safety standards are reshaping material specifications for wetted components in pharmaceutical and food-contact applications. ECHA substance of very high concern listings are restricting certain elastomer and coating chemistries previously standard in sealing systems, forcing reformulation of gaskets and barrier fluids. German and Swiss process equipment suppliers are responding with accelerated qualification of fluoropolymer and platinum-cured silicone alternatives for high-purity duty.
Aftermarket service unbundling is disrupting traditional bundled maintenance contracts as large chemical and mining operators bring condition monitoring in-house. Third-party predictive analytics platforms are displacing OEM-exclusive service agreements, particularly in US Gulf Coast petrochemical clusters where operator engineering capabilities support direct sensor integration. This shift is compressing vendor service margins and forcing equipment suppliers to differentiate through proprietary diagnostic algorithms rather than geographic service density alone.
Global Industrial Centrifuges Market Segmentation
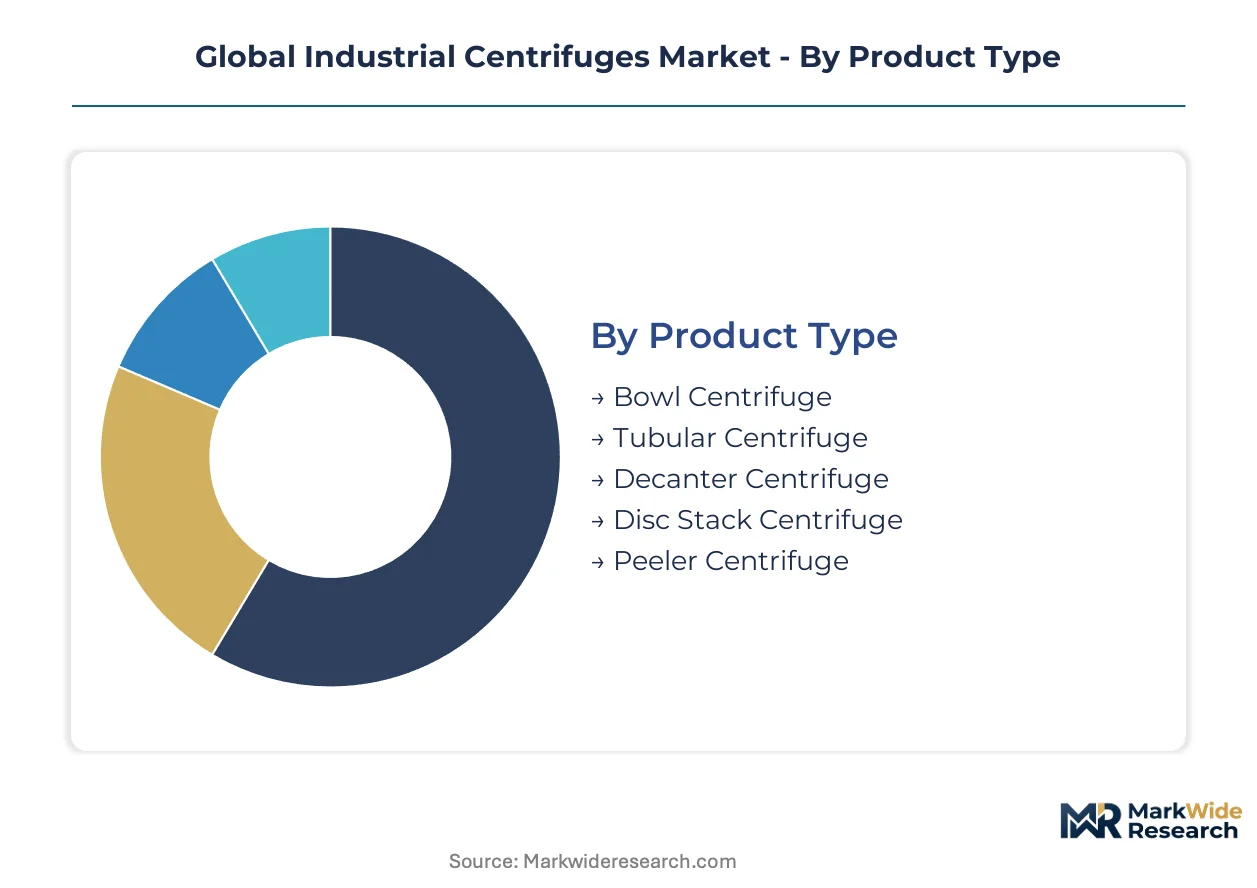
Centrifuge procurement decisions fragment sharply across mechanical configuration, process duty, and regulatory exposure. Specification engineers weight bowl geometry against solids loading, while compliance teams map refrigerant and material restrictions to end-use certification tiers.
Product Type:
Cost tier differentiation separates continuous-duty industrial workhorses from batch pharmaceutical systems with clean-in-place validation.
- Decanter Centrifuge:Horizontal solid-bowl designs with scroll discharge handle high-solids slurries continuously. Wastewater treatment facilities in Germany and China specify these for municipal sludge dewatering under tightening EU Green Deal discharge benchmarks.
- Disc Stack Centrifuge:Conical plate assemblies generate high g-force for liquid-liquid-solid separation in hermetic configurations. Pharmaceutical corridors around Hyderabad and Ahmedabad concentrate demand for GMP-compliant units with magnetic bearing seals.
- Bowl Centrifuge:Cylindrical or conical bowls for batch or semi-continuous operation in chemical processing.
- Tubular Centrifuge:High-speed vertical rotors for fine particle recovery in biotechnology and vaccine purification.
- Peeler Centrifuge:Batch discharge systems for crystalline solids in fine chemical and API manufacturing.
Decanter configurations command the established base. The steepest expansion runs through disc stack units.
Technology:
Application severity dictates technology selection, with abrasive mining duty at one extreme and aseptic pharmaceutical processing at the other.
- Solid Bowl:Single-piece rotating assemblies without internal conveyors suit simple clarification tasks. Mining tailings recovery in Brazil deploys abrasion-resistant solid bowls for iron ore and phosphate processing.
- Scroll:Helical conveyors differentially rotate within the bowl to discharge settled solids continuously. Oilfield solids control operators on the US Gulf Coast favor scroll mechanisms for drilling mud reclamation under EPA effluent guidelines.
- Pusher:Reciprocating plates advance solids through perforated screens for washing and dewatering.
- Basket:Perforated vertical bowls with manual or automated discharge for batch crystallization.
- Horizontal:Low-center-of-gravity mounting for high-throughput continuous duty.
- Vertical:Space-efficient orientation for cleanroom and containment applications.
Scroll technology anchors heavy-industry procurement. Magnetic-bearing horizontal designs are climbing the fastest.
Application:
Regulatory intensity varies dramatically across process streams, with pharmaceutical and food contact imposing material and documentation burdens absent in mining or petroleum.
- Wastewater Treatment:Municipal and industrial effluent processing demands continuous, unattended operation. German facilities upgrade decanter installations to meet EU Green Deal industrial emissions benchmarks for chemical and food processor discharge.
- Pharmaceuticals Purification:Active ingredient recovery and vaccine clarification require validated cleanability. India's CDSCO enforcement of GMP standards drives disc stack procurement with platinum-cured silicone seals replacing restricted elastomers.
- Chemicals Processing:Solvent recovery and catalyst separation in continuous manufacturing.
- Food & Beverage Separation:Dairy fat standardization and beverage clarification with hygienic design certification.
- Oil & Gas Extraction:Produced water treatment and drilling fluid recycling in upstream operations.
Wastewater treatment commands the established base. Pharmaceutical purification is gaining share fastest.
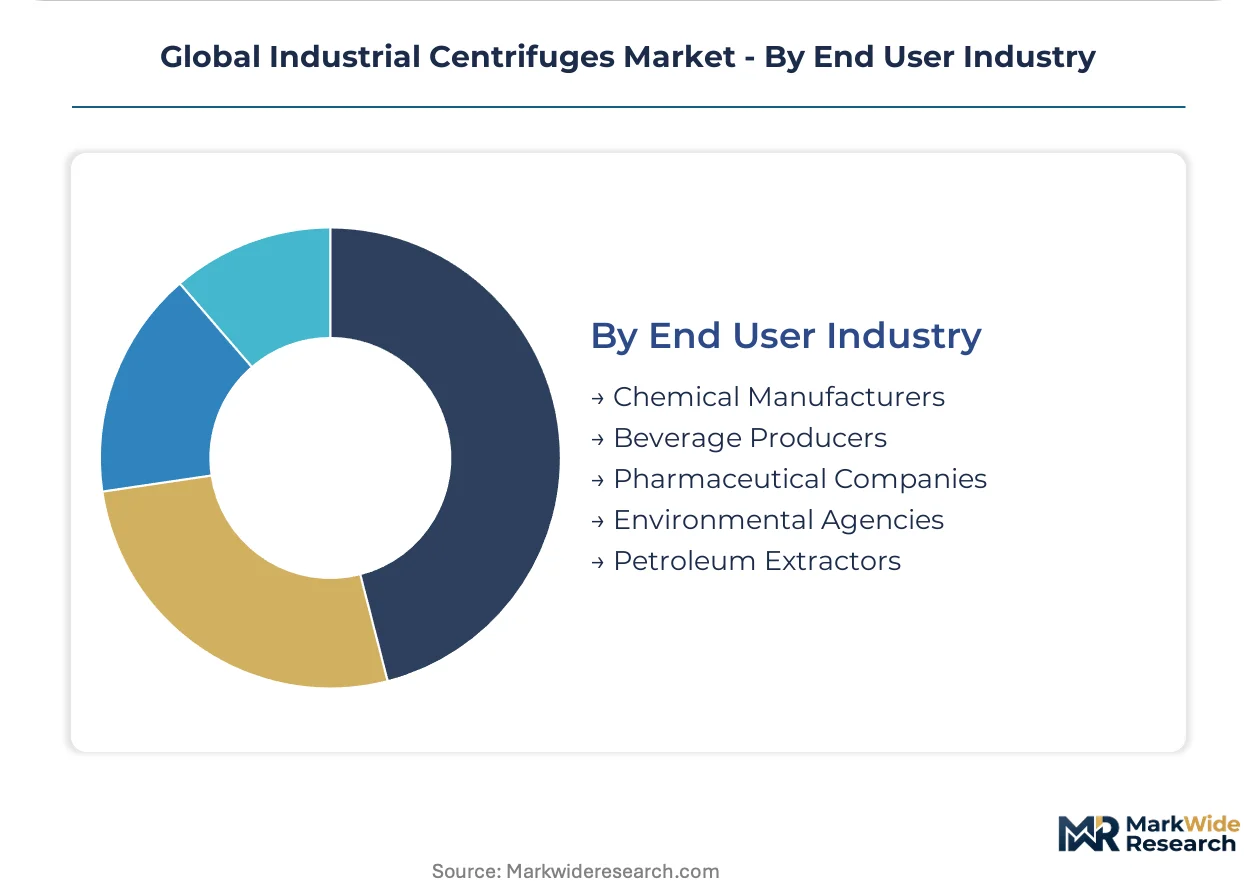
End User Industry:
Customer type determines procurement sophistication, with multinational chemical operators bundling predictive maintenance against fragmented municipal purchasing.
- Environmental Agencies:Municipal wastewater authorities specify for lifecycle cost under constrained capital budgets. China's MEE dual carbon goals accelerate replacement of aging high-consumption separation units in provincial treatment networks.
- Pharmaceutical Companies:Global manufacturers demand validated equipment with digital twin integration for predictive maintenance. Swissmedic and EMA inspection protocols shape specification for barrier fluid systems and magnetic bearing documentation.
- Chemical Manufacturers:Process-scale separation for intermediates and specialty chemicals.
- Beverage Producers:Hygienic clarification for brewing, dairy, and soft drink operations.
- Petroleum Extractors:Upstream solids control and produced water management.
Environmental agencies command the established base. Pharmaceutical companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German centrifuge manufacturers export decanter and disc stack systems to wastewater treatment networks across China and India, while US Gulf Coast petrochemical operators import European hygienic designs for pharmaceutical-grade separations.
Germany
Rhineland chemical processors and Bavarian dairy cooperatives drive specification of magnetic-bearing disc stack units. The EU F-Gas Regulation constrains refrigerant cooling architectures in temperature-controlled pharmaceutical applications. Stuttgart-area engineering clusters concentrate aftermarket service capabilities for predictive maintenance integration.
China
Provincial wastewater authorities in Jiangsu and Shandong provinces replace aging high-consumption separation units. The MEE dual carbon goals mandate energy efficiency thresholds for industrial equipment above specified power ratings. Yangtze River Delta manufacturing corridors scale domestic purification capacity for pharmaceutical intermediates.
United States
Gulf Coast petrochemical clusters and Permian Basin oilfield operators compel upgrades to legacy separation infrastructure. The EPA enforces effluent limitation guidelines for chemical manufacturers and petroleum extractors. Houston-area engineering contractors bundle predictive maintenance software with mechanical hardware procurement.
India
Hyderabad and Ahmedabad pharmaceutical corridors concentrate demand for GMP-compliant disc stack centrifuges with clean-in-place validation. The CDSCO enforces domestic manufacturing standards for active ingredient recovery equipment. Gujarat chemical processing zones expand solvent recovery and catalyst separation capacity.
Brazil
Iron ore and phosphate processors in Minas Gerais deploy abrasion-resistant decanter units for mining tailings recovery. ANVISA pharmaceutical regulations shape material specifications for food-contact and hygienic applications. São Paulo-state engineering distributors anchor aftermarket service relationships for South American mining operations.
Global Industrial Centrifuges Market Competitive Landscape
On the supply side, the industry is consolidating around engineering-intensive specialists with vertical control over bowl metallurgy and aftermarket service networks. Three archetypes dominate: European hygienic design houses with magnetic-bearing expertise, German and Austrian mining-duty fabricators with abrasion-resistant bowl technology, and diversified process equipment conglomerates with marine and industrial separation heritage. Competitive moves center on predictive maintenance software bundling and geographic expansion into underpenetrated mining jurisdictions.
Within the European hygienic tier, ALFA LAVAL and GEA Group Aktiengesellschaft exemplify engineering-intensive positioning where validated clean-in-place systems command premium pricing. ANDRITZ occupies a distinct archetype as an Austrian-based diversified technology group with mining and minerals processing heritage. These three anchors represent contrasting strategic vectors: marine-industrial separation heritage, dairy-brewery hygienic specialization, and abrasive-duty bowl durability respectively.
| Leading Market Players |
|---|
| ALFA LAVAL |
| GEA Group Aktiengesellschaft |
| ANDRITZ |
| FLSmidth A/S |
| Flottweg SE |
| Mitsubishi Kakoki Kaisha, Ltd. |
| SPX FLOW, Inc. |
| Ferrum AG |
| SIEBTECHNIK TEMA GmbH |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese stainless-steel bowl fabrication is compressing margins for mid-tier decanter suppliers while simultaneously enabling aggressive pricing postures from European hygienic-design specialists who source selectively from premium-grade German and Austrian foundries.
Pricing Analysis
Current-generation magnetic-bearing disc stack units command 40-60% premiums over oil-lubricated prior-generation equivalents, while next-generation AI-integrated predictive maintenance bundles are reshaping contract structures toward subscription-based service revenues. Pricing stratifies across premium, standard, and economy tiers where magnetic-bearing hermetic configurations with platinum-cured silicone seals anchor the premium band, commodity scroll decanters with standard elastomers occupy the economy tier, and mid-range solid-bowl units with conventional bearings fill the standard segment. Cost compression in the economy tier is intensifying because Indonesian nickel supply volatility feeds through to duplex stainless input costs. Municipal wastewater authorities in China exhibit the highest price sensitivity due to constrained capital budgets, while pharmaceutical multinationals in Switzerland and Germany demonstrate the lowest sensitivity given validation requirements and lifecycle cost optimization priorities.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized foundries in Germany, Austria, and select Japanese engineering clusters that retain captive capacity for high-alloy bowl casting and precision machining. Geographic supply concentration centers on Germany for magnetic-bearing assemblies, Austria for mining-duty abrasion-resistant bowls, and China for standard stainless-steel components and electric drive systems. Raw material dependencies draw from Indonesian nickel mining, Russian molybdenum concentrate, and Chinese rare-earth magnet supply for high-speed motor integration. Single-source vulnerability in superalloy feedstock creates exposure to export restriction cascades. Distribution runs through OEM-direct channels for pharmaceutical and food applications, regional engineering distributors for mining and wastewater sectors, and integrated service contractors for oilfield solids control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of qualified magnetic-bearing engineering talent and validated clean-in-place system integration expertise is concentrating competitive advantage among incumbent European specialists, creating asymmetric returns for firms that capture this capability base.
For Market Incumbents: Build predictive-maintenance software moats by bundling proprietary vibration-monitoring AI with equipment sales, compressing third-party service displacement. Incumbents should anchor high-margin aftermarket contracts through exclusive diagnostic algorithm access while accelerating backward integration into superalloy bowl casting to offset Indonesian nickel price volatility. Membrane filtration substitution in beverage and bioprocessing segments represents the primary substitute technology threat requiring continuous R&D differentiation in shear-tolerance performance. For New Entrants and Emerging Players: Brazilian mining tailings recovery operations represent the most penetrable entry point for abrasion-resistant decanter specialists, given underpenetrated installed base and limited local fabrication capacity. Secondary white-space targets include mid-scale Indian pharmaceutical manufacturers seeking GMP-compliant disc stack units with domestic service support. A go-to-market angle anchored to outcome-based performance contracts—guaranteeing solids recovery rates or energy consumption thresholds—can bypass incumbent service network advantages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European hygienic-design specialists with established pharmaceutical validation protocols and captive aftermarket service networks. Long-term viability across the analysis window favors acquisition targets with demonstrated magnetic-bearing integration capabilities and regulatory dossier depth for FDA and EMA pharmaceutical applications. The signal to watch is CDSCO enforcement intensity in Indian pharmaceutical corridors, which will accelerate demand for validated equipment and compress unqualified supplier margins.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Migration | Eliminates lubrication contamination risks in aseptic pharmaceutical and dairy processing applications. |
| Predictive Maintenance Platform Integration | Enables outcome-based service contracts that capture lifecycle value beyond initial equipment sale. |
| Superalloy Bowl Casting Backward Integration | Reduces exposure to Indonesian nickel and Russian molybdenum supply concentration volatility. |
| GMP Validation Dossier Investment | Secures pharmaceutical procurement preference under Swissmedic and EMA inspection protocols. |
| Brazilian Mining Service Network Expansion | Captures tailings recovery demand from iron ore and phosphate processors in Minas Gerais. |
Research Methodology
A spread of perspectives from plant engineers at wastewater treatment facilities, procurement leads at pharmaceutical manufacturers, aftermarket service heads at OEMs, and technical directors at process engineering consultants converged on the working assumptions. Primary fieldwork combined structured interviews with maintenance directors and brownfield project managers across German, Chinese, and US Gulf Coast installations. Secondary validation drew from EPA effluent guideline filings, EU ECHA substance restriction updates, CDSCO manufacturing standard circulars, and customs trade data for centrifuge equipment imports. Bottom-up unit economics triangulated against top-down industry spending estimates anchored the market sizing.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling installed base replacement cycles against greenfield capacity additions in pharmaceutical and mining corridors. Segmentation dimensions included mechanical configuration type, process duty severity, regulatory certification tier, and geographic manufacturing cluster. CAGRs were derived from slope-intercept modeling of historical shipment data against announced capacity expansions and regulatory mandate timelines. Industry-specific forecast inputs incorporated MEE dual carbon goal implementation schedules and EU F-Gas Regulation phase-down calendars for refrigerant-dependent cooling architectures.
Practitioners should monitor nickel and molybdenum price volatility, REACH substance restriction expansions, and membrane filtration technology cost curves for early signals of forecast revision. Quarterly review of OEM order backlogs, provincial wastewater authority procurement announcements in China, and pharmaceutical corridor investment permits in India is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Electric Actuator Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Seismic Data Acquisition Equipment Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Industrial Marking Equipment Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Spherical Roller Bearings Market