
 Embedded Biometric Sensor Market | 2026-2036
Embedded Biometric Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Biometric Sensor Market Insights
Multi-source procurement for biometric ASICs is hardening as OEMs hedge against supply concentration risk. Infineon Technologies anchors European automotive and industrial fingerprint module supply through its security chip foundry footprint. Shenzhen Goodix Technology dominates capacitive sensor shipments to Chinese smartphone brands, while Fingerprint Cards AB specializes in ultrathin formats for wearable devices.
An embedded biometric sensor integrates fingerprint, facial, iris, or voice-capture hardware with onboard signal processing and encryption, typically fabricated on silicon substrates between 50 and 500 micrometers thick for seamless device integration. Fingerprint sensors command the largest product-type volume, though facial recognition modules capture disproportionate value in premium smartphone tiers. Capacitive technology retains manufacturing scale advantages, while ultrasonic sensing penetrates high-end handsets where moisture tolerance and spoof resistance justify unit cost premiums.
EU GDPR and the EU AI Act constrain facial recognition deployment in public and financial contexts, pushing vendors toward on-device processing and anonymized templates. FDA guidance on biometric patient identification in healthcare settings shapes product validation requirements for clinical-grade sensors. NHTSA and OEM cybersecurity standards are extending into vehicle cabin authentication, creating new compliance baselines that suppliers must meet to access automotive programs. Stakeholders should track which regulatory domains adopt biometric-specific certification regimes, as these will determine market-access sequencing and R&D allocation across product lines.
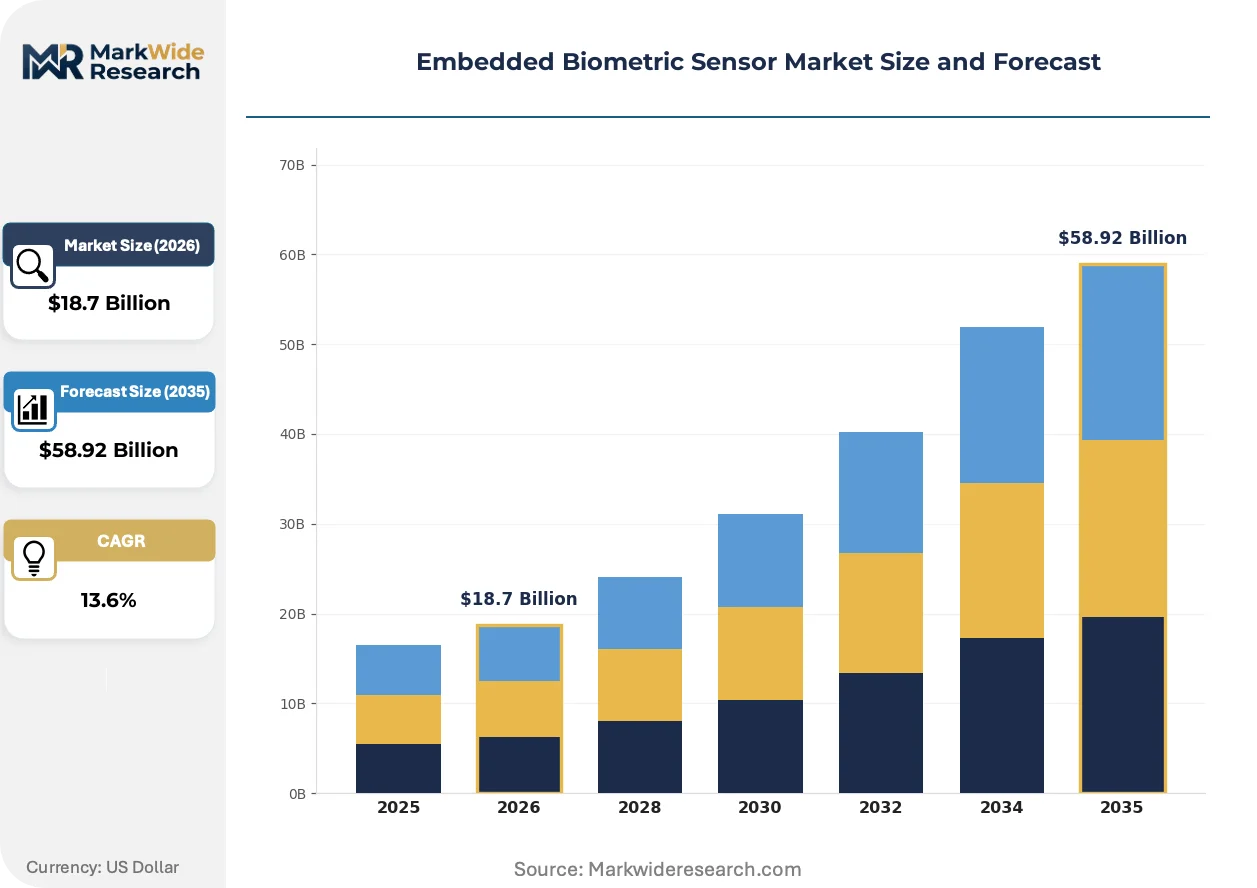
Market Dynamics
Financial regulators across multiple jurisdictions now mandate stronger customer authentication, forcing smartphone OEMs to embed biometric modules as default hardware rather than premium-tier options. This regulatory compression is accelerating sensor integration into mid-range devices and expanding addressable hardware volumes beyond flagship tiers.
Growth Catalysts
- EU AI Act compliance:Facial recognition deployments in European financial services must process biometric data on-device, creating pull for embedded modules with local template storage and encryption.
- Automotive cabin authentication:NHTSA cybersecurity standards now extend to driver monitoring and personalized vehicle access, opening embedded fingerprint and iris modules to tier-1 automotive programs.
- Capacitive sensor manufacturing scale:Mature 8-inch wafer processing lines in East Asia deliver unit economics that ultrasonic alternatives cannot match for sub-premium smartphone tiers.
Market Restraints
- Silicon substrate cost volatility:Polished silicon wafer prices fluctuate with semiconductor cycle swings, compressing gross margins for sensor fabs operating at 50-500 micrometer thickness specifications.
- GDPR template storage requirements:European data minimization rules limit cloud-based biometric matching, forcing costly on-device secure element integration that adds BOM complexity.
- Optical facial recognition substitution:Structured-light and time-of-flight camera arrays in premium handsets reduce reliance on dedicated biometric sensors for certain authentication workflows.
Strategic Opportunities
- India PLI scheme localization:Smartphone assembly incentives under India's production-linked initiative create demand for domestic biometric module sourcing to satisfy local content thresholds.
- Wearable health convergence:Ultrathin fingerprint sensors combined with photoplethysmography enable continuous patient identification in clinical remote monitoring devices.
- ISO/IEC 30107-3 certification:Presentation attack detection standards create tiered product positioning where certified modules command preferential placement in banking and government procurement.
Industry Challenges
- Spoof resistance engineering talent:Deep expertise in liveness detection algorithm development concentrates among a small pool of specialists, constraining R&D velocity for second-tier vendors.
- FDA 510(k) validation timelines:Clinical-grade biometric sensors for patient identification face extended regulatory review cycles that delay product launches against consumer electronics cadences.
- Automotive qualification protocols:AEC-Q100 stress testing and OEM cybersecurity audits demand 18-24 month pre-production cycles unfamiliar to consumer sensor suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Biometric Sensor Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Sensors, Facial Recognition Modules, Iris Scanners, Voice Recognition Systems Application: Smartphones, Wearable Devices, Access Control Systems, Financial Services Technology: Optical, Capacitive, Ultrasonic, Thermal End User: Government, Healthcare, Banking, Retail |
| Companies Covered | IDEMIA, Infineon Technologies, Fingerprint Cards AB, Synaptics Incorporated, NEC Corporation, IDEX Biometrics ASA, Shenzhen Goodix Technology, Fujitsu, Egis Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Biometric Sensor Market Trends and Innovations
Ultrasonic sensing architectures are absorbing development resources as manufacturers chase moisture tolerance and sub-surface fingerprint reading capabilities. Three interconnected developments are restructuring competitive positioning and procurement patterns.
Ultrasonic fingerprint sensors employ piezoelectric transducers to penetrate epidermal layers and capture three-dimensional ridge detail. Automotive OEMs adopting NHTSA cabin authentication standards are specifying these modules for steering wheel and center console integration. The technology is absorbing premium-tier smartphone allocation that capacitive alternatives once dominated.
GDPR and the EU AI Act now classify biometric data as special category information requiring explicit consent and purpose limitation. Financial institutions in Germany and France must demonstrate on-device processing with no cloud template transmission. Banks are responding by specifying embedded secure elements from European-certified foundries rather than generic ASICs.
Chinese smartphone brands now consolidate biometric sensor procurement through captive supply arrangements with domestic module houses. Tier-1 OEMs in Shenzhen and Beijing negotiate multi-year volume commitments that lock out second-source qualification. This concentration is most visible in the 150-400 USD smartphone tier where fingerprint sensors ship as standard configuration.
Embedded Biometric Sensor Market Segmentation
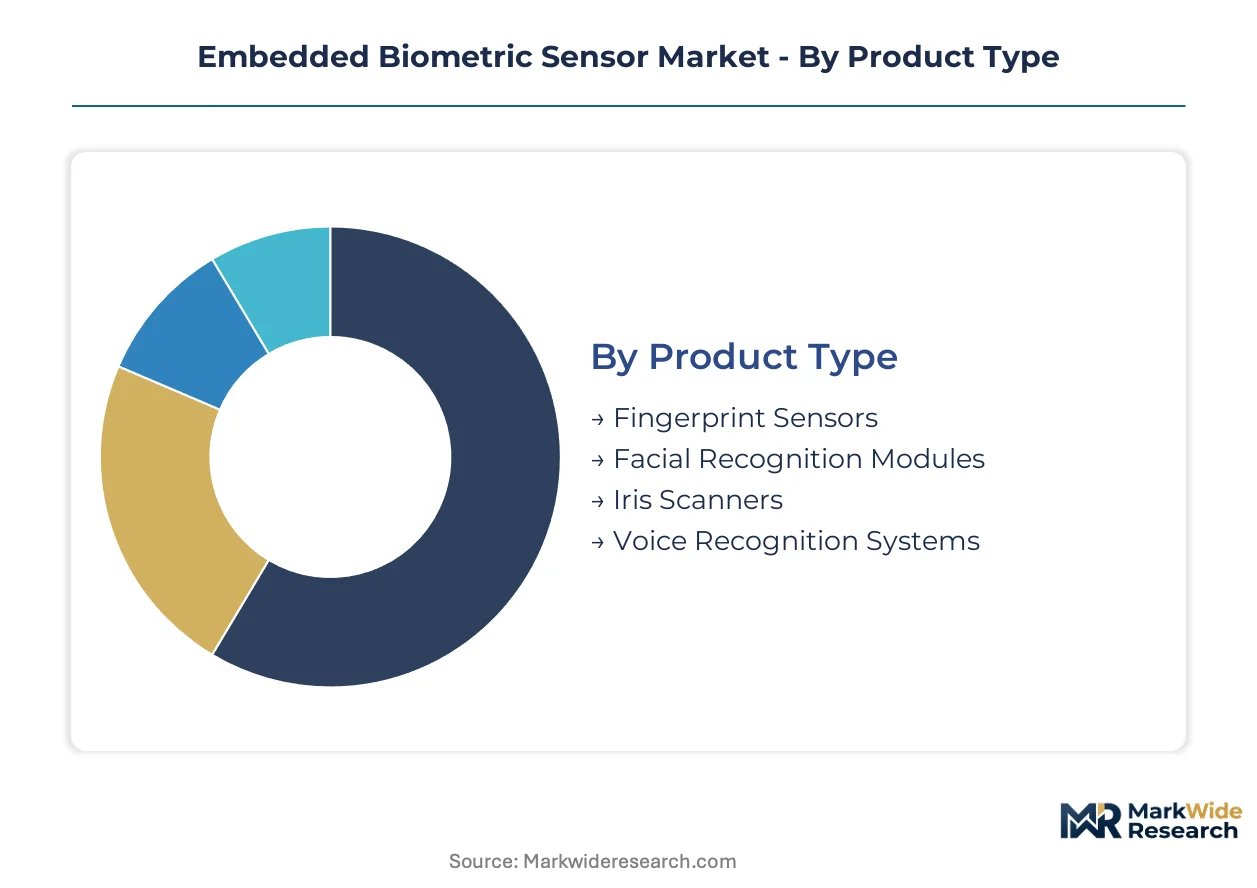
Embedded biometric sensors fragment across four dimensions that determine procurement economics and R&D allocation. Product type and technology choices drive unit cost structures, while application and end-user segments dictate compliance requirements and certification depth.
Product Type:
Fingerprint sensors dominate unit shipments while facial recognition modules command premium pricing in flagship tiers.
- Fingerprint Sensors:Capacitive and ultrasonic variants fabricated on silicon substrates between 50 and 500 micrometers thick. Chinese smartphone OEMs in Shenzhen and Beijing specify these as standard configuration across the 150-400 USD tier, locking in multi-year volume commitments with domestic module houses.
- Facial Recognition Modules:Structured-light and time-of-flight arrays with onboard neural processing for 3D depth mapping. EU financial institutions under GDPR and the EU AI Act mandate on-device template storage, pulling demand toward European-certified secure element integration.
- Iris Scanners:Near-infrared imaging systems for high-assurance authentication in government and defense applications.
- Voice Recognition Systems:Microphone arrays with speaker identification algorithms for hands-free device access.
Today's leader: Fingerprint Sensors. Tomorrow's challenger: Facial Recognition Modules.
Application:
Smartphone integration sets baseline volumes; automotive and healthcare applications impose divergent qualification timelines.
- Smartphones:The default deployment channel where regulatory compression from financial authorities has shifted biometric hardware from premium-tier option to mid-range standard. NHTSA cybersecurity standards now extend this specification logic into vehicle cabin authentication programs.
- Wearable Devices:Ultrathin form factors below 200 micrometers enable continuous biometric monitoring in smartwatches and clinical remote patient identification systems. FDA 510(k) validation timelines stretch product launches against consumer electronics cadences.
- Access Control Systems:Enterprise and residential entry points requiring ISO/IEC 30107-3 presentation attack detection certification.
- Financial Services:Banking terminals and payment devices with stringent EU GDPR template storage requirements forcing on-device secure element integration.
Smartphones anchor current procurement volumes; Wearable Devices are climbing the fastest as health convergence accelerates.
Technology:
Manufacturing maturity separates cost-optimized from performance-premium technology selections.
- Capacitive:Mature 8-inch wafer processing lines in East Asia deliver unit economics that alternatives cannot match for sub-premium smartphone tiers.
- Ultrasonic:Piezoelectric transducers penetrating epidermal layers for moisture-tolerant, spoof-resistant authentication. Automotive OEMs specify these for steering wheel and center console integration under NHTSA standards.
- Optical:CMOS-based imaging for cost-sensitive applications with moderate security requirements.
- Thermal:Temperature differential sensing for liveness detection in high-assurance deployments.
Capacitive technology holds manufacturing scale; Ultrasonic architectures gain share fastest in premium tiers.
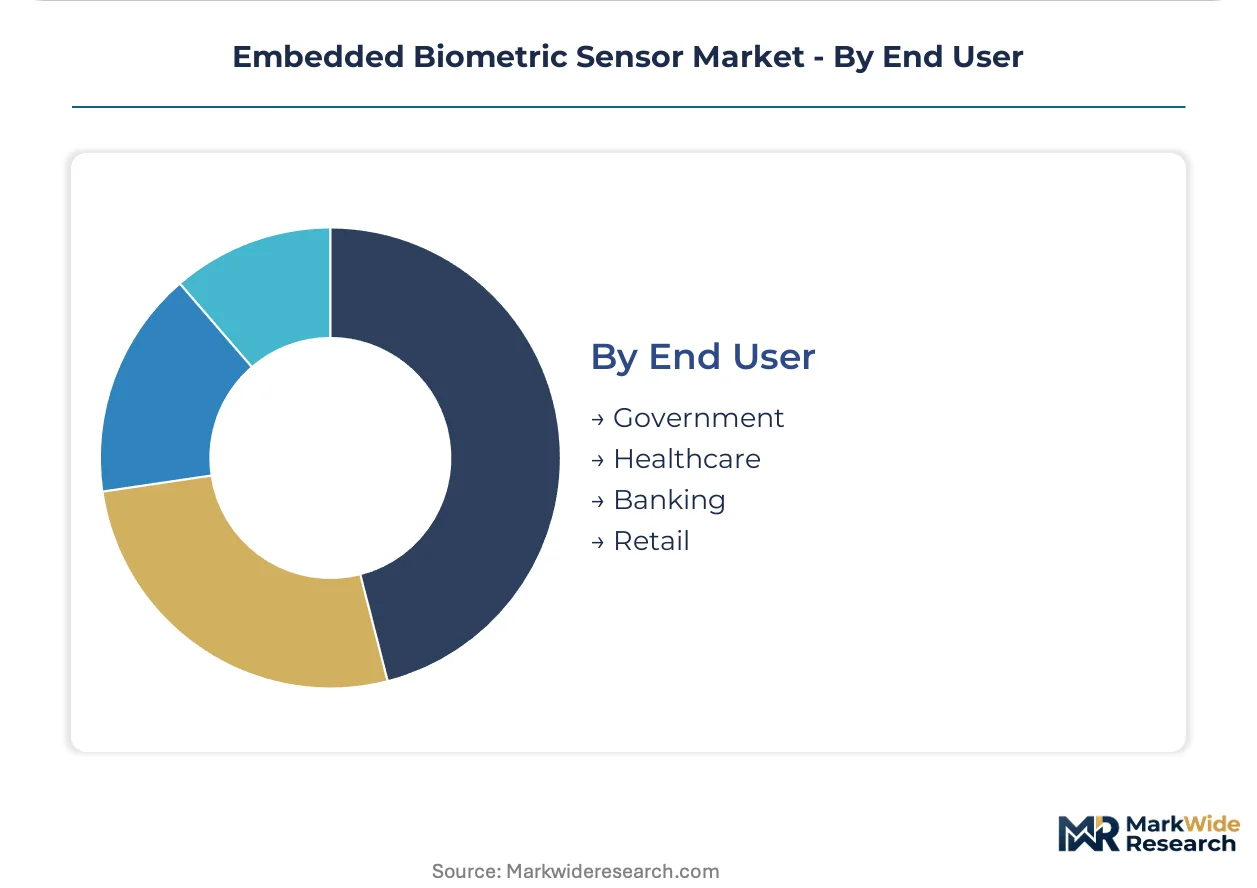
End User:
Regulatory jurisdiction determines certification depth and procurement channel structure.
- Government:National ID and border control systems requiring ISO/IEC 30107-3 presentation attack detection and extended environmental stress testing.
- Healthcare:Clinical patient identification devices facing FDA validation cycles and HIPAA biometric data handling constraints.
- Banking:Financial terminals governed by GDPR special category data rules and explicit consent requirements in Germany and France.
- Retail:Point-of-sale and loyalty authentication with lighter compliance burdens but price-sensitive procurement.
Healthcare and Banking segments impose the steepest compliance barriers; Retail offers volume scale with thinner margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Beijing anchor global biometric sensor procurement through captive supply arrangements with domestic module houses. Smartphone OEMs in these clusters negotiate multi-year volume commitments that lock out second-source qualification. Regulatory compression from financial authorities across multiple jurisdictions now embeds biometric hardware as standard configuration rather than premium-tier option.
China
Capacitive fingerprint sensor manufacturing concentrates in Shenzhen and Dongguan, where 8-inch wafer processing lines deliver unit economics unmatched elsewhere. MIIT cybersecurity standards mandate hardware-level encryption for domestic smartphone authentication. Beijing-based OEMs consolidate procurement through Goodix Technology and other domestic suppliers, locking in multi-year volume commitments across the 150-400 USD device tier.
United States
NHTSA cybersecurity standards now extend to driver monitoring and personalized vehicle access, opening automotive cabin authentication programs to embedded sensor suppliers. FDA guidance shapes clinical-grade sensor validation requirements for healthcare biometric applications. California and Texas host the primary automotive OEM engineering centers specifying these modules for steering wheel integration.
Germany
GDPR special category data rules and the EU AI Act constrain facial recognition deployment in financial services, forcing on-device processing with local template storage. KBA automotive standards intersect with NHTSA-aligned cybersecurity protocols for vehicle cabin authentication. Bavaria hosts Infineon Technologies' security chip foundry operations serving European automotive and industrial fingerprint module demand.
India
Smartphone assembly incentives under the PLI scheme create demand for domestic biometric module sourcing to satisfy local content thresholds. RBI authentication mandates for digital payments accelerate sensor integration into mid-range devices. Tamil Nadu and Karnataka manufacturing clusters attract module houses establishing captive supply for export-oriented OEM assembly operations.
South Korea
Ultrasonic fingerprint sensor adoption in premium handsets drives moisture-tolerant authentication specifications for flagship device tiers. MFDS medical device regulations shape clinical-grade sensor development for healthcare applications. Seoul-based OEMs specify these modules for devices targeting export markets with stringent spoof-resistance requirements.
Embedded Biometric Sensor Market Competitive Landscape
Global majors compete with regional champions across technology licensing and foundry access. The vendor base organizes around three tiers: European automotive-security specialists, Chinese smartphone-scale suppliers, and Nordic wearable-format innovators. Strategic differentiation concentrates on secure element certification depth, wafer processing scale, and presentation attack detection algorithm sophistication. Competitive moves center on captive supply arrangements with tier-1 OEMs and multi-year volume commitments that foreclose second-source qualification.
Within the European automotive-security tier, Infineon Technologies anchors supply through its security chip foundry footprint. Shenzhen Goodix Technology exemplifies the Chinese smartphone-scale archetype with dominant capacitive sensor shipments to domestic brands. Fingerprint Cards AB occupies the Nordic wearable-format position, specializing in ultrathin sensor configurations for devices below 200 micrometers thickness. These three represent distinct competitive vectors: certification-heavy automotive programs, volume-driven mobile procurement, and form-factor-constrained health convergence applications.
| Leading Market Players |
|---|
| IDEMIA |
| Infineon Technologies |
| Fingerprint Cards AB |
| Synaptics Incorporated |
| NEC Corporation |
| IDEX Biometrics ASA |
| Shenzhen Goodix Technology |
| Fujitsu |
| Egis Technology |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ISO/IEC 30107-3 validated modules and uncertified alternatives manifests in both unit economics and sourcing geography. Premium-tier ultrasonic sensors with presentation attack detection certification command foundry allocation from European automotive-security suppliers, while uncertified capacitive alternatives flow through Shenzhen module houses serving price-constrained smartphone OEMs.
Pricing Analysis
Polished silicon wafer cost pass-through determines margin compression across the 50-500 micrometer thickness specification range. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade ultrasonic modules with AEC-Q100 validation from mid-tier smartphone capacitive sensors and commodity optical alternatives. Pricing pressure stems from 8-inch wafer processing overcapacity in East Asia compressing quotes for sub-premium tiers. Mid-range smartphone OEMs exhibit highest price sensitivity, while NHTSA-aligned automotive programs tolerate premium positioning for cybersecurity compliance.
Supply Chain Analysis
India's PLI scheme local content thresholds and China's MIIT cybersecurity mandates are reshaping module sourcing toward domestic foundry partnerships. Manufacturing gravity centers on China, South Korea, and Taiwan, where 8-inch wafer lines feed capacitive sensor die production. Supply chains draw from silicon substrate suppliers, piezoelectric transducer material providers, and secure element foundries. Single-source vulnerability concentrates in European secure element capacity for GDPR-compliant facial recognition modules. Distribution runs through tier-1 OEM captive supply arrangements rather than open merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded biometric sensors function as a stable compounder anchored by regulatory compression from financial authorities mandating stronger customer authentication across device tiers. This structural demand driver sustains volume visibility independent of discretionary consumer spending cycles.
For Market Incumbents: Lock in multi-year volume commitments with Chinese smartphone OEMs before India's PLI scheme matures domestic module alternatives. Deepen backward integration into 8-inch wafer processing to defend margin position against silicon substrate volatility. Prioritize AEC-Q100 certification investment to capture NHTSA-driven automotive cabin authentication specification. For New Entrants and Emerging Players: Capture wearable health convergence white space where ultrathin fingerprint sensors combined with photoplethysmography enable continuous patient identification. India's Tamil Nadu and Karnataka manufacturing clusters offer the most penetrable geography before PLI localization requirements harden. Pursue ISO/IEC 30107-3 certification as the go-to-market angle for banking and government procurement preference. For Investors and Strategic Acquirers: Consolidation pressure builds where spoof resistance engineering talent concentrates among a small specialist pool constraining R&D velocity for second-tier vendors. The market supports 5-10 year compound growth under regulatory authentication mandates. Target acquisition candidates with FDA 510(k) pathway progress or AEC-Q100 pre-qualification completion. Watch for EU AI Act enforcement actions against cloud-based biometric processing as the inflection signal accelerating on-device secure element demand.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Certification Investment | GDPR and EU AI Act compliance now requires European-certified foundry sourcing for financial services deployment. |
| Automotive Qualification Completion | AEC-Q100 stress testing and NHTSA cybersecurity audits unlock tier-1 OEM steering wheel integration programs. |
| India PLI Localization Partnership | Domestic module sourcing satisfies local content thresholds for smartphone assembly incentives under RBI authentication mandates. |
| Presentation Attack Detection R&D | ISO/IEC 30107-3 certification creates preferential placement in banking and government procurement channels. |
| Ultrasonic Architecture Development | Piezoelectric transducer expertise enables moisture-tolerant authentication for premium smartphone and automotive tiers. |
Research Methodology
Multiple input streams — sensor foundry production data, OEM procurement contract disclosures, and regulatory filing analysis — were reconciled across primary interviews with biometric module engineering directors, tier-1 automotive supplier procurement leads, smartphone OEM hardware strategists, and FDA regulatory affairs specialists. Secondary validation incorporated MIIT cybersecurity standards documentation, EU AI Act implementation guidance, NHTSA Federal Motor Vehicle Safety Standards, and SEC 10-K filings from disclosed sensor suppliers. Bottom-up die shipment estimates and top-down OEM bill-of-materials analysis were triangulated to anchor volume figures.
Historical capacity utilization patterns from East Asian 8-inch wafer fabs were cross-referenced against panel input from module house executives to model supply elasticity. Segmentation across the analysis window incorporated product type, technology architecture, application vertical, and regulatory jurisdiction dimensions. CAGRs were derived from regression against smartphone shipment forecasts, automotive cabin authentication penetration curves, and wearable health device adoption rates. Industry-specific inputs included FDA 510(k) approval timelines and AEC-Q100 qualification cycle durations.
Silicon substrate price volatility, EU AI Act enforcement timing uncertainty, and automotive OEM cybersecurity audit backlog are the dominant revision risks that could compress or extend forecast trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Battery Leakage Detection Sensor Market