
 SCR Dosing Control Modules Market | 2026-2036
SCR Dosing Control Modules Market Size, Share, and Industry Trends Forecast 2026-2036
SCR Dosing Control Modules Market Insights
Fleet operator consolidation around large logistics networks is expanding the addressable base for integrated SCR dosing platforms. Bosch leverages its electronics manufacturing scale to serve tier-1 supplier channels across European truck OEMs. Continental AG anchors its position through closed-loop control software embedded in hybrid dosing architectures. Denso Corporation specializes in thermal management integration for Asian commercial vehicle platforms.
SCR dosing control modules regulate urea injection rates into exhaust streams to catalyze nitrogen oxide reduction, typically operating at injection pressures between 5 and 9 bar with pulse-width-modulated solenoid response times under 2 milliseconds. Electronic Control Units capture the dominant share of product value owing to firmware complexity and emissions calibration lock-in with engine control modules. Adaptive Control technology is gaining fastest traction among fleet operators seeking real-time NOx feedback optimization across variable duty cycles. Heavy-Duty Trucks represent the deepest application pool, though Agricultural Equipment is emerging as a retrofit growth corridor driven by non-road engine regulations.
EPA Tier 4 Final standards and the EU Green Deal's transport decarbonization framework shape product certification requirements, while China's MIIT enforces GB VI emission limits that mandate onboard diagnostics integration. NHTSA and the California Air Resources Board coordinate heavy-duty vehicle compliance testing that directly determines module specification thresholds. Stakeholders must monitor regulatory divergence between Euro VII and emerging national standards to anticipate calibration complexity and aftermarket service lifecycle requirements.
Market Dynamics
Fleet operator consolidation around large logistics networks is compressing procurement cycles and forcing module suppliers to integrate predictive maintenance algorithms directly into Electronic Control Unit firmware. This structural shift toward outcome-based uptime guarantees is reshaping supplier-OEM relationships across commercial vehicle platforms.
Growth Catalysts
- Euro VII Standards:The European Commission's proposed emission limits mandate closed-loop NOx monitoring systems that require upgraded dosing control architectures with faster solenoid response calibration.
- Heavy-Duty Truck Fleets:Logistics operators in Germany, China, and the United States are retrofitting existing vehicle pools with adaptive control modules to preempt regulatory non-compliance penalties during recertification cycles.
- Onboard Diagnostics Integration:China's GB VI emission framework requires real-time urea quality sensing and injection fault logging, expanding module functionality beyond basic dosing into full emissions telemetry systems.
Market Restraints
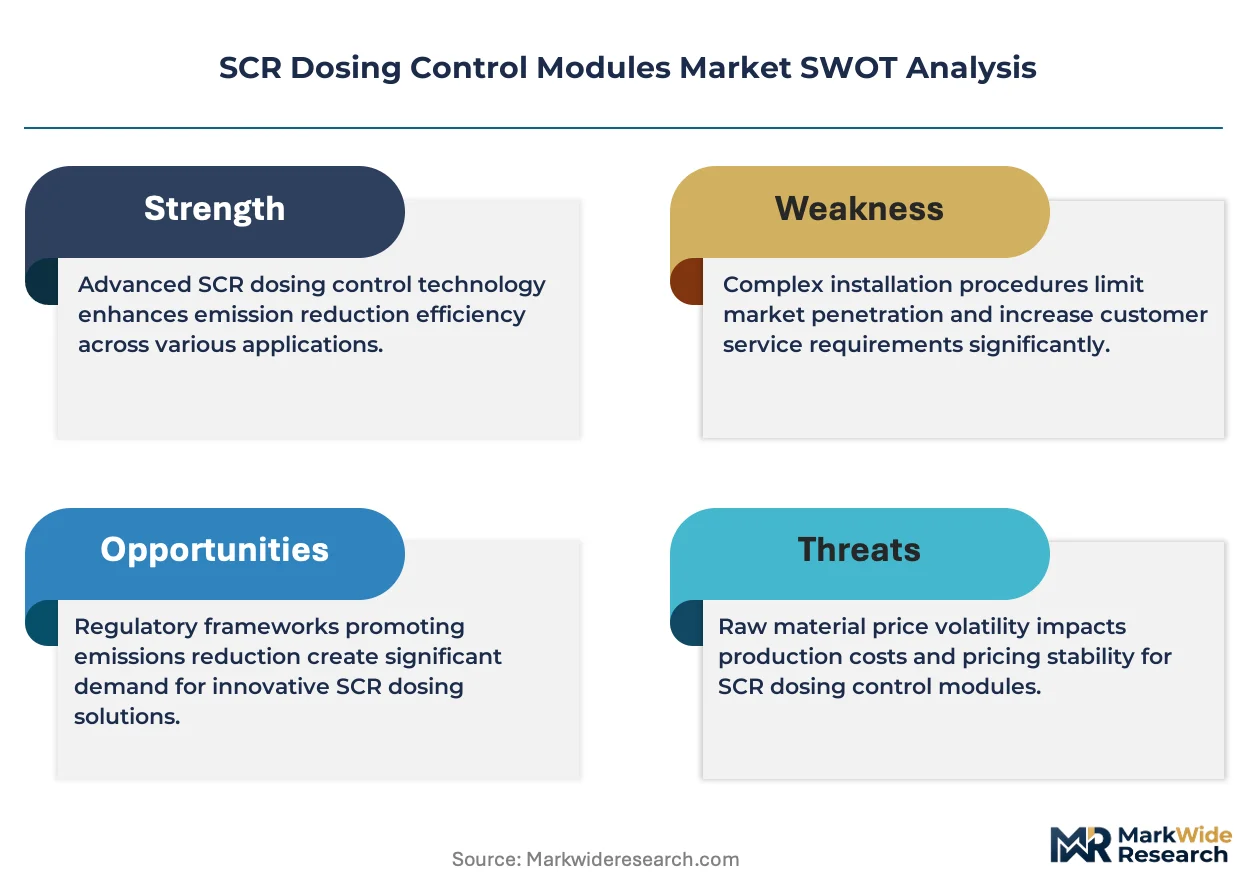
- Platinum Group Metal Volatility:SCR catalyst substrates depend on palladium and rhodium pricing, creating margin pressure for module manufacturers who must absorb or pass through raw material swings.
- Supply Concentration in Semiconductor Foundries:ECU production relies on automotive-grade microcontroller supply from a concentrated East Asian foundry base, exposing dosing system OEMs to allocation risk during capacity crunches.
- Technical Limitation in Cold-Start Performance:Urea crystallization below minus eleven degrees Celsius degrades injection precision, requiring auxiliary heating elements that add cost and complexity to northern climate specifications.
Strategic Opportunities
- Agricultural Equipment Retrofit:Non-road engine regulations in the United States and European Union are extending compliance deadlines to tractors and harvesters, creating a replacement module demand corridor outside traditional on-highway channels.
- Dual-Fuel and Hydrogen-Blend Engines:Convergence between SCR dosing systems and alternative fuel injection architectures enables suppliers to bundle emissions control with fuel flexibility in next-generation powertrain contracts.
- Telematics-Enabled Predictive Service:Fleet management platforms are unbundling after-sales module calibration from OEM service networks, opening direct supplier-to-operator subscription channels for firmware updates and dosing optimization.
Industry Challenges
- Embedded Software Certification Timelines:EPA and CARB validation protocols for ECU firmware revisions extend eighteen to twenty-four months, compressing product refresh windows against accelerating regulatory change cycles.
- Legacy System Integration Friction:Retrofit module installation requires CAN bus protocol adaptation with aging engine control modules from discontinued OEM platforms, demanding costly backward compatibility engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SCR Dosing Control Modules Market |
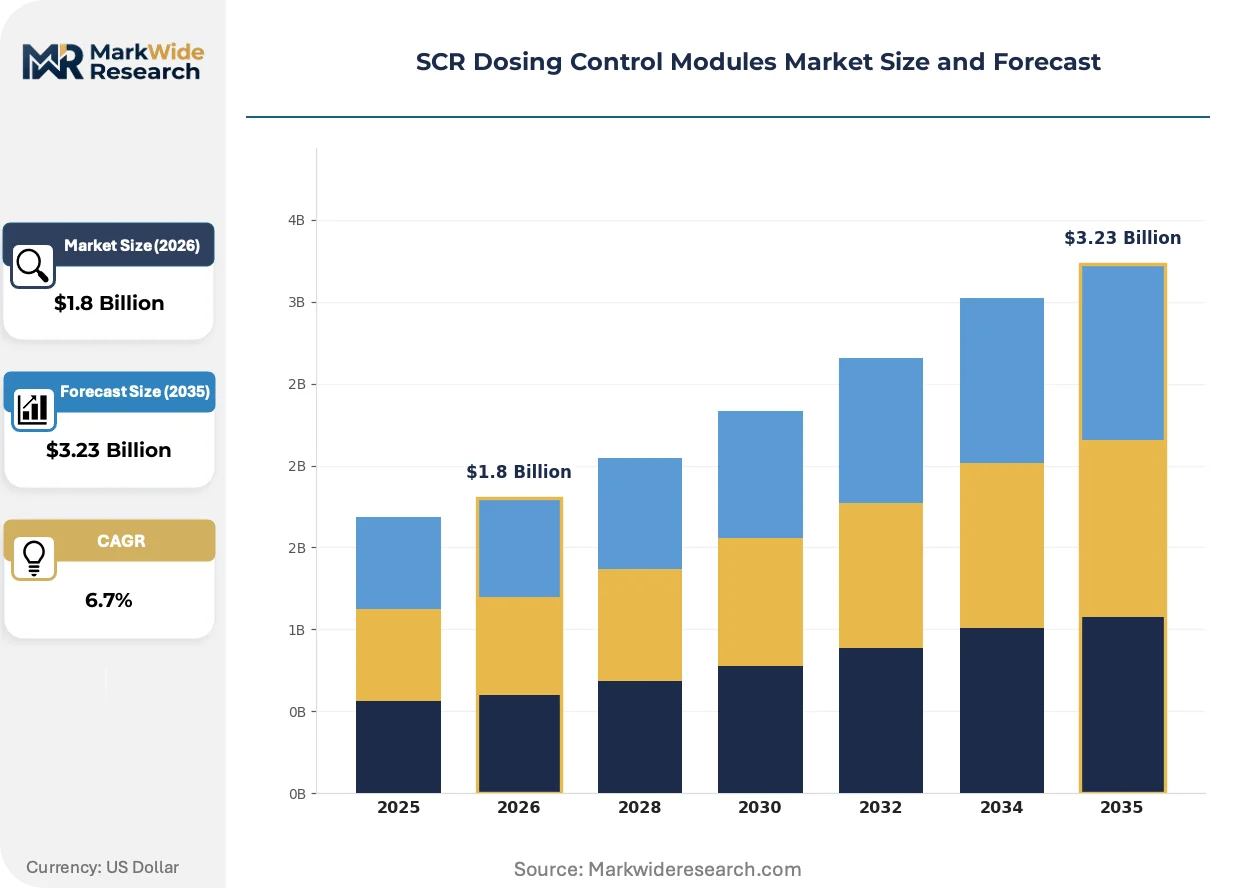
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Control Units, Hydraulic Dosing Modules, Pneumatic Dosing Modules, Hybrid Control Systems Technology: Closed-Loop Control, Open-Loop Control, Adaptive Control, Predictive Control, Feedback Control Application: Heavy-Duty Trucks, Construction Machinery, Agricultural Equipment, Marine Engines, Railroad Locomotives End User: OEMs, Tier-1 Suppliers, Fleet Operators, Aftermarket Service Providers |
| Companies Covered | Bosch, Continental AG, Denso Corporation, Cummins, BorgWarner, FORVIA, Eberspächer Group, Hitachi Astemo, Weichai Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SCR Dosing Control Modules Market Trends and Innovations
Adaptive dosing algorithms are displacing fixed-map injection strategies across commercial vehicle categories. This shift demands continuous recalibration infrastructure and real-time exhaust sensor networks that transform module suppliers into software-telemetry hybrid vendors.
Pulse-width-modulated solenoid technology is rewriting injection precision standards in heavy-duty applications. Bosch and Continental are deploying sub-two-millisecond response actuators in European truck OEM platforms. This capability is compressing the competitive moat around firmware-locked calibration databases.
EPA Tier 4 Final standards and the EU Green Deal transport decarbonization framework are mandating onboard diagnostics integration that exceeds prior hardware-only compliance models. Agricultural equipment manufacturers in the United States face compressed certification timelines for non-road engines. Module suppliers are responding by pre-certifying platform variants across multiple regulatory jurisdictions simultaneously.
Fleet procurement is consolidating around total cost of ownership metrics that weight module durability against urea consumption efficiency. Large logistics operators in Germany are displacing spot-buy replacement patterns with multi-year dosing system service agreements. This behavioral shift is most visible in long-haul trucking networks where fuel and fluid costs dominate operating economics.
SCR Dosing Control Modules Market Segmentation
SCR dosing control module procurement patterns diverge sharply across certification regimes, with EPA Tier 4 Final and Euro VII standards dictating firmware complexity tiers. Module suppliers must architect product portfolios around distinct validation timelines and hardware-software integration depths.
Product Type:
EPA and CARB certification protocols impose eighteen-to-twenty-four-month firmware validation cycles that segment suppliers by embedded software maturity and emissions calibration lock-in capabilities.
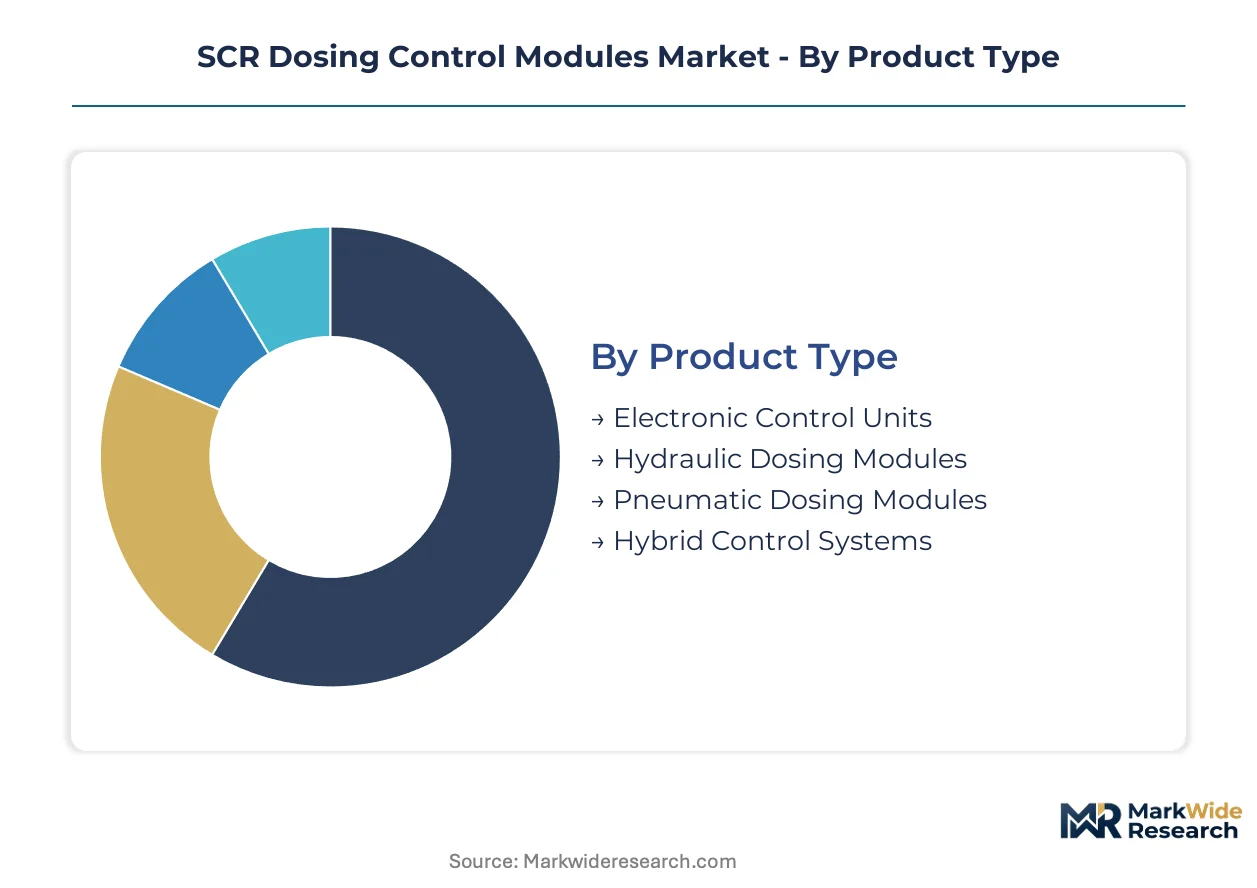
- Electronic Control Units:Firmware-intensive architectures integrating pulse-width-modulated solenoid drivers with real-time NOx sensor feedback loops. Demand concentrates in German and US heavy-duty truck OEM channels where Euro VII and EPA Tier 4 Final mandate closed-loop monitoring with sub-two-millisecond response calibration.
- Hybrid Control Systems:Dual-architecture platforms combining electronic precision with hydraulic backup actuation for mission-critical uptime guarantees. Logistics operators in China and the United States are specifying these for long-haul fleets where GB VI and EPA compliance failures trigger operational penalties.
- Hydraulic Dosing Modules:Pressure-actuated injection systems serving legacy retrofit installations where CAN bus protocol adaptation limits electronic upgrade feasibility.
- Pneumatic Dosing Modules:Compressed-air-driven architectures prevalent in cost-sensitive agricultural equipment segments facing delayed non-road engine compliance deadlines.
Electronic Control Units sit at the top of the volume ranking, with Hybrid Control Systems climbing the fastest.
Technology:
Cost stratification across technology tiers reflects sensor density and telemetry infrastructure requirements, with premium architectures commanding three-to-five-year service contract attachments.
- Adaptive Control:Machine-learning-enabled dosing algorithms recalibrating injection maps across variable duty cycles without manual technician intervention. Fleet operators in Germany and the United States are prioritizing this capability for logistics networks where route diversity degrades fixed-map precision.
- Closed-Loop Control:Real-time exhaust sensor feedback architectures with continuous urea injection adjustment. Euro VII mandates are accelerating specification in European truck OEM platforms where NOx threshold tightening eliminates open-loop tolerance bands.
- Predictive Control:Duty-cycle-anticipating firmware pre-positioning injection timing before load transitions occur.
- Feedback Control:Post-catalyst sensor verification systems providing compliance audit trails for regulatory documentation.
- Open-Loop Control:Engine-map-based dosing without exhaust sensor verification, retaining relevance only in pre-regulatory retrofit corridors.
Closed-Loop Control dominates current procurement volumes, while Adaptive Control is gaining share fastest among large fleet operators.
Application:
Application segmentation tracks regulatory phase-in schedules, with on-highway mandates preceding non-road engine compliance deadlines by three-to-five-year intervals.
- Heavy-Duty Trucks:Long-haul and regional delivery platforms subject to the most stringent in-use emissions testing protocols. Germany, China, and the United States represent the deepest specification pools where NHTSA, MIIT, and KBA coordinate certification reciprocity.
- Agricultural Equipment:Tractors and harvesters entering regulated compliance frameworks under EPA Tier 4 Final and EU non-road engine directives. Retrofit module demand is accelerating in the United States and European Union as original equipment replacement cycles compress.
- Construction Machinery:Excavators and loaders facing delayed but tightening emissions enforcement in urban air quality zones.
- Marine Engines:Harbor craft and inland waterway vessels subject to IMO Tier III standards in coastal jurisdictions.
- Railroad Locomotives:Line-haul and switcher engines under EPA locomotive emissions regulations with extended compliance timelines.
Heavy-Duty Trucks anchor volume procurement, with Agricultural Equipment expanding most quickly as retrofit deadlines approach.
End User:
Customer-type segmentation reveals diverging procurement authority, with fleet operator consolidation shifting specification influence away from traditional OEM channels.
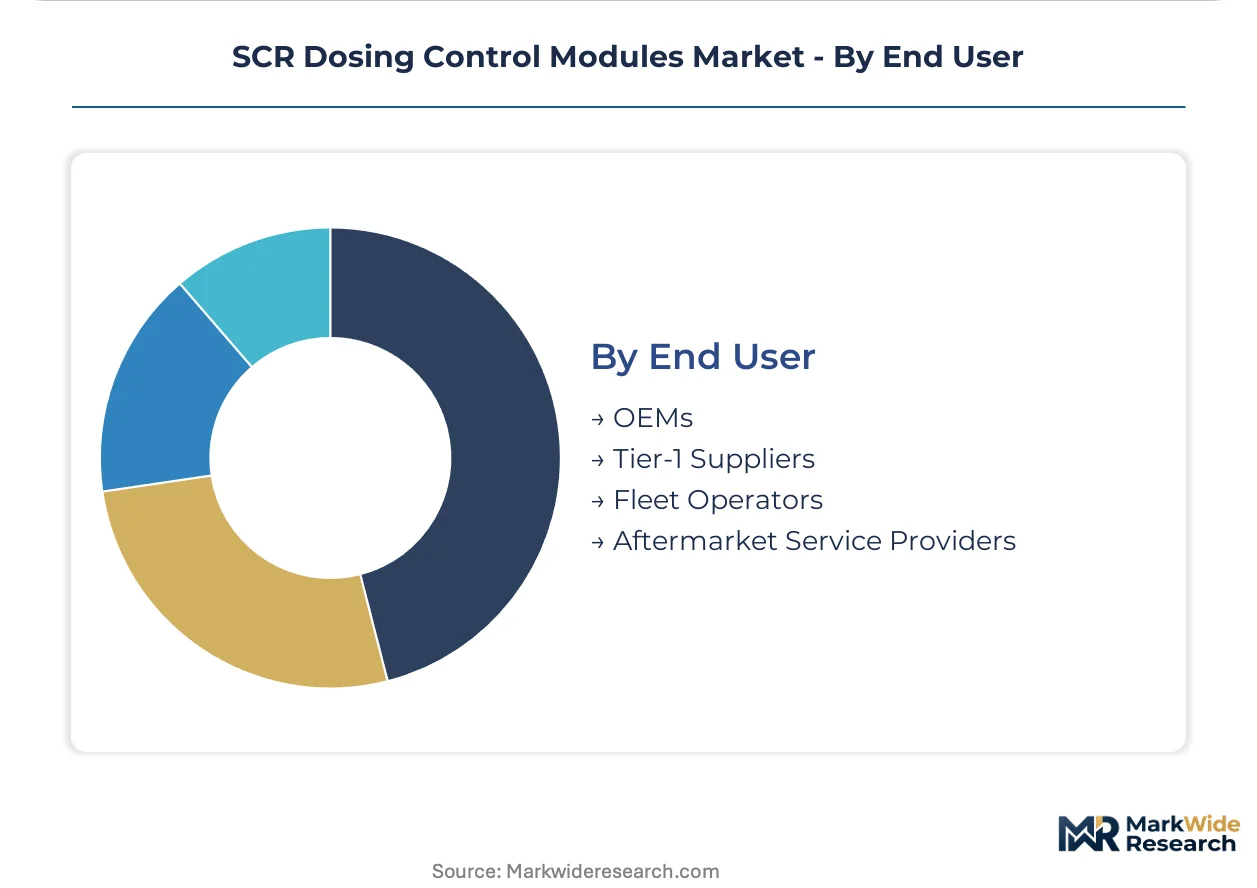
- Fleet Operators:Large logistics networks unbundling after-sales calibration from OEM service networks and negotiating direct supplier relationships. German and US operators are pioneering multi-year dosing system service agreements with predictive maintenance firmware subscriptions.
- OEMs:Integrated powertrain manufacturers embedding modules within engine certification cycles and controlling specification for new vehicle platforms.
- Tier-1 Suppliers:System integrators sourcing modules for assembly into complete aftertreatment packages.
- Aftermarket Service Providers:Independent repair networks handling retrofit installation and legacy system protocol adaptation.
Fleet Operators are capturing specification authority fastest, though OEMs retain volume dominance in new vehicle procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive engineering talent and Chinese manufacturing scale anchor the geographic distribution of SCR dosing control module demand. Detroit's powertrain engineering clusters and Tokyo's precision electronics corridors complete the core concentration map.
United States
Heavy-duty truck fleet operators in Michigan and Ohio are retrofitting existing vehicle pools with adaptive control modules. EPA Tier 4 Final standards mandate eighteen-to-twenty-four-month firmware validation cycles that compress procurement timelines. Detroit's automotive corridor hosts concentrated module specification activity tied to NHTSA compliance testing protocols.
Germany
Logistics networks in Bavaria and North Rhine-Westphalia are pioneering multi-year dosing system service agreements with predictive maintenance subscriptions. KBA coordinates heavy-duty vehicle certification reciprocity with NHTSA and MIIT counterparts. Stuttgart's powertrain engineering clusters drive specification authority for Euro VII-compliant closed-loop architectures.
China
Commercial vehicle OEMs in Shanghai and Beijing are integrating GB VI-mandated onboard diagnostics into module firmware. MIIT enforcement of real-time urea quality sensing expands module functionality into full emissions telemetry. Weichai Power and other domestic suppliers anchor manufacturing scale in Shandong province.
Japan
Precision electronics manufacturers in Nagoya and Tokyo are deploying sub-two-millisecond response actuators for Asian commercial vehicle platforms. METI standards alignment with Euro VII creates export pathway certification efficiency. Hitachi Astemo and Denso Corporation anchor thermal management integration expertise in the Chubu region.
India
Commercial vehicle OEMs in Maharashtra and Tamil Nadu are sourcing modules for BS VI-compliant heavy-duty truck platforms. The country's national automotive regulator mandates emission limits that track Euro VI phase-in schedules. Pune's automotive component clusters are emerging as specification influence points for fleet operator procurement.
SCR Dosing Control Modules Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the SCR dosing control module value chain. The vendor base clusters around three strategic archetypes: integrated automotive electronics conglomerates, powertrain system integrators, and precision fluidics specialists. Consolidation pressure is intensifying as fleet operator procurement centralization favors multi-year service contract capabilities. M&A activity targets firmware-locked calibration databases and predictive maintenance algorithm portfolios.
Within the integrated electronics tier, Bosch and Continental AG represent diversified conglomerate positioning with embedded software scale advantages. Denso Corporation exemplifies the precision thermal management specialist archetype serving Asian commercial vehicle platforms. These three anchors illustrate the competitive tension between firmware complexity depth and geographic manufacturing proximity to OEM assembly operations.
| Leading Market Players |
|---|
| Bosch |
| Continental AG |
| Denso Corporation |
| Cummins |
| BorgWarner |
| FORVIA |
| Eberspächer Group |
| Hitachi Astemo |
| Weichai Power |
| Others |
Pricing and Supply Chain Analysis
Euro VII emission mandates gate qualified supply and premium-tier pricing access for SCR dosing control modules, compressing procurement authority to suppliers with validated firmware architectures while tiering module costs around certification complexity and predictive maintenance bundling.
Pricing Analysis
Bundled firmware subscription models are displacing transactional per-unit pricing across fleet procurement channels. Three-tier pricing structure across premium, standard, and economy levels segments by ECU firmware complexity and after-sales telemetry integration, with Euro VII-certified closed-loop architectures commanding service contract attachments. Price differentiation tracks certification grade and urea consumption optimization guarantees, with adaptive control modules facing cost compression from semiconductor allocation constraints. Tier-1 fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations weighting downtime penalties, while aftermarket retrofit channels remain most price-elastic.
Supply Chain Analysis
Automotive-grade microcontroller supply rests on Taiwanese and South Korean foundry capacity, with Bosch and Continental anchoring ECU assembly in Germany and China. Raw material dependencies span palladium and rhodium for catalyst substrates, precision solenoid actuators from Japanese suppliers, and thermal management ceramics from domestic Chinese producers. Single-source vulnerability in 28nm automotive microcontroller fabrication exposes dosing system OEMs to allocation risk during capacity crunches. Distribution runs through tier-1 supplier channels into OEM assembly plants, with direct fleet operator procurement emerging as a parallel pathway for retrofit module specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German engineering-intensive specification authority and Chinese manufacturing scale, with Euro VII validation timelines in Stuttgart creating cost premiums that Shandong-based production can undercut for emerging market OEMs.
For Market Incumbents: To counter firmware-locked calibration database commoditization, Bosch and Continental should deepen backward integration into automotive-grade semiconductor sourcing through captive foundry partnerships in Taiwan, while accelerating predictive maintenance algorithm development to capture fleet operator subscription revenue streams away from OEM service networks.
For New Entrants and Emerging Players: Capture agricultural equipment retrofit corridors in the United States and European Union where non-road engine compliance deadlines lag on-highway mandates by three-to-five-year intervals, penetrating through cost-optimized pneumatic dosing modules with CAN bus protocol adaptation services for legacy tractor platforms.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision fluidics specialists with thermal management integration capabilities but limited firmware scale, with long-term viability hinging on adaptive control algorithm portfolios that transform hardware vendors into software-telemetry hybrids. Watch for MIIT enforcement acceleration on GB VI onboard diagnostics as the inflection signal for Chinese market premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Locked Calibration Database Acquisition | Consolidates emissions certification lock-in with engine control module suppliers across Euro VII platforms. |
| Predictive Maintenance Algorithm Development | Enables direct supplier-to-fleet subscription channels unbundled from OEM service networks. |
| Automotive-Grade Foundry Partnership | Secures 28nm microcontroller allocation priority during East Asian capacity crunches. |
| Agricultural Equipment Retrofit Platform Launch | Captures non-road engine compliance deadline compression in EPA Tier 4 Final corridors. |
| Multi-Jurisdiction Pre-Certification Investment | Compresses product refresh windows against divergent Euro VII and GB VI validation timelines. |
Research Methodology
Bottom-up fleet operator demand modeling reconciled against top-down supplier shipment tracking forms the analytical core, combining primary interviews with OEM platform engineers, tier-1 supplier procurement leads, fleet maintenance directors, and aftermarket service heads with secondary validation against EPA certification filings, MIIT GB VI enforcement notices, KBA type-approval databases, and commercial vehicle production registries from IHS Markit.
Historical trendline analysis of module replacement cycles and retrofit penetration rates across the projection horizon underpins growth trajectory modeling, with segmentation across product type, technology tier, application category, and end-user procurement authority informing volume allocation. CAGRs derive from regression analysis of regulatory phase-in schedules and fleet operator consolidation patterns, incorporating urea consumption efficiency benchmarks and semiconductor allocation constraints as industry-specific forecast inputs.
Regulatory enforcement delays, platinum group metal price volatility, and foundry capacity crunches are the dominant revision risks to modeled outputs, with forecasts reflecting assumptions around Euro VII final rule timing and NHTSA-CARB compliance reciprocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
Anemometer Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
PID Controller Market
Sensors and Controls
Gesture Recognition and Touch-Less Sensing Market
Sensors and Controls
Wind Vane Sensor Market