
 Multi Touch Sensing Market | 2026-2036
Multi Touch Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Touch Sensing Market Foresight
A widening capital-intensity gap between captive foundry operators and fabless design houses is rotating competitive advantage toward vertically integrated players. Synaptics Incorporated leverages its mixed-signal IP portfolio to sustain premium positioning in biometric touch controllers. Infineon Technologies AG anchors European automotive supply chains through its projected capacitive sensor arrays certified for cabin safety systems. Samsung Electronics dominates captive consumption, routing in-house touch IC production into Galaxy device lines and reducing external procurement exposure.
Multi touch sensing refers to the detection and tracking of multiple simultaneous contact points on a display surface, typically resolving X-Y coordinates through capacitive field distortion measured at frequencies between 50-300 Hz for consumer-grade controllers and up to 1 kHz for industrial panels requiring sub-millisecond latency. Its primary commercial purpose is to replace mechanical input devices with gesture-driven interfaces that reduce part count and enable sealed, contaminant-resistant enclosures. Capacitive technology leads volume shipments due to its integration with cover glass laminates, while projected capacitive variants command margin pools in automotive and medical applications where electromagnetic immunity standards apply. Surface acoustic wave installations occupy industrial controls where surface durability outweighs cost sensitivity, and optical imaging competes in large-format interactive displays for retail and education deployments.
The EU's REACH regulation and RoHS directive restrict hazardous substances in touch sensor substrates and conductive coatings, compelling reformulation of indium tin oxide alternatives and silver nanowire inks. The US FCC Part 15 rules govern electromagnetic emissions from capacitive controllers, creating pre-certification barriers for new entrants targeting North American OEM channels. China's GB standards for information technology equipment safety mandate specific dielectric strength and isolation requirements for touch-enabled products sold domestically. Stakeholders must monitor divergence between regional material compliance regimes and emission testing protocols when configuring multi-generational product platforms.
Market Dynamics
Automotive haptic interfaces are compressing mechanical control supply chains as OEMs consolidate dashboard electronics into sealed, gesture-driven surface modules that eliminate discrete switches and rotary encoders.
Growth Catalysts
- Ecodesign for Sustainable Products Regulation:The EU's material disclosure mandates are accelerating indium tin oxide replacement programs, opening specification windows for silver nanowire and metal mesh alternatives in premium touch stacks.
- China's display cluster concentration:Shenzhen and Hefei panel packaging ecosystems enable domestic OEMs to source touch ICs, cover glass, and controller firmware within 200-kilometer radii, compressing NPI cycles.
- Projected capacitive sensor arrays:Cabin safety certification for these arrays is unlocking automotive center console and steering wheel applications previously reserved for mechanical backup controls.
Market Restraints
- Indium supply concentration:Primary indium refining concentrates in Chinese smelters tied to zinc production, exposing ITO sputtering targets to export quota volatility and price spikes.
- Silver nanowire ink qualification timelines:Automotive electromagnetic immunity testing under EUCE R-10 extends validation cycles to 18-24 months, freezing design wins for emerging conductive coatings.
- Surface acoustic wave substitution:Industrial controls in food processing and mining continue specifying SAW panels for surface durability, limiting capacitive penetration in high-abrasion environments.
Strategic Opportunities
- Medical imaging consoles:Electromagnetic immunity requirements and sealed enclosure mandates in surgical environments favor projected capacitive arrays over resistive alternatives, opening margin pools in diagnostic equipment.
- India's PLI scheme for electronics:Display module manufacturing incentives are attracting touch controller packaging investments to Noida and Sriperumbudur, creating localized supply for smartphone OEMs.
- Convergence of haptic feedback and force sensing:Integration of piezoelectric actuators with capacitive position detection enables pressure-sensitive interfaces that replicate mechanical button travel without moving parts.
Industry Challenges
- Multi-frequency controller firmware development:Engineering teams capable of optimizing noise rejection algorithms across 50 Hz to 1 kHz sampling ranges remain concentrated at mixed-signal specialists, constraining fabless design house expansion.
- Legacy automotive qualification carryover:Tier-1 suppliers must maintain dual-source mechanical switch inventories alongside touch surface ramps to satisfy FMVSS 124 backup control requirements during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Touch Sensing Market |
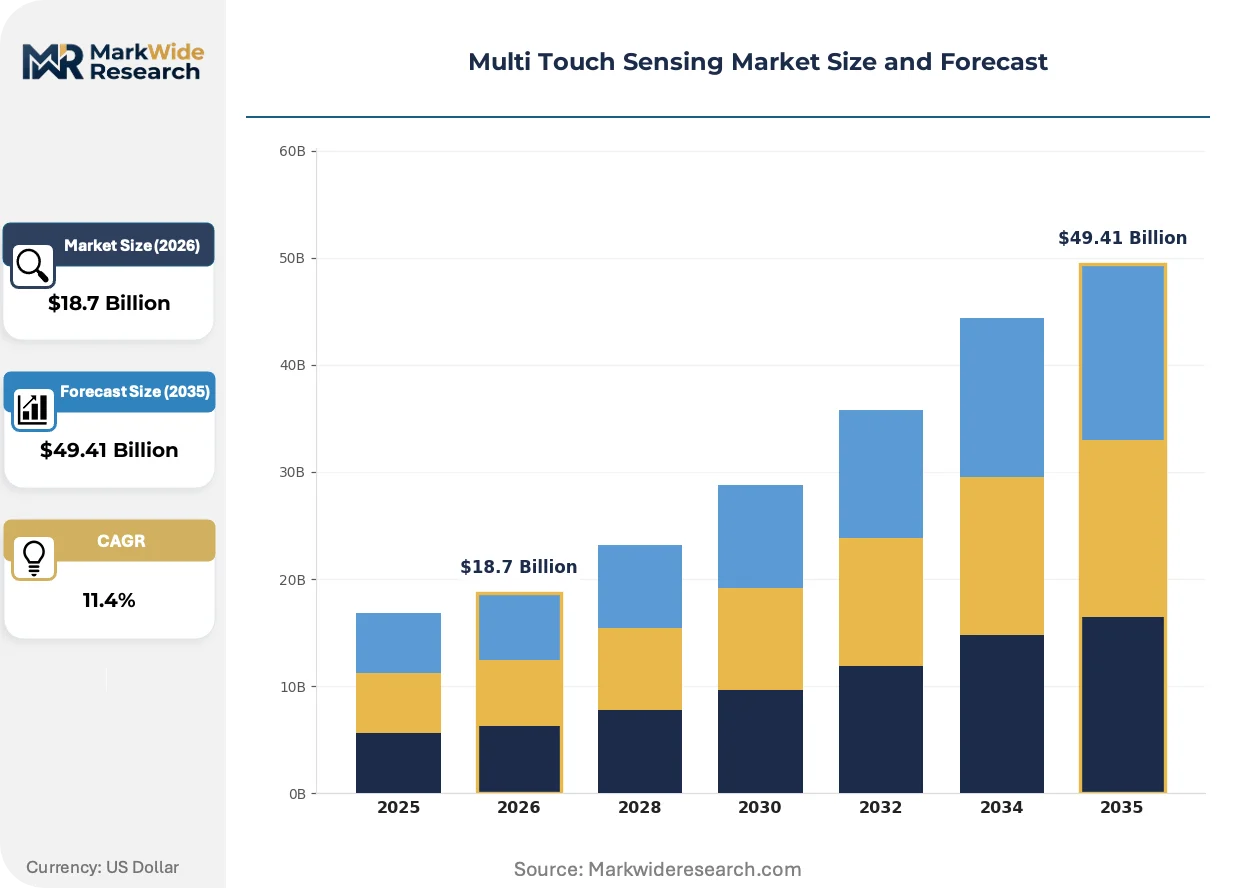
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resistive, Capacitive, Optical, Infrared Technology: Surface Acoustic Wave, Projected Capacitive, Optical Imaging, Freestyle Application: Consumer Electronics, Automotive Interfaces, Industrial Controls, Gaming End User: OEMs, Retailers, Educators, Enterprises |
| Companies Covered | Synaptics Incorporated, Texas Instruments Incorporated, Infineon Technologies AG, NXP Semiconductors, TPK Holding Co., Ltd., Samsung Electronics, Shenzhen Goodix Technology, STMicroelectronics, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Touch Sensing Market Shifts & Advancements
Touch controller architectures are bifurcating between ultra-low-power mobile-optimized designs and high-sampling-rate automotive-grade platforms, with process node selection and packaging technology becoming primary differentiation vectors.
Metal mesh conductive films are supplanting traditional indium tin oxide layers in automotive and large-format display applications. Tier-1 dashboard suppliers at Hyundai Mobis and Continental have qualified copper-based mesh patterns for 12-inch and larger center stacks. This conductor geometry is supplanting ITO sputtering in applications where sheet resistance below 100 ohms per square couples with mechanical flexibility requirements for curved surfaces.
REACH authorization requirements for nickel compounds are forcing reformulation of electroless plating chemistries used in flex circuit termination. The European Chemicals Agency's sunset date enforcement is compressing supplier qualification windows for automotive touch module interconnects. German KBA type approval processes now explicitly query REACH substance restriction compliance in component-level documentation.
Fleet operators and shared mobility platforms are consolidating touch interface specifications across vehicle classes, eliminating variant proliferation that previously sustained multiple controller SKUs. Procurement teams at lease-fleet aggregators now mandate five-year availability guarantees and pin-compatible successor migration paths. This specification consolidation is most visible in China, where Didi and T3 Mobility are driving standardization of 10.1-inch portrait touch surfaces across multiple OEM badge-engineered models.
Multi Touch Sensing Market Segmentation
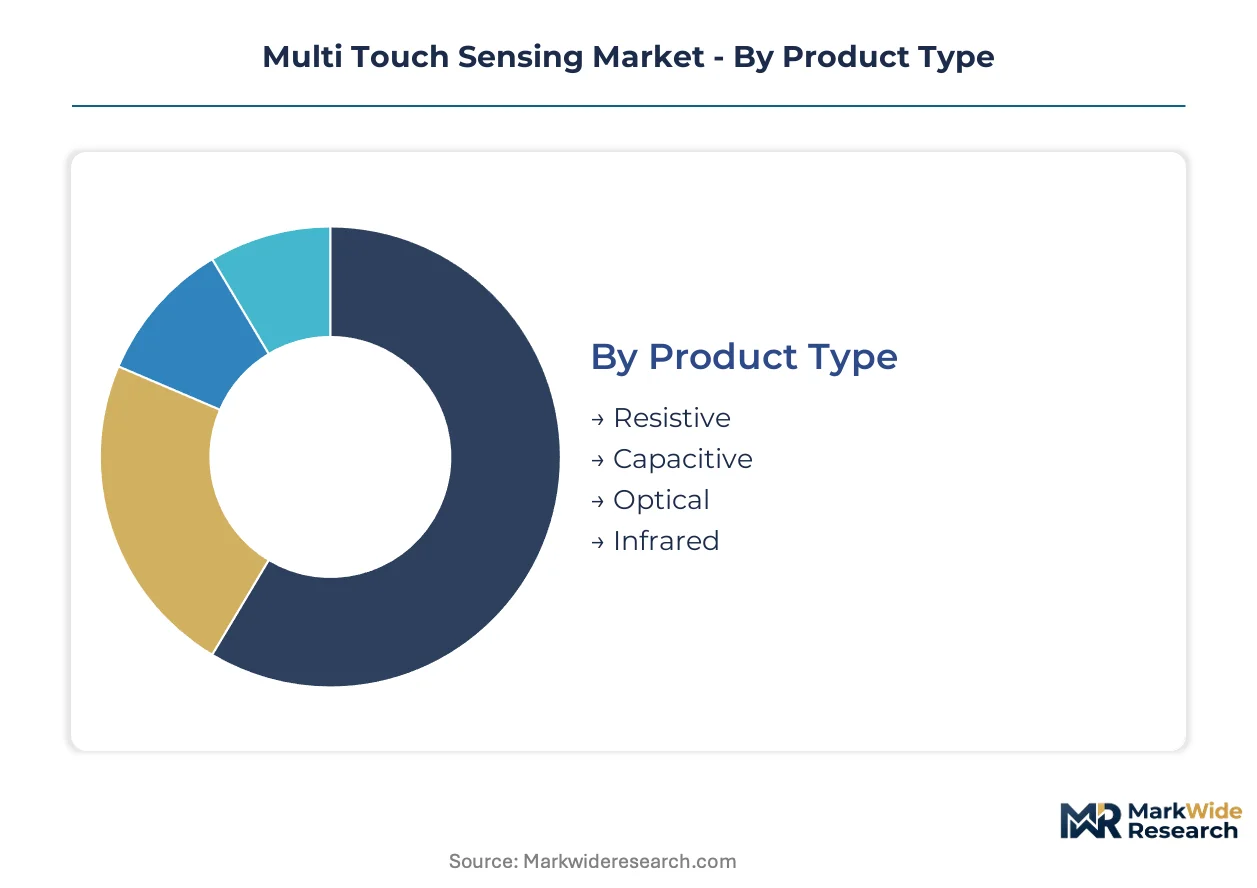
Segmentation in multi touch sensing reveals divergent vulnerability profiles across sensing modalities and end-use environments. Substitute technologies threaten established categories unevenly, with some segments facing imminent displacement while others deepen moats through certification complexity.
Product Type:
Resistive sensing faces the most acute substitution pressure as capacitive alternatives achieve cost parity in consumer applications while eliminating the force-contact requirement that degrades surface durability.
- Capacitive:Electrostatic field distortion detection enables sealed glass laminates without mechanical wear layers. Automotive center consoles and smartphone displays in China, South Korea, and Vietnam drive specification consolidation around projected capacitive stacks with sub-100 ohm sheet resistance targets.
- Resistive:Pressure-activated membrane stacks using indium tin oxide or silver nanowire conductive coatings persist in industrial gloves-required environments and legacy medical equipment where electromagnetic immunity certification remains pending for capacitive alternatives.
- Optical:Camera-based triangulation systems dominate large-format interactive whiteboards and retail kiosks above 32 inches diagonal where capacitive sensor density becomes economically prohibitive.
- Infrared:LED array interruption detection occupies niche gaming and casino applications requiring multi-user simultaneous input across expansive surface areas without glass overlay weight penalties.
Capacitive anchors the volume base while optical gains share at the steepest rate in education and retail deployments.
Technology:
Cost tier stratification separates automotive-qualified platforms from consumer-grade controllers, with process node selection and firmware complexity creating divergent margin structures.
- Projected Capacitive:XY electrode grid arrays with mutual-capacitance measurement achieve electromagnetic immunity compliance for EUCE R-10 automotive certification. German KBA type approval and US NHTSA FMVSS 124 backup control waivers unlock steering wheel and center console placements previously reserved for mechanical switches.
- Surface Acoustic Wave:Piezoelectric transducer arrays on glass substrates deliver scratch-resistant performance for food processing and mining controls. The technology resists capacitive substitution where surface abrasion exceeds 10,000 cycles in MIL-STD-810G dust exposure testing.
- Optical Imaging:CMOS camera triangulation with infrared illumination enables 40-inch and larger interactive surfaces for corporate collaboration suites and museum installations.
- Freestyle:Camera-based stylus and finger tracking without surface overlay penetrates digital whiteboard and architectural visualization markets requiring pressure-sensitive input across irregular projection surfaces.
Projected capacitive commands the premium tier while surface acoustic wave retains defensive positions in industrial abrasion environments.
Application:
Customer type concentration shapes procurement patterns, with fleet operators and platform aggregators consolidating specifications that previously sustained fragmented SKU proliferation.
- Consumer Electronics:Smartphone, tablet, and wearable controllers demand 50-300 Hz sampling rates with sub-10 milliwatt active power consumption. Shenzhen and Hefei packaging ecosystems enable Chinese OEMs to source touch ICs, cover glass, and controller firmware within compressed NPI cycles.
- Automotive Interfaces:Haptic dashboard modules eliminate discrete switches and rotary encoders, consolidating electronics into sealed gesture-driven surfaces. EU Ecodesign for Sustainable Products Regulation material disclosure mandates accelerate indium tin oxide replacement programs in European vehicle programs.
- Industrial Controls:Sealed enclosure requirements and electromagnetic immunity standards in manufacturing automation favor projected capacitive arrays over resistive alternatives in diagnostic equipment consoles.
- Gaming:Arcade and casino applications specify infrared and optical imaging for multi-user input durability without glass breakage liability in high-traffic entertainment venues.
Consumer electronics anchors volume procurement while automotive interfaces expand most quickly through haptic consolidation mandates.
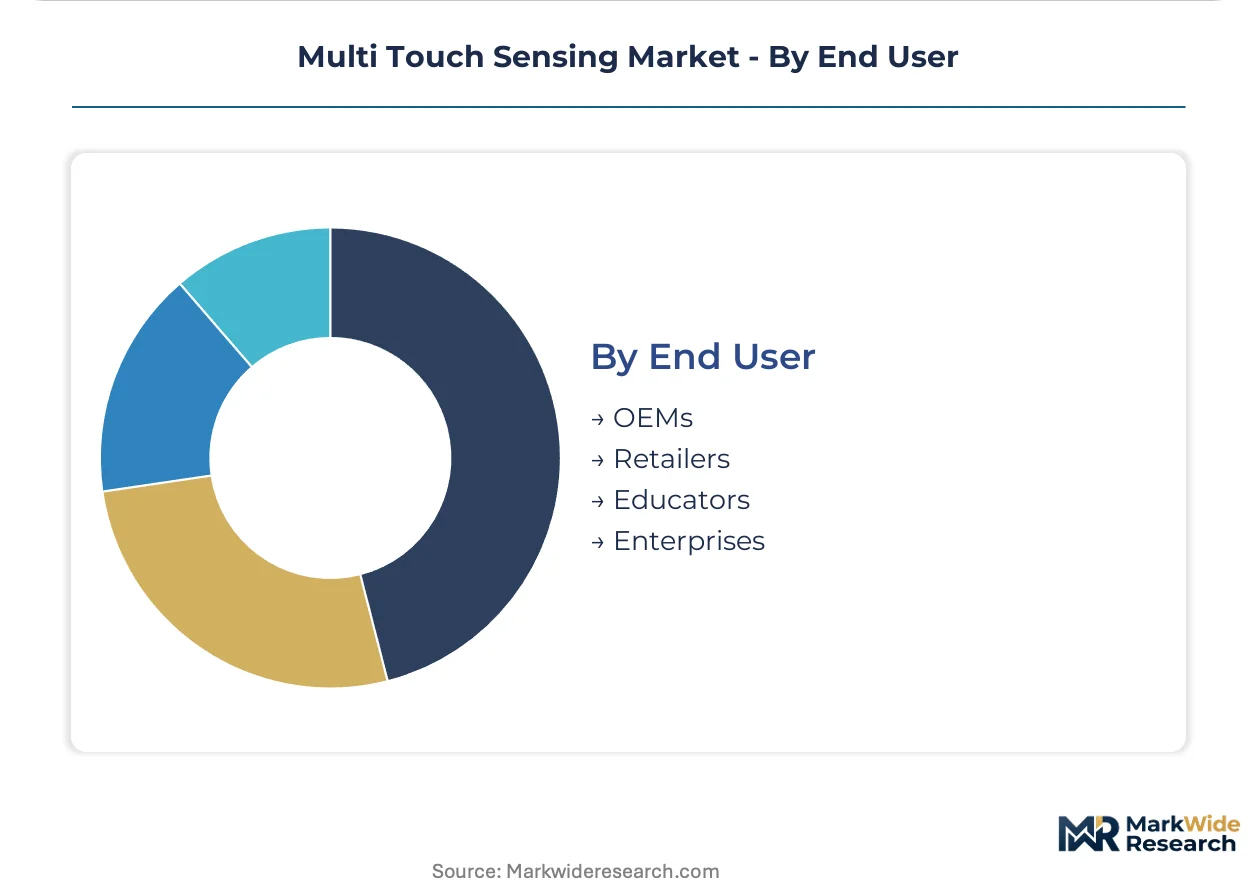
End User:
Supply concentration among captive foundry operators versus fabless design houses rotates procurement leverage toward vertically integrated OEMs with in-house controller production.
- OEMs:Device manufacturers with captive touch IC design capabilities route in-house production into flagship product lines, reducing external procurement exposure. Samsung Electronics exemplifies this model with Galaxy device integration.
- Retailers:Interactive kiosk and digital signage deployments specify optical imaging and infrared for large-format durability in high-traffic environments.
- Educators:School district and university procurement consolidates around 65-inch and larger interactive whiteboards, driving optical imaging specification standardization.
- Enterprises:Corporate collaboration suite investments favor projected capacitive and optical imaging for conference room controller durability and multi-user support.
OEMs dominate procurement volume while enterprise deployments are climbing the fastest through hybrid workplace collaboration investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese OEMs exhibit the lowest price elasticity, absorbing premium touch controller costs through captive display clusters, while European automakers face acute cost pressure from REACH compliance and indium substitution mandates.
China
Shenzhen and Hefei panel packaging ecosystems compress new product introduction cycles for domestic smartphone OEMs sourcing touch ICs, cover glass, and controller firmware within 200-kilometer radii. MIIT GB standards for information technology equipment safety mandate specific dielectric strength requirements for touch-enabled products sold domestically. Yangtze River Delta semiconductor foundries are expanding projected capacitive sensor array capacity for automotive qualification programs.
Germany
KBA type approval processes now explicitly query REACH substance restriction compliance in automotive touch module documentation, extending validation timelines. ECHA sunset date enforcement for nickel compounds compresses supplier qualification windows for flex circuit termination chemistries. Bavaria-based Tier-1 dashboard suppliers at Continental have qualified copper-based metal mesh patterns for 12-inch center stacks.
United States
FCC Part 15 electromagnetic emissions rules create pre-certification barriers for capacitive controller entrants targeting North American OEM channels. NHTSA FMVSS 124 backup control requirements force Tier-1 suppliers to maintain dual-source mechanical switch inventories alongside touch surface ramps. Michigan automotive electronics clusters are consolidating haptic interface specifications across vehicle classes.
South Korea
Seoul Capital Area display manufacturers route in-house touch IC production into flagship device lines, reducing external procurement exposure. MFDS electromagnetic immunity standards for medical equipment create specification windows for projected capacitive arrays in diagnostic consoles. Busan-Ulsan packaging ecosystems are expanding force-sensing integration with piezoelectric actuator production.
India
PLI scheme incentives for display module manufacturing are attracting touch controller packaging investments to Noida and Sriperumbudur. BIS certification requirements for information technology equipment safety mandate specific isolation standards for touch-enabled products sold domestically. Tamil Nadu electronics manufacturing clusters are localizing supply for smartphone OEMs targeting export markets.
Multi Touch Sensing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry operators commanding procurement leverage over fabless design houses. The market structure stratifies by process node selection and firmware complexity, creating divergent margin pools between automotive-qualified platforms and consumer-grade controllers. Three archetypes dominate: vertically integrated OEMs with in-house touch IC production, mixed-signal specialists with biometric IP portfolios, and European automotive anchor suppliers with cabin safety certifications. Competitive moves concentrate on backward integration into sensor substrate production and strategic partnerships with display panel manufacturers.
Within the mixed-signal specialist tier, Synaptics Incorporated and Texas Instruments Incorporated exemplify premium positioning through controller firmware expertise. Infineon Technologies AG anchors European automotive supply chains with projected capacitive sensor arrays. Among Asia-Pacific fabricators, Samsung Electronics represents captive consumption models, while Shenzhen Goodix Technology occupies a position serving domestic Chinese OEM volume requirements.
| Leading Market Players |
|---|
| Synaptics Incorporated |
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| NXP Semiconductors |
| TPK Holding Co., Ltd. |
| Samsung Electronics |
| Shenzhen Goodix Technology |
| STMicroelectronics |
| Microchip Technology |
| Others |
Supply & Pricing Matrix
Silver nanowire ink substitution for indium tin oxide sputtering targets simultaneously redistributes supply geography toward Chinese nanomaterial refiners and compresses pricing economics for automotive touch stack suppliers facing EUCE R-10 qualification timelines. This input transition rewards buyers with captive formulation capabilities while exposing fabless design houses to raw material volatility.
Pricing Analysis
After-market firmware licensing and extended calibration service contracts drive lifetime value for automotive-qualified projected capacitive controllers. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-level tiers reflects electromagnetic immunity testing investment and sampling rate performance. Cost compression in consumer-grade controllers intensifies because Shenzhen packaging ecosystems enable Chinese OEMs to source complete touch modules domestically. Fleet procurement teams at mobility platforms exhibit lowest price elasticity, while education-sector interactive whiteboard buyers negotiate aggressively on large-format optical imaging deployments.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose indium concentrate shipments from Chinese zinc smelters to ITO target manufacturers in South Korea and Japan. Touch controller production draws from Taiwan foundry capacity, Chinese display panel clusters, and German automotive Tier-1 qualification laboratories. Single-source vulnerability concentrates in indium refining tied to zinc mining byproduct recovery. Distribution runs through OEM direct procurement for captive consumption, distributor networks for aftermarket replacement, and contract manufacturers for white-label industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi touch sensing sits in early-cycle expansion as automotive haptic interfaces displace mechanical controls across center console and steering wheel applications. Penetration tailwinds from EU Ecodesign material disclosure mandates and fleet operator specification consolidation sustain momentum.
For Market Incumbents: Compound firmware differentiation through multi-frequency noise rejection algorithms spanning 50 Hz to 1 kHz sampling ranges. Anchor automotive supply relationships with five-year availability guarantees and pin-compatible successor migration paths. Defend against emerging metal mesh conductive film suppliers by qualifying copper-based patterns for curved surface applications before KBA sunset date enforcement accelerates.
For New Entrants and Emerging Players: EUCE R-10 certification fast-tracks unlock automotive center console placements previously reserved for mechanical backup controls. White-space concentrates in medical imaging consoles requiring electromagnetic immunity compliance and sealed enclosure mandates. Target India's PLI scheme display module investments at Noida and Sriperumbudur for localized smartphone OEM supply. Go-to-market through force-sensing integration partnerships with piezoelectric actuator manufacturers.
For Investors and Strategic Acquirers: Capital is best deployed toward mixed-signal specialists with biometric IP portfolios and automotive cabin safety certifications. Long-term viability frames around controller firmware expertise as process node selection and packaging technology become primary differentiation vectors. Watch for inflection when fleet operator specification consolidation eliminates variant proliferation that previously sustained multiple controller SKUs.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Certification Investment | EUCE R-10 compliance unlocks steering wheel placements under FMVSS 124 waiver pathways. |
| Backward Integration into Sensor Substrates | Copper-based metal mesh pattern qualification reduces ITO indium exposure and REACH compliance risk. |
| Force-Sensing Platform Integration | Piezoelectric actuator convergence with capacitive detection replicates mechanical button travel. |
| Geographic Manufacturing Footprint | Noida and Sriperumbudur packaging investments capture PLI scheme incentives for smartphone OEM supply. |
| Strategic Partnership with Display Panel Manufacturers | Shenzhen and Hefei ecosystem integration compresses NPI cycles for domestic Chinese OEMs. |
Research Methodology
A standing panel of touch controller firmware engineers, automotive Tier-1 procurement directors, display panel manufacturing executives, and semiconductor foundry operations managers provided ongoing calibration across primary interview rounds. Secondary validation drew from MIIT GB standard filings, KBA type approval documentation, FCC Part 15 equipment authorization databases, and SEC 10-K disclosures from mixed-signal semiconductor suppliers. Bottom-up unit economics triangulated against top-down display shipment forecasts.
Consistency checks validated volume and value outputs against IHS Markit vehicle production databases, smartphone bill-of-materials estimates, and industrial automation capex tracking. The analytical framework modeled technology segmentation across projected capacitive, surface acoustic wave, optical imaging, and freestyle tracking; application segmentation across consumer electronics, automotive interfaces, industrial controls, and gaming; and geographic production clustering across the analysis window. CAGRs derived from regression against historical controller ASP trajectories and automotive content-per-vehicle expansion curves.
Decision-makers should treat outputs as directional under sustained automotive electrification and fleet aggregation assumptions; material deviation in indium supply concentration or REACH enforcement timing would warrant model refresh. Practitioners should keep alternative scenarios live as EU Ecodesign disclosure requirements and China display cluster capacity expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Torque Transducer Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Global Printed Sensor Market