
 Bimetallic Thermometer Market | 2026-2036
Bimetallic Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Bimetallic Thermometer Market Outlook
Multi-source procurement for bimetallic sensing elements is broadening as end-users reduce dependency on single foundries. WIKA Alexander Wiegand SE & Co. KG leverages captive strip production in Germany to sustain margin control across precision instrument lines. Ashcroft Inc. competes through North American distribution density and aftermarket calibration services. Emerson Electric Co. anchors its position via embedded temperature transmitters that integrate bimetallic probes with digital output protocols.
A bimetallic thermometer employs two dissimilar metal strips—typically invar and steel or brass—bonded together to produce mechanical deflection proportional to temperature change, with standard ranges spanning negative forty to five hundred degrees Celsius and accuracies of one percent full scale. Dial thermometers retain dominant share in heavy industrial settings where mechanical reliability outweighs digital complexity, while digital thermometers capture fastest growth in food processing plants requiring HACCP-compliant data logging. Bi-metallic sensors with integrated temperature compensation circuits command premium positioning in pharmaceutical cleanroom applications where drift tolerance falls below half a degree Celsius.
EPA mandates under the Clean Air Act and OSHA process safety management rules compel refineries and chemical plants to maintain redundant temperature monitoring on critical pressure vessels, directly sustaining replacement demand for certified bimetallic instruments. The EU F-Gas Regulation and REACH chemical restrictions further shape product material specifications, limiting mercury alternatives and driving stainless steel encapsulation standards. Stakeholders must weigh calibration traceability investments against the accelerating shift toward wireless sensor networks in brownfield industrial facilities.
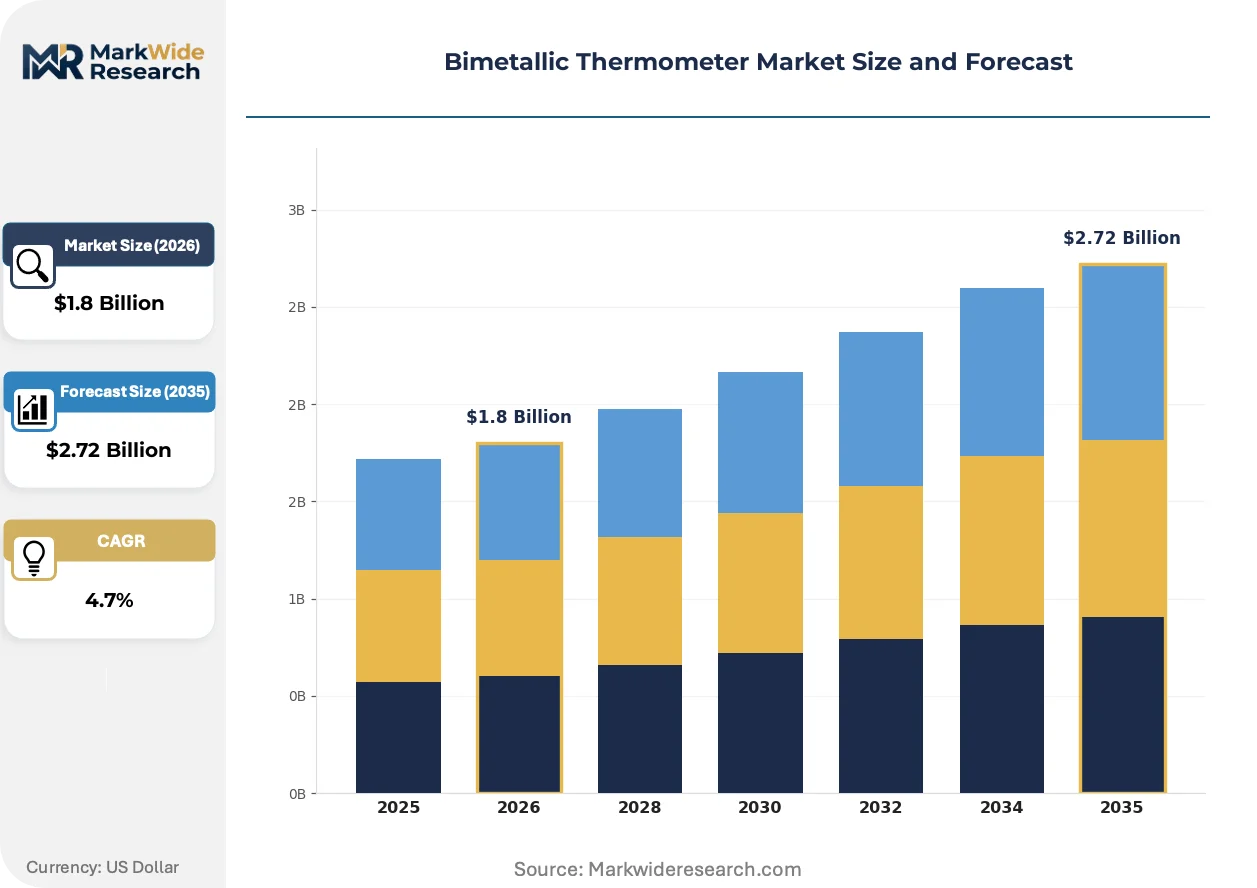
Market Dynamics
Industrial refrigeration retrofits under EPA and EU F-Gas mandates are compressing replacement cycles for certified bimetallic instruments, while East Asian manufacturing corridors absorb disproportionate procurement volumes.
Growth Catalysts
- EPA Clean Air Act enforcement:Refineries and chemical plants in the United States must maintain redundant temperature monitoring on pressure vessels, sustaining certified instrument replacement schedules.
- Food safety digitization:HACCP-compliant data logging requirements in processing plants accelerate dial-to-digital thermometer conversions.
- Shanghai-Shenzhen industrial corridor expansion:Chemical processing and pharmaceutical cleanroom construction concentrates demand for drift-tolerant bi-metallic sensors.
Market Restraints
- Invar alloy supply concentration:Nickel-iron alloy production for precision strips clusters in German and Japanese specialty foundries, exposing buyers to single-source risk.
- Wireless sensor substitution:Industrial IoT temperature transmitters with digital output protocols displace mechanical dials in brownfield automation projects.
- REACH material restrictions:EU chemical regulations limit mercury-alternative formulations and mandate stainless steel encapsulation, raising unit production costs.
Strategic Opportunities
- Pharmaceutical cleanroom certification:Bi-metallic sensors with integrated temperature compensation circuits command premium positioning where drift tolerance falls below 0.5°C.
- Calibration-as-a-service channels:Aftermarket traceability investments create recurring revenue streams independent of hardware sales cycles.
- Dual-carbon manufacturing zones in China:MEE emissions monitoring rules expand instrument procurement for reactor vessel monitoring in Ningbo and Tianjin clusters.
Industry Challenges
- ISO 17025 calibration technician scarcity:Certified metrology labs face bottlenecks in generating NIST-traceable documentation for regulated end-users.
- Legacy system integration friction:Mechanical dial retrofits into digital SCADA architectures require custom signal conditioning hardware and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bimetallic Thermometer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dial Thermometers, Digital Thermometers, Liquid-in-glass Thermometers, Infrared Thermometers End User: Manufacturing, Food Processing, Pharmaceutical, HVAC Technology: Bimetallic Strip, Bi-metallic Sensors, Temperature Compensation, Calibration Techniques Application: Automotive, Industrial Processes, Heating Systems, Refrigeration |
| Companies Covered | WIKA Alexander Wiegand SE & Co. KG, Ashcroft Inc., OMEGA Engineering Inc., Emerson Electric Co., Fluke Corporation, Ametek Inc., Dwyer Instruments Inc., Tel-Tru Manufacturing Company, REOTEMP Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bimetallic Thermometer Market Strategic Shifts
Bi-metallic sensing technology is converging with digital output protocols and wireless telemetry, compressing the traditional divide between mechanical reliability and data connectivity in industrial temperature monitoring.
Smart bi-metallic probes with embedded HART or IO-Link transmitters are integrating analog sensing elements with digital communication stacks. Pharmaceutical manufacturers and cold chain operators are adopting these hybrid instruments fastest. This convergence is integrating mechanical durability with enterprise asset management visibility, eroding the traditional cost advantage of pure mechanical dials.
EU F-Gas Regulation phase-down schedules are tightening leak-detection and temperature monitoring requirements in industrial refrigeration systems. Equipment operators must install certified instruments with documented calibration traceability. Food processing and chemical cold storage facilities in Germany and France are responding by pre-buying compliant bi-metallic inventory ahead of enforcement deadlines.
Multi-vendor instrument sourcing is displacing sole-source procurement contracts among chemical processors. End-users in the United States and Germany now qualify secondary strip suppliers to reduce foundry concentration risk. This pattern is most visible in reactor vessel monitoring applications where OSHA process safety management rules mandate redundant sensor configurations.
Bimetallic Thermometer Market Segmentation
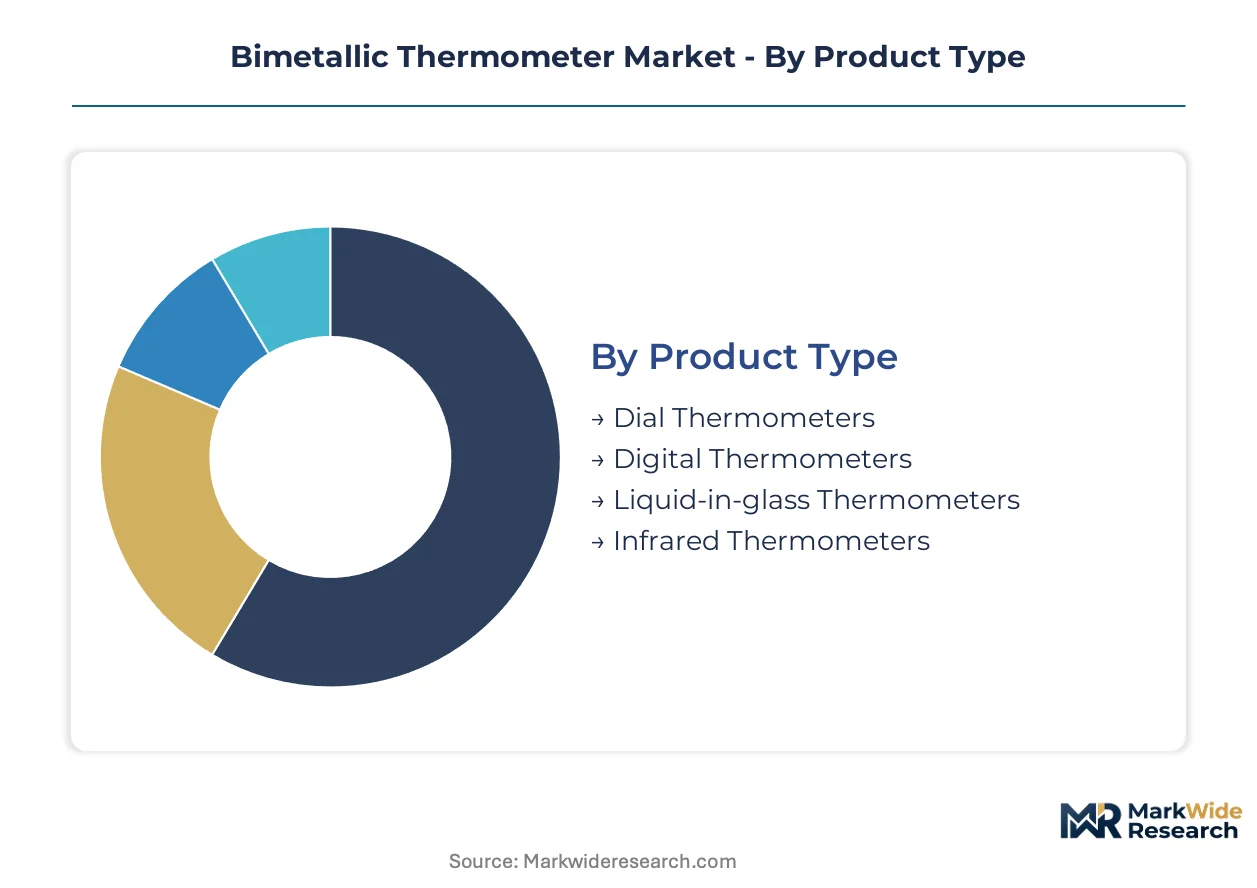
Segmentation in the bimetallic thermometer market reflects divergent certification burdens across industrial verticals. Product type determines mechanical versus digital compliance pathways, while end-use application dictates whether FDA, EPA, or ISO 17025 traceability governs procurement specifications.
Product Type:
Dial thermometers carry minimal electronics certification overhead, while digital variants face FCC emissions testing and embedded software validation under EU MDR and FDA 21 CFR Part 820.
- Dial Thermometers:Mechanical deflection instruments using bonded invar-steel or brass-steel strips deliver one percent full-scale accuracy across negative forty to five hundred degrees Celsius. Refineries and chemical plants in the United States absorb dominant procurement volumes under OSHA process safety management rules mandating redundant pressure vessel monitoring.
- Digital Thermometers:Bi-metallic probes with integrated A/D conversion and HART or IO-Link output protocols require electromagnetic compatibility certification. Food processing facilities in Germany and France accelerate dial-to-digital conversions to satisfy HACCP-compliant data logging mandates under EU F-Gas Regulation enforcement.
- Liquid-in-glass Thermometers:Mercury-alternative formulations face REACH material restrictions limiting encapsulation options to stainless steel housings.
- Infrared Thermometers:Non-contact thermal measurement devices compete at the periphery of bi-metallic applications, primarily in HVAC commissioning workflows.
Dial thermometers sit at the top of the volume ranking, with digital thermometers climbing the fastest.
End User:
Customer type stratification tracks capital intensity and calibration frequency, with pharmaceutical and food processing commanding premium pricing for documented traceability.
- Manufacturing:General industrial buyers prioritize unit cost and mechanical durability over data connectivity, sustaining dial thermometer dominance in heavy machinery monitoring.
- Food Processing:HACCP compliance drives fastest expansion for digital bi-metallic sensors with integrated data logging capabilities.
- Pharmaceutical:Cleanroom installations demand drift tolerance below half a degree Celsius and ISO 17025 calibration documentation.
- HVAC:Refrigeration retrofit cycles under EPA Clean Air Act and EU F-Gas mandates compress replacement intervals for certified instruments.
Manufacturing captures the largest addressable base, though pharmaceutical applications generate steepest margin expansion.
Technology:
Technical differentiation centers on precision alloy sourcing and signal conditioning sophistication, with captive strip production conferring supply security advantages.
- Bimetallic Strip:Nickel-iron invar bonded to steel or brass forms the foundational sensing element; German and Japanese specialty foundries concentrate supply.
- Bi-metallic Sensors:Packaged probe assemblies with stainless steel encapsulation satisfy REACH restrictions and pharmaceutical cleanroom ingress requirements.
- Temperature Compensation:Integrated circuitry corrects for ambient drift, commanding premium positioning where process tolerance tightens below one degree Celsius.
- Calibration Techniques:NIST-traceable and ISO 17025 documentation services create recurring revenue independent of hardware replacement cycles.
Bi-metallic strip technology anchors installed base volumes, while temperature compensation circuits gain share fastest in precision applications.
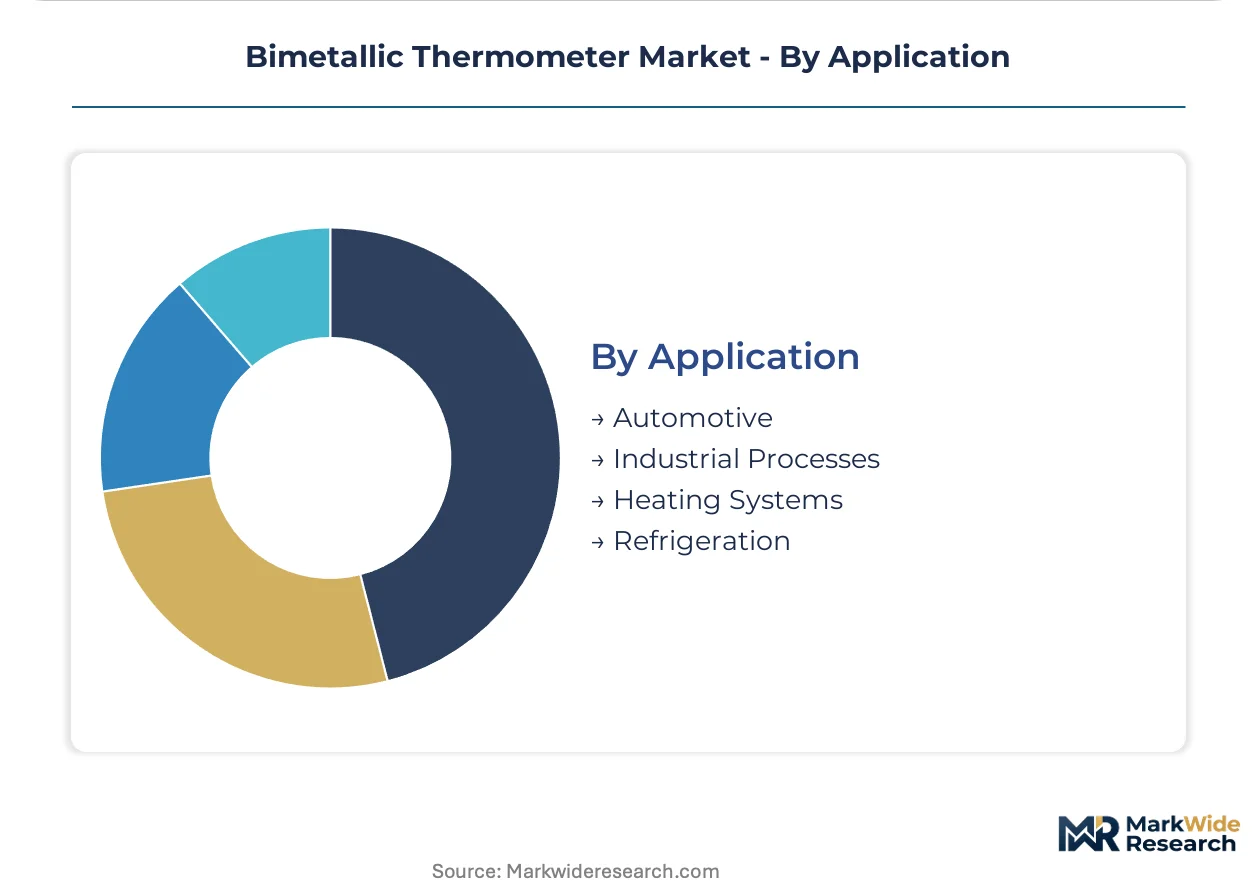
Application:
Use-case segmentation aligns with regulatory enforcement intensity, with industrial processes and refrigeration facing the most stringent monitoring mandates.
- Automotive:Engine and exhaust temperature monitoring employs compact bi-metallic probes, though electrification trends displace thermal management instrumentation.
- Industrial Processes:Reactor vessel monitoring in chemical processing facilities across Germany and the United States sustains certified instrument replacement schedules under EPA and OSHA rules.
- Heating Systems:Boiler and furnace applications favor mechanical dials for reliability in high-vibration environments.
- Refrigeration:Cold storage and industrial refrigeration retrofits under F-Gas phase-down schedules concentrate demand in French and German facilities.
Industrial processes generate the highest absolute demand, with refrigeration applications expanding most quickly on regulatory retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Shenzhen industrial corridor concentrates the most intensive procurement activity for precision temperature instrumentation, with chemical processing and pharmaceutical cleanroom construction driving concentrated demand clusters across East Asian manufacturing zones.
United States
Petrochemical refineries along the Gulf Coast sustain replacement schedules for certified bimetallic instruments under EPA Clean Air Act enforcement and OSHA process safety management rules. Houston and Corpus Christi host the densest concentrations of reactor vessel monitoring installations requiring redundant sensor configurations.
Germany
Industrial refrigeration retrofits under EU F-Gas Regulation phase-down schedules compress replacement cycles for drift-tolerant bi-metallic sensors. BASF and Bayer facility clusters in Ludwigshafen and Leverkusen anchor precision instrument demand for pharmaceutical cleanroom applications.
China
Dual-carbon manufacturing zones in Ningbo and Tianjin expand instrument procurement for reactor vessel monitoring under MEE emissions monitoring rules. The Yangtze River Delta chemical processing corridor absorbs disproportionate volumes of temperature compensation circuits for sub-half-degree drift tolerance specifications.
Japan
Specialty invar alloy foundries in Osaka and Nagoya supply precision strip materials to domestic instrument manufacturers under JIS standards. METI industrial efficiency programs accelerate dial-to-digital conversions in food processing facilities requiring HACCP-compliant data logging.
France
Cold storage facilities around Lyon and Paris pre-buy compliant bi-metallic inventory ahead of EU F-Gas Regulation enforcement deadlines. ANSM pharmaceutical manufacturing guidelines tighten cleanroom temperature monitoring requirements for bi-metallic sensors with ISO 17025 calibration documentation.
Bimetallic Thermometer Market Competitive Environment
Global majors compete with regional champions across distribution density and captive alloy supply security. The vendor base stratifies into three tiers: precision instrument specialists with in-house strip production, diversified industrial conglomerates embedding temperature sensing within automation portfolios, and regional calibration service providers. Consolidation pressure intensifies around aftermarket traceability capabilities and wireless protocol integration expertise.
Among Germany-based precision instrument groups, WIKA Alexander Wiegand SE & Co. KG exemplifies the captive-production archetype through controlled supply of sensing elements. Ashcroft Inc. and Emerson Electric Co. occupy positions reflecting divergent strategic vectors—distribution-centric aftermarket services versus embedded digital transmitter integration. These three anchors represent the dominant competitive configurations: vertical alloy control, geographic density, and protocol convergence.
| Leading Market Players |
|---|
| WIKA Alexander Wiegand SE & Co. KG |
| Ashcroft Inc. |
| OMEGA Engineering Inc. |
| Emerson Electric Co. |
| Fluke Corporation |
| Ametek Inc. |
| Dwyer Instruments Inc. |
| Tel-Tru Manufacturing Company |
| REOTEMP Instruments Corporation |
| Others |
Value Chain & Pricing Dynamics
Certified calibration technician pools in Germany and Japan sustain labor-cost premiums that widen pricing spreads between ISO 17025-traceable instruments and uncertified economy-tier alternatives. This workforce concentration forces buyers to absorb tier premiums or accept documentation gaps that risk regulatory non-compliance under EPA and EU F-Gas enforcement.
Pricing Analysis
Input-cost pass-through from invar alloy strip pricing anchors three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle NIST-traceable calibration certificates and stainless steel REACH-compliant encapsulation, while economy tiers sacrifice documentation depth for unit-cost minimization. Pricing pressure stems from wireless IoT transmitter substitution in brownfield automation projects. Food processing buyers exhibit highest price sensitivity due to volume procurement and HACCP compliance commoditization, whereas pharmaceutical cleanroom operators accept steep premiums for sub-0.5°C drift tolerance specifications.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement contracts as chemical processors in the United States and Germany qualify secondary strip suppliers to mitigate foundry concentration risk. Invar alloy production clusters in Germany and Japan, with secondary capacity emerging in South Korea. Nickel-iron strip sourcing, precision machining capabilities, and calibration laboratory accreditation form critical input dependencies. Single-source vulnerability in specialty foundry capacity exposes buyers to allocation rationing during demand surges. Distribution runs through authorized instrument distributors and direct OEM channels serving reactor vessel monitoring and pharmaceutical cleanroom applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bimetallic thermometer market functions as a stable compounder anchored by regulatory mandates that compel recurring instrument replacement regardless of industrial cycle positioning.
For Market Incumbents: Lock in captive strip production or long-term offtake agreements with German and Japanese specialty foundries to secure margin control against invar supply rationing. Deepen calibration-as-a-service revenue streams to offset hardware commoditization pressure from wireless sensor substitution. Prioritize HART and IO-Link protocol integration to defend position in brownfield digital retrofit cycles. For New Entrants and Emerging Players: Enter via aftermarket calibration traceability services rather than hardware manufacturing, exploiting ISO 17025 laboratory scarcity in East Asian manufacturing corridors. Target pharmaceutical cleanroom certification segments where drift tolerance specifications below 0.5°C sustain premium positioning. Pursue white-label supply partnerships with established distributors lacking captive calibration capabilities. For Investors and Strategic Acquirers: Industrial automation conglomerates seeking sensor portfolio completeness represent the most active acquirer in this space, particularly those lacking temperature sensing verticals. Acquisition targets with integrated calibration laboratories and wireless protocol engineering teams command strategic premiums. Watch for inflection in EPA enforcement intensity around Clean Air Act pressure vessel monitoring mandates as a demand accelerator signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Invar Strip Production | WIKA's German foundry control insulates margin structures against nickel-iron supply volatility. |
| Calibration-as-a-Service Expansion | Ashcroft's North American laboratory network generates recurring revenue independent of hardware replacement. |
| HART/IO-Link Protocol Integration | Emerson's embedded transmitter architecture bridges mechanical reliability with digital SCADA connectivity. |
| Pharmaceutical Cleanroom Certification | Drift-tolerant sensors with temperature compensation circuits command 40-60% premiums in FDA-regulated facilities. |
| East Asian Distribution Density | Shanghai-Shenzhen corridor concentration absorbs disproportionate procurement volumes under MEE emissions rules. |
Study Parameters
Direct dialogue with plant engineers at chemical processing facilities, calibration laboratory directors, OEM procurement managers, and aftermarket service technicians grounded qualitative insights. Secondary validation drew from EPA enforcement databases, EU F-Gas Regulation implementation reports, SEC instrument manufacturer filings, and customs trade data for nickel-iron alloy shipments. Bottom-up demand modeling across reactor vessel monitoring, pharmaceutical cleanroom, and food processing applications triangulated against top-down industrial instrumentation market sizing.
Segmented outputs across dial, digital, and liquid-in-glass product types; manufacturing, food processing, pharmaceutical, and HVAC end-use verticals; and bimetallic strip, temperature compensation, and calibration technique technology layers structured the analytical framework. CAGRs derived from regression analysis of historical replacement cycles against regulatory enforcement intensity curves, with industrial refrigeration retrofit timelines and pharmaceutical construction permits serving as industry-specific forecast inputs across the projection horizon.
Inputs from EPA enforcement action records and EU ECHA REACH restriction updates were available through the study window; gaps in real-time Chinese MEE emissions monitoring procurement data introduce uncertainty bands around East Asian demand trajectories. Deviation in OSHA process safety management audit frequency or EU F-Gas phase-down acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Americas Sterility Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Self-Testing Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Global Cannabis Testing Market
Testing Services
Global Rapid Test Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
Biomarker Testing Services Market