
 Evening Primrose Oil Market | 2026-2036
Evening Primrose Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Evening Primrose Oil Market Analysis
Organic and cold-pressed certification standards is bifurcating the competitive landscape into premium-validated suppliers and conventional processors. Henry Lamotte Oils GmbH leverages its German extraction heritage to dominate European pharmaceutical-grade supply. CONNOILS LLC anchors North American demand through backward integration into organic seed sourcing. Efamol differentiates via decades of clinical research backing its proprietary evening primrose oil formulations.
Evening primrose oil contains gamma-linolenic acid (GLA) at concentrations of 9-10% in refined grades, extracted through cold-pressing or solvent methods from Oenothera biennis seeds for use in dermatological and nutritional applications. The capsules segment leads value capture due to dose-standardization requirements in pharmaceutical channels, while liquid formats occupy specialty cosmetic manufacturing where formulation flexibility commands premium positioning. Online retail distribution is accelerating fastest as direct-to-consumer supplement brands bypass traditional pharmacy markups.
FDA dietary supplement GMPs and the EU Novel Food Catalogue govern ingredient safety claims and market access across the Atlantic, with EFSA health claim rejections tightening permissible marketing language for GLA-containing products. Health Canada and Australia's TGA impose additional therapeutic goods classifications on high-potency formulations. Stakeholders must monitor evolving pharmacovigilance reporting obligations as regulators scrutinize botanical supplement adverse event databases more closely.
Market Dynamics
The EU Novel Food Catalogue's ingredient approval pathways are compressing market access timelines for new evening primrose oil entrants, forcing suppliers to pre-validate extraction methods and GLA concentration claims before commercial launch. This regulatory architecture privileges established cold-press operators with existing Novel Food registrations.
Growth Catalysts
- EFSA health claim scrutiny:Germany's pharmaceutical-grade demand concentrates around Hamburg and Bremen logistics clusters, pulling certified organic supply toward northern European ports.
- Direct-to-consumer supplement brands:Online retail channels bypass traditional pharmacy markups, expanding addressable consumer bases for dose-standardized capsules.
- Cold-pressed extraction heritage:Multi-generational European oil processors retain technical know-how for pharmaceutical-grade GLA stabilization that solvent methods cannot replicate.
Market Restraints
- Seed supply concentration:Organic Oenothera biennis cultivation clusters in specific temperate zones, exposing processors to regional weather volatility and crop substitution risk.
- FDA dietary supplement GMP compliance costs:Small-scale cold-press operators face disproportionate quality system investments relative to revenue scale.
- Borage oil substitution threat:Higher GLA concentration in competing botanical sources pressures evening primrose oil's positioning in hormonal health applications.
Strategic Opportunities
- Cosmetic formulation flexibility:Liquid format evening primrose oil commands premium positioning in specialty dermatological manufacturing where cold-pressed certification validates ingredient storytelling.
- Australia TGA therapeutic goods pathway:High-potency GLA formulations face lighter regulatory burden in Australian complementary medicine channels compared to EU pharmaceutical classification.
- Health Canada Natural Health Products registration:Monograph-compliant products access pharmacy distribution networks that remain inaccessible to unregistered dietary supplements.
Industry Challenges
- Pharmacovigilance reporting obligations:Botanical supplement adverse event database scrutiny demands dedicated regulatory affairs capacity that mid-tier processors struggle to staff.
- Organic certification audit timelines:Third-party organic validation creates 12-18 month lag between facility investment and commercial shipment authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evening Primrose Oil Market |
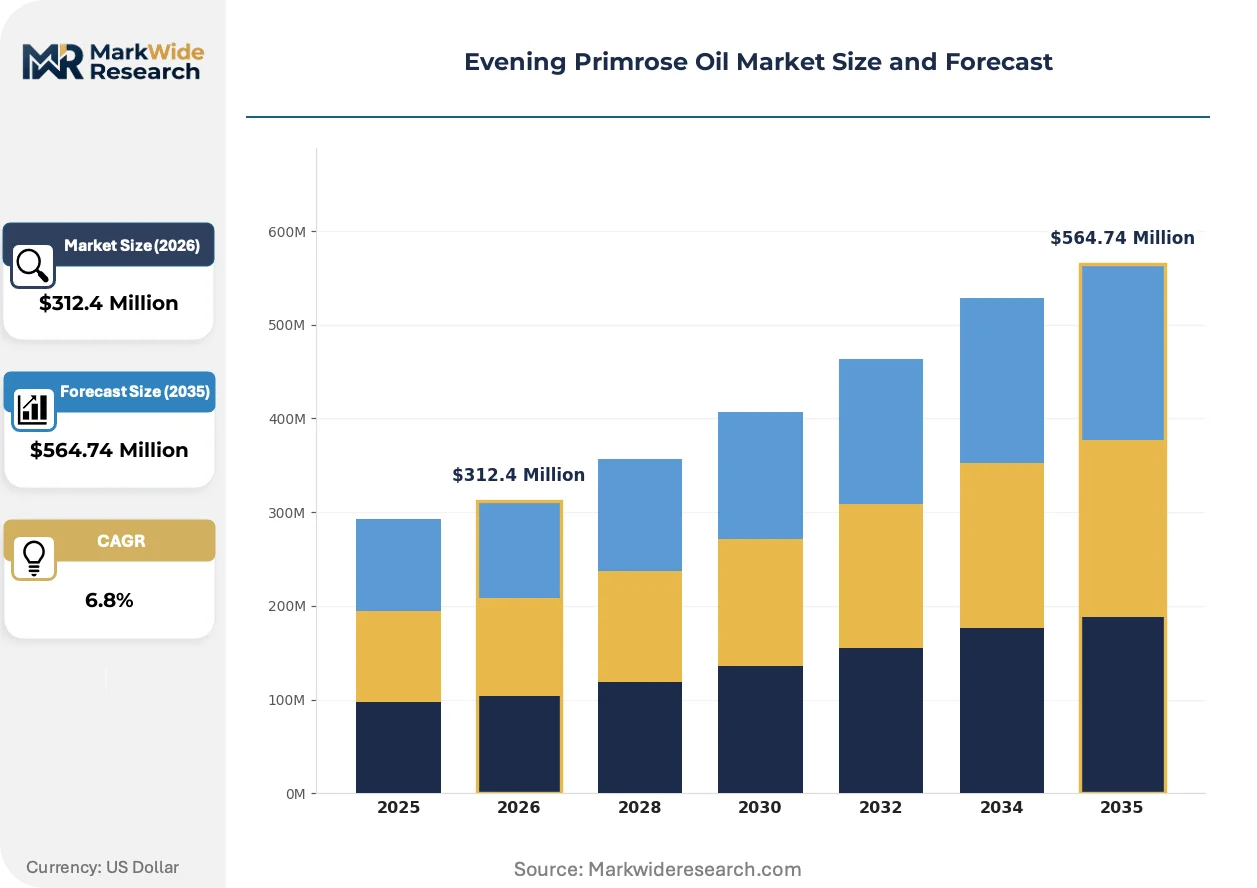
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Liquid, Cream, Powder Application: Cosmetics, Dietary Supplements, Pharmaceutical, Food Industry Packaging Type: Bottles, Sachets, Jars, Bulk Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Henry Lamotte Oils GmbH, CONNOILS LLC, Efamol, OmegaNZ, Grupo Plimon, Sanmark Corporate, Baxco Pharmaceutical Inc., Oil Seed Extractions, Aromex Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evening Primrose Oil Market Emerging Trajectories
Extraction technology diversification is fragmenting competitive positioning across the evening primrose oil value chain. Suppliers now compete on validated method claims rather than commodity GLA concentration alone.
Supercritical CO2 extraction is fragmenting the traditional cold-press versus solvent dichotomy that has governed evening primrose oil quality tiers for decades. Premium cosmetic manufacturers in France and Switzerland are adopting this method for its superior oxidative stability and residue-free positioning. The technology is fragmenting supplier hierarchies by enabling new entrants to leapfrog heritage cold-press credentials with laboratory-validated purity metrics.
REACH registration requirements for imported botanical feedstocks are tightening traceability documentation across EU-bound supply chains. Extractors must now demonstrate seed provenance and pesticide residue testing at batch level. German pharmaceutical manufacturers are responding by consolidating supplier panels to pre-audited organic cooperatives with integrated quality management systems.
Subscription-based supplement replenishment is displacing pharmacy counter purchasing for hormonal health and dermatological applications. Direct-to-consumer brands in the United States and United Kingdom are capturing recurring revenue through personalized dosing protocols. This channel shift concentrates demand among digitally native buyers who prioritize convenience over in-person pharmacist consultation.
Evening Primrose Oil Market Segmentation
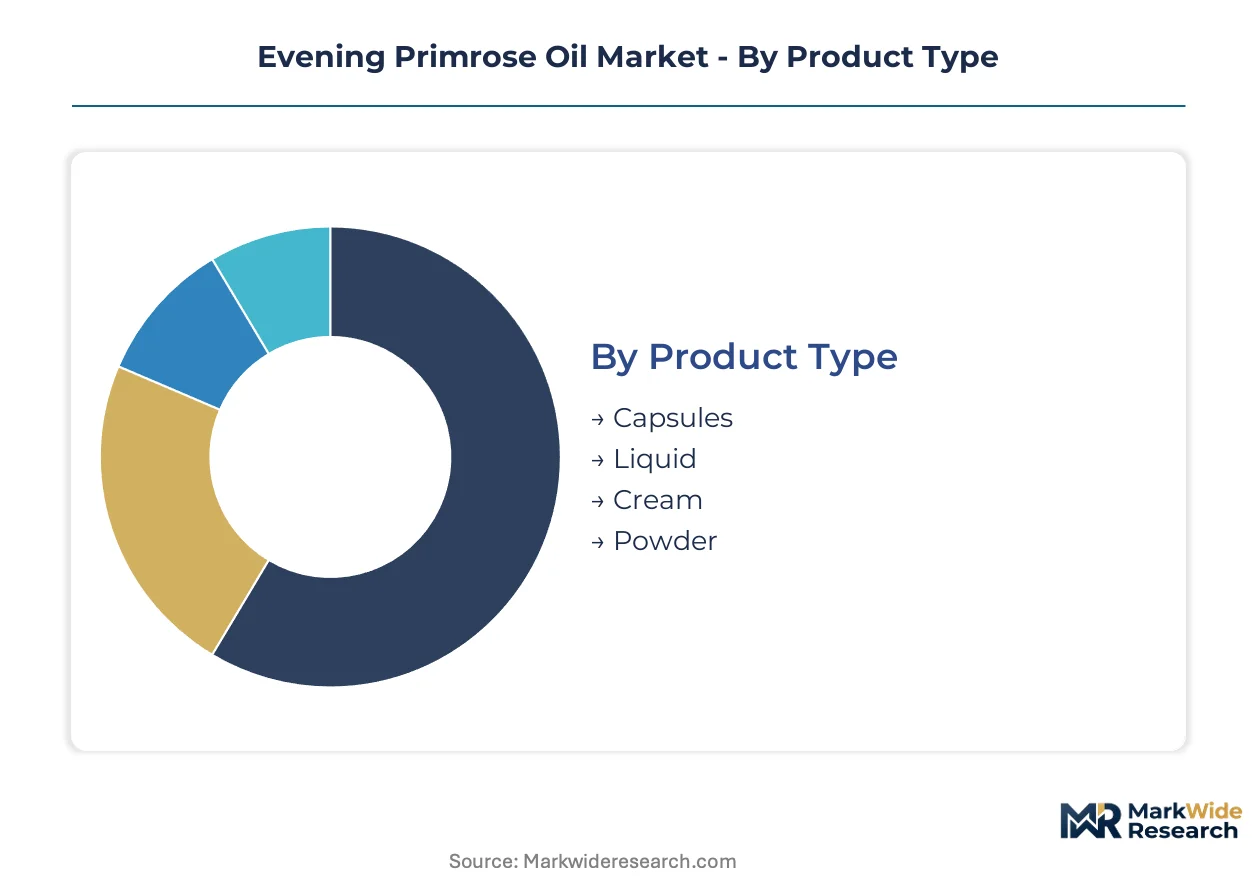
Segmentation in evening primrose oil markets reflects divergent regulatory pathways and end-use specifications. Pharmaceutical-grade GLA concentrates command distinct certification requirements from cosmetic or food-grade alternatives, shaping supplier specialization and margin structures across the value chain.
Product Type:
FDA dietary supplement GMPs and EU pharmaceutical directives create tiered compliance burdens that segment manufacturers by technical capability and capital intensity.
- Capsules:Hard-shell and soft-gel formats contain standardized 500-1300mg evening primrose oil doses with 9-10% GLA concentration. German pharmaceutical manufacturers in Hamburg and Bremen logistics clusters drive demand for dose-standardized capsules that satisfy pharmacy distribution requirements. FDA 21 CFR Part 111 compliance costs favor larger contract manufacturers with dedicated quality systems.
- Liquid:Cold-pressed oil in amber glass or opaque bottles serves cosmetic formulators requiring oxidative stability and batch-level traceability. Specialty dermatological manufacturers in France and Switzerland pay premiums for supercritical CO2 extracted liquids with validated purity metrics. REACH registration requirements for imported feedstocks intensify documentation obligations for liquid format suppliers.
- Cream:Emulsified evening primrose oil formulations target topical hormonal health and eczema management applications.
- Powder:Microencapsulated formats enable functional food fortification and powder supplement blends with extended shelf stability.
Established volume favors Capsules; emerging adoption favors Liquid.
Application:
End-use specifications determine GLA concentration thresholds, extraction method validation, and permissible health claim language.
- Cosmetics:Cold-pressed and supercritical CO2 extracted oils at 9-10% GLA serve premium skincare formulations targeting barrier repair and anti-inflammatory positioning. French and Swiss cosmetic manufacturers concentrate demand for residue-free extraction methods that support clean beauty storytelling. ECHA REACH compliance for botanical feedstocks adds 8-12% to input costs for EU-bound cosmetic supply chains.
- Dietary Supplements:Capsule and soft-gel formats dominate North American and European consumer markets for hormonal health and skin condition management. Direct-to-consumer brands in the United States bypass pharmacy markups through subscription replenishment models. Health Canada Natural Health Products registration opens pharmacy distribution networks unavailable to unregistered supplements.
- Pharmaceutical:Prescription-grade evening primrose oil requires EMA-compliant manufacturing and validated GLA stability data for eczema and mastalgia indications.
- Food Industry:Microencapsulated powders and functional food applications face EFSA Novel Food approval pathways for new ingredient positioning.
Cosmetics capture premium pricing through extraction method differentiation; Dietary Supplements expand most quickly via direct-to-consumer channel displacement.
Packaging Type:
Packaging selection correlates with volume scale, oxidation sensitivity, and end-user handling requirements across supply chain tiers.
- Bottles:Amber glass and opaque PET containers protect liquid evening primrose oil from photodegradation during retail shelf life. German organic retailers and North American health food stores prefer bottle formats for visible quality signaling and dosing flexibility. Child-resistant closure requirements under FDA Poison Prevention Packaging Act add compliance costs for US-bound shipments.
- Sachets:Single-serve foil pouches serve travel-size cosmetics and sample distribution for dermatological brands testing market response.
- Jars:Wide-mouth containers accommodate cream and balm formulations with scoop-accessible textures.
- Bulk:Drum and tote packaging serves cosmetic manufacturers and contract encapsulators with captive filling operations.
Bottles dominate pharmacy and health store distribution; Bulk shipments are climbing the fastest as cosmetic manufacturers consolidate supplier panels.
Distribution Channel:
Channel selection determines margin retention, customer data access, and regulatory classification obligations for evening primrose oil products.
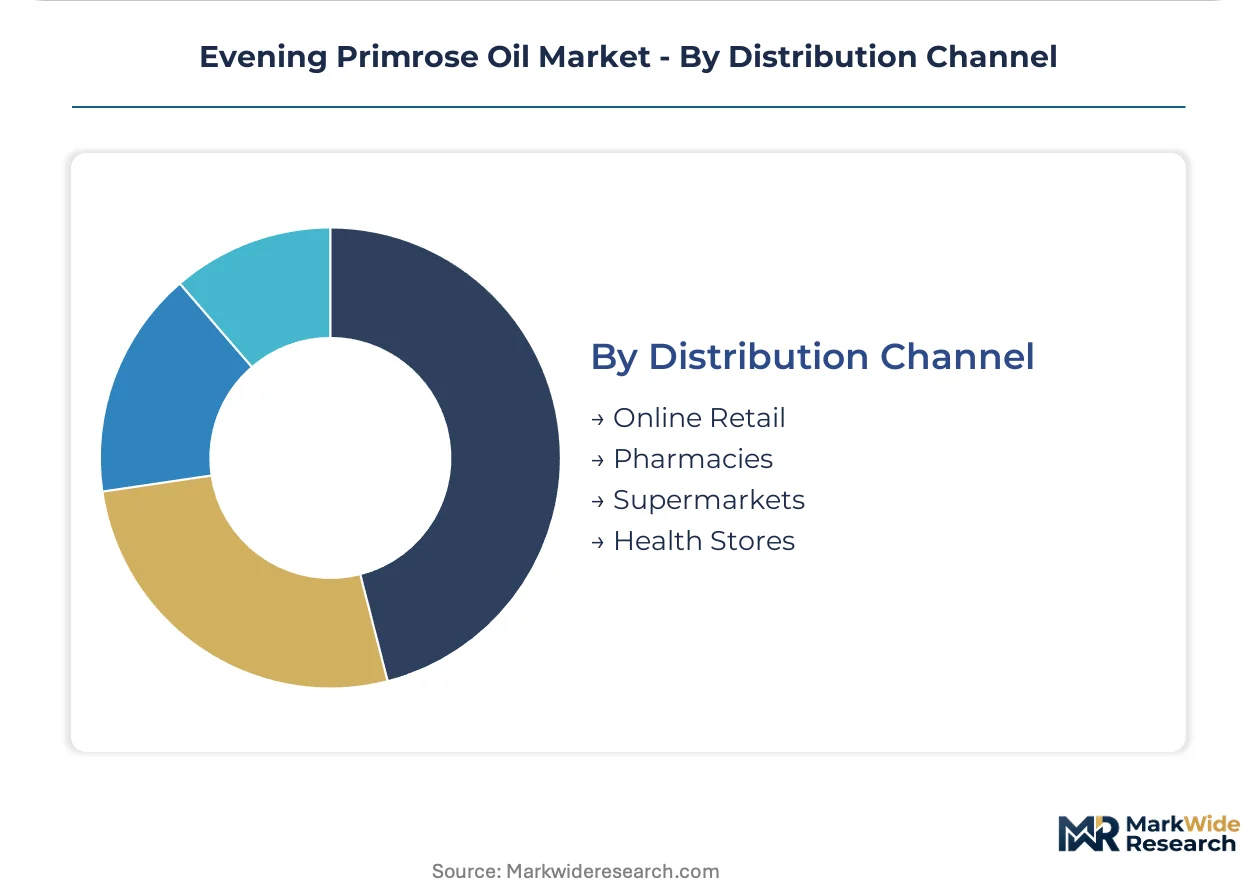
- Online Retail:Direct-to-consumer platforms and marketplace listings bypass traditional wholesale markups for supplement and cosmetic brands. United States and United Kingdom digital-native buyers prioritize subscription convenience over pharmacist consultation, concentrating recurring revenue among brands with personalized dosing protocols. FDA and FTC advertising scrutiny intensifies for health claims made in e-commerce listings.
- Pharmacies:Brick-and-mortar pharmacy counters retain importance for prescription-grade evening primrose oil and pharmacist-recommended supplements. German pharmacy chains require pharmaceutical-grade certification and batch-level documentation that excludes unregistered suppliers.
- Supermarkets:Mass retail placement demands price-competitive positioning and simplified health claim language acceptable to general consumer audiences.
- Health Stores:Specialty retailers emphasize organic certification and cold-pressed extraction storytelling for premium-positioned evening primrose oil.
Pharmacies anchor prescription-grade volume; Online Retail gains share fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for botanical ingredient traceability are redirecting procurement flows toward certified organic supply corridors. Cold-pressed extraction heritage concentrates in temperate climate zones with established seed processing infrastructure. Regulatory divergence between pharmaceutical-grade and cosmetic-grade pathways is forcing suppliers to choose dedicated compliance investments by geography.
Germany
Pharmaceutical-grade demand from Hamburg and Bremen logistics clusters pulls certified organic supply toward northern European ports. EMA pharmaceutical directives and EU Novel Food Catalogue requirements compress market access timelines for new entrants. Cold-press extraction facilities cluster along the Elbe River corridor, with multi-generational processors retaining technical know-how for GLA stabilization.
United States
Direct-to-consumer supplement brands bypass traditional pharmacy markups through subscription replenishment models. FDA dietary supplement GMPs under 21 CFR Part 111 favor larger contract manufacturers with dedicated quality systems. Digital-native buyers concentrate in coastal metropolitan areas where personalized dosing protocols capture recurring revenue.
France
Premium cosmetic manufacturers adopt supercritical CO2 extraction for residue-free positioning in clean beauty formulations. ECHA REACH registration requirements for imported botanical feedstocks intensify documentation obligations at batch level. Lyon and Grenoble specialty chemical clusters host validation laboratories serving supercritical extraction adopters.
China
Domestic omega-6 fatty acid demand expands through functional food and traditional medicine channels. NMPA and SAMR oversight of dietary supplement manufacturing tightens facility licensing requirements. Yangtze River Delta processing hubs integrate backward into organic seed cultivation in temperate northern provinces.
Australia
TGA therapeutic goods classification offers lighter regulatory burden for high-potency GLA formulations compared to EU pharmaceutical pathways. Health practitioner recommendation networks drive pharmacy channel placement for hormonal health applications. Melbourne and Sydney complementary medicine distributors consolidate supply from pre-audited organic cooperatives.
Evening Primrose Oil Market Vendor Landscape
Listed leaders compete with private specialists across extraction method validation and certification tier positioning. The supplier base fragments into heritage cold-press operators, supercritical CO2 technology adopters, and solvent-based commodity processors. Three archetypes dominate: multi-generational European oil mills with pharmaceutical-grade registrations, North American organic specialists with backward integration into seed sourcing, and Asian contract manufacturers serving functional food applications. Competitive moves concentrate on supplier panel consolidation by pharmaceutical buyers and technology licensing agreements for supercritical extraction scale-up.
Within the heritage European tier, Henry Lamotte Oils GmbH represents multi-generational cold-press extraction credentials anchored in German pharmaceutical supply chains. CONNOILS LLC exemplifies North American organic specialists with upstream control over seed procurement. Efamol occupies a position linking decades of clinical research to proprietary formulation positioning in consumer channels.
| Leading Market Players |
|---|
| Henry Lamotte Oils GmbH |
| CONNOILS LLC |
| Efamol |
| OmegaNZ |
| Grupo Plimon |
| Sanmark Corporate |
| Baxco Pharmaceutical Inc. |
| Oil Seed Extractions |
| Aromex Industry |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German pharmaceutical manufacturers and northern European organic cooperatives lock in both cold-pressed supply access and price visibility across volatile seed harvest cycles. These agreements insulate Hamburg and Bremen logistics clusters from spot market fluctuations while embedding quality premiums for EMA-compliant documentation.
Pricing Analysis
Certification level creates the primary spread, with EU Organic and pharmaceutical-grade GLA concentrates commanding substantial premiums over conventional solvent-extracted grades. Three-tier pricing structure across premium, standard, and economy levels reflects extraction method validation, batch traceability depth, and Novel Food registration status. Price differentiation stems from supercritical CO2 residue-free positioning in French cosmetic channels and FDA 21 CFR Part 111 compliance costs for capsule manufacturers. Cost compression in mid-tier cold-pressed supply is intensifying because REACH registration requirements add documentation overhead without commensurate quality tier advancement. Mass retail buyers in supermarket channels exhibit highest price sensitivity, while specialty dermatological manufacturers in Switzerland show lowest elasticity due to formulation flexibility requirements.
Supply Chain Analysis
Organic Oenothera biennis seed availability from temperate cultivation zones in China, Germany, and Canada creates seasonal procurement chokepoints that constrain processor utilization rates. Cold-pressed oil production draws from certified organic seed stocks, pharmaceutical-grade amber glass packaging, and batch-level pesticide residue testing protocols. Single-source vulnerability concentrates in northern Chinese provinces where climate volatility threatens organic cultivation continuity. Distribution runs through pre-audited supplier panels serving German pharmaceutical buyers, direct-to-consumer fulfillment centers in the United States, and cosmetic formulators in France and Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment platforms are reconfiguring this market around recurring revenue economics, with interoperability between personalized dosing protocols and pharmacy distribution networks determining competitive durability.
For Market Incumbents: Fortify supplier panel consolidation by acquiring pre-audited organic cooperatives with integrated quality management systems. Deepen backward integration into captive seed cultivation in temperate zones to mitigate crop substitution risk from borage oil competitors. EMA pharmacovigilance reporting obligations represent the primary regulatory threat requiring dedicated compliance capacity investment. For New Entrants and Emerging Players: Anchor in Australian TGA therapeutic goods pathways where high-potency GLA formulations face lighter classification burden than EU pharmaceutical channels. White-space concentrates in direct-to-consumer subscription models for hormonal health applications, supercritical CO2 extraction services for clean beauty manufacturers, and Health Canada Natural Health Products registration support for pharmacy network access. Go-to-market leverage rests on laboratory-validated purity metrics that bypass heritage cold-press credential requirements. For Investors and Strategic Acquirers: Capital is best deployed toward multi-generational European oil mills with existing Novel Food registrations and established EMA pharmaceutical supply relationships. Long-term viability hinges on extraction method diversification capability and regulatory affairs infrastructure depth across Atlantic jurisdictions. Monitor EFSA health claim adjudication patterns as the critical signal for permissible marketing language expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Enables residue-free positioning for French and Swiss clean beauty manufacturers seeking validated purity metrics. |
| Backward Integration into Organic Seed Cultivation | Secures supply continuity against regional weather volatility and borage oil substitution pressures. |
| Health Canada Natural Health Products Registration | Opens pharmacy distribution networks previously inaccessible to unregistered dietary supplement competitors. |
| Direct-to-Consumer Subscription Platform Launch | Captures recurring revenue from United States and United Kingdom digital-native buyers prioritizing convenience. |
| Novel Food Registration Pre-Validation | Compresses EU market access timelines by securing extraction method and GLA concentration claims before commercial launch. |
Methodological Framework
Operator-level perspectives from cold-press facility managers, organic cooperative procurement leads, pharmaceutical quality affairs directors, cosmetic formulator R&D heads, and direct-to-consumer brand founders anchored the qualitative base. Secondary validation drew from EMA pharmaceutical directives, FDA 21 CFR Part 111 guidance documents, EFSA health claim registers, EU Novel Food Catalogue entries, and customs trade data for Oenothera biennis seed flows. Bottom-up segment sizing triangulated against top-down market value reconstructions across extraction method tiers.
Sensitivity analysis tested forecast robustness against seed supply disruption scenarios, regulatory approval timeline compression, and channel shift acceleration parameters. Modeled dimensions spanned product type, application end-use, extraction technology, certification tier, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization trends, with specific inputs including organic certification audit timelines and supercritical CO2 equipment capacity expansion patterns.
Underlying assumptions cover sustained EU Novel Food enforcement intensity, stable organic cultivation acreage in temperate zones, and continued TGA therapeutic goods pathway accessibility, with deviation risk concentrated in EFSA health claim restriction tightening and climate-induced seed yield volatility. Practitioners should keep alternative scenarios live as pharmacovigilance database scrutiny intensity and subscription platform competitive dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Global Sea Buckthorn Oil Market