
 Aromatherapy Oils Market | 2026-2036
Aromatherapy Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Aromatherapy Oils Market Insights
Single-source botanical supply chains is decoupling from traditional distiller-dependent models as aromatherapy brands diversify raw material procurement across multiple cultivation zones. doTERRA International LLC leverages co-impact sourcing partnerships with smallholder farms across Nepal, Madagascar, and Kenya to secure frankincense and ylang-ylang resin supplies. Young Living Essential Oils LC anchors its competitive position through proprietary Seed to Seal quality protocol covering company-owned and partner farms. NOW Health Group Inc. competes on manufacturing scale, operating GMP-certified facilities that supply private-label essential oils to mass-market retailers.
Aromatherapy oils are volatile plant-derived extracts obtained through steam distillation, cold pressing, or solvent extraction, typically containing concentrated terpenes, esters, and phenolic compounds at purity grades ranging from therapeutic to cosmetic quality; these oils function primarily in inhalation therapy, topical application, and ambient diffusion for stress modulation, sleep enhancement, and complementary wellness protocols. Essential oils dominate value capture within the product type dimension, with lavender, tea tree, and eucalyptus varieties commanding premium pricing due to established clinical validation. Direct sales channels sustain higher per-unit margins through practitioner networks, while online retail experiences the fastest volume expansion as subscription-based replenishment models gain traction among repeat buyers.
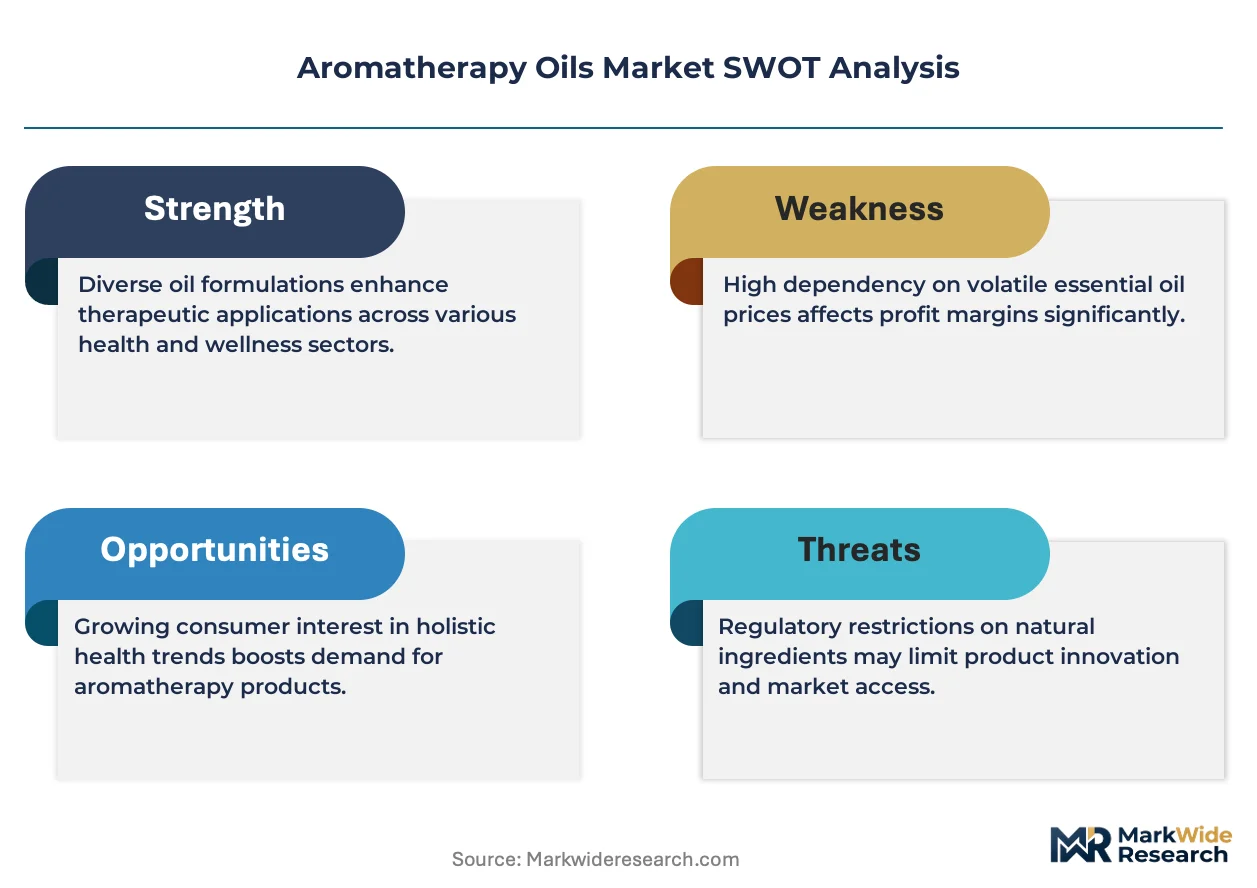
FDA oversight of aromatherapy products marketed with therapeutic claims forces companies to navigate cosmetic-drug regulatory boundaries, with unsubstantiated health assertions triggering warning letters and import detentions. EU REACH and CLP frameworks mandate detailed safety data sheets and allergen labeling for essential oil formulations containing sensitizing compounds like linalool and limonene. ISO 4720 standards for essential oil nomenclature and botanical sourcing documentation provide baseline quality benchmarks that facilitate cross-border trade. Stakeholders must monitor evolving classification decisions by national pharmacovigilance agencies that could reclassify popular essential oils from cosmetic to medicinal status, fundamentally altering market access requirements.
Market Dynamics
EU REACH and CLP allergen disclosure mandates are forcing aromatherapy brands to reconfigure labeling systems and reformulate high-linalool blends, compressing margins while accelerating compliance technology procurement across European supply chains.
Growth Catalysts
- Wellness tourism expansion:Thai and Balinese spa operators are embedding aromatherapy protocols into hospitality packages, creating captive demand for bulk essential oil supplies.
- REACH compliance technology:ECHA-mandated safety data sheet digitization is driving software adoption that streamlines cross-border essential oil shipments.
- Steam distillation automation:Precision temperature controls are reducing terpene degradation in lavender and eucalyptus processing, improving therapeutic-grade yields.
Market Restraints
- Frankincense supply concentration:Somaliland and Ethiopia smallholder networks face climate volatility and political instability that disrupt resin harvesting cycles.
- Cold-pressed citrus input costs:Bergamot and orange peel oil production depends on Mediterranean agricultural yields vulnerable to drought-induced price spikes.
- FDA cosmetic-drug boundary enforcement:Warning letters targeting therapeutic claims force brands to either dilute marketing or pursue costly drug approval pathways.
Strategic Opportunities
- Australian direct-to-consumer penetration:Subscription-based replenishment models are capturing repeat buyers in underdeveloped urban markets outside Sydney and Melbourne.
- Clinical aromatherapy protocols:Hospital integrative medicine departments in Germany are piloting lavender inhalation for pre-surgical anxiety management.
- ISO 4720 certification convergence:Standardized botanical nomenclature is reducing trade friction between Nepalese distillers and European formulators.
Industry Challenges
- Gas chromatography-mass spectrometry analyst shortage:Authenticity verification of adulterated oils requires specialized technicians scarce in emerging cultivation zones.
- Organic certification timeline compression:Three-year conversion periods for conventional farmland delay supply responses to premium segment demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aromatherapy Oils Market |
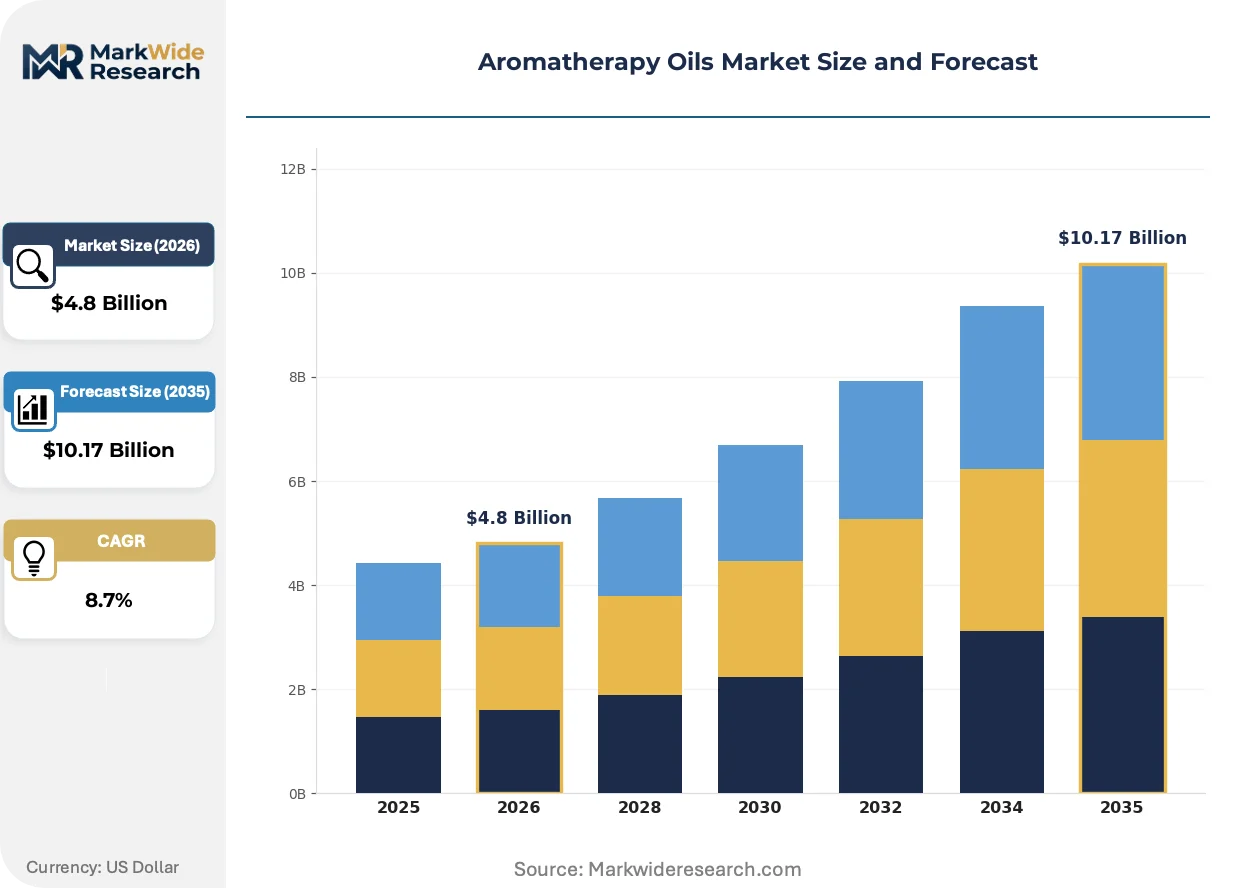
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Carrier Oils, Blending Oils, Fragrance Oils End User: Retail Consumers, Spa and Wellness Centers, Aromatherapy Practitioners, Healthcare Providers Application: Massage Therapy, Home Fragrance, Skin Care, Sleep Aid Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Plant Therapy LLC, Edens Garden, doTERRA International LLC, Aromaaz International, Eden Botanicals, Young Living Essential Oils LC, Rocky Mountain Oils LLC, Florihana, NOW Health Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aromatherapy Oils Market Trends and Innovations
Supercritical CO2 extraction is displacing traditional steam distillation for heat-sensitive botanicals, while blockchain traceability platforms and inhalable delivery formats are restructuring how purity is verified and consumed across therapeutic applications.
Supercritical CO2 extraction technology is integrating into commercial-scale operations for jasmine and rose absolute production, preserving volatile compounds degraded by thermal processing. German pharmaceutical-grade manufacturers are adopting these systems fastest, securing contracts with cosmetic formulators demanding residue-free extracts. This capital-intensive shift is compressing the supplier base toward integrated processors with captive CO2 infrastructure.
EU CLP regulation revisions are expanding mandatory allergen labeling from 26 to 80+ fragrance compounds, including linalool and limonene oxidation products. Formulators must redesign packaging and reformulate bestselling blends, with compliance costs falling heaviest on small-batch artisan producers. French and German regulators are coordinating implementation timelines, creating a phased but inevitable compliance cliff.
Subscription-based replenishment is displacing one-time retail purchases among repeat therapeutic oil users, particularly in United Kingdom and Australian metropolitan markets. Direct-to-consumer platforms are capturing customer lifetime value through algorithmic scent profiling and auto-ship logistics. This channel shift concentrates volume with digitally native brands capable of warehousing volatile inventory safely.
Aromatherapy Oils Market Segmentation
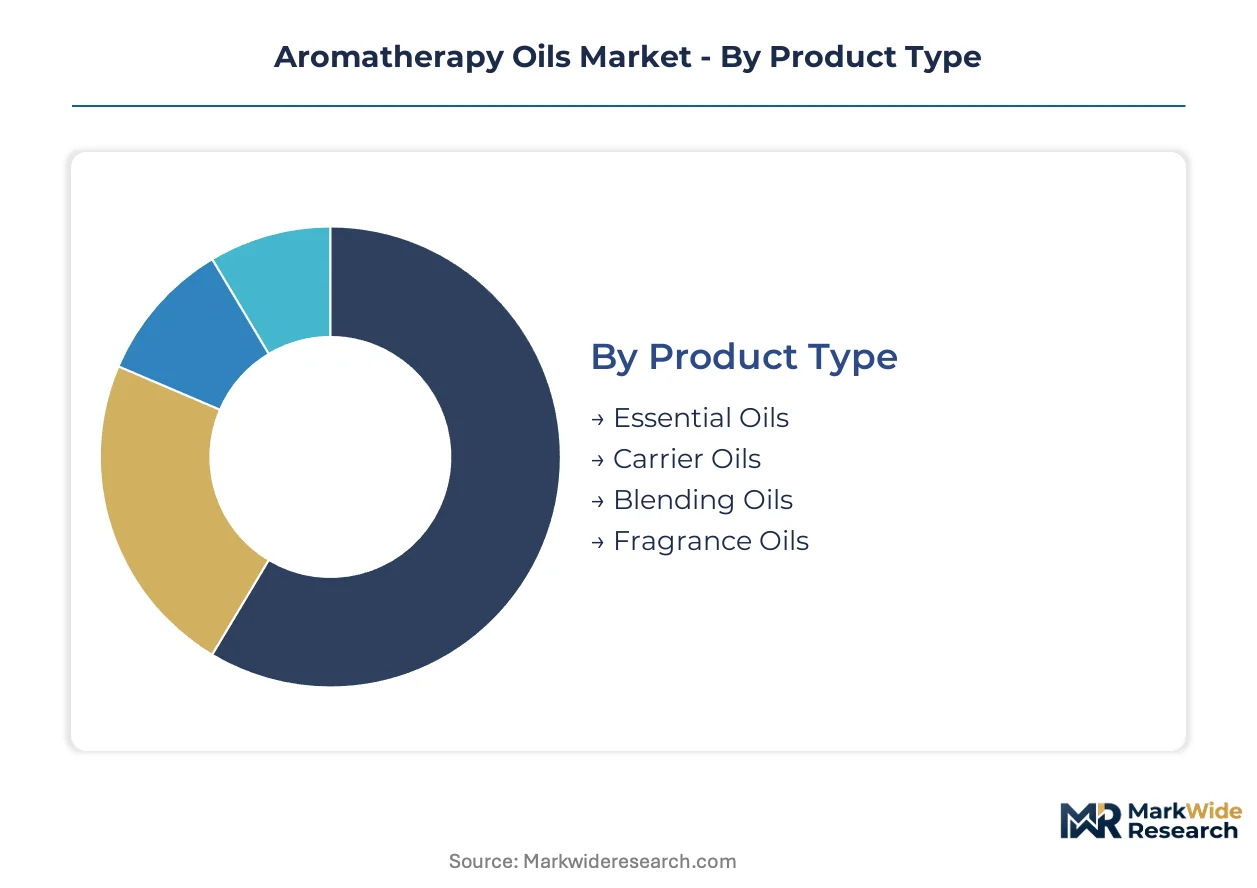
Aromatherapy oils fragment across four intersecting dimensions where therapeutic positioning, channel economics, and regulatory exposure create divergent margin profiles. Each category reveals distinct procurement patterns between clinical-grade formulators and ambient wellness consumers.
Product Type:
Volume concentrates in commodity-grade extracts while premium capture belongs to certified-therapeutic grades with full botanical traceability.
- Essential Oils:Concentrated volatile extracts obtained through steam distillation or cold pressing, containing terpenes and phenolic compounds at purity grades from cosmetic to pharmaceutical specifications. Demand clusters in German and Australian direct-to-consumer channels where subscription replenishment models dominate repeat purchasing for lavender, tea tree, and eucalyptus varieties.
- Carrier Oils:Fixed vegetable oils including jojoba, sweet almond, and fractionated coconut that dilute essential oils for topical application. Spa and wellness operators in Thailand and Bali source these in bulk for massage therapy protocols, with organic certification commanding price premiums in European procurement tenders.
- Blending Oils:Pre-formulated combinations targeting specific wellness outcomes such as stress modulation or respiratory support.
- Fragrance Oils:Synthetic or nature-identical aromatic compounds used primarily in ambient diffusion and home fragrance applications.
Mature deployment sits with Essential Oils. Newer deployment is concentrated in Blending Oils.
End User:
Procurement authority separates between institutional buyers with formulation expertise and individual consumers driven by algorithmic recommendation engines.
- Retail Consumers:Individual purchasers acquiring oils for personal inhalation, topical, or diffusion use. United Kingdom and Australian metropolitan markets show the steepest expansion trajectory for subscription-based auto-replenishment platforms with scent profiling capabilities.
- Spa and Wellness Centers:Hospitality and treatment facilities embedding aromatherapy into service menus. Thai operators are expanding bulk procurement of frankincense and ylang-ylang as wellness tourism packages standardize aromatic protocols.
- Aromatherapy Practitioners:Certified therapists prescribing specific oil combinations for clinical outcomes.
- Healthcare Providers:Hospital integrative medicine departments piloting lavender inhalation for pre-surgical anxiety management in German clinical settings.
Volume leadership belongs to Retail Consumers. Margin concentration favors Healthcare Providers.
Application:
Functional outcomes range from sensory ambiance to clinically validated physiological intervention, with regulatory scrutiny intensifying at the therapeutic boundary.
- Massage Therapy:Topical application requiring carrier oil dilution for muscular relaxation and circulation enhancement. EU REACH and CLP allergen disclosure mandates are forcing reformulation of high-linalool blends used in professional spa environments.
- Home Fragrance:Ambient diffusion for olfactory environment modification. Cold-pressed citrus inputs face drought-induced price volatility in Mediterranean sourcing regions.
- Skin Care:Cosmetic formulations leveraging antimicrobial and anti-inflammatory properties.
- Sleep Aid:Inhalation protocols targeting circadian rhythm modulation through sedative terpene profiles.
Regulatory exposure concentrates in Sleep Aid claims. Ambient use dominates volume in Home Fragrance.
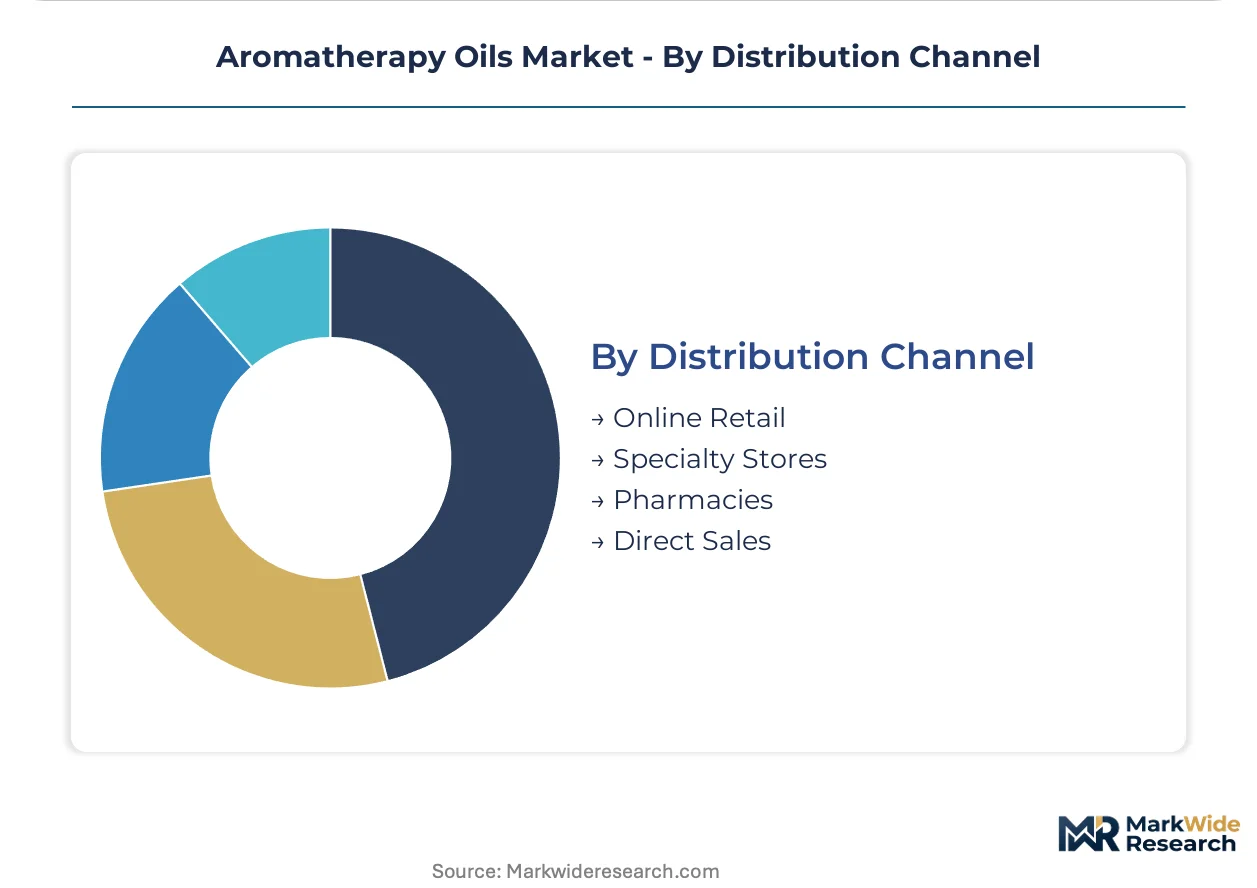
Distribution Channel:
Channel selection determines compliance burden, with direct sales sustaining margin premiums while online retail captures volume expansion.
- Online Retail:E-commerce platforms and brand-direct websites with algorithmic personalization. German, United Kingdom, and Australian markets show fastest volume expansion as warehousing protocols for volatile inventory improve.
- Specialty Stores:Brick-and-mortar retailers with trained staff and sampling capabilities. These outlets face margin compression from EU CLP labeling requirements affecting packaging redesign costs.
- Pharmacies:Licensed retail with pharmacist oversight, particularly relevant for products approaching medicinal classification.
- Direct Sales:Practitioner networks and multi-level marketing channels with higher per-unit margins sustained through relationship-based replenishment.
Established infrastructure sits with Direct Sales. Digital-native brands are gaining share fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Somali frankincense resin and Nepalese wintergreen anchor raw-material procurement for European and North American formulators, while Australian eucalyptus and Indonesian ylang-ylang plantations reshape distillation geography.
Germany
Hospital integrative medicine departments in Berlin and Munich pilot lavender inhalation protocols for pre-surgical anxiety management. ECHA REACH mandates digitize safety data sheets for cross-border essential oil shipments. Bavarian pharmaceutical-grade manufacturers adopt supercritical CO2 extraction systems for residue-free jasmine and rose absolute production.
United Kingdom
Metropolitan subscription platforms capture repeat therapeutic oil buyers through algorithmic scent profiling and auto-ship logistics. CLP regulation revisions expand mandatory allergen labeling from 26 to 80-plus fragrance compounds. London-based direct-to-consumer brands warehouse volatile inventory under improved protocols for same-day fulfillment.
Australia
Eucalyptus and tea tree cultivation clusters in New South Wales and Victoria supply domestic distillation and Asian export markets. TGA oversight of therapeutic claims forces cosmetic-drug boundary navigation for sleep-aid and stress-modulation products. Sydney and Melbourne digital-native brands expand subscription replenishment into underdeveloped urban markets.
Thailand
Wellness tourism operators in Phuket and Chiang Mai embed aromatherapy protocols into hospitality packages, creating captive demand for bulk frankincense and ylang-ylang supplies. National pharmaceutical regulators monitor essential oil quality standards for spa and wellness center procurement. Bangkok-based hospitality distributors consolidate bulk carrier oil sourcing for massage therapy applications.
United States
FDA warning letters targeting unsubstantiated therapeutic claims force brands to dilute marketing or pursue costly drug approval pathways. Direct sales practitioner networks sustain higher per-unit margins through relationship-based replenishment. Utah and Idaho host concentrated multi-level marketing headquarters for essential oil distribution.
Aromatherapy Oils Market Competitive Landscape
Strategic partnerships dominate the current landscape as brands secure smallholder farm relationships across volatile sourcing regions. The vendor base stratifies between integrated processors with captive extraction infrastructure and digital-native formulators lacking backward supply control. Three archetypes define positioning: multi-level marketing networks with practitioner-driven distribution, pharmaceutical-grade manufacturers with GMP-certified facilities, and artisan producers with organic certification premiums. Competitive moves concentrate on co-impact sourcing alliances and subscription platform technology licensing.
Among integrated supply-chain specialists, doTERRA International LLC and Young Living Essential Oils LC exemplify contrasting procurement philosophies, with the former leveraging smallholder partnerships across Nepal and Madagascar while the latter anchors quality protocols through company-owned and partner farm networks. NOW Health Group Inc. occupies a scale-driven position, supplying private-label essential oils to mass-market retailers through GMP-certified manufacturing facilities. These three entities represent the spectrum from relationship-based sourcing to volume manufacturing.
| Leading Market Players |
|---|
| Plant Therapy LLC |
| Edens Garden |
| doTERRA International LLC |
| Aromaaz International |
| Eden Botanicals |
| Young Living Essential Oils LC |
| Rocky Mountain Oils LLC |
| Florihana |
| NOW Health Group Inc. |
| Others |
Pricing and Supply Chain Analysis
Frankincense resin procurement costs from Somaliland and Ethiopian smallholder networks cascade through three distinct pricing tiers, with pharmaceutical-grade manufacturers absorbing climate-induced volatility while cosmetic-grade buyers shift toward synthetic alternatives.
Pricing Analysis
Warranty-backed batch certification unbundles from base product pricing, creating a two-tier structure where ISO 4720-compliant traceability commands substantial premiums over undocumented commodity grades. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified therapeutic oils from cosmetic-grade extracts and private-label commodity supplies. Cost compression in the economy tier intensifies because REACH-mandated allergen labeling is forcing small-batch artisan producers toward either consolidation or exit. Spa and wellness operators in Thailand exhibit highest price sensitivity due to bulk volume procurement, while German hospital integrative medicine departments demonstrate lowest sensitivity given clinical validation requirements.
Supply Chain Analysis
Dual-sourcing qualification requirements from European formulators are compelling distiller networks in Nepal, Madagascar, and Kenya to maintain parallel supply relationships with multiple buyer consortia. Raw material dependencies center on Somali frankincense resin, Australian eucalyptus leaf, and Indonesian ylang-ylang flower. Single-source vulnerability concentrates in climate-stressed Mediterranean citrus peel for bergamot and orange cold-pressed oils. Distribution runs through direct-to-consumer platforms in Germany, the United Kingdom, and Australia, with subscription logistics capturing repeat buyer volume fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction systems are displacing legacy steam distillation infrastructure, creating asymmetric investment burdens between capital-rich integrated processors and heat-dependent artisan distillers facing obsolescence risk.
For Market Incumbents: Lock in captive CO2 extraction capacity through equipment financing partnerships with German pharmaceutical-grade manufacturers, insulating margin position against terpene degradation yield losses that plague thermal competitors. Secure multi-year offtake agreements with Somaliland and Ethiopian frankincense cooperatives before climate volatility triggers supply rationing. Prioritize ISO 4720 certification convergence to reduce trade friction with European formulators facing REACH compliance deadlines. For New Entrants and Emerging Players: Subscription-platform algorithms targeting underdeveloped Australian urban markets outside Sydney and Melbourne offer the most penetrable white-space entry, bypassing incumbent saturation in established metropolitan corridors. Direct-to-consumer auto-replenishment models with scent profiling capabilities capture customer lifetime value through warehousing protocols for volatile inventory. Clinical aromatherapy protocols in German hospital integrative medicine departments present a second viable beachhead, leveraging lavender inhalation pilot programs for pre-surgical anxiety management. For Investors and Strategic Acquirers: Distressed-cycle entries favor GMP-certified mid-scale processors in Bavaria with underutilized supercritical CO2 infrastructure and existing European formulator relationships. Long-term viability over the coming decade hinges on backward integration into cultivation zones with political stability premiums relative to Horn of Africa sourcing. Watch for ECHA CLP implementation timeline acceleration as the inflection signal that compresses artisan producer margins and triggers consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Preserves heat-sensitive jasmine and rose volatile compounds for pharmaceutical-grade contracts. |
| Co-Impact Sourcing Partnerships | Secures frankincense and ylang-ylang resin through Nepalese and Kenyan smallholder networks. |
| REACH Compliance Technology Investment | Automates safety data sheet digitization for cross-border European essential oil shipments. |
| Subscription Platform Development | Captures repeat buyers through algorithmic scent profiling in United Kingdom and Australian markets. |
| Clinical Protocol Validation | Generates lavender inhalation evidence base for German hospital integrative medicine adoption. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with essential oil distiller operators, spa procurement managers, pharmaceutical formulators, and EU regulatory affairs specialists. ECHA REACH guidance documents, FDA warning letter archives, TGA therapeutic claim determinations, and ISO 4720 nomenclature standards provided cross-referenced validation. Bottom-up volume modeling from cultivation zone harvest estimates reconciled against top-down demand aggregation from channel shipment data.
Data-stream reconciliation across the projection horizon applied segmented growth assumptions by product type, end user archetype, application function, and distribution channel. Therapeutic-grade versus cosmetic-grade purity specifications, organic certification penetration rates, and subscription platform adoption curves informed category-specific trajectory modeling. CAGRs were derived from compound growth path calibration against historical channel expansion patterns and regulatory implementation timelines.
The model holds under stable EU CLP implementation schedules and continued wellness tourism recovery in Southeast Asia; deviation in Somali frankincense harvest yields or REACH allergen threshold revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Global Pet Food Flavors Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Pericarp Waste Market