
 Grape Seed Extract in Pet Food Application Market | 2026-2036
Grape Seed Extract in Pet Food Application Market Size, Share, and Industry Trends Forecast 2026-2036
Grape Seed Extract in Pet Food Application Market Foresight
Specialty pet retail and veterinary clinic channels is reconfiguring how grape seed extract reaches end buyers, with premium placement replacing mass-market shelf strategies. Kemin Industries leverages its vertical integration in antioxidant manufacturing to sustain supply consistency across North American veterinary networks. Botaniex Inc. anchors its competitive position through concentrated proanthocyanidin standardization, while Nexira competes in European markets with clean-label extraction credentials.
Grape seed extract in pet food application comprises polyphenolic compounds derived from Vitis vinifera seeds, typically standardized to 85-95% proanthocyanidin content through aqueous ethanol extraction and spray-drying into powder or granule form. Its primary commercial purpose centers on delivering antioxidant, anti-inflammatory, and circulatory support claims in canine and feline nutritional formulations. Powder formulations currently dominate manufacturing throughput due to blending compatibility with extruded kibble and biscuit matrices, while liquid extract variants represent the fastest-growing segment driven by wet food and supplement applications. Pet food manufacturers command the largest end-user volume, though veterinarian-directed channels capture disproportionate margin pools through prescription-grade positioning.
FDA Center for Veterinary Medicine guidelines, AAFCO ingredient definition protocols, and EU Feed Additives Regulation collectively govern market access and label claim permissibility for polyphenol-based pet supplements. These frameworks compel suppliers to invest in GRAS self-affirmation or EFSA-compliant safety dossiers before commercial scale-up. Stakeholders must monitor evolving tolerance thresholds for condensed tannin levels and emerging state-level restrictions on antioxidant marketing language in companion animal products.
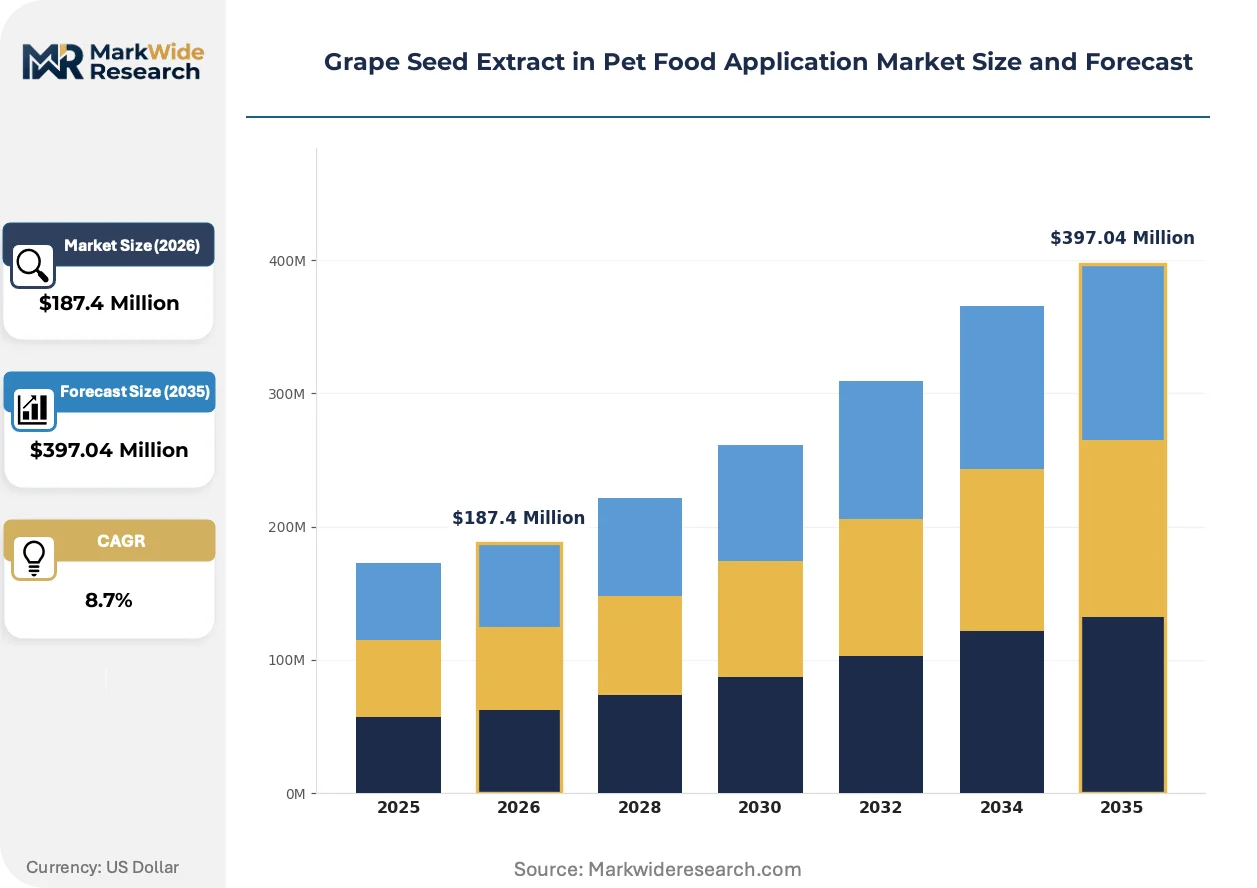
Market Dynamics
Polyphenol standardization requirements are compressing supplier margins while veterinary endorsement protocols reshape channel economics across companion animal nutrition.
Growth Catalysts
- EU Green Deal ingredient traceability mandates:Feed additive suppliers are accelerating EFSA-compliant dossier investments to preempt market access barriers. Procurement teams now prioritize certified sustainable extraction partners.
- Veterinary prescription-grade positioning:Clinic-directed supplement channels capture disproportionate margin pools as pet owners seek preventive health validation from licensed practitioners.
- Wet food matrix compatibility:Liquid extract variants penetrate premium formulations where aqueous solubility enables functional claim integration.
Market Restraints
- Condensed tannin tolerance thresholds:FDA Center for Veterinary Medicine guidelines impose upper limits that constrain proanthocyanidin concentration in canine formulations.
- Grape pomace supply concentration:Wine industry byproduct availability fluctuates with harvest cycles, creating input cost volatility for aqueous ethanol extraction facilities.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and ethoxyquin retain cost advantages in economy-tier kibble despite clean-label pressure.
Strategic Opportunities
- Direct-to-consumer subscription channels:United States pet owners demonstrate willingness to automate recurring supplement purchases when paired with veterinary telehealth integration.
- Feline therapeutic nutrition:Underdeveloped antioxidant positioning in cat food creates white space as renal and circulatory support claims gain traction.
- AAFCO ingredient definition expansion:Emerging recognition pathways for novel polyphenol delivery systems enable first-mover advantage in standardized extract categories.
Industry Challenges
- GRAS self-affirmation timeline compression:FDA notification periods extend 18-24 months, delaying commercial scale-up for novel extraction methodologies.
- Cross-matrix stability engineering:Proanthocyanidin degradation during extrusion requires capital-intensive encapsulation technology deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grape Seed Extract in Pet Food Application Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Granules, Liquid Extract, Powder, Tablets End User: Pet Owners, Pet Food Manufacturers, Veterinarians, Animal Nutritionists Formulation Type: Biscuit, Kibble, Wet Food, Supplements Distribution Channel: Online Retail, Specialty Stores, Veterinary Clinics, Supermarkets |
| Companies Covered | Botaniex Inc., Naturex, Kemin Industries, Hangzhou Green Sky Biotechnology Co., Ltd., Maypro, Polyphenolics, Nexira, Royal Grapeseed, Indena S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grape Seed Extract in Pet Food Application Market Shifts & Advancements
Extraction technology convergence with veterinary diagnostic integration is reconfiguring how bioactive compounds demonstrate efficacy in companion animal formulations.
Supercritical CO2 extraction is collapsing the cost differential between conventional solvent-based methods and clean-label alternatives. Premium pet food manufacturers in North America and Western Europe are adopting these systems at accelerated capex cycles. The technology is collapsing barriers to organic certification while compressing residual solvent testing burdens.
EU F-Gas Regulation phase-down schedules are pressuring spray-drying operations to adopt alternative thermal processing. European extraction facilities face retrofit deadlines that favor aqueous concentration methods over conventional drying towers. Wet food specialists in Germany and France are responding by sourcing pre-concentrated liquid extracts to bypass drying-stage compliance costs.
Subscription-based preventive health bundles are displacing single-transaction supplement purchases. Veterinary clinic networks in the United States are unbundling physical examinations from recurring nutritional counseling, creating dedicated channels for antioxidant education. California and Texas metropolitan markets exhibit the highest concentration of these hybrid digital-physical service models.
Grape Seed Extract in Pet Food Application Market Segmentation
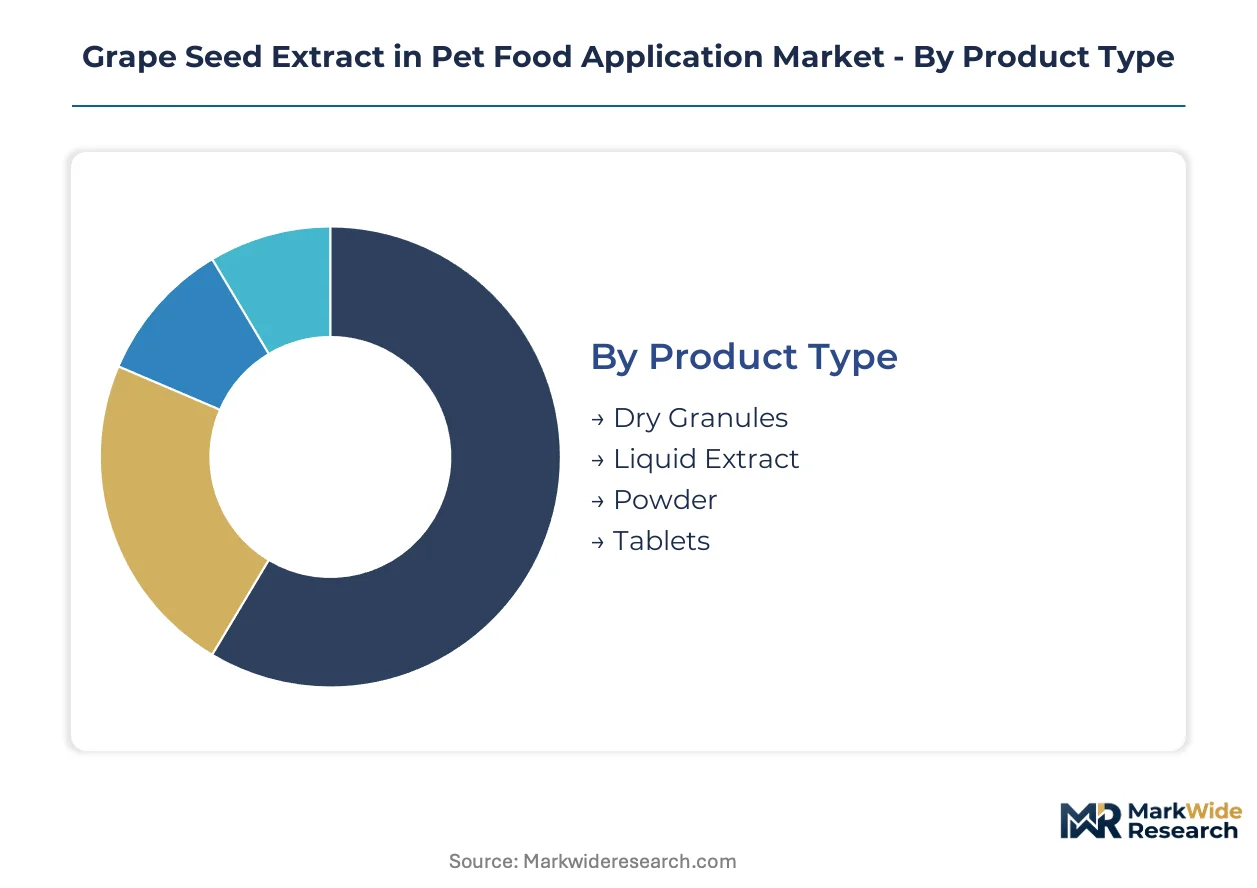
Segmentation in grape seed extract procurement reveals divergent technical requirements across formulation matrices and channel economics. Product form dictates extraction method investments while end-user sophistication determines margin capture potential.
Product Type:
Cycle times vary dramatically: powder and granule formats turn inventory weekly through extrusion facilities, while liquid extracts face longer procurement cycles tied to wet food production schedules.
- Powder:Spray-dried proanthocyanidin concentrates standardized to 85-95% purity dominate manufacturing throughput. Pet food extrusion facilities in the United States and Germany absorb the highest volumes for kibble fortification, driven by blending compatibility and shelf stability requirements.
- Liquid Extract:Aqueous ethanol concentrates enable functional claim integration in wet food matrices where solubility determines bioavailability. Premium manufacturers in France and California source these for renal support formulations targeting feline therapeutic nutrition.
- Dry Granules:Agglomerated particles improve flow properties for high-speed biscuit production lines.
- Tablets:Compressed dosage forms serve veterinary-directed supplement channels with precise dosing requirements.
Powder anchors the volume base while liquid extract gains share at the steepest rate.
End User:
Cost stratification separates commodity procurement from premium positioning, with veterinary endorsement commanding the highest per-kilogram pricing.
- Pet Food Manufacturers:Volume buyers driving standardization protocols for proanthocyanidin content. These processors negotiate long-term contracts with extraction facilities to secure wine industry byproduct supply chains.
- Veterinarians:Clinic-directed channels capture disproportionate margin pools through prescription-grade positioning and preventive health validation. United States metropolitan markets show the highest concentration of these networks.
- Pet Owners:Direct purchasers through subscription channels automate recurring supplement purchases.
- Animal Nutritionists:Formulation consultants influence specification standards for therapeutic diets.
Pet food manufacturers absorb the largest absolute tonnage while veterinarians deliver the highest per-unit economics.
Formulation Type:
Application requirements dictate thermal stability thresholds and encapsulation investments across matrix categories.
- Kibble:Extruded dry food matrices require heat-stable proanthocyanidin variants. Proanthocyanidin degradation during high-temperature processing necessitates capital-intensive encapsulation technology deployment in North American facilities.
- Wet Food:Aqueous matrices enable direct liquid extract incorporation without drying-stage costs. German and French manufacturers leverage EU F-Gas Regulation pressure to source pre-concentrated extracts bypassing spray-drying compliance burdens.
- Biscuit:Baked matrices demand modified release characteristics for palatability retention.
- Supplements:Standalone delivery formats enable highest concentration claims for therapeutic positioning.
Kibble commands the production volume base while wet food climbs the fastest on clean-label migration.
Distribution Channel:
Channel selection determines regulatory compliance burden and customer education requirements.
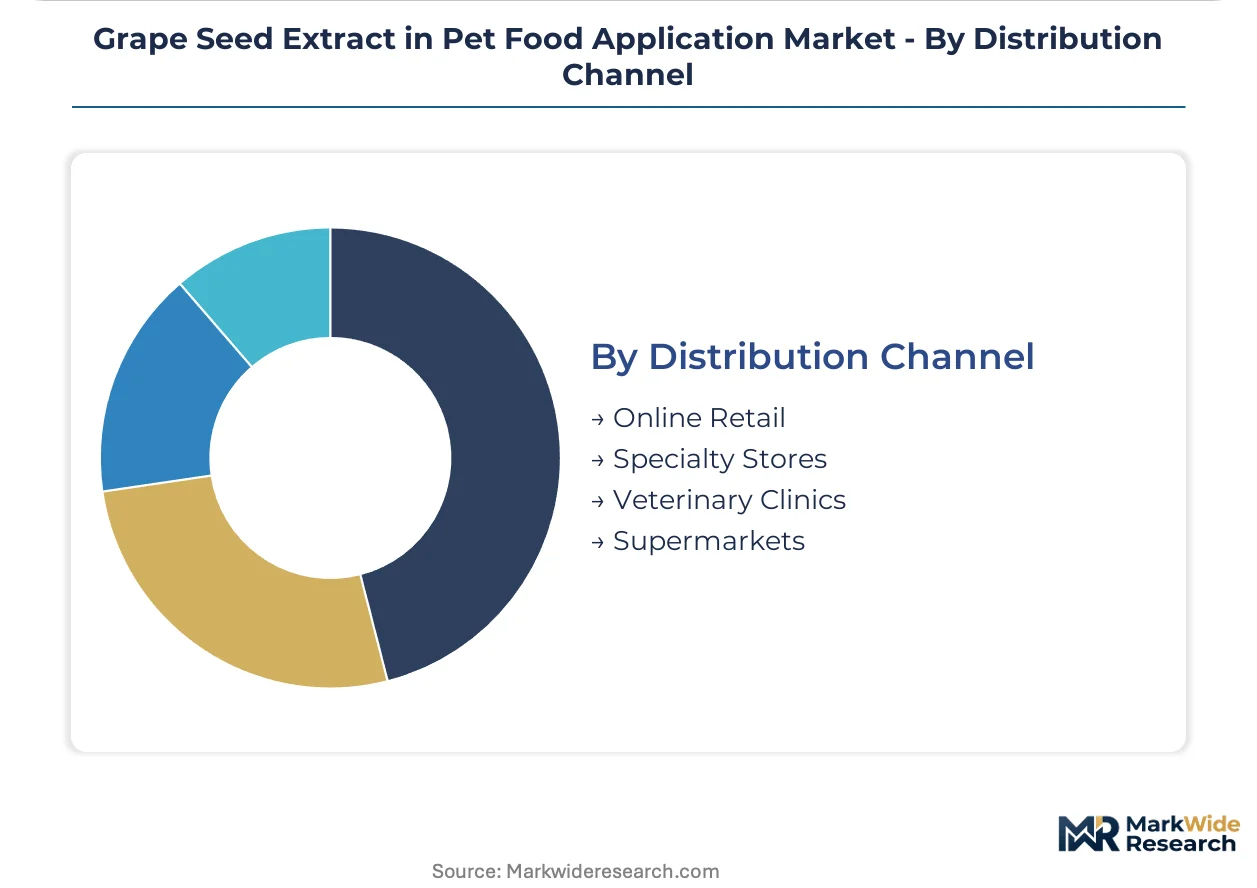
- Specialty Stores:Premium placement replaces mass-market shelf strategies with trained staff delivering antioxidant education. These outlets concentrate in California and Texas metropolitan markets.
- Veterinary Clinics:Prescription-grade positioning with GRAS-affirmed products captures validation-seeking pet owners. FDA Center for Veterinary Medicine guidelines shape permissible marketing language in these channels.
- Online Retail:Direct-to-consumer subscription channels automate recurring purchases when paired with veterinary telehealth integration.
- Supermarkets:Mass-market penetration faces synthetic antioxidant substitution pressure from economy-tier kibble.
Specialty stores anchor current volume while veterinary clinics expand share on preventive health prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine guidelines anchor regulatory frameworks in the United States, the dominant geography for veterinary-endorsed supplement channels and direct-to-consumer subscription models. Procurement teams across four additional markets navigate distinct compliance architectures and supply chain configurations.
United States
Veterinary telehealth integration and subscription automation drive channel innovation in California and Texas metropolitan markets. FDA notification timelines for GRAS self-affirmation extend commercialization cycles for novel extraction methodologies. Kemin Industries maintains supply consistency across North American veterinary networks through captive antioxidant manufacturing assets.
Germany
Wet food specialists in Bavaria and Baden-Württemberg source pre-concentrated liquid extracts to bypass EU F-Gas Regulation compliance costs in spray-drying operations. EFSA-compliant dossier investments preempt market access barriers under tightening ingredient traceability mandates. Stuttgart-area extraction facilities face retrofit deadlines favoring aqueous concentration methods.
France
Premium manufacturers in Île-de-France and Provence-Alpes-Côte d'Azur integrate aqueous ethanol concentrates for renal support formulations targeting feline therapeutic nutrition. EU Green Deal procurement protocols prioritize certified sustainable extraction partners. Lyon-clustered pet food R&D centers validate proanthocyanidin bioavailability claims in wet food matrices.
China
Hangzhou-based biotechnology suppliers standardize proanthocyanidin concentrates for export markets amid evolving GB standards for feed additive safety. Domestic pet food manufacturers in Yangtze River Delta industrial zones absorb powder formulations for kibble fortification. Shanghai regulatory filings align with international tolerance thresholds for condensed tannin levels.
Italy
Wine industry byproduct availability in Piedmont and Tuscany creates regional supply advantages for aqueous ethanol extraction facilities. Lombardy-based pet food extrusion plants negotiate long-term contracts securing grape pomace supply chains. EMA-aligned veterinary supplement channels in Milan capture premium positioning through prescription-grade antioxidant formulations.
Grape Seed Extract in Pet Food Application Market Competitive Landscape
Specialized extraction houses and diversified nutrition ingredient suppliers split the market into distinct capability tiers. Consolidation pressure concentrates around polyphenol standardization investments and EFSA-compliant dossier development. Three archetypes dominate: verticalized botanical extractors with wine industry supply relationships, broad-spectrum antioxidant manufacturers serving human and animal nutrition, and clean-label specialists competing on organic certification credentials. Capacity expansion in supercritical CO2 systems and strategic partnerships with veterinary clinic networks represent the dominant competitive moves.
Within the verticalized extraction tier, Botaniex Inc. and Royal Grapeseed exemplify concentrated proanthocyanidin standardization capabilities, while Kemin Industries occupies a position representing backward integration into antioxidant manufacturing. Nexira anchors the clean-label specialization vector with European market extraction credentials. These three entities collectively represent the strategic positioning spectrum spanning supply chain control, technical standardization, and regulatory compliance differentiation.
| Leading Market Players |
|---|
| Botaniex Inc. |
| Naturex |
| Kemin Industries |
| Hangzhou Green Sky Biotechnology Co., Ltd. |
| Maypro |
| Polyphenolics |
| Nexira |
| Royal Grapeseed |
| Indena S.p.A. |
| Others |
Supply & Pricing Matrix
Piedmont and Tuscany wine regions anchor European grape pomace availability, concentrating extraction capacity among Italian and French suppliers who command premium positioning through EFSA-compliant dossier investments. This geographic concentration feeds downstream pricing power dynamics across veterinary-directed and direct-to-consumer channels.
Pricing Analysis
California and Texas metropolitan markets exhibit the widest price spreads between prescription-grade veterinary formulations and economy-tier kibble additives. Pricing stratifies across premium, standard, and economy tiers driven by proanthocyanidin concentration grade and AAFCO certification status. Cost compression in economy segments intensifies as synthetic antioxidant substitutes retain manufacturing cost advantages. Pet food manufacturers demonstrate highest price sensitivity through long-term contract negotiations, while veterinary clinics absorb premium markups for GRAS-affirmed positioning.
Supply Chain Analysis
EU F-Gas Regulation phase-down schedules function as de facto export controls on spray-drying thermal processing technology, restricting equipment flows to European extraction facilities. Supply concentrates in Italy, France, and the United States where wine industry byproduct relationships anchor aqueous ethanol extraction. Raw material dependencies center on Vitis vinifera grape pomace harvest cycles, aqueous ethanol solvent supply, and proanthocyanidin standardization reagents. Single-source vulnerability runs through concentrated pomace supply agreements tied to vintage fluctuations. Distribution runs through specialty retail and veterinary clinic networks with trained staff delivering antioxidant education.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment through GRAS self-affirmation and EFSA-compliant dossiers creates substantial switching costs for downstream buyers.
For Market Incumbents: Entrench market position through backward integration into wine industry pomace supply chains and accelerated supercritical CO2 extraction capacity deployment. Synthetic antioxidant substitution in economy kibble segments threatens margin compression; counter through veterinary telehealth integration and subscription channel control in California and Texas metropolitan markets. For New Entrants and Emerging Players: Feline therapeutic nutrition in wet food matrices represents the most penetrable entry point given underdeveloped antioxidant positioning and aqueous solubility advantages of liquid extracts. Direct-to-consumer subscription models paired with preventive health bundles offer the clearest go-to-market angle bypassing incumbent veterinary network dominance. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors extraction specialists with certified sustainable credentials and EFSA-aligned dossier capabilities. Long-term viability rests on regulatory compliance infrastructure rather than commodity scale. Watch for inflection signals in EU Green Deal procurement protocol adoption rates among premium pet food manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Collapses cost differential with solvent-based methods while enabling organic certification for North American veterinary networks. |
| EFSA-Compliant Dossier Investment | Preempts EU Green Deal market access barriers and secures premium positioning in German and French wet food supply chains. |
| Veterinary Telehealth Integration | Unbundles physical examinations from nutritional counseling, creating dedicated antioxidant education channels in subscription models. |
| Pre-Concentrated Liquid Extract Sourcing | Bypasses EU F-Gas Regulation spray-drying compliance costs for wet food specialists in Bavaria and Baden-Württemberg. |
| Proanthocyanidin Encapsulation R&D | Addresses thermal degradation during extrusion, unlocking higher concentration claims in kibble matrices. |
Research Methodology
A standing panel of extraction facility technical directors, pet food formulation scientists, veterinary clinic procurement managers, and AAFCO regulatory affairs specialists provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, EFSA feed additive safety dossiers, EU F-Gas Regulation compliance filings, and customs trade data on grape pomace flows. Bottom-up volume modeling and top-down value triangulation anchored forecast outputs.
Scenario-bracketing around regulatory timeline uncertainty and harvest cycle volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product form, end-user archetype, formulation matrix type, and distribution channel structure. CAGRs derived from weighted average growth assumptions across these segments, with specific inputs from veterinary endorsement protocol adoption rates and supercritical CO2 extraction capacity expansion schedules.
Practitioners should monitor condensed tannin tolerance threshold revisions and EU Green Deal ingredient traceability mandate enforcement intensity for early signals. Forecasts reflect assumptions on regulatory stability and wine industry byproduct supply continuity. Material shifts in FDA notification timelines for novel extraction methodologies or vintage-driven pomace availability disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Specialty Meat Ingredients Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Aromatherapy Carrier Oil Market