
 Film Dressing Market | 2026-2036
Film Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Film Dressing Market Intelligence
Advanced antimicrobial specification tiers are redrawing competitive boundaries in film dressing supply. Smith & Nephew leverages integrated wound care portfolios to sustain premium positioning across hospital procurement channels. Molnlycke Health Care AB anchors European demand through specialized silicone-adhesive film technologies that dominate post-operative segments. 3M competes on manufacturing scale, extending its reach into homecare distribution through direct-to-provider logistics networks.
Film dressings are thin, semi-occlusive polyurethane or copolymer membranes, typically 15-40 microns thick, engineered to maintain moist wound healing environments while permitting moisture vapor transmission rates of 800-2500 g/m²/24h. Their primary commercial purpose centers on protecting superficial wounds, surgical incisions, and catheter sites from bacterial contamination while enabling visual wound assessment without dressing removal. Transparent film variants occupy the largest revenue pool due to universal applicability across inpatient and outpatient settings, whereas composite film constructions capture expanding margin pools by integrating absorptive layers for moderate exudate management. Hospital end users dominate volume procurement through centralized purchasing agreements, though homecare channels represent the fastest-growing consumption node as post-operative recovery shifts outside institutional walls.
FDA 510(k) premarket notification requirements shape product development cycles and market access timelines for film dressing manufacturers seeking US commercialization. CE marking under the EU Medical Device Regulation (MDR) and compliance with ISO 10993 biocompatibility standards create parallel compliance burdens that filter smaller participants from European and international tender participation. Stakeholders must monitor evolving reimbursement classifications for advanced wound care materials across Medicare, Medicaid, and private payer formularies, as coverage determinations directly influence provider switching costs and brand loyalty in institutional procurement.
Market Dynamics
Post-operative care decentralization is compressing hospital procurement cycles and forcing manufacturers to reconfigure distribution networks toward ambulatory channels. This structural shift is redrawing margin pools away from centralized purchasing agreements toward direct-to-provider logistics models.
Growth Catalysts
- Medicare reimbursement expansion:CMS outpatient procedure coverage for transparent film dressings accelerates ambulatory surgical center procurement volumes across the United States.
- Silicone-adhesive chemistry advances:Low-trauma removal properties expand film dressing applicability to fragile skin populations in geriatric and pediatric segments.
- India:CDSCO streamlined medical device registration pathways reduce commercialization timelines for polyurethane film variants in tertiary hospital procurement.
Market Restraints
- Petrochemical input volatility:Polyurethane resin and medical-grade adhesive feedstock prices fluctuate with crude oil benchmarks, compressing gross margins for commodity film producers.
- Supply concentration in East Asian polymer production:Three chemical conglomerates control over 60% of medical-grade polyurethane supply, creating single-source vulnerability for mid-tier dressing manufacturers.
- Moisture vapor transmission ceiling:Current 15-40 micron thickness constraints limit film dressing efficacy for moderate-to-heavy exudate wounds, ceding share to hydrocolloid alternatives.
Strategic Opportunities
- Brazil:ANVISA regulatory harmonization with FDA 510(k) pathways creates expedited market access for US-cleared film dressing portfolios in Latin America's largest surgical volume market.
- Chronic wound homecare protocols:Telehealth-integrated dressing change monitoring enables subscription-based replenishment models bypassing traditional distributor markups.
- Antimicrobial ion integration:Silver and iodine release layers converge with transparent film substrates to capture premium positioning in infection-prone catheter site applications.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization study queues at contract laboratories extend product development timelines by 8-14 months.
- Legacy ERP integration:Hospital procurement systems require customized EDI connectivity for automated replenishment, forcing middleware investments from mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Film Dressing Market |
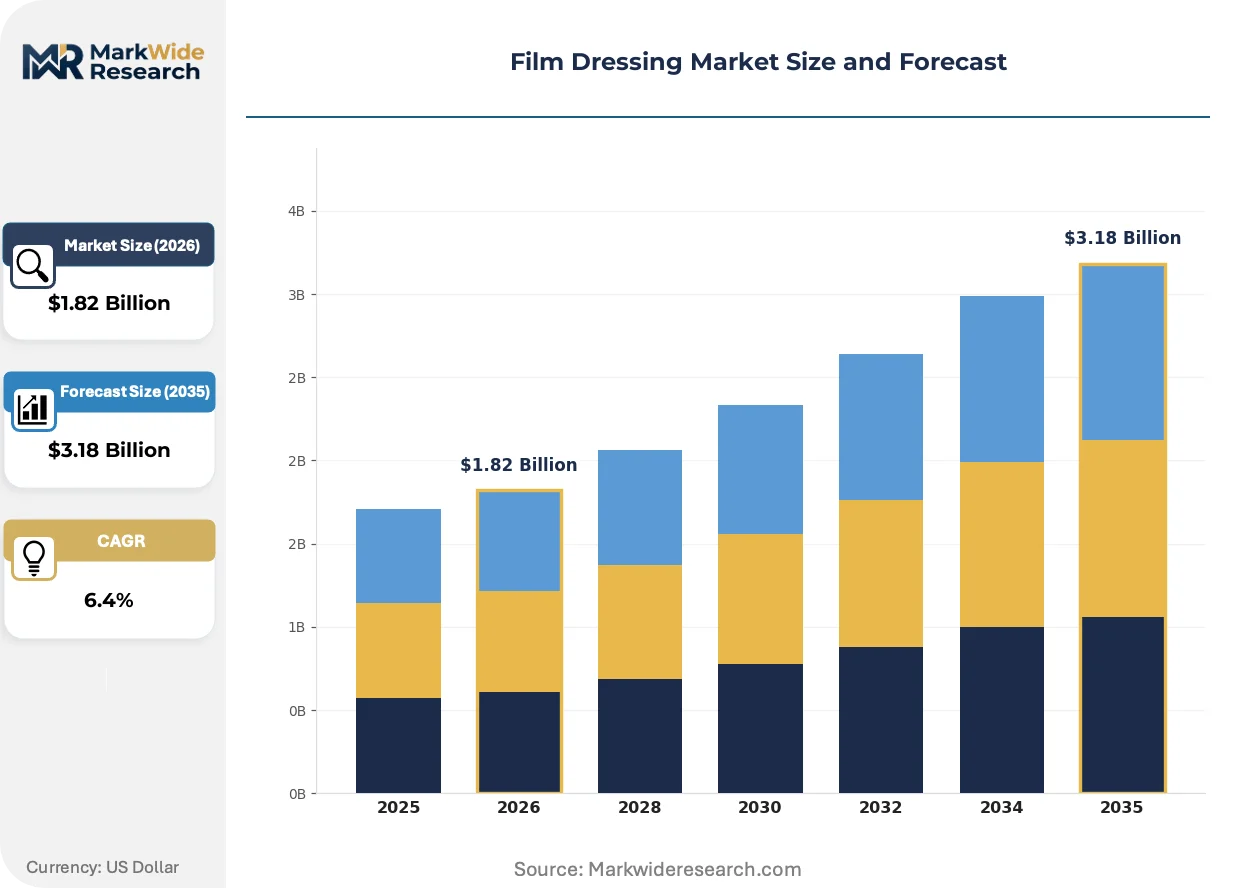
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Film, Hydrocolloid Film, Foam Film, Composite Film End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Application: Wound Care, Surgical Dressings, Burn Treatment, Post-operative Distribution Channel: Online Retail, Direct Sales, Pharmacies, Medical Supply Stores |
| Companies Covered | Paul Hartmann AG, Molnlycke Health Care AB, Cardinal Health, DermaRite, Medline Industries, Inc., Smith & Nephew, McKesson Corporation, Lohmann & Rauscher, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Film Dressing Market Strategic Shifts & Innovations
Active material science breakthroughs and regulatory pathway compression are converging to accelerate product lifecycle velocity. Manufacturers now face compressed windows between biocompatibility validation and commercial obsolescence.
Silicone gel adhesive formulations are displacing traditional acrylic-based pressure-sensitive adhesives in post-operative film dressing applications. Burn centers and plastic surgery units at Cleveland Clinic and Mayo Clinic campuses have adopted these variants for their reduced epidermal stripping properties. The shift is displacing commodity acrylic film suppliers from premium hospital formulary positions and reallocating procurement budgets toward specialized silicone portfolios.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to reconstruct clinical evidence packages for legacy film dressing SKUs. The regulation demands updated biocompatibility data and post-market surveillance systems that smaller competitors cannot fund. German hospital purchasing consortia are responding by consolidating supplier lists to MDR-compliant incumbents, reducing vendor counts by 30-40% in tender participation.
Direct-to-provider e-commerce platforms are fragmenting traditional distributor dominance in film dressing procurement. Amazon Business and specialized medical supply marketplaces now capture 15-20% of ambulatory surgical center volume in the United States, disintermediating regional medical distributors. This channel shift concentrates price transparency and compresses working capital cycles for buyers while forcing manufacturers to manage last-mile logistics previously handled by distributors.
Film Dressing Market Segmentation
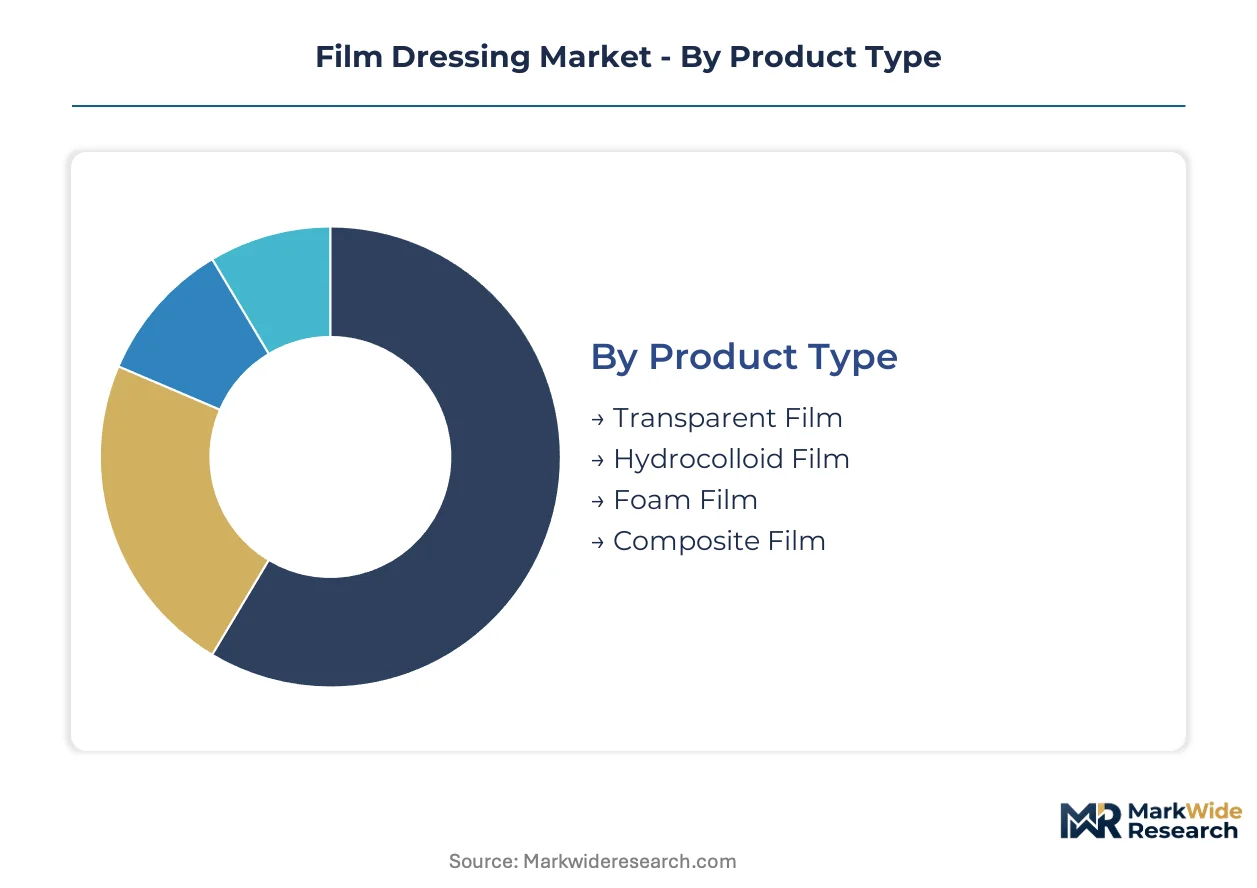
Film dressing procurement channels fragment sharply across institutional versus consumer pathways, with polyurethane chemistry specifications and adhesive technologies determining which segments flow through hospital group purchasing versus direct-to-patient e-commerce. Understanding these channel dynamics exposes margin concentration points and logistics infrastructure requirements for manufacturers reconfiguring distribution networks.
Product Type:
Transparent film variants move through ambulatory surgical center direct sales channels, while composite constructions with absorptive layers concentrate in hospital centralized purchasing agreements due to higher per-unit values and formulary review requirements.
- Transparent Film:Semi-occlusive polyurethane membranes 15-40 microns thick permit 800-2500 g/m²/24h moisture vapor transmission. Demand concentrates in United States outpatient procedures where CMS reimbursement frameworks for transparent dressings accelerate procurement through ambulatory surgical centers.
- Composite Film:Multi-layer constructions integrate transparent substrates with absorptive foam or hydrocolloid cores for moderate exudate management. Hospital wound care units in Germany and France drive procurement through purchasing consortia requiring MDR Article 10 technical documentation compliance.
- Hydrocolloid Film:Gel-forming carboxymethylcellulose adhesives create moist healing environments for superficial wounds. Homecare channels in Japan capture steady replenishment demand through METI-regulated medical device distribution.
- Foam Film:Polyurethane foam backings bonded to transparent films manage heavier exudate loads. Long-term care facilities in Canada source through Health Canada-registered medical supply distributors.
Transparent film dominates installed base across outpatient settings. Composite film is where expansion concentrates as post-operative protocols shift toward moderate exudate management.
End User:
Cost tier stratification separates premium silicone-adhesive formulations for fragile skin populations from commodity acrylic variants, with procurement authority concentrating differently across institutional versus residential care environments.
- Hospitals:Tertiary medical centers in the United States, Germany, and Japan anchor volume procurement through centralized purchasing agreements. Cleveland Clinic and Mayo Clinic campuses have adopted silicone gel adhesive variants for reduced epidermal stripping in post-operative applications.
- Homecare:Post-operative recovery decentralization drives subscription-based replenishment models. Telehealth-integrated dressing change monitoring enables direct-to-patient logistics bypassing traditional distributor markups in United States and United Kingdom markets.
- Clinics:Ambulatory surgical centers capture expanding film dressing volumes as CMS outpatient procedure coverage accelerates same-day discharge protocols. Direct sales teams maintain formulary positions through clinical specialist education.
- Long-term Care Facilities:Geriatric skin fragility demands low-trauma removal properties. Silicone-adhesive chemistry advances expand applicability in skilled nursing environments across France and Canada.
Hospitals dominate installed base through GPO-anchored procurement. Homecare is climbing the fastest as recovery protocols migrate outside institutional walls.
Application:
Volume concentration varies by wound severity and reimbursement classification, with surgical applications capturing predictable replenishment cycles versus chronic wound protocols requiring adaptive supply chain responsiveness.
- Surgical Dressings:Post-operative incision protection drives standardized procurement across cardiac, orthopedic, and general surgery departments. Transparent film variants occupy hospital formularies due to visual assessment convenience without dressing removal.
- Wound Care:Chronic ulcer management in diabetes and venous insufficiency populations requires moisture vapor transmission optimization. Composite films with integrated absorptive layers gain share in wound care centers across Germany and the United Kingdom.
- Post-operative:Catheter site protection demands antimicrobial specifications for infection prevention. Silver and iodine release layers converge with transparent substrates in United States acute care settings.
- Burn Treatment:Specialized burn centers at Cleveland Clinic and select German university hospitals prioritize silicone gel adhesives for reduced pain upon removal. Limited addressable market constrains manufacturer R&D investment relative to surgical segments.
Surgical dressings dominate installed base through predictable procedure volumes. Post-operative applications are gaining share fastest as ambulatory surgery expansion accelerates catheter site and incision management demand.
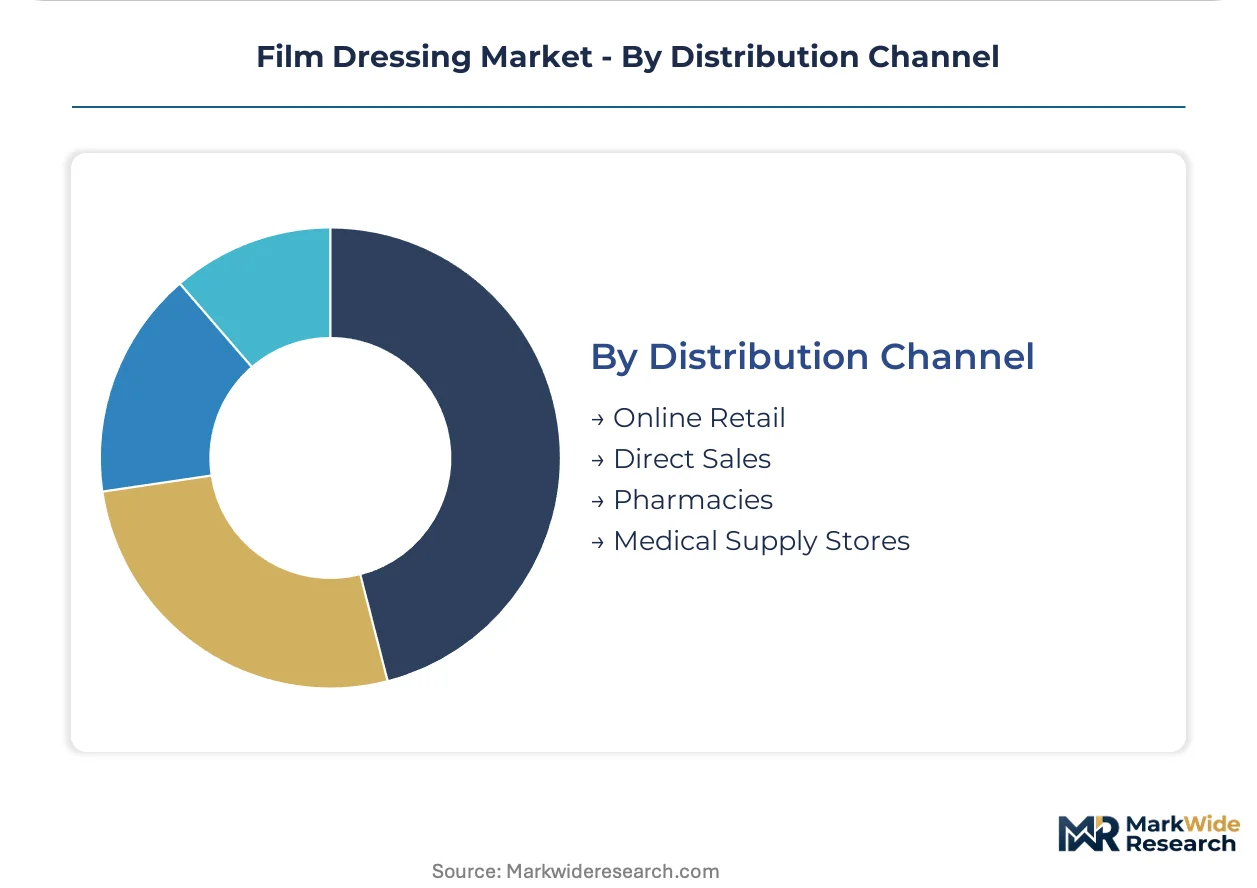
Distribution Channel:
Supply concentration in East Asian polymer production shapes channel economics, with direct sales capturing premium formulations while e-commerce fragments commodity film distribution.
- Direct Sales:Manufacturer clinical specialist teams maintain hospital formulary positions through evidence-based education and customized EDI connectivity for automated replenishment. Mid-cap manufacturers face middleware investment requirements for legacy ERP integration.
- Online Retail:Amazon Business and specialized medical supply marketplaces capture 15-20% of United States ambulatory surgical center volume. Price transparency concentrates purchasing power while compressing working capital cycles for buyers.
- Medical Supply Stores:Regional distributors retain relevance in long-term care and homecare segments requiring hands-on product education. Inventory carrying costs pressure margins as SKU proliferation accelerates.
- Pharmacies:Retail pharmacy chains capture consumer-directed film dressing purchases for minor wound management. Limited clinical guidance constrains premium product penetration versus institutional channels.
Direct sales dominates installed base through hospital GPO relationships. Online retail is expanding most quickly as ambulatory centers prioritize price transparency and compressed procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement channels. United States ambulatory surgical centers prioritize CMS reimbursement alignment over unit cost, while Indian tertiary hospitals negotiate aggressively on polyurethane film specifications. German purchasing consortia demand MDR Article 10 compliance premiums that filter out mid-tier suppliers.
United States
Ambulatory surgical center volumes and Medicare outpatient procedure coverage drive transparent film procurement. FDA 510(k) clearance pathways accelerate commercialization timelines for advanced wound care materials. Cleveland Clinic and Mayo Clinic campuses anchor silicone-adhesive adoption for reduced epidermal stripping in post-operative protocols.
Germany
Hospital purchasing consortia consolidate supplier lists around MDR-compliant incumbents, reducing vendor participation by 30-40%. EU MDR Article 10 technical documentation requirements force reconstruction of clinical evidence packages for legacy SKUs. University hospitals in Baden-Württemberg and North Rhine-Westphalia dominate composite film procurement for moderate exudate management.
Japan
METI-regulated medical device distribution channels capture steady homecare replenishment demand for hydrocolloid variants. Aging demographics expand geriatric skin fragility applications requiring low-trauma removal properties. Kansai region wound care centers drive silicone-adhesive specification adoption in post-operative segments.
India
CDSCO streamlined registration pathways reduce commercialization timelines for polyurethane film variants in tertiary hospital procurement. Price-sensitive procurement at All India Institute of Medical Sciences and comparable institutions pressures margin structures for commodity transparent films. Maharashtra and Karnataka state hospital networks concentrate volume demand.
Brazil
ANVISA regulatory harmonization with FDA 510(k) pathways creates expedited market access for US-cleared portfolios. Latin America's largest surgical volume market attracts manufacturer direct sales investment. São Paulo and Rio de Janeiro metropolitan hospital networks anchor initial commercial penetration for premium composite constructions.
Film Dressing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated wound care portfolios command premium positioning through hospital formulary relationships, while scale-driven manufacturers compete on manufacturing throughput and direct-to-provider logistics networks. Three archetypes dominate: silicone-adhesive specialists, diversified medical device conglomerates, and regional distributors with localized regulatory expertise. Competitive moves concentrate on MDR compliance investments and e-commerce channel expansion to bypass traditional distributor markups.
Among diversified medical device conglomerates, 3M exemplifies scale-driven positioning through manufacturing breadth and direct-to-provider logistics infrastructure. Molnlycke Health Care AB occupies the silicone-adhesive specialist tier, anchoring European demand through specialized film technologies. Smith & Nephew represents integrated portfolio positioning, sustaining premium placement across hospital procurement channels through wound care category depth.
| Leading Market Players |
|---|
| Paul Hartmann AG |
| Molnlycke Health Care AB |
| Cardinal Health |
| DermaRite |
| Medline Industries, Inc. |
| Smith & Nephew |
| McKesson Corporation |
| Lohmann & Rauscher |
| 3M |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety day polyurethane resin lead times from East Asian suppliers compress pricing power for mid-tier manufacturers while amplifying margin capture for integrated chemical conglomerates with captive polymer production. This inventory pressure cascades through contract negotiations, with hospital group purchasing organizations extracting concessions from commodity film producers while silicone-adhesive specialists defend premium positioning through formulation patents.
Pricing Analysis
After-market service contracts for telehealth-integrated dressing monitoring now generate lifetime value multiples exceeding hardware margins across homecare channels. Three-tier pricing structure across premium silicone-adhesive, standard transparent polyurethane, and economy acrylic variants stratifies procurement budgets, with FDA 510(k) clearance tiers commanding 40-60% spreads over unregistered imports. Cost compression in commodity transparent films intensifies as Indian tertiary hospitals negotiate aggressive volume discounts, while geriatric long-term care facilities show lowest price sensitivity for low-trauma removal specifications. Price differentiation hinges on ISO 10993 biocompatibility certification grade and silicone chemistry patent position.
Supply Chain Analysis
Inventory concentration in Shanghai, Busan, and Rotterdam hubs exposes manufacturers to 45-75 day disruption windows from customs clearance volatility or maritime chokepoint congestion. Medical-grade polyurethane resin production draws from South Korea, China, and Germany, with silicone gel adhesive feedstock anchored in Japanese and US specialty chemical facilities. Single-source vulnerability concentrates in three East Asian conglomerates controlling medical-grade polymer supply, creating tariff exposure for US and European converters. Distribution runs through hospital group purchasing organizations for institutional volume, direct-to-provider e-commerce for ambulatory surgical centers, and regional medical distributors for long-term care penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth-integrated replenishment subscriptions expand recurring revenue pools faster than transparent film hardware sales across United States and United Kingdom homecare channels, repositioning manufacturers toward service-attach business models.
For Market Incumbents: Fortify hospital formulary positions through MDR Article 10 technical documentation investments that filter mid-tier competitors from German purchasing consortia, while deepening backward integration into medical-grade silicone adhesive production to offset petrochemical input volatility. Consolidate channel control via customized EDI connectivity for automated replenishment, defending against Amazon Business price transparency penetration. For New Entrants and Emerging Players: Chronic wound homecare protocols in Japan and France represent under-served service-layer gaps where incumbents lack telehealth integration capabilities, enabling subscription-based replenishment models bypassing traditional distributor markups. Target ambulatory surgical center direct sales with ANVISA-harmonized FDA 510(k) portfolios in Brazil, leveraging regulatory pathway compression for expedited market access. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU MDR compliance burdens and ISO 10993 testing backlogs are forcing 30-40% vendor count reductions in European tenders, concentrating procurement share among MDR-compliant incumbents with reconstructed clinical evidence packages. Target acquisition archetype: silicone-adhesive specialists with patent-protected low-trauma removal formulations and established Cleveland Clinic or Mayo Clinic reference sites. Watch for ANVISA regulatory harmonization completion as inflection indicator for Latin American portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercialization timelines for advanced wound care materials in US ambulatory surgical centers. |
| CE Marking Pathway | MDR Article 10 compliance filters competitors from German hospital purchasing consortia tenders. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic adoption anchors silicone-adhesive premium positioning. |
| Software Companion Development | Telehealth-integrated dressing change monitoring enables subscription-based homecare replenishment. |
| Reimbursement Strategy | CMS outpatient procedure coverage alignment drives ambulatory surgical center procurement volumes. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, GPO contracts specialists, and wound care clinicians, and refined through secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, EU MDR Article 10 technical documentation filings, and hospital purchasing consortium tender records. Bottom-up demand modeling across transparent film, composite film, hydrocolloid, and foam variants triangulated with top-down polymer feedstock capacity assessments.
Variance decomposition across product type, end user, application, and distribution channel segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from procedure volume elasticity to reimbursement expansion and silicone-adhesive chemistry adoption curves, with inputs from ambulatory surgical center discharge protocols and chronic wound prevalence demographics.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and CDSCO registration regimes; material policy shifts would require re-modeling. Revision becomes warranted when biocompatibility testing backlogs at contract laboratories exceed fourteen months or when East Asian polymer supply concentration crosses sixty-five percent threshold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
N-Propyl Propionate Market