
 Special Effect Pigments Market | 2026-2036
Special Effect Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Special Effect Pigments Market Outlook
The capital-intensity divergence between integrated titanium dioxide substrate producers and specialty coating formulators is redrawing competitive boundaries in special effect pigments. Merck KGaA leverages its precision thin-film deposition expertise to dominate optical variable pigment architectures. ALTANA (ECKART) anchors European supply through captive metal flake milling and surface treatment capabilities. Shepherd Color specializes in high-temperature stable complex inorganic color pigments for industrial coatings.
Special effect pigments comprise platelet or particulate materials engineered to produce angle-dependent color travel, metallic luster, or dynamic chromatic response through interference, reflection, or thermochromic mechanisms, typically manufactured via vapor deposition, wet chemical coating, or controlled oxidation of metal substrates. Their primary commercial purpose is to impart premium aesthetic differentiation and functional signaling in consumer-facing and industrial products. Pearlescent pigments lead volume consumption in cosmetics and automotive refinish due to established mica substrate supply chains and proven formulation compatibility. Metallic pigments concentrate margin pools in luxury automotive OEM coatings where aluminum and copper-zinc alloy flakes command specification premiums. Thermochromic applications in packaging and textiles represent the fastest-growing functional segment as brand owners seek interactive consumer engagement features.
EPA oversight of metal particulate emissions shapes US manufacturing facility siting and pollution control investments, while REACH registration requirements and ECHA substance evaluation govern European market access for novel pigment chemistries. China's MEE enforces GB standards on heavy metal content in coatings and plastics, directly restricting cadmium and lead-based legacy pigment formulations. Formulators must monitor evolving regulatory thresholds for microplastic restrictions and perfluorinated compound bans that threaten conventional surface treatment chemistries.
Market Dynamics
Automotive OEMs are consolidating coating specifications around interference pigments that deliver precise angle-dependent color travel, compressing formulation diversity while elevating performance thresholds for substrate purity and deposition control.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH substance evaluations are accelerating substitution of solvent-borne carriers with waterborne and bio-based alternatives, opening specification windows for compliant special effect pigment portfolios.
- Cosmetics formulators in Germany:Premium skincare and color cosmetic brands are expanding pearlescent pigment loading rates to achieve multi-dimensional luminosity in high-definition digital photography environments.
- Thermochromic inkjet deposition:Packaging converters are integrating temperature-responsive pigments into direct-to-shape digital printing lines for interactive consumer engagement features.
Market Restraints
- Titanium dioxide substrate volatility:Feedstock concentration among integrated chloride-process producers in China creates input cost instability for mica-based pearlescent pigment manufacturers.
- Legacy cadmium and lead pigment phase-outs:China's MEE enforcement of GB standards on heavy metal content is forcing rapid reformulation of industrial coatings without drop-in chromatic replacements.
- Precision vapor deposition equipment scarcity:Thin-film optical variable pigment production requires vacuum coating systems with sub-nanometer thickness control, limiting capacity expansion outside established technical centers.
Strategic Opportunities
- Underpenetrated Indian automotive refinish:Premium vehicle parc expansion in Maharashtra and Tamil Nadu is creating first-mover positioning for metallic flake suppliers with localized technical service capabilities.
- CSRD-aligned sustainable sourcing mandates:European corporate sustainability reporting requirements are rewarding pigment producers with certified mica traceability and conflict-mineral-free supply chains.
- Convergence of photoluminescent and interference technologies:Dual-function pigments combining daytime color travel with nighttime glow are opening specification channels in safety signage and architectural coatings.
Industry Challenges
- Vacuum deposition technician scarcity:Specialized thin-film coating operators with plasma physics and optical monitoring expertise command premium compensation, constraining production scale-up timelines.
- Multi-jurisdictional substance registration:Novel pigment chemistries require sequential REACH, EPA TSCA, and NMPA filings with divergent data requirements, extending commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Effect Pigments Market |
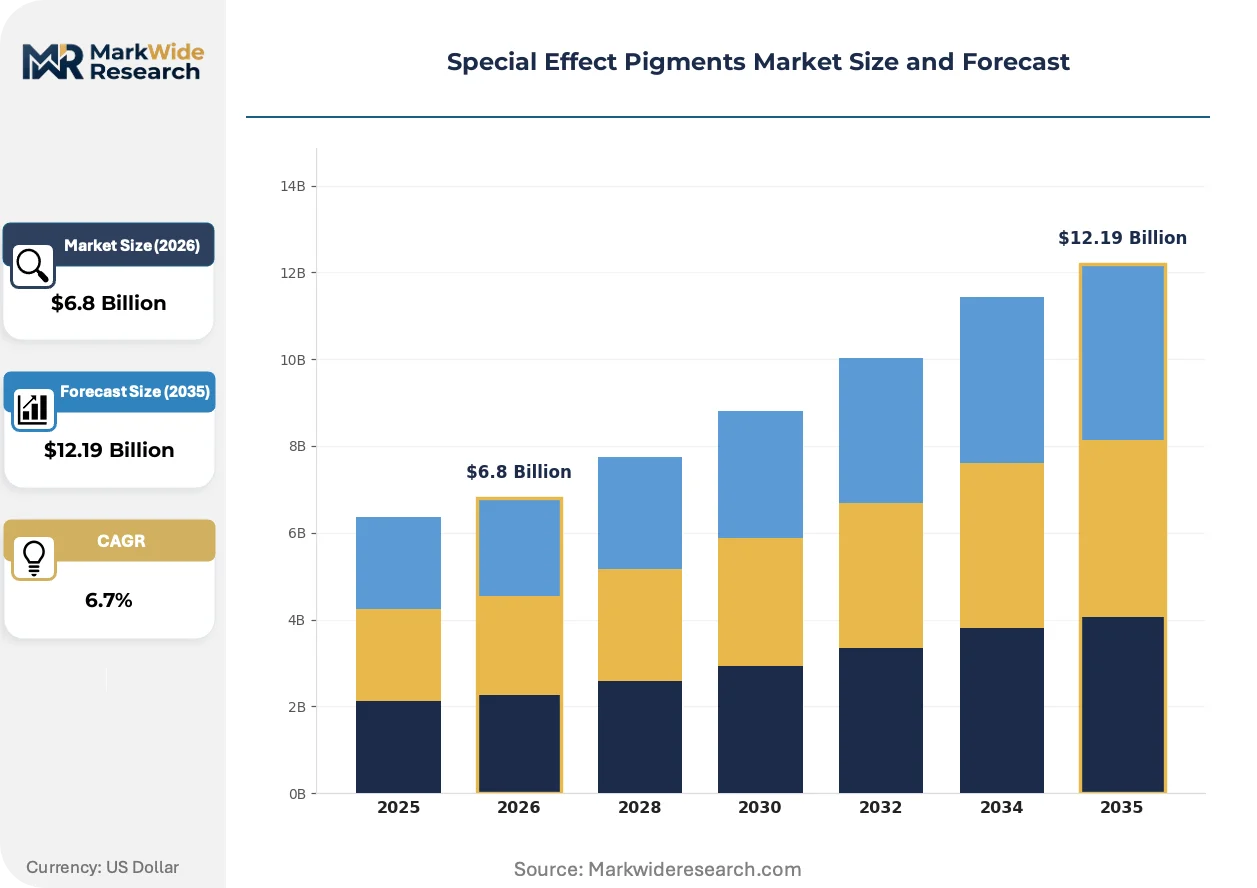
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pearlescent, Metallic, Fluorescent, Thermochromic End Use Industry: Automotive Coatings, Cosmetics, Plastics, Inks Application: Interior Design, Packaging, Decorative Paints, Textiles Distribution Channel: Online Retail, Direct Sales, Distributors, Retail Stores |
| Companies Covered | The Chemours Company, Shepherd Color, Merck KGaA, Silberline Manufacturing Co., Inc., SCHLENK SE, ALTANA (ECKART), Sudarshan Chemical Industries Limited, VIAVI Solutions Inc., DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Effect Pigments Market Strategic Shifts
Digital color specification tools and AI-driven formulation matching are compressing the traditional sample-and-approve cycle, while regulatory pressure on microplastic-containing surface treatments is forcing reinvention of carrier and encapsulation chemistries.
Multi-layer thin-film optical stacks are fragmenting the premium automotive pigment landscape. These architectures deliver precise interference color with fewer pigment loadings than conventional metal oxide-coated mica. German and Japanese OEM color stylists are specifying these materials for signature brand hues. The technology is fragmenting supplier hierarchies by rewarding deposition precision over raw material scale.
REACH microplastic restriction proposals are forcing reformulation of conventional surface treatment chemistries. ECHA's anticipated restriction on synthetic polymer microparticles threatens standard encapsulation systems used in cosmetics and coatings. Producers are responding with bio-based alternatives and inorganic surface modifications, though performance parity remains uneven across humidity and shear stress conditions.
Brand owners are consolidating pigment procurement through direct masterbatch partnerships rather than distributed distributor networks. Large cosmetics and coatings formulators in the United States and Germany are negotiating volume commitments with substrate producers, bypassing traditional specialty chemical distributors. This channel compression is most visible in pearlescent pigment categories where formulation technical service requirements have diminished with standardization.
Special Effect Pigments Market Segmentation
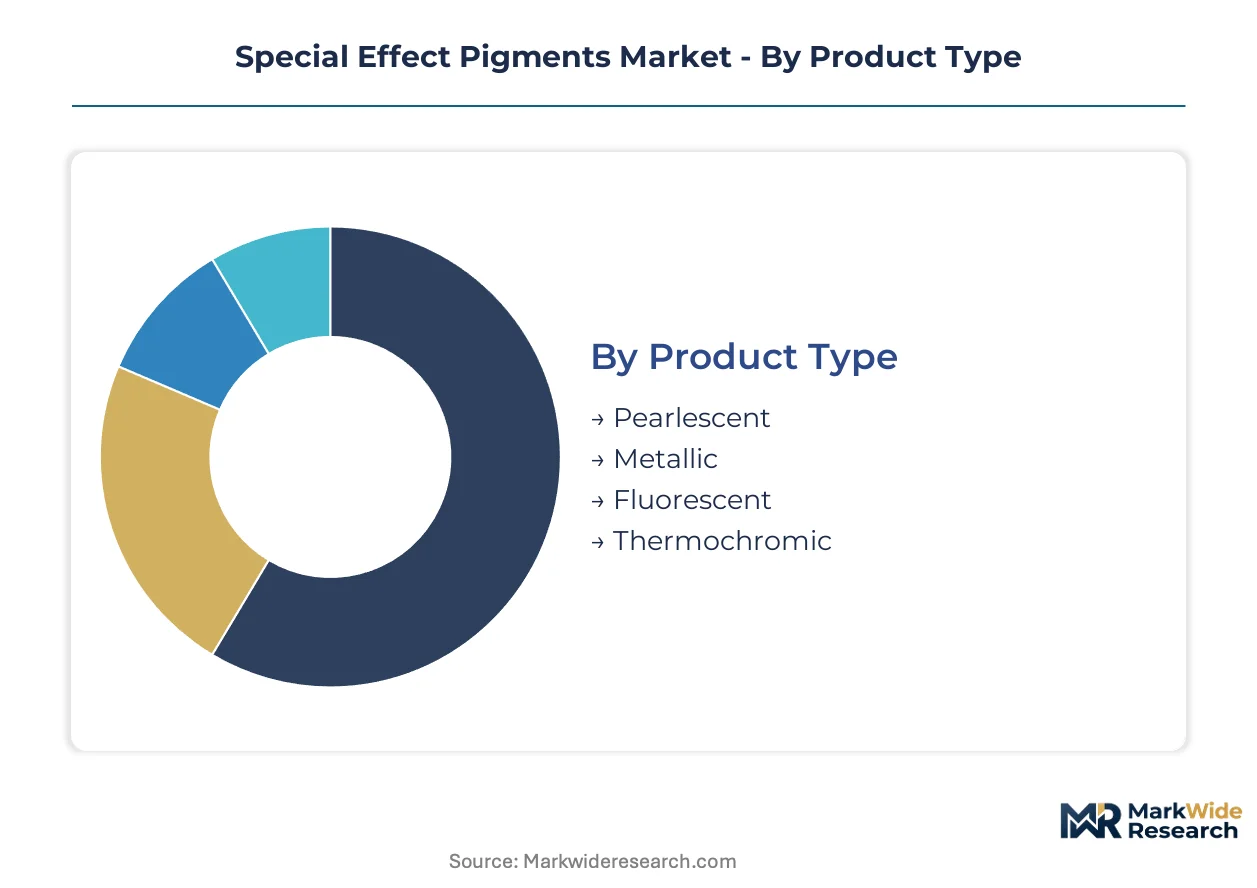
Special effect pigments serve divergent performance requirements across aesthetic and functional applications, making product-level and channel-level segmentation essential for aligning formulation expertise with end-use specifications. The market fragments across substrate technologies, regulatory compliance tiers, and customer procurement sophistication.
Product Type:
Premium margin pools concentrate in thin-film interference architectures where deposition precision creates specification lock-in with automotive OEM color stylists.
- Pearlescent:Titanium dioxide and iron oxide coatings on mica substrates deliver multi-angle luminosity through thin-film interference. German cosmetics formulators in Hamburg and Düsseldorf drive specification intensity for high-definition digital photography compatibility. REACH microplastic restrictions are forcing rapid carrier system reformulation without performance degradation.
- Metallic:Aluminum and copper-zinc alloy flakes provide specular reflection and metallic luster through controlled particle geometry. Luxury automotive OEM coatings in Germany, China, and the United States anchor demand concentration, with aluminum flake purity specifications tightening under EPA metal particulate emission oversight.
- Fluorescent:Organic dye-based systems absorb UV and re-emit visible wavelengths for high-visibility safety applications.
- Thermochromic:Temperature-responsive leuco dye microencapsulation enables dynamic color shift for interactive packaging and consumer engagement features.
The dominant share belongs to pearlescent pigments, while thermochromic systems are closing the gap fastest.
End Use Industry:
Volume concentration tracks manufacturing cluster density, with automotive and cosmetics commanding the tightest specification tolerances.
- Automotive Coatings:OEM and refinish applications specify interference pigments for precise angle-dependent color travel. Chinese, German, and US automotive manufacturing clusters concentrate demand, with waterborne carrier transitions accelerating under EU Green Deal chemical restrictions.
- Cosmetics:Skincare and color cosmetic brands in Germany expand pearlescent loading rates for multi-dimensional luminosity. ECHA substance evaluations govern novel pigment chemistry market access, compressing formulation approval cycles.
- Plastics:Masterbatch integration requires thermal stability and shear resistance for injection molding and extrusion processes.
- Inks:Flexographic, gravure, and inkjet deposition systems demand particle size distribution control for printhead compatibility.
Automotive coatings command the specification premium tier, though cosmetics applications are expanding most quickly.
Application:
Functional performance requirements separate architectural durability specifications from disposable packaging economics.
- Interior Design:Architectural coatings and decorative surfaces demand lightfastness and abrasion resistance for extended service life.
- Packaging:Temperature-responsive and photochromic features enable brand differentiation in food, beverage, and personal care segments. China's MEE enforcement of GB standards on heavy metal content restricts legacy pigment formulations in export-oriented production.
- Decorative Paints:DIY and professional coating segments balance cost position with aesthetic impact in residential and commercial construction.
- Textiles:Fiber and fabric applications require washfastness and flexibility without stiffness or crocking.
Packaging applications show the steepest expansion trajectory as digital printing enables mass customization, while interior design maintains the value concentration.
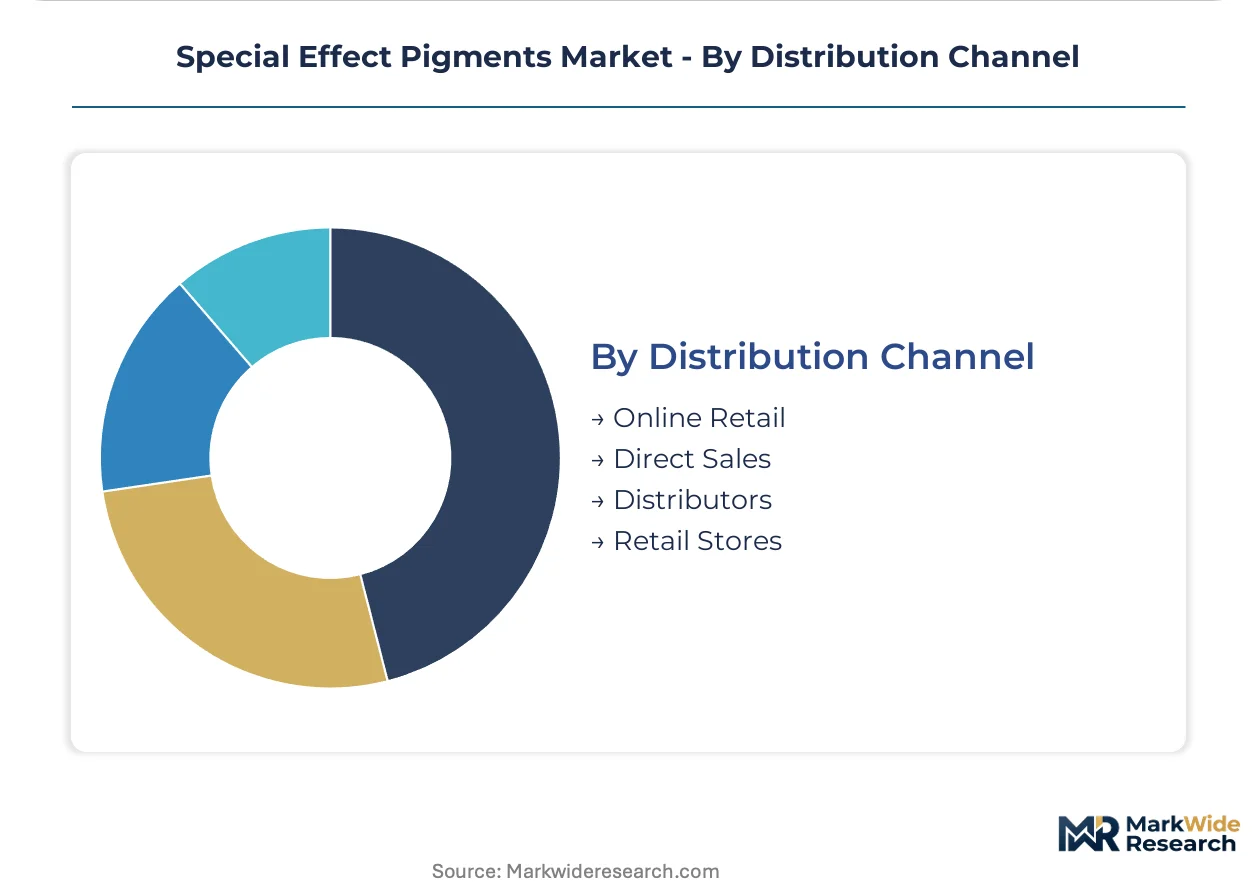
Distribution Channel:
Procurement consolidation is compressing traditional distributor networks as large formulators seek direct substrate producer relationships.
- Online Retail:E-commerce platforms serve small-scale cosmetics and craft coating formulators with standardized pigment grades and rapid sample fulfillment.
- Direct Sales:Volume commitments with substrate producers bypass specialty chemical distributors, concentrating in pearlescent categories where technical service standardization has diminished. German and US coatings formulators lead this channel compression.
- Distributors:Regional specialty chemical distributors retain relevance in fragmented automotive refinish and industrial coatings segments requiring localized technical support.
- Retail Stores:Consumer-facing channels serve DIY decorative paint and craft applications with pre-formulated color systems.
Direct sales channels capture the premium volume, while online retail is climbing the fastest among small and mid-scale formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany tolerate premium pricing for interference pigments, while Indian refinish buyers prioritize metallic flake cost efficiency. Cosmetics formulators in France absorb specification premiums for pearlescent luminosity. Chinese industrial coatings buyers face forced reformulation costs from heavy metal restrictions.
United States
Luxury automotive OEM coatings in Michigan and California specify aluminum flake purity grades that command specification premiums. EPA metal particulate emission oversight shapes manufacturing facility siting in Ohio and Pennsylvania. Detroit-area automotive clusters concentrate demand for waterborne carrier transitions.
Germany
Premium skincare brands in Hamburg and Düsseldorf expand pearlescent pigment loading rates for high-definition digital photography compatibility. REACH substance evaluations and EU Green Deal chemical restrictions accelerate waterborne carrier adoption. Bavarian automotive manufacturing anchors interference pigment specification intensity.
China
Automotive OEM and refinish applications in Shanghai and Guangdong specify angle-dependent color travel pigments for domestic EV brands. MEE enforcement of GB standards on heavy metal content forces rapid cadmium and lead pigment phase-outs. Yangtze River Delta coatings clusters drive metallic flake volume consumption.
India
Premium vehicle parc expansion in Maharashtra and Tamil Nadu creates first-mover positioning for metallic flake suppliers with localized technical service. BIS certification requirements govern industrial coatings pigment formulations. Mumbai-Pune automotive corridors concentrate refinish demand growth.
Japan
Automotive color stylists in Nagoya and Tokyo specify multi-layer thin-film optical stacks for signature brand hues. METI industrial standards govern coatings environmental performance thresholds. Kanto region manufacturing clusters concentrate precision deposition equipment technical expertise.
Special Effect Pigments Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with titanium dioxide substrate producers commanding input cost leverage over formulators. Merck KGaA, ALTANA (ECKART), and Shepherd Color anchor the upper tier through captive deposition or milling capabilities. Strategic moves concentrate on M&A for substrate supply security and capacity expansion in thin-film optical variable architectures.
Among Germany-based integrated producers, Merck KGaA and ALTANA (ECKART) exemplify the precision deposition archetype, while Shepherd Color represents the high-temperature stability specialist tier. These three occupy positions that reward technical specification lock-in over commodity scale.
| Leading Market Players |
|---|
| The Chemours Company |
| Shepherd Color |
| Merck KGaA |
| Silberline Manufacturing Co., Inc. |
| SCHLENK SE |
| ALTANA (ECKART) |
| Sudarshan Chemical Industries Limited |
| VIAVI Solutions Inc. |
| DIC Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between automotive OEM coating divisions and thin-film interference pigment producers lock in multi-year supply access while providing forward price visibility against titanium dioxide substrate volatility. These contracts typically embed volume commitments from German and Chinese manufacturing clusters with price adjustment clauses tied to chloride-process feedstock indices.
Pricing Analysis
After-sales technical service revenue from color matching and formulation support drives lifetime value for specialty pigment suppliers. Three-tier pricing structure across premium, standard, and economy levels separates optical variable pigments with sub-nanometer deposition control from conventional mica-based pearlescents and commodity metallic flakes. Cost compression in standard-grade pearlescent tiers is intensifying because Chinese chloride-process titanium dioxide producers exercise input leverage over mica coaters. Automotive refinish shops in India and Southeast Asia exhibit the highest price sensitivity, while German luxury OEM color stylists absorb specification premiums for signature interference hues.
Supply Chain Analysis
Strait of Malacca transit routes underpin raw material flows for mica substrate processors serving Asian coatings clusters. Supply concentration rests on China for titanium dioxide feedstock, India for natural mica mining, and Germany for precision vapor deposition equipment manufacturing. Raw material dependencies span chloride-process TiO2, aluminum and copper-zinc alloy ingots, and synthetic fluorophlogopite substrates. Single-source vulnerability concentrates in vacuum coating systems with plasma physics expertise concentrated in Japanese and German technical centers. Distribution runs through direct masterbatch partnerships with large formulators bypassing traditional specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital color specification tools and AI-driven formulation matching threaten incumbent technical service margins by compressing the sample-and-approve cycle that historically justified premium pricing. Incumbents must defend against substitution from algorithmic color matching platforms that reduce dependency on supplier-provided formulation expertise.
For Market Incumbents: Compound deposition precision advantages through captive vacuum coating capacity expansion in Bavaria and Nagoya technical corridors. Secure titanium dioxide substrate supply through backward integration into chloride-process feedstock or long-term offtake with Chinese producers. Defend against digital color platform substitution by embedding proprietary spectral data libraries into customer workflow software.
For New Entrants and Emerging Players: Localized technical service gaps in Indian automotive refinish present white-space positioning opportunities for metallic flake suppliers with Maharashtra-based application laboratories. Target thermochromic packaging converters seeking direct-to-shape digital printing integration with temperature-responsive pigment masterbatches. Penetrate through certified mica traceability offerings that satisfy European CSRD-aligned sustainable sourcing mandates.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among thin-film interference pigment producers with automotive OEM color stylist specification lock-in. Long-term viability across the analysis window favors deposition-technology specialists over commodity substrate processors. Monitor ECHA microplastic restriction implementation timelines as inflection indicators for bio-based carrier system adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide Feedstock | Chinese chloride-process producers currently exercise pricing leverage over mica-based pearlescent manufacturers. |
| Vacuum Deposition Capacity Expansion | German and Japanese technical centers concentrate plasma physics expertise for optical variable pigment architectures. |
| Bio-Based Carrier System Development | REACH microplastic restrictions threaten conventional encapsulation chemistries in cosmetics and coatings segments. |
| Certified Mica Traceability Program | European CSRD requirements reward conflict-mineral-free supply chains with procurement preference. |
| Direct Masterbatch Partnership Expansion | Large formulators in Germany and the United States are consolidating procurement through substrate producer relationships. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with pigment industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews encompassed coatings formulators at German automotive OEMs, Chinese industrial coatings procurement leads, Indian automotive refinish distributors, and Japanese precision deposition equipment engineers. Secondary sources included ECHA substance evaluation dossiers, EPA metal particulate emission filings, China MEE GB standard enforcement records, and customs trade flow data for titanium dioxide and mica substrates. Bottom-up volume modeling triangulated against top-down value estimates from production capacity assessments.
Across the projection horizon, the analytical framework modeled demand across substrate technology tiers, end-use industry specifications, and regional regulatory compliance clusters. Segmentation dimensions encompassed pearlescent, metallic, thermochromic, and optical variable product architectures; automotive, cosmetics, plastics, and packaging end-use applications; and waterborne versus solvent-borne carrier system transitions. CAGRs derived from regression analysis against automotive production forecasts, cosmetics formulation loading rate trends, and packaging digital printing adoption curves.
Underlying assumptions cover REACH microplastic restriction timelines, Chinese heavy metal enforcement intensity, and titanium dioxide feedstock price stability, with deviation risk concentrated in regulatory acceleration or chloride-process supply disruptions. Practitioners should keep alternative scenarios live as EU Green Deal chemical restriction implementation evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Laser Sensitive Pigments Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Global Architectural Paint Oxide Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Resin Pigments Market