
 North America Hair Colorants Market | 2026-2036
North America Hair Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hair Colorants Market Analytics
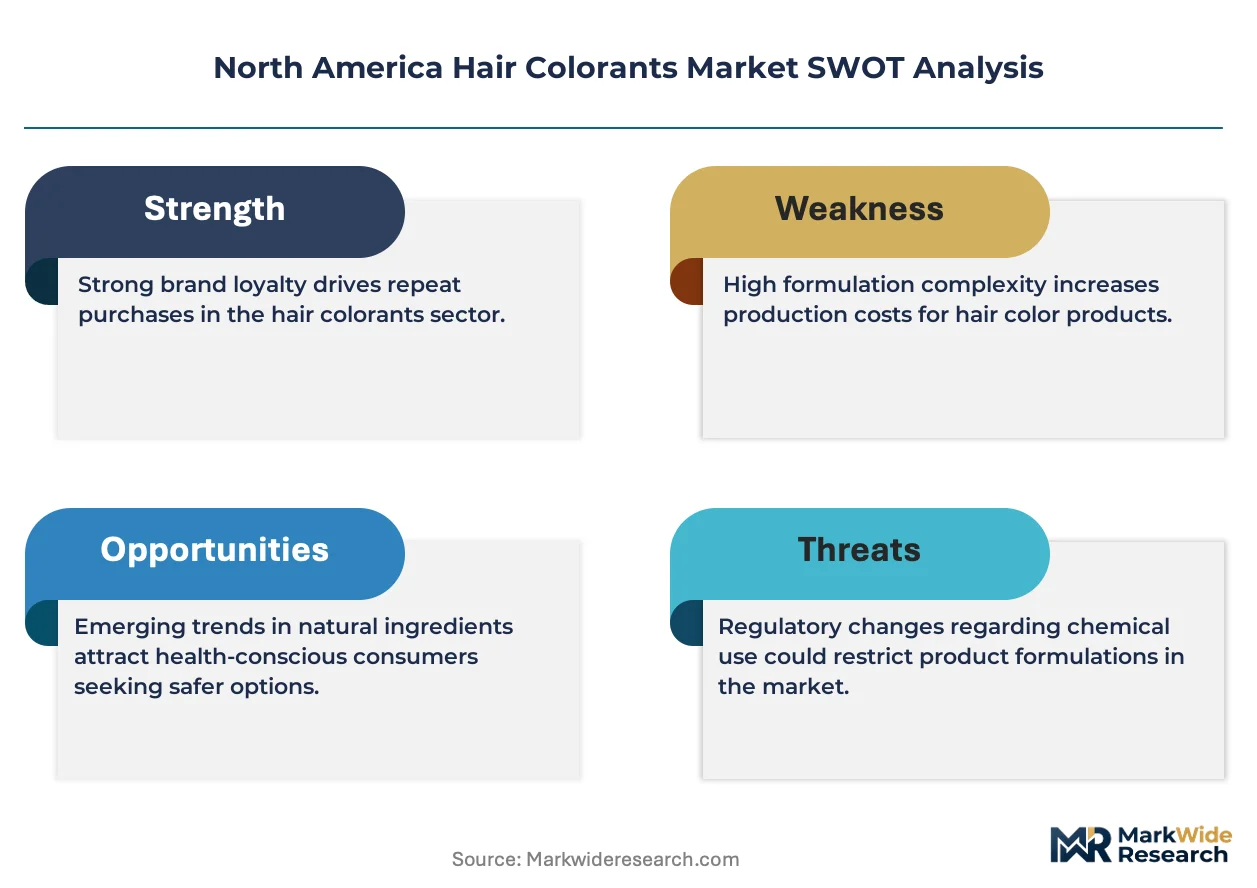
Multi-source ingredient procurement is recalibrating how formulators manage supply security across the North American hair colorants value chain. L'Oréal S.A. leverages captive R&D centers in New Jersey and Illinois to sustain innovation pipelines for professional and retail lines. Henkel AG & Co. KGaA anchors its North American position through Schwarzkopf manufacturing assets and direct salon distribution. COTY INC. competes via mass-market brand density and drugstore shelf control.
North America hair colorants comprise oxidative and non-oxidative dye systems, typically formulated with alkalizing agents, coupling intermediates, and conditioning polymers that deposit pigment onto or within the hair cortex. Permanent formulations dominate value contribution due to higher per-unit pricing and repeat purchase cycles tied to root regrowth. Cream-based delivery leads formulation preference in salon channels, while spray formats gain traction in temporary and fashion color applications. The at-home end-user segment expands fastest as post-pandemic behavior normalizes around self-application kits stocked through retail and e-commerce.
FDA oversight of coal-tar hair dyes under the FD&C Act, combined with state-level Proposition 65 enforcement in California, shapes permissible chemistry and labeling requirements across the region. Health Canada and PMRA standards for cosmetic safety further constrain cross-border formulation strategies. Stakeholders must monitor pending state legislation on per- and polyfluoroalkyl substance restrictions that could force reformulation of conditioning and shine agents.
Market Dynamics
At-home colorant adoption is compressing salon channel volume while FDA enforcement of coal-tar dye labeling forces reformulation cycles across oxidative and non-oxidative product lines.
Growth Catalysts
- Proposition 65 enforcement:California's chemical disclosure mandates push formulators toward safer alkalizing agents and conditioning polymers, opening premium positioning for compliant brands.
- Root regrowth cycles:Permanent dye users purchase every 4-6 weeks, creating predictable replenishment demand that sustains retail shelf presence and e-commerce subscription models.
- Spray format innovation:Temporary color applications in fashion and festival segments attract younger demographics previously outside the core hair colorant consumer base.
Market Restraints
- Ammonia substitute scarcity:MEA and ethanolamine alternatives carry higher raw material costs and narrower supplier bases, compressing margin structures for mass-market lines.
- Cross-border formulation friction:Health Canada PMRA standards diverge from FDA thresholds on p-phenylenediamine concentrations, forcing dual-SKU strategies that inflate inventory carrying costs.
- Gray coverage efficacy ceiling:Resistant gray hair requires higher developer volumes that accelerate cuticle damage, limiting repeat purchase loyalty among aging demographic cohorts.
Strategic Opportunities
- Midwestern manufacturing clusters:Illinois and Ohio R&D corridors offer captive pilot-scale production for custom salon lines with 48-hour formulation turnaround.
- Men's gray blending:Underpenetrated male demographic seeks subtle, gradual color deposition rather than full coverage, rewarding brands with targeted shade ranges and simplified application tools.
- Biodegradable conditioning polymers:Emerging state-level restrictions on per- and polyfluoroalkyl substances create first-mover advantage for suppliers with bio-based shine agent alternatives.
Industry Challenges
- Colorist certification bottlenecks:State licensing boards maintain inconsistent reciprocity standards, constraining salon chain expansion and standardized service delivery.
- Legacy ERP integration:Batch manufacturing systems struggle to accommodate made-to-order direct-to-consumer fulfillment, requiring middleware investments that strain mid-tier formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hair Colorants Market |
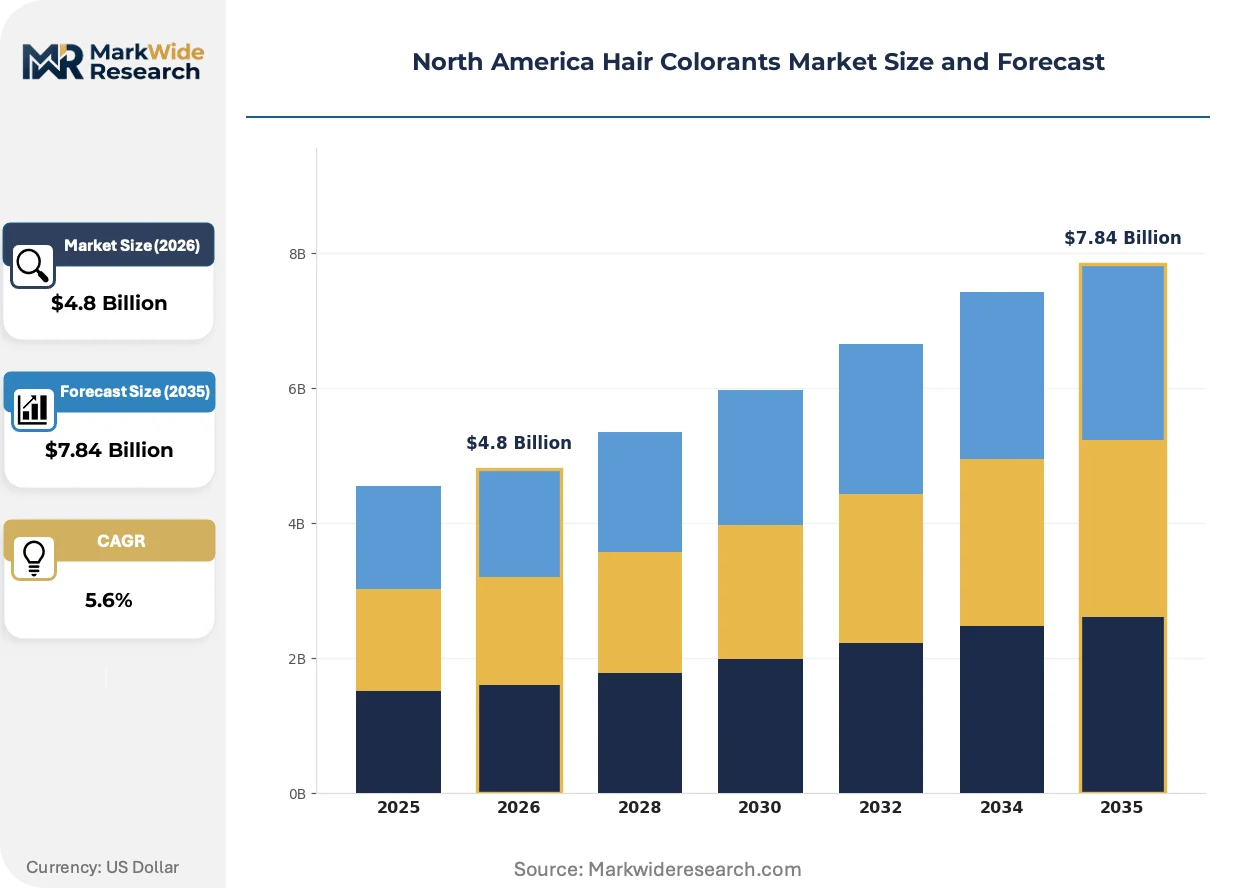
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent, Semi-Permanent, Temporary, Hair Mascara Formulation: Cream, Gel, Liquid, Spray End User: Salon, Retail, Professional, At-Home Color Type: Naturals, Fashion, Highlights, Ombre |
| Companies Covered | L'Oréal S.A., Henkel AG & Co. KGaA, COTY INC., Revlon, Kao Corporation, Procter & Gamble Co, Clairol, Estée Lauder Companies, Combe, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hair Colorants Market Evolving Landscape
Formulation chemistry and distribution architecture are undergoing parallel transformation as consumer tolerance for harsh ingredients declines and channel control fragments across retail, professional, and direct-to-consumer pathways.
Plant-derived dye precursors from indigo, henna, and walnut hull extracts are expanding into permanent colorant formulations previously dominated by synthetic intermediates. Premium salon brands and clean beauty retailers are adopting these materials at accelerating pace despite longer development timelines. The technology is expanding into oxidative systems through encapsulation methods that stabilize natural pigments against alkaline developer environments.
FDA scrutiny of coal-tar hair dyes under the FD&C Act intensified following adverse event reporting mandates enacted in 2024. Formulators now face compressed timelines for safety substantiation and expanded label disclosures that elevate compliance costs. Professional salon channels bear disproportionate impact as liability exposure concentrates with licensed colorists using higher-concentration products.
Subscription replenishment models for root touch-up kits are displacing episodic drugstore purchases among permanent colorant users. E-commerce platforms and specialty beauty retailers capture this shift through auto-delivery algorithms keyed to individual regrowth cycles. The pattern concentrates in United States metropolitan markets where delivery density supports free-shipping thresholds and return logistics infrastructure.
North America Hair Colorants Market Segmentation
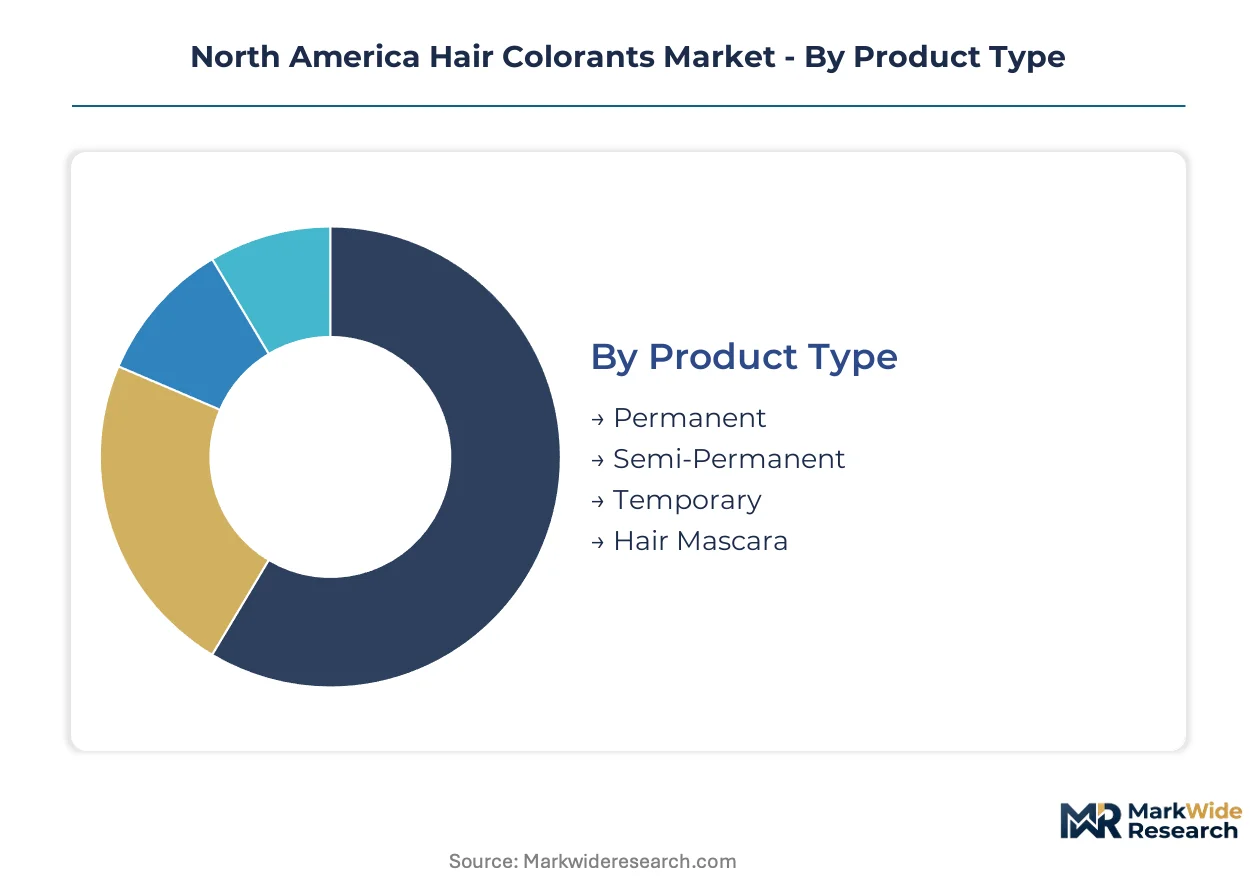
Hair colorant segmentation in North America reflects divergent consumer priorities across permanence expectations, application settings, and aesthetic goals. Formulators must balance oxidative chemistry performance against clean-label pressures while serving both licensed colorists and self-applicants.
Product Type:
Customization-vs-standardization tension peaks here, with permanent formulations demanding precise developer-pigment calibration while temporary options prioritize shelf stability and foolproof application.
- Permanent:Oxidative dye systems penetrate the cortex using ammonia or MEA alkalizers coupled with p-phenylenediamine intermediates. Salon channels in the United States concentrate demand here, driven by gray coverage requirements and root regrowth cycles that lock consumers into 4-6 week replenishment patterns.
- Semi-Permanent:Direct dyes deposit without developer activation, fading through 6-12 washes. California's Proposition 65 enforcement pushes formulators toward lower-concentration aromatic amine packages, compressing differentiation space between premium and mass-market lines.
- Temporary:Surface-coating pigments wash out in 1-2 shampoos, serving festival and costume segments.
- Hair Mascara:Wand-applied spot color for root touch-ups and gray camouflage between full applications.
Leading the category by volume: Permanent. Growing fastest: Hair Mascara.
Formulation:
Delivery format selection tracks channel economics, with cream bases commanding salon premium and spray formats capturing impulse retail velocity.
- Cream:Thickened emulsion systems enable precise sectioning and saturation control preferred by licensed colorists. Ohio and Illinois manufacturing clusters specialize in pilot-scale cream production with 48-hour formulation turnaround for custom salon lines.
- Gel:Lower-viscosity carriers suit men's gray blending applications where drip-free application and shorter processing times matter.
- Liquid:Pourable concentrates dominate at-home kit economics, enabling dual-chamber packaging that separates dye intermediates from developer until mixing.
- Spray:Aerosol and pump formats expand temporary color accessibility, with Los Angeles and New York metro areas driving fashion-forward adoption.
Cream formulations generate highest per-unit margin. Spray formats are expanding most quickly.
End User:
Channel control fragments as direct-to-consumer subscriptions displace drugstore episodic purchasing and salon chair density plateaus.
- Salon:Licensed colorist application commands premium pricing tied to labor arbitrage and liability concentration. State licensing board reciprocity bottlenecks constrain multi-location chain expansion across Texas, Florida, and New York.
- Retail:Mass-market shelf presence depends on slotting fee negotiations with CVS, Walgreens, and Ulta Beauty, where COTY and L'Oréal maintain disproportionate share.
- Professional:Back-bar gallon formats supply independent stylists and suite renters seeking brand affiliation without exclusive distribution contracts.
- At-Home:Self-application kits stocked through Amazon and specialty beauty platforms normalize post-pandemic, with auto-replenishment algorithms keyed to individual regrowth cycles.
At-Home segment climbs the fastest. Salon channel retains value leadership.
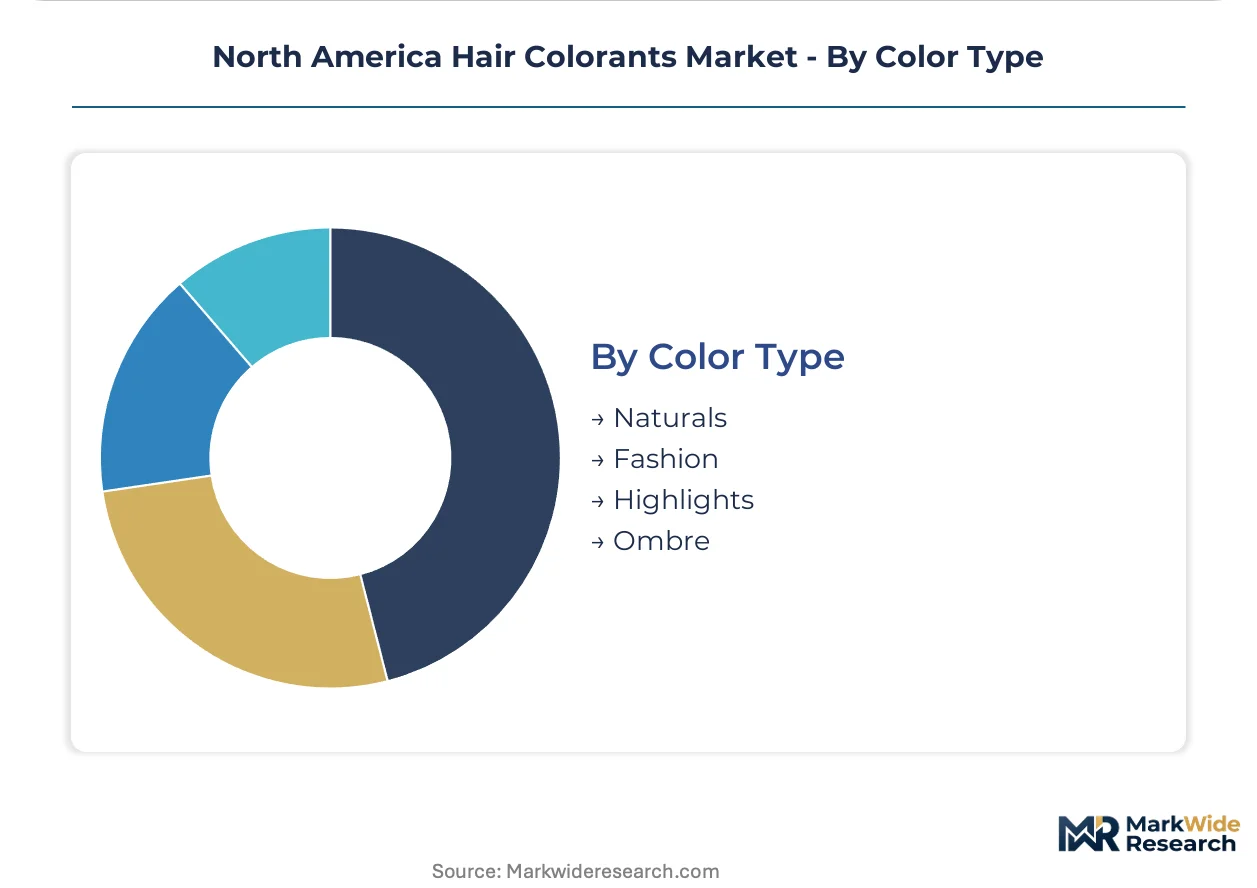
Color Type:
Aesthetic positioning ranges from demographic necessity (gray coverage) to discretionary expression (fashion shades), with formulation complexity inversely correlated to consumer age.
- Naturals:Black, brown, and blonde shades anchored in p-phenylenediamine and resorcinol chemistry serve the aging population's gray coverage imperative. FDA coal-tar dye labeling requirements intensify compliance burden for this high-volume category.
- Fashion:Vivid direct dyes in pink, blue, and violet hues attract under-35 consumers through TikTok-driven trial. Spray and temporary formats dominate here, lowering commitment barriers.
- Highlights:Bleach-and-tone or cap highlighting systems require professional skill for placement control, sustaining salon channel relevance.
- Ombre:Gradient techniques blending natural roots into lighter ends demand multi-step formulation and extended appointment times.
Naturals segment holds volume dominance. Fashion color shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan markets concentrate the majority of regional demand through dense salon networks and e-commerce fulfillment infrastructure. Canada and Mexico present distinct regulatory and channel dynamics that require tailored formulation and distribution strategies.
United States
California's Proposition 65 enforcement drives formulators toward safer alkalizing agents and expanded chemical disclosures. The FDA maintains strict coal-tar hair dye labeling requirements under the FD&C Act. New Jersey and Illinois host captive R&D centers serving both professional salon lines and mass-market retail kits.
Canada
Health Canada and PMRA standards diverge from FDA thresholds on p-phenylenediamine concentrations, forcing dual-SKU inventory strategies. Toronto and Vancouver anchor retail distribution networks with cross-border e-commerce integration. Ontario-based manufacturing clusters specialize in compliant formulations for both domestic and export markets.
Mexico
Mexico City Metro and Monterrey concentrate demand through professional salon channels and informal retail networks. COFEPRIS cosmetic safety regulations shape permissible chemistry for products manufactured domestically versus imported formulations. Nuevo León industrial corridors support contract manufacturing for brands seeking nearshored production.
North America Hair Colorants Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents balance professional salon prestige against mass-market volume capture. The vendor base stratifies into three tiers: multinational beauty conglomerates with captive R&D infrastructure, mid-sized specialists with salon-exclusive distribution, and private-label contract manufacturers serving retail channel clients. Strategic archetypes include science-forward formulators leveraging pharmaceutical-grade safety substantiation, trend-responsive players capturing fashion color cycles, and efficiency-driven operators optimizing at-home kit economics. M&A activity and geographic expansion represent the dominant competitive moves as players seek scale and regulatory arbitrage.
Within the multinational tier, L'Oréal S.A., Henkel AG & Co. KGaA, and COTY INC. exemplify divergent strategic positions. L'Oréal S.A. anchors its North American presence through captive innovation infrastructure in New Jersey and Illinois. Henkel AG & Co. KGaA occupies a position emphasizing professional channel control through salon-direct distribution networks. COTY INC. represents the mass-market density archetype with drugstore shelf presence and retail partnership concentration.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| COTY INC. |
| Revlon |
| Kao Corporation |
| Procter & Gamble Co |
| Clairol |
| Estée Lauder Companies |
| Combe |
| Others |
Value Network & Pricing Analysis
California's Proposition 65 enforcement gates qualified supply for premium-tier hair colorant formulations, restricting p-phenylenediamine concentrations and mandating expanded chemical disclosures that elevate compliance costs. Formulators meeting these standards command pricing premiums from professional salon channels and clean beauty retailers, while mass-market lines face margin compression from reformulation cycles and dual-SKU inventory burdens.
Pricing Analysis
Volume-vs-margin splits sharply across the North American hair colorants landscape, with permanent oxidative formulations generating highest per-unit returns through 4-6 week replenishment cycles, while temporary spray formats sacrifice margin for impulse velocity. Price differentiation rests on FDA coal-tar dye certification tiers and salon channel exclusivity, with professional back-bar gallons commanding 3-4x per-ounce premiums over retail kits. Cost compression in mass-market ammonia-substitute chemistry is intensifying because MEA and ethanolamine alternatives carry narrower supplier bases. At-home self-applicants exhibit highest price sensitivity, whereas licensed colorists prioritize efficacy and liability protection over unit cost.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Illinois and Ohio R&D corridors, where pilot-scale manufacturing clusters enable 48-hour formulation turnaround for custom salon lines. Raw material dependencies draw from China for p-phenylenediamine intermediates, Germany for conditioning polymer specialties, and domestic petrochemical feedstocks for alkalizing agents. Single-source vulnerability concentrates in encapsulated natural pigment supply for clean-label oxidative systems. Distribution runs through regional professional beauty distributors serving salon chains, direct-to-consumer fulfillment centers for subscription replenishment, and mass-market retail DCs for drugstore shelf stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America hair colorants market functions as a vertical-integration race, with players pursuing captive R&D infrastructure to compress formulation turnaround times and defend margin structures against regulatory-driven reformulation cycles.
For Market Incumbents: Acquire pilot-scale manufacturing assets in Midwestern corridors to secure 48-hour custom formulation capability for salon-exclusive lines. Consolidate position by locking multi-year p-phenylenediamine supply contracts before pending state-level PFAS restrictions inflate input costs. Channel control through direct salon distribution networks remains essential as e-commerce subscriptions displace retail shelf velocity. For New Entrants and Emerging Players: Enter via biodegradable conditioning polymer innovation targeting California's Proposition 65 compliance gaps ahead of incumbent reformulation cycles. Men's gray blending represents the most penetrable white-space segment, with underpenetrated male demographics seeking gradual deposition tools. A direct-to-consumer subscription model keyed to individual regrowth cycles offers the clearest go-to-market angle against entrenched retail shelf control. For Investors and Strategic Acquirers: FDA adverse event reporting mandate intensification is the leading indicator that liability exposure will concentrate with professional channel players possessing pharmaceutical-grade safety substantiation infrastructure. Long-term viability across the projection horizon favors science-forward formulators with captive R&D centers over trend-responsive fashion color specialists. Acquisition target archetypes include mid-sized salon-exclusive brands with compliant formulation libraries and established professional distributor relationships. Watch for state-level PFAS restriction passage as the inflection signal triggering accelerated M&A among conditioning polymer suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkalizing Agent Production | Captive MEA and ethanolamine supply secures margin control against raw material cost volatility. |
| Clean-Label Formulation Certification | Proposition 65 compliance unlocks premium positioning in California's high-value salon and retail channels. |
| Subscription Replenishment Platform Launch | Auto-delivery algorithms keyed to root regrowth cycles capture recurring revenue from permanent colorant users. |
| Midwestern Manufacturing Cluster Expansion | Ohio and Illinois pilot-scale assets enable rapid custom formulation turnaround for professional salon lines. |
| Men's Gray Blending Product Line Extension | Simplified application tools for gradual color deposition address underpenetrated male demographic demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North America hair colorants market assessment. Primary interviews with formulation chemists, professional salon distributors, retail category buyers, and regulatory affairs specialists at FDA and Health Canada supplemented secondary validation. FDA coal-tar dye labeling databases, Health Canada PMRA cosmetic safety submissions, and professional beauty association membership records provided quantitative anchors. Bottom-up SKU-level modeling triangulated against top-down channel revenue estimates.
Granularity-level framing applied country-specific regulatory thresholds, product-type permanence categories, and end-user channel distinctions across the modeling period. Segmentation dimensions included formulation chemistry type, delivery format, and professional versus at-home application setting. CAGRs derived from regression analysis of historical replenishment cycle data and channel shift trajectories. Industry-specific forecast inputs incorporated salon chair density projections and e-commerce fulfillment infrastructure expansion rates.
Revisions become necessary when state-level PFAS restriction legislation materializes or FDA enforcement intensity shifts coal-tar dye labeling timelines. Forecasts reflect assumptions regarding regulatory stability and raw material supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Organic Lake Pigments Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Laser Sensitive Pigments Market