

Copper Chromite Black Pigment Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Chromite Black Pigment Market Insights
Aftermarket technical service revenue is rewriting how pigment suppliers capture lifetime value from coatings formulators. The Shepherd Color Company leverages its Color Solutions Lab network to sustain deep formulation partnerships with automotive OEMs. Heubach anchors European supply through specialized high-heat stable pigment production for industrial coatings. Zhonglong Materials dominates cost-optimized powder grades for Asia-Pacific plastics processors.
Copper chromite black pigment is a complex inorganic color pigment (CICP) synthesized from copper(II) oxide and chromium(III) oxide calcined at temperatures exceeding 700°C, yielding a spinel crystal structure with exceptional thermal stability above 1000°C and strong infrared reflectance. Its primary industrial purpose is to deliver durable jet-black coloration in high-performance coatings, plastics, and ceramics where organic pigments would degrade under thermal or UV stress. Micronized grades command premium positioning in automotive basecoat systems where particle size distribution directly governs gloss and flop behavior. The coatings application segment leads absolute volume, though ceramics demand is accelerating fastest as architectural tile producers in Southern Europe adopt infrared-reflective cool pigments for energy-efficient building envelopes.
EPA oversight under the Toxic Substances Control Act shapes permissible chromium content thresholds for pigments sold into U.S. consumer goods, while REACH registration requirements in Europe mandate full toxicological dossiers for copper chromite imports. China's GB standards for hazardous substance limits in coatings and plastics create a parallel compliance track that domestic producers such as Hunan Jufa Pigment navigate more efficiently than foreign entrants. Stakeholders must monitor whether forthcoming amendments to EU CLP classification rules will recategorize chromium-containing pigments, as this would force immediate reformulation investments across the European supply base.
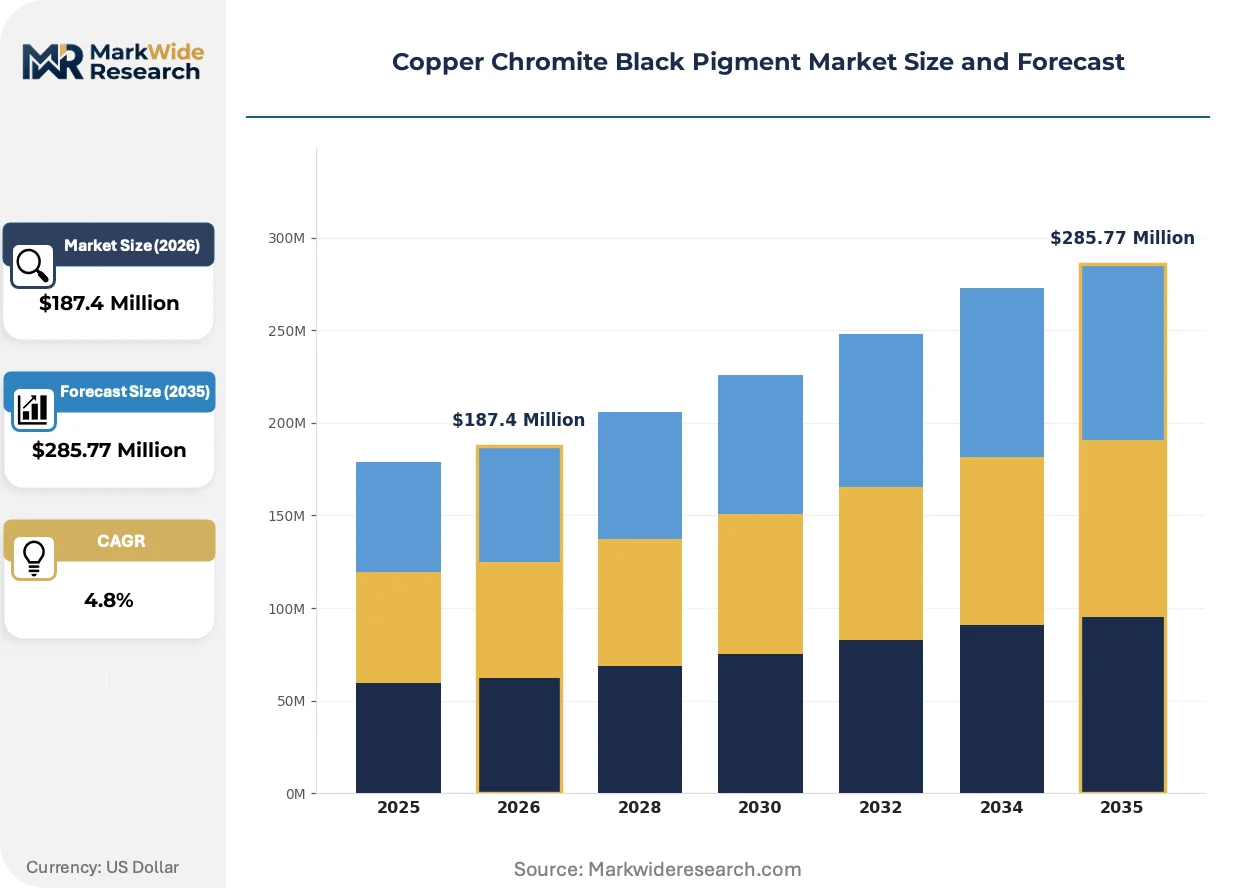
Market Dynamics
REACH compliance deadlines and EPA heavy-metal thresholds are compressing formulation windows for coatings manufacturers, forcing accelerated qualification of compliant copper chromite grades before legacy stocks deplete.
Growth Catalysts
- Infrared-reflective architectural coatings:Building envelope energy codes in Germany and Spain mandate solar reflectance for dark pigments, pulling copper chromite into cool roof formulations.
- Automotive OEM thermal management:EV battery pack housings and exterior body panels require pigments stable above 300°C during cathodic electrocoat curing cycles.
- REACH registration completion:Full toxicological dossiers for copper chromite now enable uninterrupted European supply to industrial coatings compounders.
Market Restraints
- Chromium oxide feedstock concentration:South African chromite ore processing dominates metallurgical-grade chromium supply, exposing pigment producers to export duty volatility.
- Calcination energy intensity:Sustained 700-1000°C firing requirements consume natural gas volumes that European producers cannot hedge beyond twelve-month horizons.
- Organic black pigment substitution:Carbon black formulations with improved UV stabilizer packages compete in lower-temperature plastics applications below 200°C processing thresholds.
Strategic Opportunities
- India industrial coatings expansion:BIS certification harmonization with REACH standards positions domestic pigment distributors to supply Maharashtra and Gujarat automotive clusters.
- Ceramic inkjet printing adoption:Architectural tile producers in Italy and Spain are converting from roller coating to digital decoration, requiring sub-micron pigment dispersions.
- EU Green Deal embodied carbon tracking:EPD certification for building materials creates preference for domestically produced pigments with verified Scope 3 emissions data.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in CICP dispersion rheology and high-temperature stability testing concentrates among retiring technicians at legacy coatings laboratories.
- Dual compliance timeline compression:Simaneous EPA TSCA Section 5 notifications and EU CLP reclassification reviews strain regulatory affairs bandwidth at mid-sized pigment suppliers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Chromite Black Pigment Market Trends and Innovations
Particle engineering and digital color matching are compressing development cycles for custom pigment grades, while regulatory transparency tools reshape how buyers verify compliance credentials.
Micronization technology is hybridizing with surface treatment chemistries to produce dual-function pigments that simultaneously deliver jet-black coloration and enhanced dispersibility in waterborne automotive basecoats. Tier 1 coatings suppliers in Stuttgart and Detroit are qualifying these grades for robotic spray applications where particle size distribution governs transfer efficiency. The structural consequence is compressing qualification timelines from 18 months to 9 months for OEM color approvals.
EPA is finalizing amendments to chromium compound reporting thresholds under TSCA Section 8(a), requiring pigment importers to disclose volume and end-use data previously exempt from disclosure. Industrial coatings formulators serving consumer goods markets face reformulation investments to maintain market access. The segment most affected is household appliance finishes, where manufacturers are pre-qualifying alternative CICP blacks before the rule takes effect.
Coatings procurement teams are unbundling technical service contracts from pigment supply agreements, paying separately for formulation support while driving raw material costs toward spot-indexed benchmarks. Automotive OEM color labs in Wolfsburg and Toyota City now contract directly with pigment technical service networks. This shift is most visible in Japan, where METI-sponsored digital supply chain platforms enable transparent price discovery for specialty pigment grades.
Copper Chromite Black Pigment Market Segmentation
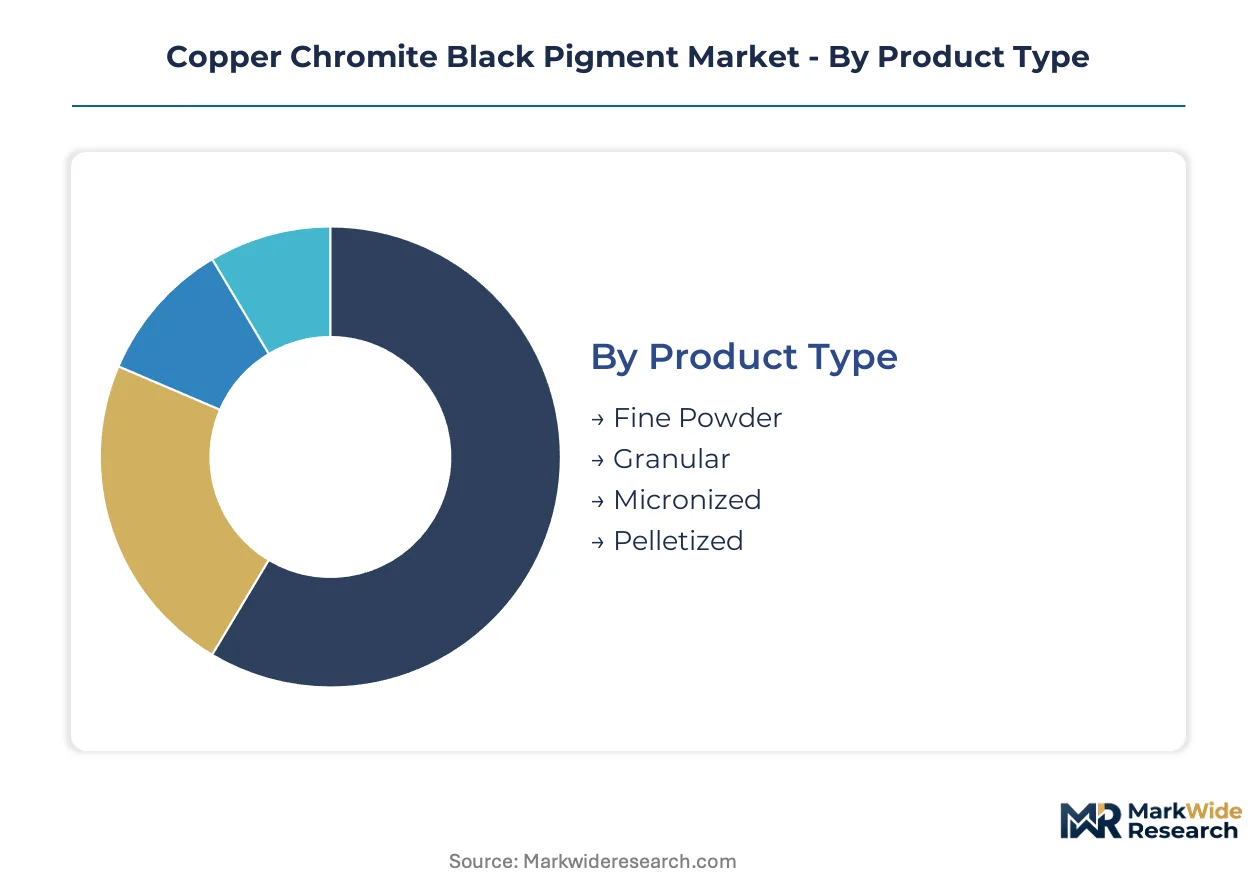
Copper chromite black pigment suppliers configure product specifications around thermal stability thresholds and dispersion requirements that vary sharply across coatings, ceramics, and plastics processing. Segmentation discipline separates volume-driven commodity grades from premium micronized variants where particle engineering commands pricing power in automotive OEM qualifications.
Product Type:
Use-case spectrum spans powder metallurgy feedstocks requiring free-flowing granular grades through to waterborne automotive basecoats demanding sub-micron dispersions.
- Fine Powder:Standard milled pigment with particle sizes between 5-15 microns serves high-volume industrial coatings where cost efficiency outweighs gloss requirements. Demand concentrates in China's architectural coatings corridor, with domestic processors scaling output for Southeast Asian export markets constrained by REACH registration timelines.
- Micronized:Sub-micron particle engineering through jet milling and surface treatment delivers controlled gloss and flop in robotic automotive spray applications. Stuttgart and Detroit OEM color labs are compressing qualification cycles for these grades as waterborne basecoat formulations displace solvent-borne systems.
- Granular:Agglomerated free-flowing form reduces dusting during bulk handling for powder coatings compounders.
- Pelletized:Binder-bound concentrates simplify dosing precision for continuous plastics extrusion lines in polyolefin masterbatch production.
The dominant share belongs to Fine Powder, while Micronized is closing the gap fastest.
Application:
Cost tier stratification separates commodity ceramics consumption from premium automotive thermal management specifications.
- Coatings:Architectural and automotive finishes represent the volume anchor, with infrared-reflective formulations gaining share in Germany and Spain cool roof mandates. Cathodic electrocoat curing cycles above 300°C filter out organic pigment alternatives.
- Ceramics:Architectural tile producers in Italy and Spain are converting from roller coating to digital inkjet decoration, pulling sub-micron pigment dispersions into ceramic ink formulations. Southern European building envelope energy codes accelerate adoption of solar-reflective dark pigments.
- Plastics:Polyolefin and engineering polymer coloration for consumer goods and automotive interiors, competing with carbon black in sub-200°C processing windows.
- Printing Inks:UV-curable and solvent-based systems for specialty packaging requiring heat resistance during drying.
- Rubber:Industrial hose and conveyor belt applications where thermal stability exceeds organic pigment limits.
Coatings retains the largest volume position, though Ceramics is expanding most quickly as digital decoration technology penetrates tile manufacturing.
End User:
Customer type determines technical service intensity and contract structure, with automotive OEM direct relationships commanding premium positioning.
- Paint Manufacturers:Industrial and automotive coatings compounders drive micronized grade specifications, unbundling technical service contracts from pigment supply agreements in Wolfsburg and Toyota City procurement patterns.
- Plastic Processors:Masterbatch compounders and direct extrusion operators in Asia-Pacific markets prioritize cost-optimized powder grades with consistent batch-to-batch color.
- Ink Producers:Specialty packaging ink formulators requiring dispersion stability in high-solids UV systems.
- Ceramic Artisans:Small-scale tile and sanitary ware producers with fragmented procurement patterns and limited formulation support requirements.
Paint Manufacturers command the deepest technical service relationships, while Plastic Processors are gaining procurement leverage through consolidated masterbatch distributor networks.
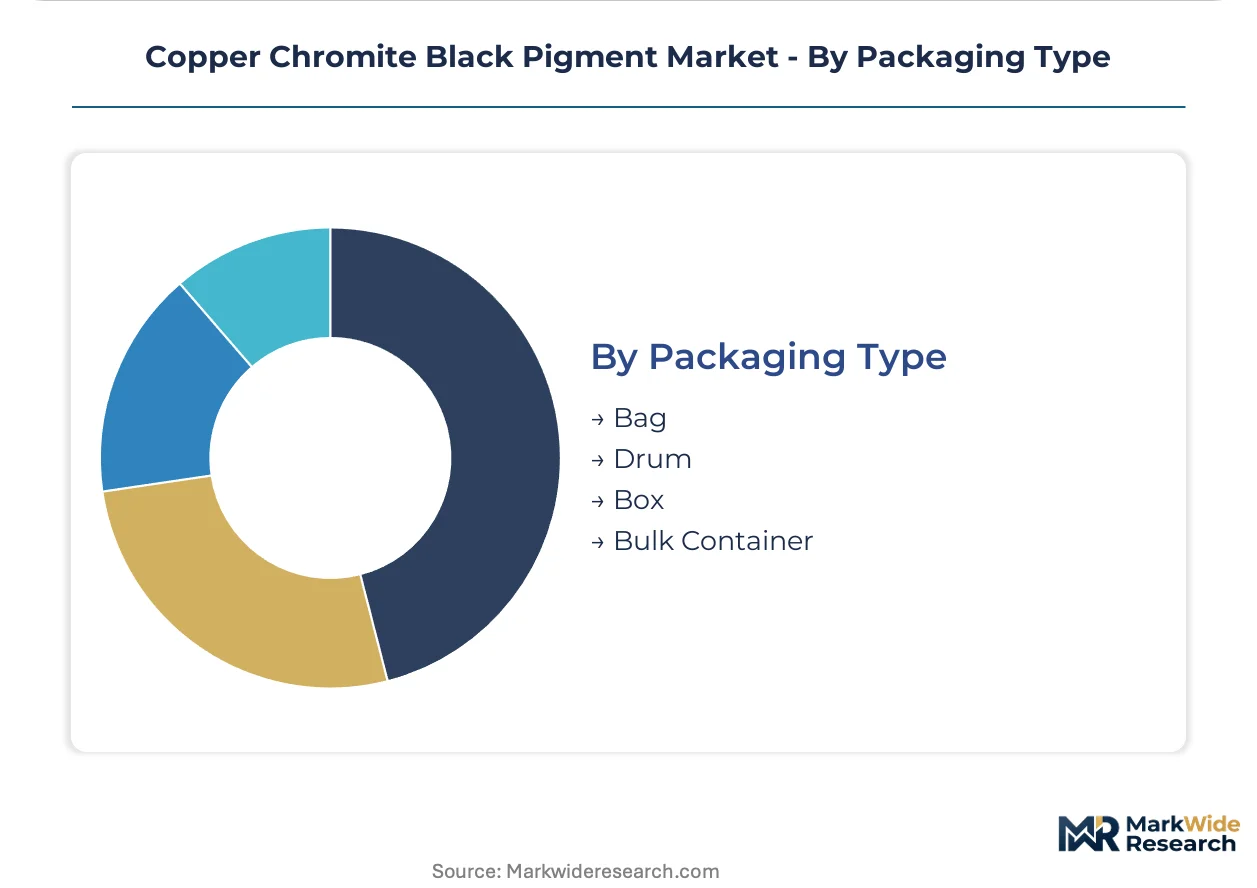
Packaging Type:
Supply chain configuration tracks volume scale and handling automation, with bulk systems penetrating high-throughput coatings plants.
- Bag:Standard 25kg multi-wall paper sacks for mid-volume coatings and plastics processors with manual handling capabilities.
- Drum:Steel and fiber containers for moisture-sensitive micronized grades requiring sealed storage in humid climates.
- Box:Corrugated bulk bins for automated dosing systems in continuous production environments.
- Bulk Container:Intermediate bulk containers and silo deliveries for high-volume automotive coatings plants with pneumatic conveying infrastructure.
Bag packaging still handles the majority of shipments, though Bulk Container adoption is climbing fastest among tier 1 coatings suppliers consolidating receiving operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes copper chromite black pigment predominantly for plastics masterbatch export supply, while Germany and the United States concentrate procurement in automotive thermal management coatings. This consumption-mix differential shapes regional supply chain configurations and technical service intensity.
China
Domestic pigment processors scale output for Southeast Asian plastics compounders seeking REACH-registered feedstock. GB standards for hazardous substance limits in coatings create parallel compliance tracks that Hunan Jufa Pigment navigates efficiently. The Yangtze River Delta clusters pigment dispersion facilities serving both local architectural coatings and export ceramic inkjet markets.
Germany
Automotive OEM color labs in Stuttgart drive micronized grade specifications for waterborne basecoat systems. ECHA REACH registration requirements mandate full toxicological dossiers for copper chromite imports, filtering supplier qualification. Bavaria's industrial coatings corridor concentrates cathodic electrocoat curing expertise for EV battery pack housings.
United States
EPA TSCA Section 8(a) amendments force pigment importers to disclose volume and end-use data previously exempt. Household appliance finish manufacturers in the Midwest pre-qualify alternative CICP blacks before rule implementation. Detroit automotive clusters compress OEM color approval timelines from 18 months to 9 months.
India
Maharashtra and Gujarat automotive clusters expand procurement as BIS certification harmonizes with REACH standards. Domestic pigment distributors capture industrial coatings supply previously routed through European traders. Western India masterbatch compounders consolidate distributor networks to gain procurement leverage.
Spain
Architectural tile producers in Valencia and Catalonia convert from roller coating to digital inkjet decoration, pulling sub-micron pigment dispersions. Building envelope energy codes mandate solar reflectance for dark pigments in cool roof formulations. Southern European ceramics demand accelerates fastest among all application segments.
Copper Chromite Black Pigment Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The copper chromite black pigment market structures around three to five dominant processors controlling premium micronized grades, while Chinese domestic suppliers capture volume in standard powder metallurgy feedstocks. Strategic archetypes separate infrared-reflective formulation specialists, calcination-integrated mineral processors, and regional distribution-anchored traders. Competitive moves concentrate on backward integration into chromium oxide feedstock and technical service network expansion.
Within the formulation-specialist tier, The Shepherd Color Company and Heubach exemplify premium positioning through deep OEM color lab relationships. Zhonglong Materials occupies a position among cost-optimized powder grade suppliers serving Asia-Pacific plastics processors. Hunan Jufa Pigment represents the domestic Chinese archetype navigating GB standards compliance more efficiently than foreign entrants. These three anchors illustrate how geographic origin and company structure correlate with strategic positioning across capability-intensive versus scale-driven market segments.
| Leading Market Players |
|---|
| The Shepherd Color Company |
| Vibrantz Technologies |
| Heubach |
| BASF SE |
| Asahi Kasei Kogyo |
| Zhonglong Materials |
| Hunan Jufa Pigment |
| Jiangxi Dingrui New Materials |
| Carl Schlenk |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam container corridor anchors freight cost dynamics that amplify both supply concentration effects and downstream price stratification across copper chromite black pigment tiers. Chinese processors leverage this route's scale economies to undercut European calcination costs, while automotive OEMs in Stuttgart absorb premium logistics spend for micronized grades with guaranteed thermal stability certification.
Pricing Analysis
Long-term offtake agreements dominate procurement between tier 1 coatings suppliers and calcination-integrated processors, locking in chromium oxide feedstock costs against South African export duty volatility. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered micronized grades for automotive OEMs from unregistered powder feedstocks for plastics masterbatch compounders. Price differentiation hinges on thermal stability certification tier and volume scale commitment, with spot-indexed benchmarks penetrating Asia-Pacific distributor networks. Cost compression in standard powder grades is intensifying because Zhonglong Materials and Hunan Jufa Pigment are expanding calcination capacity; plastic processors remain most price-sensitive while automotive color labs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now structure working capital flows between European coatings compounders and Chinese pigment exporters, with supply-chain finance facilities emerging as competitive differentiators for mid-sized distributors. Geographic supply concentration centers on China, South Africa, and Germany, with chromium oxide feedstock drawing from Bushveld Complex metallurgical operations and calcination energy anchored in Yangtze River Delta gas supply. Raw material dependencies rest on chromite ore, metallurgical-grade copper oxide, and natural gas for sustained 700-1000°C firing. Single-source vulnerability runs through South African chromite export channels. Distribution runs through consolidated masterbatch distributor networks in Asia-Pacific and direct technical service relationships in European automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in ceramic inkjet decoration, where digital tile production in Italy and Spain is displacing roller-coating pigment specifications faster than incumbent supply chains can reconfigure. This demand-side shift creates niche entry points for sub-micron dispersion specialists outside legacy coatings networks.
For Market Incumbents:Pre-empt organic black pigment substitution in sub-200°C plastics applications by qualifying copper chromite grades with enhanced UV stabilizer packages at price parity. Backward integration into chromium oxide feedstock secures margin against South African export duty volatility, while technical service network expansion in Maharashtra and Gujarat automotive clusters defends share against emerging Indian distributors.
For New Entrants and Emerging Players:India's industrial coatings corridor offers the most penetrable white-space target, where BIS-REACH harmonization has fragmented procurement previously captured by European traders. Ceramic inkjet ink formulation presents a second entry vector, with sub-micron pigment dispersion expertise transferable from digital printing adjacent sectors. Go-to-market leverage rests on direct technical service contracts with Valencia and Catalonia tile producers bypassing incumbent distributor markups.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified chemical conglomerates with underoptimized pigment divisions lacking REACH registration completion or automotive OEM color lab relationships. Long-term viability over the projection horizon favors calcination-integrated assets with verified Scope 3 emissions data for EU Green Deal EPD certification. The signal to watch is EPA TSCA Section 8(a) enforcement intensity against non-compliant household appliance finish imports, which would accelerate consolidation toward registered suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromium Oxide | Captive supply of Bushveld Complex feedstock insulates margin from South African export duty volatility. |
| REACH Registration Completion | Full toxicological dossiers enable uninterrupted European supply to industrial coatings compounders. |
| Technical Service Network Expansion | Direct formulation partnerships with Stuttgart and Toyota City OEM color labs compress qualification cycles. |
| Sub-micron Dispersion Capacity Addition | Jet milling investment captures ceramic inkjet demand from Valencia and Catalonia tile producers. |
| Scope 3 Emissions Verification | EPD certification for building materials creates preference in EU Green Deal procurement frameworks. |
Research Methodology
A standing panel of calcination plant managers, automotive OEM color lab directors, coatings procurement leads, and ceramic inkjet formulators provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews combined with customs/trade data, Cefic sector reports, SEC 10-K filings from listed chemical conglomerates, and ECHA REACH registration databases enabled bottom-up volume triangulation against top-down value estimates from coatings and plastics industry associations.
Scenario-bracketing framed analytical approach across the analysis window, with segmentation dimensions modeling product type tier, end-use industry, regional production hub, and thermal stability specification grade. CAGRs derived from weighted average of historical volume trajectories and forward-looking capacity expansion announcements, with chromium oxide price volatility and natural gas cost curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese domestic processors or accelerated EPA enforcement against chromium compound reporting would shift outcomes. Macroeconomic deviation in automotive production, regulatory reclassification under EU CLP rules, or breakthrough organic pigment thermal stability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.