
 Pigment Dispersion Resin Market | 2026-2036
Pigment Dispersion Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Pigment Dispersion Resin Market Analytics
China is reshaping supply dynamics through expanded acrylic and polyurethane dispersion resin capacity serving coatings and plastics converters. BASF SE leverages integrated precursor supply from Ludwigshafen to sustain margin control across European automotive pigment dispersions. Sun Chemical anchors North American ink specialization with waterborne formulation expertise. Heubach GmbH competes through heritage color chemistry knowledge applied to high-performance epoxy dispersions.
Pigment dispersion resin denotes a polymeric carrier system—typically acrylic, epoxy, polyurethane, or vinyl—engineered to stabilize and distribute pigment particles at 40-60% solids content while controlling viscosity and preventing flocculation in liquid or powder coatings. Acrylic resins dominate volume in architectural and automotive coatings due to clarity, UV resistance, and waterborne compatibility. Polyurethane dispersions command premium positioning in flexible packaging inks and textile applications where elasticity and adhesion prove critical. Solvent-based formulations retain share in industrial maintenance coatings requiring extreme chemical resistance, though regulatory pressure erodes this position steadily.
EPA VOC regulations in the United States, REACH authorization requirements in Europe, and China's MEE emission standards collectively restrict solvent-borne systems and redirect R&D investment toward waterborne and UV-cured alternatives. FDA compliance for healthcare and food-contact applications adds a secondary compliance layer that limits qualified resin suppliers. Stakeholders must monitor regulatory divergence between jurisdictions while building formulation flexibility that accommodates both low-VOC mandates and performance specifications from automotive and electronics end users.
Market Dynamics
Waterborne formulation chemistry is reconfiguring competitive advantage across coatings value chains, compressing solvent-borne margins while rewarding resin producers with integrated acrylic precursor capabilities.
Growth Catalysts
- REACH VOC limits:European coatings formulators face tightening emission thresholds under EU Green Deal implementation, redirecting procurement toward low-solids acrylic dispersions.
- Automotive refinishing waterborne transition:Collision repair networks in Germany and the United States are mandating waterborne basecoat systems to meet booth emission standards.
- UV-cured inkjet expansion:Packaging converters are adopting energy-curable pigment dispersions for narrow-web label applications requiring instant drying.
Market Restraints
- Propylene oxide volatility:Acrylic dispersion resin producers face margin compression from upstream petrochemical feedstock price swings.
- MEE enforcement in China:Environmental compliance costs for solvent-borne capacity retrofits are eroding cost advantages for smaller dispersion resin manufacturers.
- Performance gap in chemical resistance:Waterborne epoxy dispersions still fail to match solvent-borne equivalents in heavy industrial maintenance exposures.
Strategic Opportunities
- India automotive OEM localization:Domestic coating plants serving Maruti Suzuki and Hyundai Motor India are qualifying local pigment dispersion resin sources.
- Food-contact compliance:FDA Title 21 clearance for dispersion resins opens flexible packaging ink applications previously blocked by migration limits.
- Digital printing convergence:Inkjet pigment dispersions are penetrating ceramic tile decoration, displacing traditional screen printing in Italian and Spanish manufacturing clusters.
Industry Challenges
- Colloidal stability expertise scarcity:Formulation chemists capable of engineering 40-60% solids dispersions with sub-micron particle size control command premium compensation.
- Multi-jurisdiction registration burden:Separate REACH, TSCA, and K-REACH filings for each resin chemistry extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigment Dispersion Resin Market |
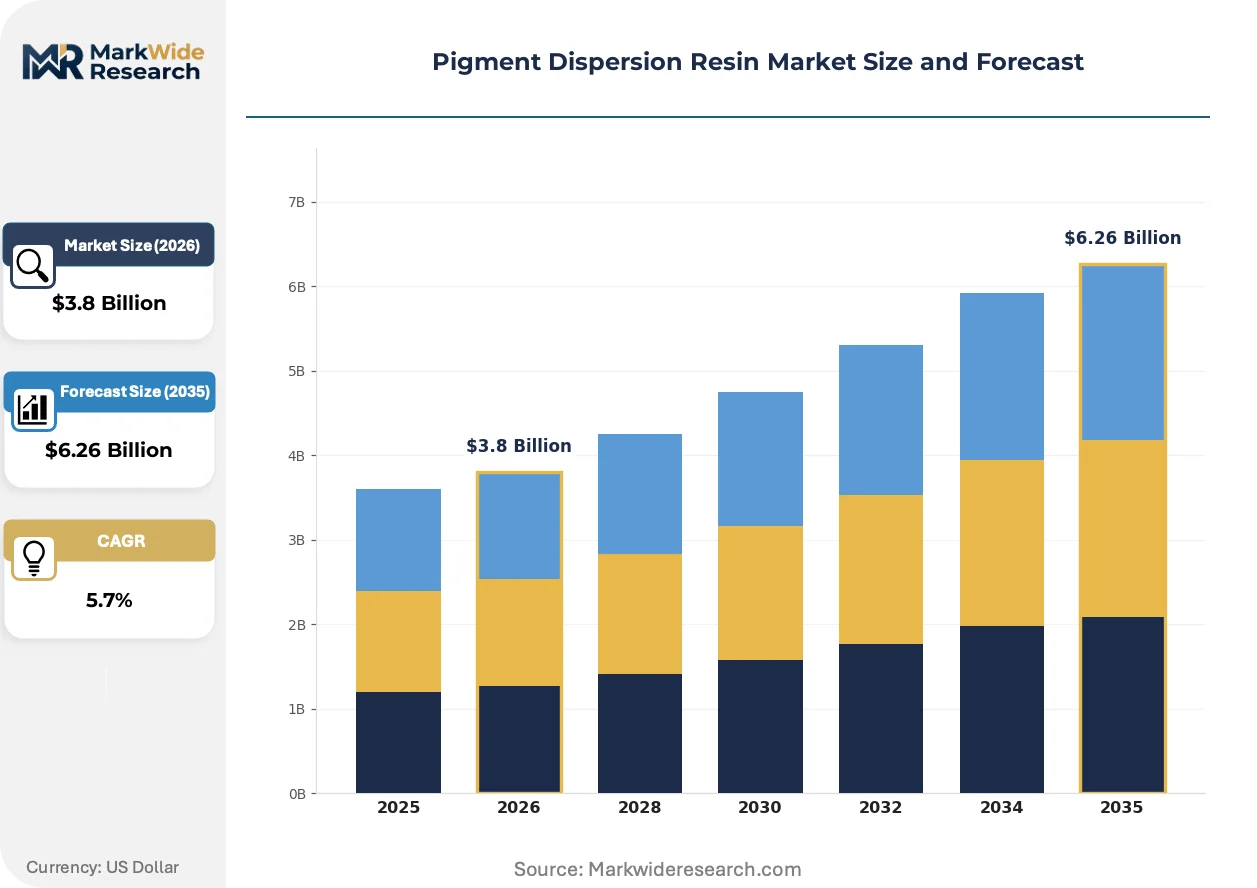
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Vinyl Application: Coatings, Inks, Plastics, Textiles End User: Automotive, Construction, Electronics, Healthcare Formulation: Waterborne, Solvent-based, UV-cured, Powdered |
| Companies Covered | Vibrantz, Heubach GmbH, BASF SE, Sun Chemical, Lanxess, DIC Corporation, Cabot Corporation, Penn Color, Sudarshan Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigment Dispersion Resin Market Evolving Landscape
Reactive diluent technology and hybrid dispersion architectures are compressing the performance gap between waterborne and solvent-borne systems, enabling regulatory compliance without sacrifice in film properties.
Self-crosslinking acrylic dispersion chemistry is rendering obsolete two-pack polyurethane systems in wood furniture coatings. Italian and German kitchen cabinet manufacturers are converting spray lines to single-component waterborne finishes. This shift collapses pot-life constraints and reduces mixing labor while matching solvent-borne scratch resistance.
EPA Method 24 VOC testing protocol revisions are forcing reformulation of architectural coatings sold in California and Northeastern states. The amended calculation rules capture previously exempt exempt solvents, compelling resin suppliers to reduce coalescent levels in dispersion formulations. High-solids acrylic suppliers serving the DIY channel are accelerating low-temperature film formation R&D.
Specification-driven procurement is consolidating qualified supplier lists among automotive OEM coating divisions. Tier-1 paint shops now require resin producers to pre-validate dispersion stability through 12-month storage testing before contract award. This behavior concentrates volume with established German and Japanese resin houses possessing archival performance data.
Pigment Dispersion Resin Market Segmentation
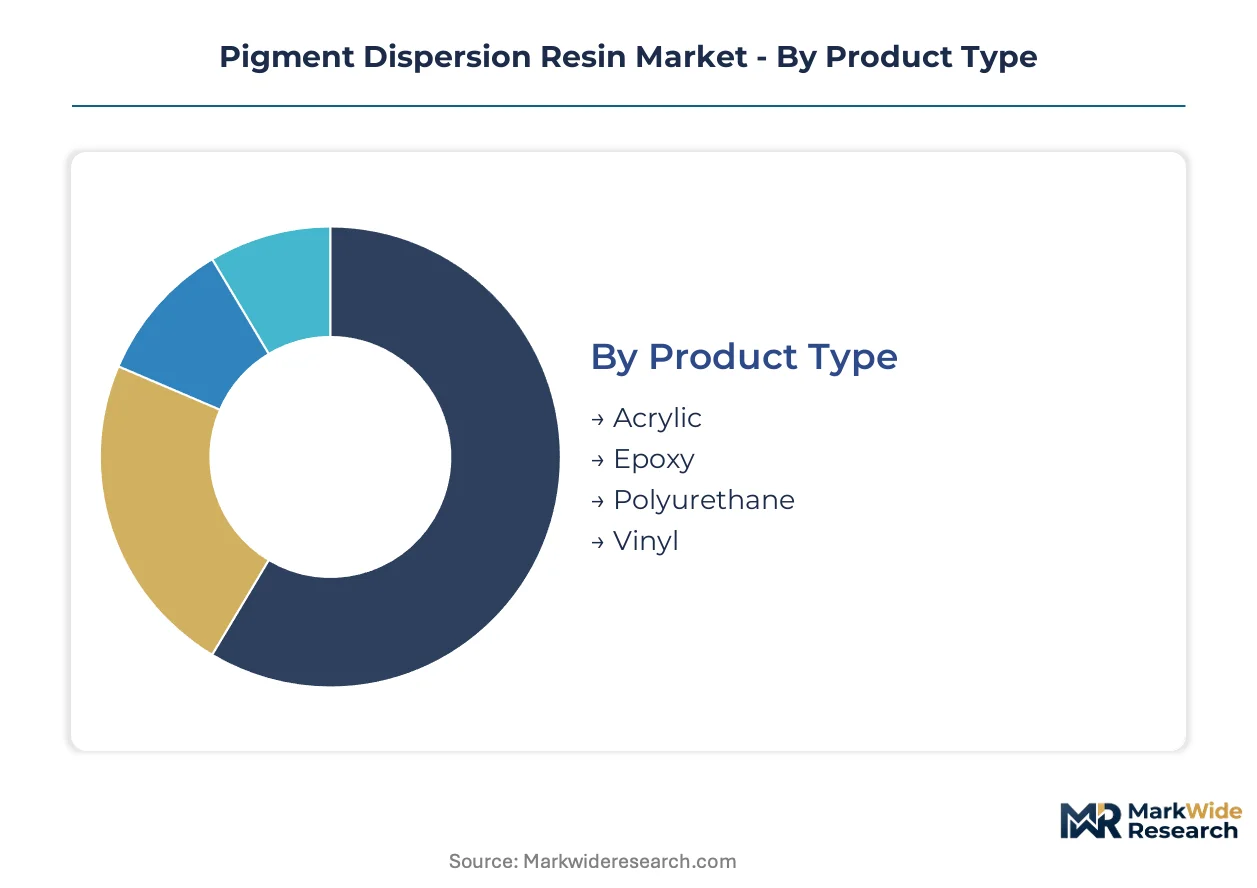
Pigment dispersion resin procurement patterns diverge sharply across chemistry families and application specifications, with automotive refinishing and architectural coatings driving divergent performance requirements. Formulation chemistry—waterborne versus solvent-borne—now functions as the primary axis of competitive positioning, as regulatory pressure reshapes viable supply options.
Product Type:
Mature acrylic systems dominate architectural volume, while polyurethane and vinyl chemistries occupy narrower but higher-margin niches in specialized applications.
- Acrylic:Waterborne acrylic dispersions deliver clarity, UV stability, and pigment compatibility at 40-60% solids content. German automotive refinishing networks and North American DIY coating channels concentrate procurement here, pressured by EPA Method 24 VOC calculations and EU Green Deal emission thresholds.
- Epoxy:Two-pack and self-crosslinking epoxy dispersions anchor industrial maintenance and protective coatings. Demand concentrates in German chemical processing infrastructure and US marine applications where chemical resistance specifications remain non-negotiable, though waterborne variants still fail to match solvent-borne performance in severe exposures.
- Polyurethane:Aliphatic polyurethane dispersions command premium positioning in flexible packaging inks and textile coatings where elasticity and adhesion prove critical.
- Vinyl:Vinyl acetate and vinyl chloride copolymer dispersions serve cost-sensitive architectural primers and paper coatings with moderate durability requirements.
Acrylic retains volume leadership across coating applications; polyurethane holds the steepest expansion curve in packaging and textile segments.
Application:
Coatings absorb the majority of resin volume, yet ink and plastics applications are gaining formulation sophistication as digital printing and polymer compounding requirements tighten.
- Coatings:Architectural, automotive OEM, and industrial maintenance coatings represent the core demand pool. Waterborne basecoat systems in German and US collision repair networks are mandating low-VOC acrylic dispersions, while powder coating growth in Chinese appliance manufacturing drives specialized resin development.
- Inks:Flexographic and gravure packaging inks, plus emerging inkjet formulations, require sub-micron particle size control and colloidal stability. FDA Title 21 compliance for food-contact applications limits qualified resin suppliers in North American flexible packaging.
- Plastics:Masterbatch and compound applications demand thermal stability during extrusion and injection molding cycles.
- Textiles:Pigment printing pastes and coating formulations prioritize soft hand feel and wash durability in apparel and technical fabric applications.
Coatings dominate absolute resin consumption; inks are climbing fastest on digital printing convergence and narrow-web label expansion.
End User:
Automotive and construction procurement patterns diverge on specification stringency, with electronics and healthcare imposing additional compliance layers that filter supplier qualification.
- Automotive:OEM clearcoats and refinishing basecoats drive premium dispersion resin specifications. Tier-1 paint shops in Germany, the United States, and Japan now require 12-month storage stability validation before contract award, concentrating volume with established resin houses possessing archival performance data.
- Construction:Architectural coatings for residential and commercial buildings prioritize cost efficiency and application latitude. High-solids acrylic suppliers serving the DIY channel are accelerating low-temperature film formation R&D following EPA Method 24 revisions.
- Electronics:Display and semiconductor manufacturing applications require ultra-low metal content and precise rheology control.
- Healthcare:Medical device coatings and pharmaceutical packaging impose FDA and EMA biocompatibility standards that extend product development timelines.
Automotive commands the highest specification barriers; healthcare is expanding most quickly on device coating and primary packaging demand.
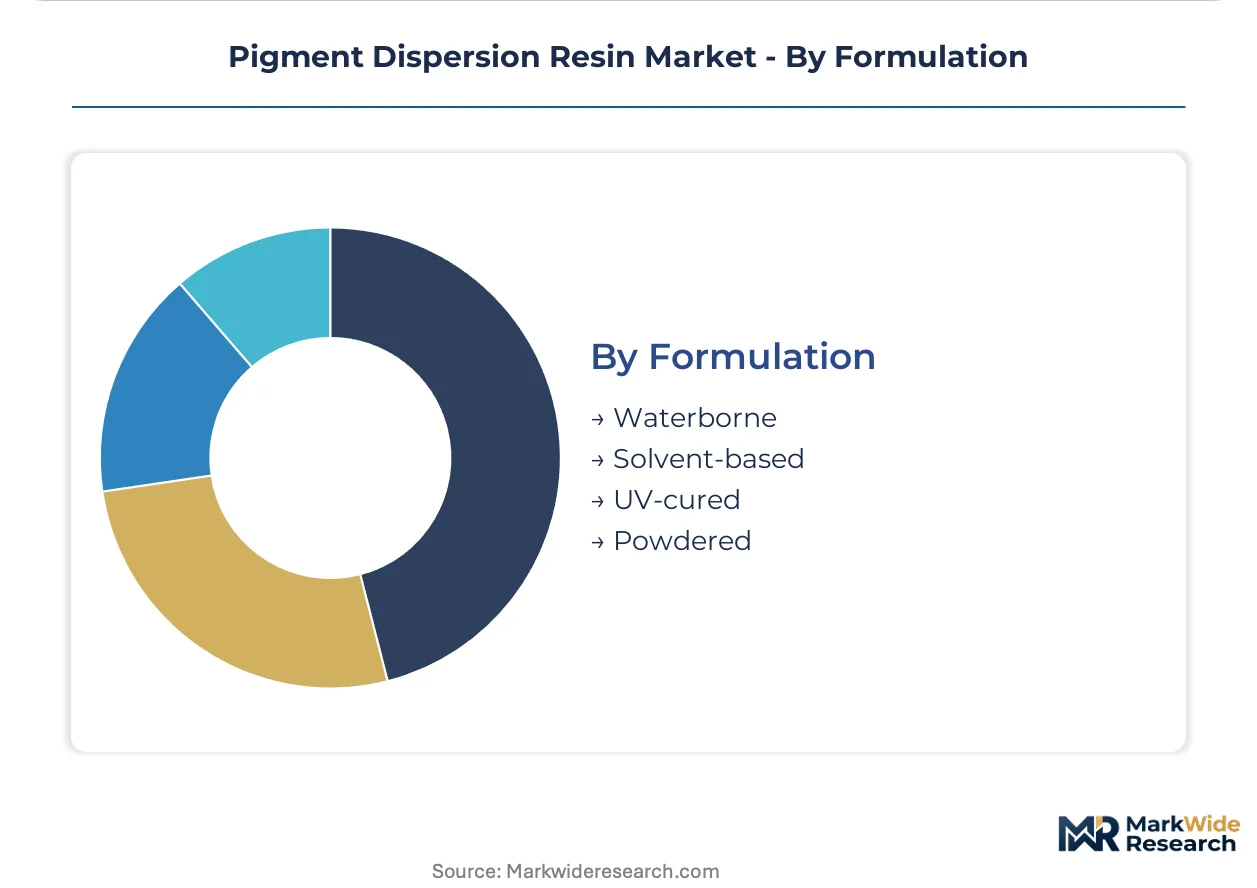
Formulation:
Waterborne systems are displacing solvent-borne alternatives across all major applications, though UV-cured and powder technologies are capturing specific performance niches where instant processing or zero-VOC profiles prove decisive.
- Waterborne:Acrylic and polyurethane dispersions in aqueous media now serve the majority of architectural and automotive refinishing applications. REACH VOC limits and China's MEE enforcement are accelerating retrofit investment, though coalescent reduction remains a technical priority for low-temperature cure performance.
- Solvent-based:Aromatic and aliphatic solvent systems retain share in heavy industrial maintenance and marine coatings. Regulatory pressure from EPA, REACH, and China's emission standards is eroding this position steadily, with margin compression from propylene oxide feedstock volatility compounding challenges.
- UV-cured:Energy-curable pigment dispersions enable instant drying in narrow-web label printing and wood furniture finishing. Italian and German kitchen cabinet manufacturers are converting spray lines to single-component waterborne UV systems, collapsing pot-life constraints.
- Powdered:Solid resin systems for electrostatic application offer zero-VOC profiles and high transfer efficiency in appliance and architectural metal coatings.
Waterborne formulations lead installed capacity; UV-cured alternatives are gaining share fastest on energy savings and instant processing advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH VOC limits anchor European procurement patterns, redirecting coating formulators toward low-solids acrylic dispersions. German automotive OEMs and industrial clusters drive premium resin demand. Chinese capacity expansion reshapes supply dynamics for Asia-Pacific converters.
Germany
Automotive refinishing networks in Stuttgart and Munich mandate waterborne basecoat systems to meet booth emission standards. The EU Green Deal implementation tightens solvent thresholds progressively. BASF SE leverages integrated precursor supply from Ludwigshafen to sustain margin control across automotive pigment dispersions.
United States
Collision repair chains in Michigan and Ohio convert spray lines to waterborne finishes under EPA Method 24 protocol revisions. California and Northeastern states enforce amended VOC calculation rules capturing previously exempt solvents. Sun Chemical anchors North American ink specialization with waterborne formulation expertise.
China
Acrylic and polyurethane dispersion resin capacity expansion serves coatings and plastics converters in Jiangsu and Zhejiang provinces. MEE emission standards enforce environmental compliance costs for solvent-borne capacity retrofits. Yangtze River Delta manufacturing clusters absorb incremental domestic supply for appliance and automotive applications.
India
Domestic coating plants serving Maruti Suzuki and Hyundai Motor India qualify local pigment dispersion resin sources in Haryana and Tamil Nadu. BIS standards govern industrial chemical quality specifications. Pune and Chennai automotive manufacturing corridors concentrate procurement for OEM clearcoat and refinishing applications.
Japan
Display and semiconductor manufacturing applications in Osaka and Nagoya require ultra-low metal content and precise rheology control. METI industrial standards guide chemical product registration and environmental compliance. Tier-1 paint shops require 12-month storage stability validation, concentrating volume with established resin houses possessing archival performance data.
Pigment Dispersion Resin Market Competitive Landscape
Integrated chemical conglomerates and specialized color chemistry houses split the market between scale-driven precursor control and formulation expertise. German and Japanese resin houses dominate premium automotive specifications through archival performance databases. Three archetypes define competitive positioning: petrochemical-integrated suppliers with captive acrylic feedstock, heritage pigment specialists with color chemistry knowledge, and regional converters serving cost-sensitive architectural channels. Dominant competitive moves include backward integration into propylene oxide derivatives and strategic partnerships with automotive OEM coating divisions for specification lock-in.
Within the heritage pigment specialist tier, Heubach GmbH and Sun Chemical occupy positions anchored in color chemistry expertise applied to high-performance dispersions. BASF SE exemplifies the petrochemical-integrated archetype through its Ludwigshafen precursor complex. These three entities represent distinct strategic postures: specialized color knowledge, waterborne formulation depth, and upstream raw material control.
| Leading Market Players |
|---|
| Vibrantz |
| Heubach GmbH |
| BASF SE |
| Sun Chemical |
| Lanxess |
| DIC Corporation |
| Cabot Corporation |
| Penn Color |
| Sudarshan Chemical |
| Others |
Value Network & Pricing Analysis
Ludwigshafen's integrated chemical complex anchors European acrylic dispersion resin supply, translating captive propylene oxide feedstock into downstream pricing leverage against Asian imports. This concentration of precursor control enables German resin houses to defend margins while coating formulators in Stuttgart and Munich face escalating procurement costs from REACH compliance mandates.
Pricing Analysis
Acrylic dispersion resin pricing spreads EUR 180-220 per metric ton between German automotive-grade specifications and Chinese architectural-grade exports. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant food-contact resins from industrial maintenance grades and cost-sensitive vinyl dispersions. Pricing pressure stems from propylene oxide feedstock volatility compressing margins at mid-tier suppliers. DIY coating channels exhibit highest price sensitivity, while automotive OEM clearcoat divisions prioritize storage stability validation over unit cost.
Supply Chain Analysis
BASF SE, DIC Corporation, and Sudarshan Chemical hold concentrated dispersion resin manufacturing capacity across Germany, Japan, and India. Supply chains draw from acrylic acid, epoxy resins, and aliphatic isocyanates as critical inputs. Single-source vulnerability persists in specialized polyurethane dispersion intermediates where Japanese chemical houses dominate technical grades. Distribution runs through regional coating compounders and masterbatch converters before reaching automotive paint shops and flexible packaging ink houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne formulation chemistry disruption is accelerating procurement consolidation as REACH VOC limits and EPA Method 24 revisions simultaneously tighten emission thresholds across European and North American coating channels.
For Market Incumbents: Entrench specification lock-in through 12-month storage stability validation protocols that Tier-1 automotive paint shops now mandate. Deepen captive precursor supply from Ludwigshafen-style integrated complexes to offset propylene oxide price volatility. Prioritize FDA Title 21 clearance investment to capture food-contact ink migration from solvent-borne alternatives.
For New Entrants and Emerging Players: Mid-market waterborne epoxy dispersions for Indian industrial maintenance represent the most penetrable entry point, as BIS standards create qualification barriers lower than REACH or EPA thresholds. Target Haryana and Tamil Nadu automotive coating corridors serving Maruti Suzuki and Hyundai Motor India localization programs. Lead with technical service partnerships rather than price undercutting to overcome archival performance data deficits.
For Investors and Strategic Acquirers: Carve-out targets emerge from European heritage pigment specialists with stranded solvent-borne capacity facing MEE retrofit costs in China. Long-term viability favors waterborne acrylic and UV-curable dispersion platforms over solvent-borne industrial maintenance exposure. Monitor EPA Method 24 enforcement intensity in California and Northeastern states as inflection signal for North American waterborne transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | BASF SE's Ludwigshafen complex secures margin control against Asian feedstock volatility. |
| FDA Title 21 Compliance Investment | Food-contact clearance opens flexible packaging ink applications blocked by migration limits. |
| Long-term Supply Agreement with Automotive OEMs | 12-month storage validation protocols lock in specification-driven procurement concentration. |
| Joint Venture in Yangtze River Delta | Chinese MEE enforcement accelerates domestic waterborne capacity for appliance coatings. |
| Green Manufacturing Transition | EU Green Deal implementation redirects R&D toward low-emission acrylic dispersion systems. |
Research Methodology
A spread of perspectives from coating formulators, resin procurement leads, automotive paint shop engineers, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined structured interviews with technical R&D directors at German and Japanese resin houses alongside distribution channel partners serving architectural and automotive end users. Secondary validation drew from ECHA REACH registration databases, EPA Method 24 protocol amendments, ACC and Cefic chemical trade reports, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down demand aggregation from coating production statistics.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions modeled include chemistry family, formulation type, application specification, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted growth rate projections incorporating automotive production forecasts and coating formulation mix shifts. Industry-specific inputs captured UV-cured inkjet penetration rates in narrow-web label printing and self-crosslinking acrylic adoption in Italian kitchen cabinet manufacturing.
Practitioners should monitor propylene oxide price volatility, MEE enforcement intensity in Jiangsu province, and EPA Method 24 state-level adoption for early signals of forecast revision. Quarterly review of automotive OEM waterborne basecoat mandate timelines and REACH authorization list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global Cosmetic Dyes Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Dyestuff (Black Color) Market
Dyes and Pigments
Global Architectural Paint Oxide Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Acid Orange Market