
 Spay and Neuter Market | 2026-2036
Spay and Neuter Market Size, Share, and Industry Trends Forecast 2026-2036
Spay and Neuter Market Insights
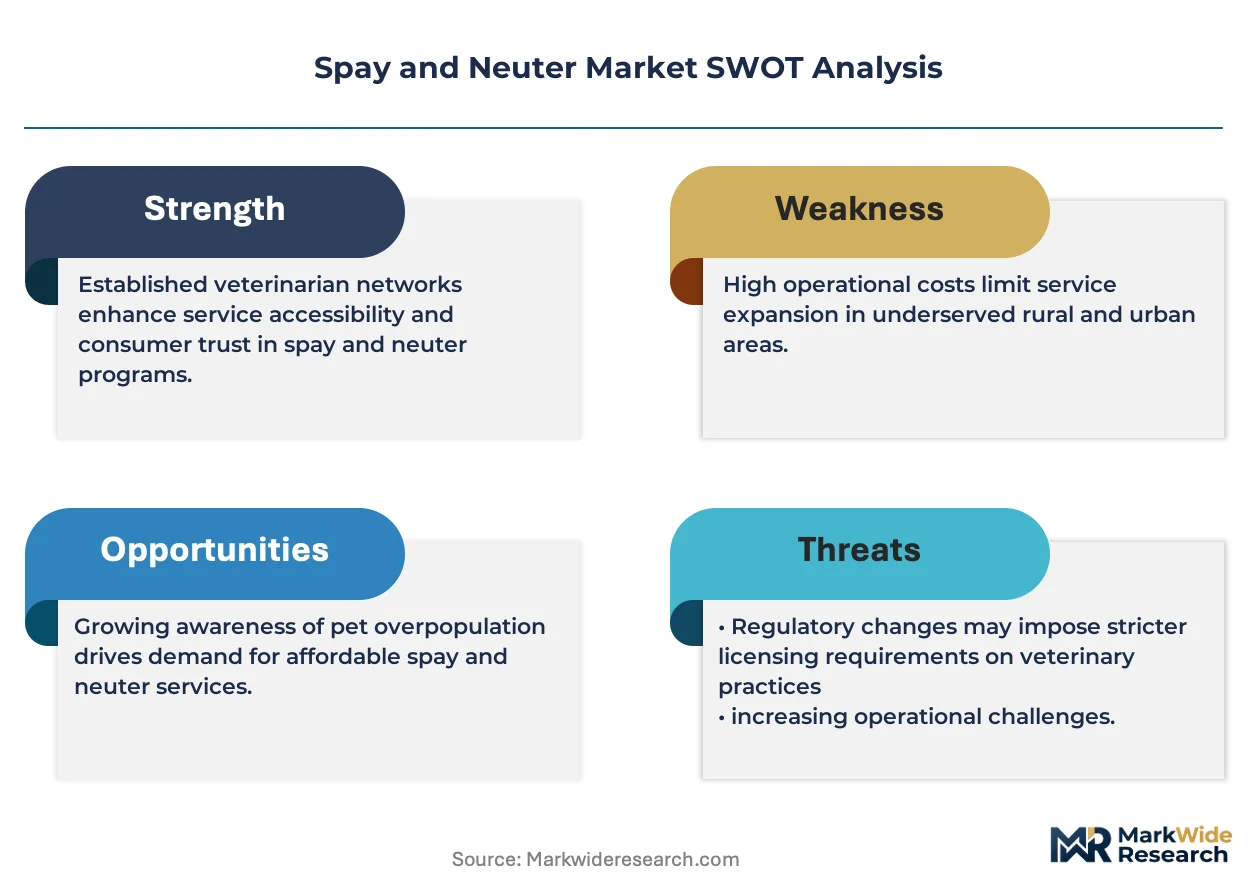
High-volume surgical capacity is bifurcating the competitive landscape between premium full-service hospitals and efficiency-driven sterilization clinics. VCA Animal Hospitals leverages its national network to sustain same-day surgical throughput across metropolitan markets. Banfield Pet Hospital anchors its position through wellness plan bundling that embeds sterilization into recurring revenue streams. Companions Spay & Neuter differentiates through dedicated low-cost facility design that occupies a distinct price-position in underserved communities.
Spay and neuter services encompass surgical sterilization procedures performed on companion animals to prevent reproduction, typically involving ovariohysterectomy or castration under general anesthesia with perioperative pain management protocols. These procedures serve dual commercial purposes: population control for municipal and shelter systems, and preventive health management for private pet owners seeking reduced cancer and behavioral risks. The service type dimension shows spaying and neutering commanding the core revenue pool while vaccination bundling captures incremental margin through pre-surgical health screening requirements. Within procedure type, laparoscopic approaches represent the fastest-expanding technical tier as veterinary groups compete on reduced tissue trauma and faster recovery parameters.
The FDA Center for Veterinary Medicine governs anesthetic drug approvals and surgical device standards, while state veterinary medical boards enforce facility accreditation and practitioner credentialing that directly determines clinic operating authority. Municipal ordinances in jurisdictions such as Los Angeles and Austin mandate sterilization prior to pet licensing, creating enforced demand flows that reshape local market dynamics. Stakeholders must monitor the divergence between shelter-system procurement consolidation and independent clinic resistance to volume-based pricing pressure.
Market Dynamics
Municipal sterilization mandates are compressing surgical capacity into high-volume corridors, forcing facility operators to choose between premium service differentiation and cost-positioned throughput models.
Growth Catalysts
- Los Angeles mandatory sterilization ordinance:Pre-licensing requirements create enforced demand flows that reshape local market dynamics and shelter procurement patterns.
- Laparoscopic surgical platforms:Reduced tissue trauma and faster recovery parameters attract private pet owners seeking premium preventive health management.
- Texas municipal shelter systems:Consolidated contracting across Dallas, Houston, and San Antonio corridors drives economies of scale for regional sterilization networks.
Market Restraints
- Isoflurane and sevoflurane supply concentration:FDA Center for Veterinary Medicine oversight of anesthetic drug approvals creates procurement bottlenecks during manufacturer shortages.
- Veterinary technician labor scarcity:Certified veterinary technician training program capacity constraints limit same-day surgical throughput expansion.
- Fixed facility cost structure:Surgical suite HVAC and anesthesia scavenging system requirements impose capital intensity that resists rapid capacity scaling.
Strategic Opportunities
- Florida underserved rural corridors:Mobile surgical units can capture volume outside metropolitan shelter medicine clusters.
- Telemedicine pre-surgical screening:Remote health assessment protocols reduce in-clinic labor allocation and expand appointment capacity.
- California Medi-Cal pet benefit expansion:State-level subsidized sterilization reimbursement creates predictable revenue streams for safety-net providers.
Industry Challenges
- AVMA accreditation timelines:Veterinary facility certification delays constrain new clinic market entry and capacity expansion.
- Anesthetic waste disposal compliance:OSHA and EPA hazardous pharmaceutical waste regulations impose operational complexity and liability exposure.
- Legacy practice management system integration:Shelter information management software incompatibility with private clinic billing platforms creates data fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spay and Neuter Market |
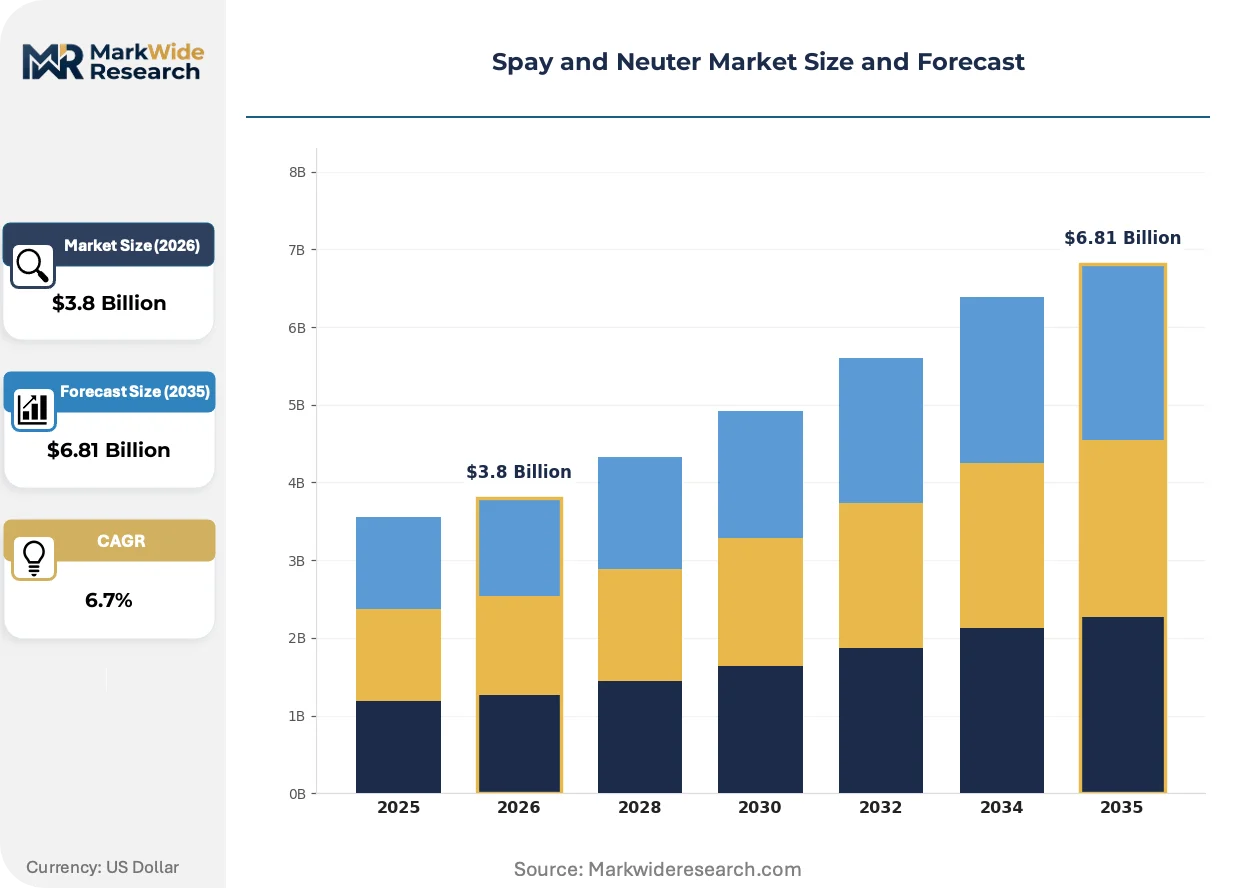
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Spaying, Neutering, Vaccination, Microchipping End User: Pet Owners, Animal Shelters, Veterinary Clinics, Rescue Organizations Procedure Type: Standard Procedure, Laparoscopic Procedure, Post-Operative Care, Emergency Surgery Pricing Model: Flat Fee, Sliding Scale, Package Deal, Donations |
| Companies Covered | VCA Animal Hospitals, Petco Animal Supplies, Companions Spay & Neuter, VetPartners Group Limited, Ethos Veterinary Health, AniCura AB, Veritas Veterinary Partners, Banfield Pet Hospital, ASPCA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spay and Neuter Market Trends and Innovations
Surgical sterilization protocols are fragmenting along technical sophistication lines, with competing facility models pursuing divergent paths toward recovery metrics, cost structures, and patient throughput optimization.
Ultrasonic surgical aspirators are miniaturizing ovarian pedicle dissection procedures in high-volume settings. Shelter medicine specialists in California and Texas corridors are adopting these platforms to compress procedure time without compromising hemostasis. The technology is miniaturizing the physical footprint required for equivalent surgical output, enabling clinic operators to repurpose square footage toward preoperative staging and recovery monitoring.
The FDA Center for Veterinary Medicine's anesthetic drug labeling revisions are tightening perioperative monitoring documentation requirements. Surgical facilities must now maintain continuous physiologic parameter logs that extend liability exposure and malpractice insurance premiums. Small independent operators in Florida and Arizona are responding by consolidating into regional networks that share compliance infrastructure and risk pools.
Pet owners are fragmenting across service delivery channels based on price transparency and appointment velocity. Municipal shelter systems and nonprofit networks are capturing price-sensitive volume through published fee schedules, while premium hospitals defend margin through bundled wellness plans that obscure sterilization line-item costs. Channel preference divergence is most visible in California's coastal metropolitan markets, where same-day scheduling availability drives clinic selection more than brand affiliation.
Spay and Neuter Market Segmentation
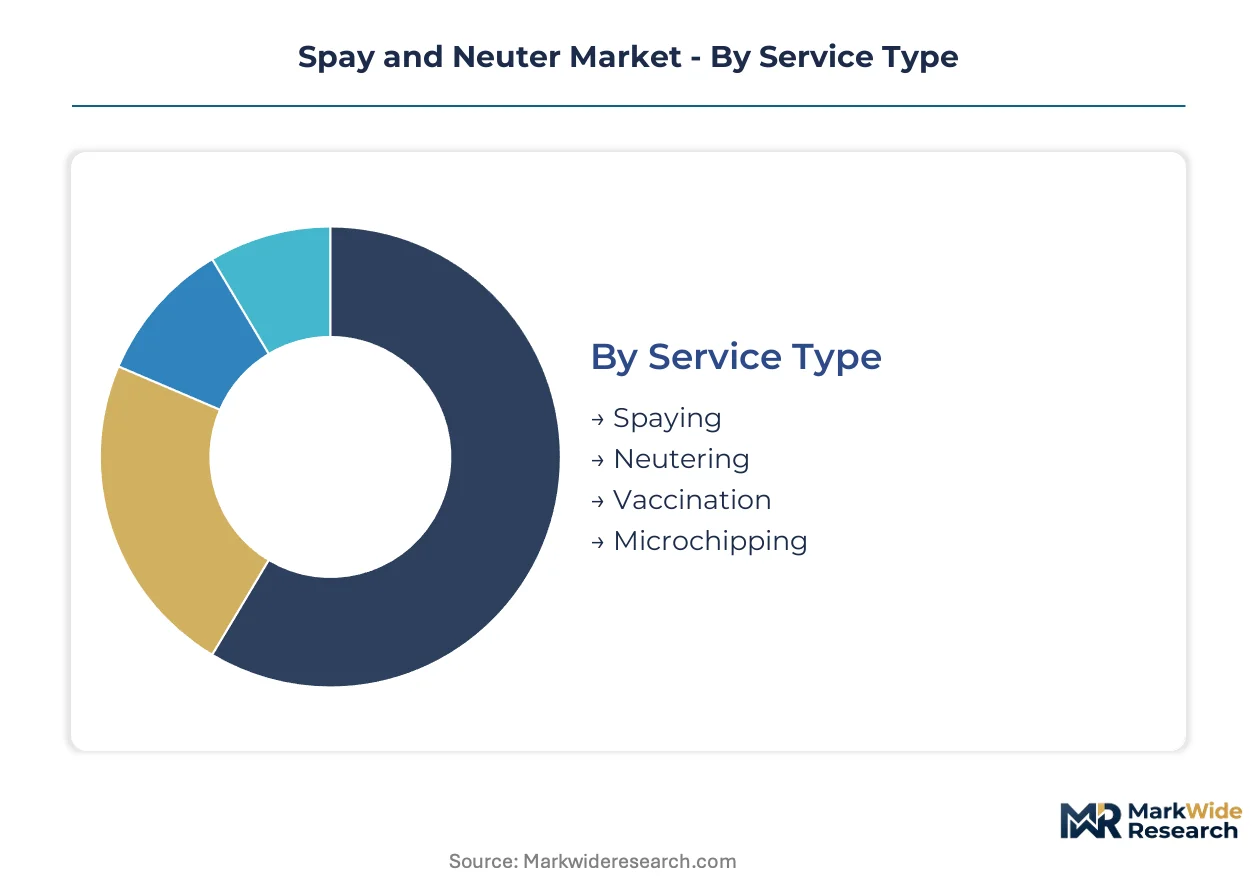
Surgical sterilization markets fragment along service delivery hierarchies that determine pricing power and throughput economics. Each segmentation dimension reveals distinct regulatory exposure, capital intensity requirements, and customer acquisition cost structures that shape competitive positioning.
Service Type:
FDA Center for Veterinary Medicine oversight of anesthetic protocols creates compliance cost differentials between surgical and ancillary service lines.
- Spaying:Ovariohysterectomy procedures under general anesthesia require continuous physiologic monitoring that extends liability exposure and malpractice premiums. Municipal shelter systems in Texas, California, and Florida corridors drive consolidated procurement for high-volume spay capacity.
- Neutering:Castration procedures present shorter anesthesia duration and reduced postoperative complication rates compared to ovariohysterectomy. Private pet owners in California coastal metropolitan markets prioritize same-day scheduling availability for neutering over brand affiliation.
- Vaccination:Pre-surgical health screening requirements capture incremental margin through bundled service delivery.
- Microchipping:Regulatory compliance with ISO 11784/11785 standards for transponder frequency varies by municipal licensing jurisdiction.
Established volume favors spaying; emerging adoption favors microchipping bundling.
End User:
Customer acquisition economics diverge sharply between institutional procurement and individual pet owner segments.
- Pet Owners:Individual consumers fragment across price transparency and appointment velocity preferences. Premium wellness plan bundling obscures sterilization line-item costs for recurring revenue capture.
- Animal Shelters:Municipal systems mandate pre-licensing sterilization that creates enforced demand flows in Los Angeles, Austin, and comparable jurisdictions.
- Veterinary Clinics:Referral networks concentrate surgical capacity into high-volume corridors with economies of scale for regional sterilization networks.
- Rescue Organizations:Nonprofit funding constraints favor sliding-scale pricing models and mobile surgical unit partnerships.
Procurement consolidation favors animal shelters; margin expansion favors pet owners.
Procedure Type:
Technical sophistication tiers separate facilities competing on recovery metrics versus cost-positioned throughput models.
- Standard Procedure:Traditional open surgical approaches dominate municipal contract fulfillment with compressed procedure times and lower capital equipment requirements.
- Laparoscopic Procedure:Minimally invasive platforms reduce tissue trauma and accelerate recovery parameters for premium-positioned private clients. Reduced physical footprint enables repurposed square footage toward preoperative staging.
- Post-Operative Care:Extended monitoring protocols address FDA documentation requirements for continuous physiologic parameter logs.
- Emergency Surgery:Unscheduled capacity demands strain same-day surgical throughput in high-volume shelter medicine clusters.
Cost efficiency favors standard procedures; steepest expansion trajectory favors laparoscopic platforms.
Pricing Model:
Revenue predictability varies with customer payment certainty and reimbursement mechanism stability.
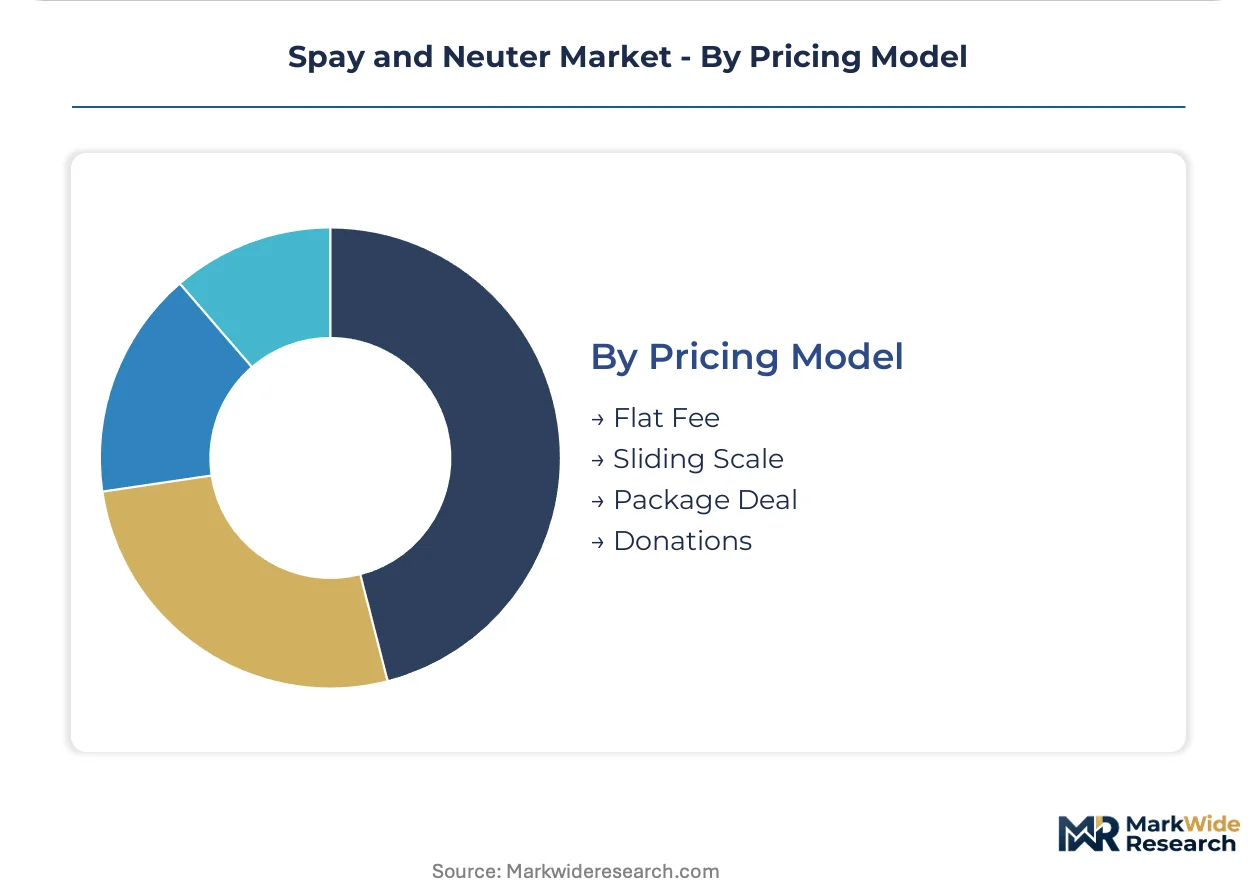
- Flat Fee:Published fee schedules capture price-sensitive volume through transparency in municipal shelter and nonprofit network channels.
- Sliding Scale:Income-adjusted pricing expands access in underserved rural corridors and safety-net provider systems.
- Package Deal:Wellness plan bundling embeds sterilization into recurring revenue streams with obscured line-item economics.
- Donations:Philanthropic funding sustains mobile surgical unit deployment outside metropolitan shelter medicine clusters.
Predictable cash flow favors flat fees; market penetration favors sliding scale models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sterilization service exports from the United States flow primarily to Canada and Mexico under NAFTA successor provisions, while European veterinary groups source laparoscopic platforms from German and Swiss manufacturers.
United States
Municipal shelter systems in Texas, California, and Florida drive consolidated procurement for high-volume sterilization capacity. The FDA Center for Veterinary Medicine governs anesthetic drug approvals and surgical device standards nationwide. Los Angeles enforces mandatory pre-licensing sterilization ordinances that reshape local market dynamics and shelter procurement patterns.
Canada
Provincial veterinary medical associations in Ontario and Quebec enforce facility accreditation that determines clinic operating authority. Health Canada regulates veterinary pharmaceutical imports through the Veterinary Drugs Directorate. Toronto and Vancouver metropolitan corridors concentrate mobile surgical unit deployment for underserved rural access expansion.
Germany
Specialized veterinary equipment manufacturers in Baden-Württemberg supply laparoscopic platforms to sterilization clinics across Europe. The German Federal Ministry of Food and Agriculture oversees animal welfare standards that mandate perioperative pain management protocols. Munich and Stuttgart anchor precision surgical instrument production clusters serving export markets.
United Kingdom
Royal College of Veterinary Surgeons credentialing requirements shape practitioner mobility and clinic staffing economics. The Veterinary Medicines Directorate regulates anesthetic drug licensing and importation procedures. Greater London and Southeast England concentrate premium wellness plan bundling that embeds sterilization into recurring revenue streams.
Australia
State-based animal welfare legislation in New South Wales and Victoria mandates desexing prior to pet registration in designated jurisdictions. The Australian Pesticides and Veterinary Medicines Authority governs pharmaceutical approvals for perioperative protocols. Sydney and Melbourne metropolitan markets fragment between municipal shelter contracts and private premium service differentiation.
Spay and Neuter Market Competitive Landscape
Listed leaders compete with private specialists across facility scale and service model dimensions. The vendor base clusters around three structural tiers: national hospital networks with same-day surgical throughput, dedicated sterilization clinics with efficiency-driven cost positioning, and nonprofit systems with subsidized access mandates. Strategic archetypes include premium full-service hospitals, low-cost dedicated facilities, and mobile surgical unit operators. Competitive moves concentrate on wellness plan bundling for recurring revenue capture and regional network consolidation for compliance infrastructure sharing.
Within the national network tier, VCA Animal Hospitals and Banfield Pet Hospital exemplify scale-driven throughput models across metropolitan markets. Companions Spay & Neuter occupies a distinct position among dedicated low-cost facility operators targeting underserved communities. Ethos Veterinary Health and AniCura AB represent European-origin groups competing on technical sophistication and laparoscopic platform deployment.
| Leading Market Players |
|---|
| VCA Animal Hospitals |
| Petco Animal Supplies |
| Companions Spay & Neuter |
| VetPartners Group Limited |
| Ethos Veterinary Health |
| AniCura AB |
| Veritas Veterinary Partners |
| Banfield Pet Hospital |
| ASPCA |
| Others |
Pricing and Supply Chain Analysis
High-volume surgical throughput in Texas, California, and Florida corridors compresses per-procedure fixed costs and establishes price floors that independent operators struggle to match. Municipal shelter procurement consolidation leverages this scale to extract volume discounts, while premium laparoscopic platforms command markups through reduced recovery time value propositions.
Pricing Analysis
Standard open surgical approaches, laparoscopic platforms, and emerging ultrasonic aspirator technologies stratify across distinct price tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and facility accreditation status. Cost compression in the standard tier intensifies because municipal contract fulfillment prioritizes throughput over margin. Rescue organizations and price-sensitive pet owners in rural Florida corridors exhibit highest price sensitivity; wellness-plan subscribers in California coastal markets show lowest sensitivity due to obscured line-item economics.
Supply Chain Analysis
Strategic stockpiling of isoflurane and sevoflurane dominates inventory strategy given FDA Center for Veterinary Medicine oversight and manufacturer concentration vulnerability. Anesthetic drug supply concentrates in United States, Germany, and India pharmaceutical manufacturing corridors. Surgical instrument sourcing draws from Baden-Württemberg precision clusters and Chinese stainless-steel component foundries. Single-source vulnerability in inhalant anesthetic production creates exposure during manufacturing disruptions. Distribution runs through regional veterinary distributor networks with direct-to-clinic fulfillment for high-volume shelter contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal sterilization mandate expansion across Los Angeles, Austin, and comparable jurisdictions signals early-cycle penetration tailwinds for procedural volume. Laparoscopic platform adoption and telemedicine pre-surgical screening represent underexploited expansion vectors.
For Market Incumbents: Secure same-day surgical throughput capacity in high-volume Texas and California corridors through certified veterinary technician pipeline investments. Lock in multi-year municipal shelter contracts before procurement consolidation accelerates. Vertical integration into mobile surgical unit deployment captures Florida rural volume outside metropolitan clusters. For New Entrants and Emerging Players: Lead with telemedicine-enabled pre-surgical screening protocols that reduce in-clinic labor allocation and expand appointment velocity. Target Medi-Cal pet benefit expansion corridors in California for predictable reimbursement revenue. Partner with existing shelter information management software providers to resolve legacy billing platform fragmentation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wellness-plan bundling operators that embed sterilization into subscription structures. Five-to-ten year viability favors regional network consolidators sharing compliance infrastructure and malpractice risk pools. Watch FDA anesthetic drug labeling revision timelines as inflection indicators for liability exposure and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Laparoscopic Platform Deployment | Reduced tissue trauma accelerates recovery metrics for premium-positioned California and Texas facilities. |
| Telemedicine Pre-Surgical Screening | Remote health assessment protocols expand appointment capacity without proportional labor expansion. |
| Municipal Contract Consolidation | Multi-year shelter procurement agreements lock in volume against emerging low-cost competitors. |
| Mobile Surgical Unit Expansion | Underserved Florida rural corridors capture volume outside fixed-facility metropolitan clusters. |
| Wellness Plan Bundling | Obscured sterilization line-item economics embed procedures into recurring revenue streams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine filings, state veterinary medical board accreditation records, and municipal shelter procurement databases. Primary interviews engaged veterinary practice owners, shelter medicine directors, certified veterinary technician program administrators, and anesthetic drug procurement managers. Secondary validation incorporated AVMA workforce studies, EPA hazardous pharmaceutical waste compliance documentation, and trade data on surgical instrument imports. Bottom-up clinic capacity modeling triangulates against top-down municipal expenditure tracking.
Segmentation dimensions modeled span service type, procedure technology tier, end-user procurement channel, and pricing mechanism across the projection horizon. CAGRs derive from surgical volume trajectory analysis calibrated to municipal mandate adoption curves and pet ownership demographic shifts. Forecast inputs incorporate certified veterinary technician training pipeline capacity and laparoscopic platform penetration rates by metropolitan market.
The analysis sits within stated boundaries; outcomes outside sustained municipal funding commitment and anesthetic drug supply stability would require recalibration. Forecasts assume continued FDA oversight consistency and state-level facility accreditation pathway accessibility. Revision becomes warranted when veterinary technician labor scarcity crosses thresholds that constrain same-day throughput expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Veterinary Parasiticides Market
Veterinary
Otc Pet Medication Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
CBD Pet Market
Veterinary
Companion Animal Drugs Market
Veterinary
Veterinary and Animal Healthcare Logistics Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Veterinary Endodontics Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Canine Arthritis Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Vet Software Market
Veterinary
Milking Salve Market