
 North America Immune Health Supplements Market | 2026-2036
North America Immune Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
North America Immune Health Supplements Market Analytics
Market Context
DSHEA enforcement modernization is broadening the cost-of-entry calculus for new immune health supplement entrants, forcing capital allocation toward quality systems and substantiation infrastructure. Pfizer Inc. leverages its pharmaceutical-grade manufacturing pedigree to anchor credibility in the clinical nutrition crossover space. NOW Foods sustains competitive intensity through vertical control over raw material sourcing and in-house analytical testing capabilities. Amway Corporation differentiates via its direct-selling network, which occupies a distinct channel position relative to conventional retail-dependent rivals.
Technical Definition and Structural Segments
Immune health supplements encompass orally administered products containing bioactive compounds—vitamins, probiotic cultures, trace minerals, or standardized botanical extracts—formulated to modulate or support immunological function through documented physiological pathways. These products typically deliver defined quantities of active ingredients via tablets, capsules, powders, or liquid preparations, with stability and bioavailability parameters governed by compendial standards. Vitamins and probiotics command the largest revenue pools, reflecting established consumer recognition and repeat purchase behavior, while herbal extracts represent the fastest-expanding category as botanical substantiation frameworks mature. Tablets and capsules dominate formulation type due to dosing precision and shelf stability, though powders gain traction among athletes and functional fitness consumers seeking customizable intake protocols.
Regulatory Frame and Forward Outlook
The FDA, FTC, and Health Canada jointly shape the North American regulatory perimeter through overlapping jurisdiction over product safety claims, advertising substantiation, and good manufacturing practice compliance. Health Canada's Natural and Non-prescription Health Products Directorate imposes distinct pre-market notification requirements that create asymmetric market access conditions relative to the United States. Stakeholders must monitor evolving enforcement priorities around structure-function claims and emerging ingredient categories to anticipate compliance cost trajectories and portfolio reconfiguration needs.
Market Dynamics
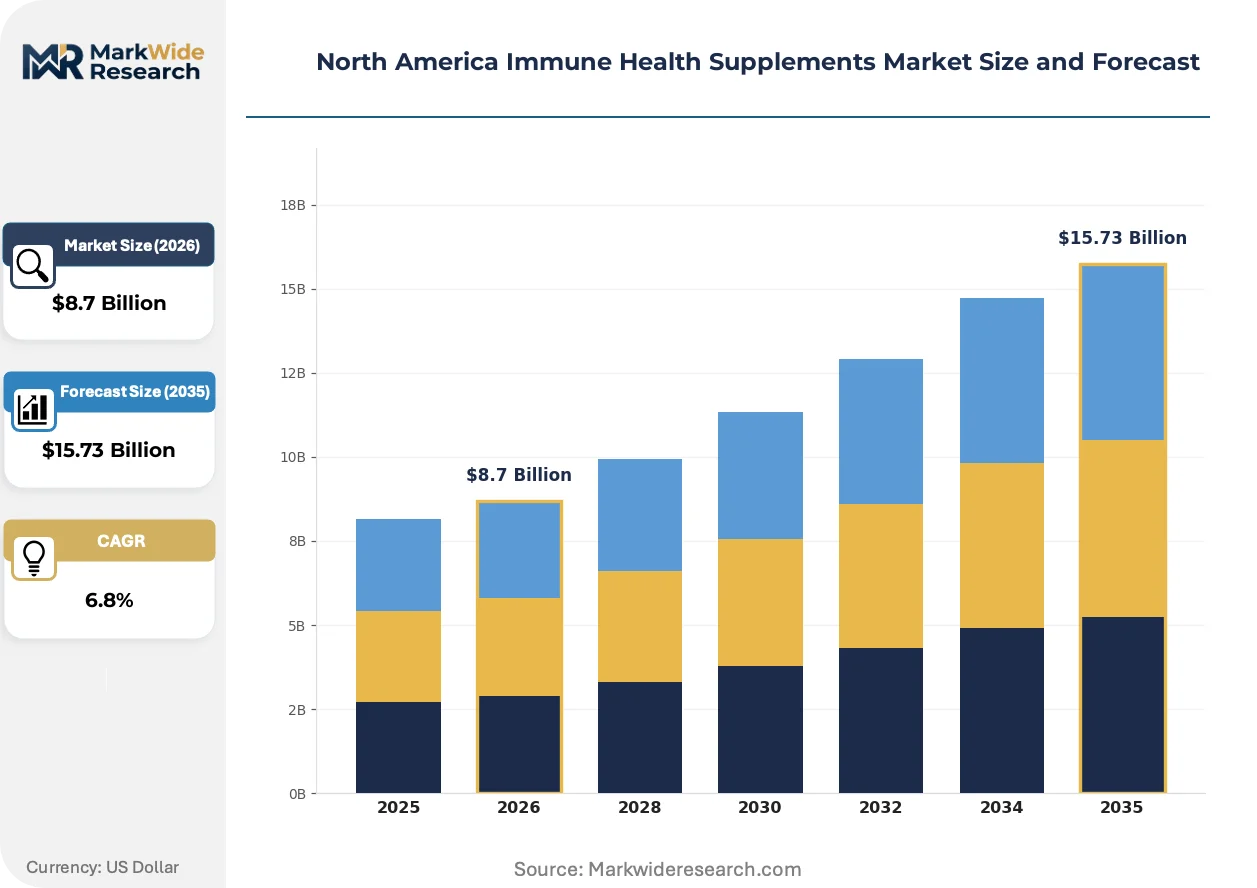
The FDA's DSHEA enforcement modernization is compressing operating margins across the North America immune health supplements value chain by mandating capital-intensive quality infrastructure upgrades and documented substantiation protocols for all structure-function claims.
Growth Catalysts
- Aging Demographics:Senior populations across the United States and Canada are prioritizing preventive immunological wellness, creating sustained demand pull for clinically positioned formulations.
- FTC Advertising Substantiation:Stricter evidentiary requirements for health claims are paradoxically advantaging manufacturers with pre-existing clinical trial capabilities and pharmacovigilance systems.
- Microbiome Science Maturation:Advances in strain-specific probiotic research are expanding permissible claim language and opening formulation differentiation pathways previously unavailable to botanical competitors.
Market Restraints
- Raw Material Concentration:Vitamin C and zinc precursor supply chains concentrate in Chinese manufacturing zones, exposing North American formulators to geopolitical tariff volatility and logistics disruption.
- Health Canada Pre-Market Notification:The Natural and Non-prescription Health Products Directorate's site licensing and product registration requirements create 12-18 month market access delays relative to the United States.
- Pharmaceutical Substitution:Prescription immunomodulatory therapies for high-risk populations reduce addressable market scope for supplement interventions in clinically managed patient segments.
Strategic Opportunities
- Canadian Regulatory Arbitrage:Manufacturers with existing Health Canada site licenses can leverage mutual recognition pathways to access European EFSA-regulated markets with reduced technical barriers.
- Sports Nutrition Convergence:Athlete and functional fitness consumers are adopting immune maintenance protocols as training load management tools, opening powder and ready-to-drink distribution through specialty retail.
- IRA Preventive Health Incentives:Medicare Advantage plan design innovations are creating reimbursement-adjacent positioning opportunities for clinically substantiated immune support products in senior care settings.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Rapidly evolving FDA guidance on New Dietary Ingredient notifications requires specialized expertise in botanical constituent identification and method validation that outpaces current workforce supply.
- Legacy ERP Integration:Batch record digitization and electronic Common Technical Document submission mandates are forcing mid-tier manufacturers to reconfigure quality management systems with substantial implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Immune Health Supplements Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Probiotics, Minerals, Herbal Extracts Formulation Type: Tablets, Capsules, Powders, Liquids End User: Adults, Seniors, Children, Athletes Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Pfizer Inc., Bayer AG, Herbalife Nutrition Inc., Amway Corporation, Nestle SA, NOW Foods, Nature's Bounty Co., GNC Holdings Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Immune Health Supplements Market Evolving Landscape
Biotechnology-enabled ingredient characterization and direct-to-consumer channel proliferation are fundamentally restructuring how immune health products reach end-users and justify premium positioning through demonstrable bioactivity.
Next-generation sequencing and metabolomic profiling are absorbing substantial R&D investment across leading probiotic developers. Senior nutrition and athletic recovery segments are adopting strain-specific formulations at accelerating velocities. This technological shift is absorbing market share from commodity multivitamin offerings by enabling personalized microbiome-matched product recommendations.
The FDA's 2023 updated guidance on enforcement discretion for certain NDI notifications is compressing innovation cycle timelines for established manufacturers with existing master files. Dietary supplement firms with pharmaceutical heritage are capturing disproportionate benefit from this regulatory clarity. Probiotic and postbiotic categories within the United States are responding fastest through accelerated strain commercialization pipelines.
Subscription-based replenishment models are displacing traditional retail replenishment cycles across immune health categories. Direct-to-consumer platforms and pharmacy-adjacent telehealth services are capturing patient acquisition previously routed through mass retail. This behavioral shift concentrates most visibly in United States metropolitan corridors with dense digital health infrastructure and same-day delivery logistics coverage.
North America Immune Health Supplements Market Segmentation
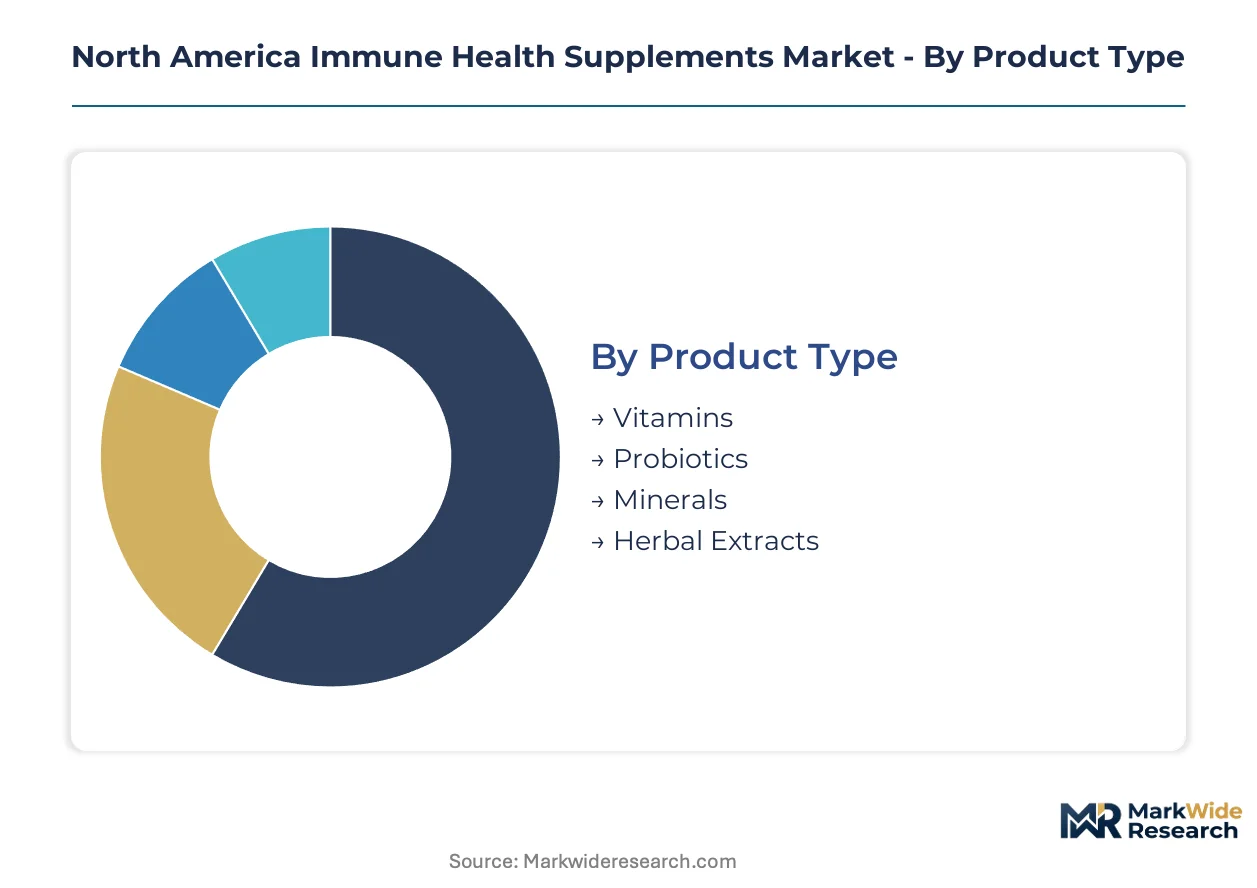
Immune health supplement manufacturers face divergent compliance burdens across product categories. FDA DSHEA enforcement modernization and Health Canada's Natural and Non-prescription Health Products Directorate create asymmetric entry costs that reshape competitive positioning within each segment tier.
Product Type:
FDA New Dietary Ingredient notifications and Health Canada site licensing requirements concentrate most heavily on botanical and microbial ingredients, while vitamin and mineral categories leverage grandfathered status under compendial standards.
- Vitamins:Ascorbic acid, cholecalciferol, and tocopherol formulations dominate retail shelf space through established USP verification pathways. Senior consumers in the United States and Canada drive repeat purchase behavior for vitamin C and D combinations positioned for respiratory defense.
- Probiotics:Live microbial cultures require strain-specific safety documentation and refrigerated supply chain infrastructure. Lactobacillus and Bifidobacterium species command premium positioning in the United States through direct-to-consumer subscription models targeting gut-immune axis science.
- Minerals:Zinc picolinate and selenium yeast formulations leverage elemental purity certifications from USP and NSF International. Athletes and fitness consumers in metropolitan United States corridors favor mineral complexes for exercise-induced immune suppression protocols.
- Herbal Extracts:Echinacea, elderberry, and astragalus preparations face elevated FDA scrutiny on structure-function claims. Health Canada's pre-market notification requirements extend lead times for Canadian commercialization relative to United States market entry.
Leading the category by volume: Vitamins. Growing fastest: Herbal Extracts.
Formulation Type:
Cost tier stratification separates precision-dosed pharmaceutical-grade formats from commodity bulk preparations, with manufacturing complexity and stability requirements determining margin profiles across the four format classes.
- Tablets:Compressed solid dosage forms with defined disintegration times per USP standards enable high-speed production and extended shelf stability. United States pharmacy networks and mass retail channels favor tablets for senior adherence programs and Medicare Advantage plan integrations.
- Capsules:Gelatin and hypromelshell encapsulation protects acid-sensitive probiotics and botanical extracts from gastric degradation. Direct-to-consumer platforms in the United States metropolitan markets position capsules for personalized subscription protocols and travel convenience.
- Powders:Bulk active ingredient blends offer dose customization for athletes and functional fitness consumers. Specialty retail and sports nutrition channels across the United States and Canada capture this segment through flavor-masking innovations and shaker-bottle compatibility.
- Liquids:Aqueous and oil-based suspensions address pediatric and geriatric swallowing difficulties. Health Canada imposes additional preservative efficacy testing that narrows formulation flexibility relative to United States regulatory pathways.
Tablets and Capsules together anchor volume leadership. Powders gain share fastest through sports nutrition convergence.
End User:
Customer type determines channel access, pricing tolerance, and clinical substantiation requirements, with senior and athlete segments commanding premium positioning through outcome-linked value propositions.
- Adults:Working-age consumers aged 18-64 represent the broadest addressable base, with demand concentrating in preventive maintenance rather than acute intervention. United States employer wellness programs and pharmacy loyalty schemes capture this cohort through seasonal promotion cycles.
- Seniors:Adults 65+ prioritize immunosenescence countermeasures and polypharmacy-conscious formulations. Medicare Advantage plan design innovations in the United States create reimbursement-adjacent positioning for clinically substantiated products in senior care settings.
- Children:Pediatric formulations require palatability engineering and weight-calibrated dosing that elevates manufacturing complexity. Health Canada's Natural and Non-prescription Health Products Directorate imposes stricter safety margins for pediatric indications than FDA structure-function frameworks.
- Athletes:Competitive and recreational athletes adopt immune maintenance as training load management infrastructure. United States specialty retail and sports nutrition e-commerce platforms serve this segment through NSF Certified for Sport and Informed Sport verification programs.
Seniors expand most quickly as aging demographics reshape North American demand. Athletes sustain premium pricing power through performance-linked positioning.
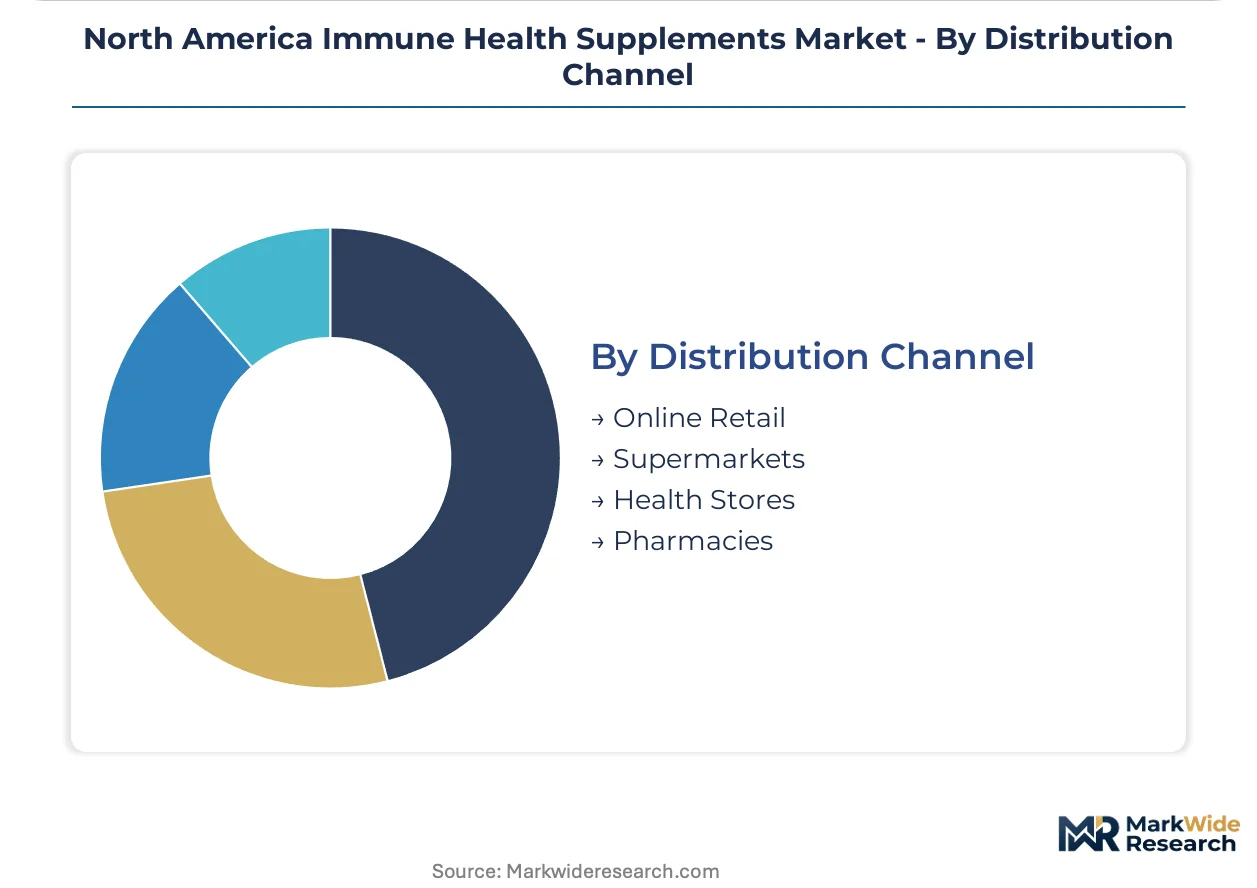
Distribution Channel:
Geography of fulfillment infrastructure determines delivery velocity and customer acquisition economics, with digital-native channels displacing traditional retail replenishment cycles across immune health categories.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription-based replenishment with same-day delivery in dense United States metropolitan corridors. Customer data capture supports personalized microbiome-matched product recommendations.
- Supermarkets:Mass retail chains depend on high-velocity SKUs and promotional slotting fees that favor established vitamin and mineral brands. United States grocery consolidation limits shelf access for emerging probiotic and herbal extract entrants.
- Health Stores:Specialty retailers with trained staff provide education-intensive selling environments for complex botanical and probiotic formulations. Canadian health store networks navigate Health Canada advertising restrictions that constrain claim language relative to United States counterparts.
- Pharmacies:Drugstore chains and independent pharmacies leverage pharmacist credibility for clinically positioned immune support products. United States pharmacy-adjacent telehealth services capture patient acquisition previously routed through mass retail channels.
Online Retail leads volume growth trajectory. Pharmacies retain margin leadership through professional channel positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers generate the dominant share of regional demand for immune health supplements, with direct-to-consumer channels and pharmacy networks commanding the deepest market penetration across North America.
United States
Senior populations and employer wellness programs drive sustained demand pull for preventive immunological formulations. FDA DSHEA enforcement modernization mandates capital-intensive quality infrastructure upgrades across the value chain. Metropolitan corridors with dense digital health infrastructure concentrate subscription-based replenishment model adoption.
Canada
Aging demographics and polypharmacy-conscious seniors prioritize clinically substantiated immune support products. Health Canada's Natural and Non-prescription Health Products Directorate imposes 12-18 month site licensing delays relative to United States market entry. Ontario and Quebec health store networks navigate advertising restrictions that constrain claim language.
Mexico
Urban middle-class consumers in Mexico City and Guadalajara metro areas adopt preventive wellness protocols. COFEPRIS regulatory alignment with FDA standards accelerates cross-border product registration for established North American manufacturers. Northern border states concentrate distribution infrastructure serving pharmacy-adjacent retail channels.
North America Immune Health Supplements Market Competitive Landscape
United States producers anchor one tier; Canadian and European specialists hold distinct positions through regulatory arbitrage and manufacturing pedigree. The market structure reflects moderate consolidation among pharmaceutical heritage manufacturers alongside fragmented botanical and probiotic specialists. Three archetypes dominate: pharmaceutical-grade clinical nutrition crossovers, vertically integrated raw material controllers, and direct-selling network operators. Competitive intensity concentrates on M&A activity for microbiome science capabilities and strategic partnerships with telehealth platforms.
Within the pharmaceutical heritage tier, Pfizer Inc. and Abbott Laboratories exemplify clinical credibility through manufacturing standards drawn from prescription drug operations. NOW Foods occupies a position among vertically integrated specialists with captive analytical testing and raw material sourcing infrastructure. Amway Corporation anchors the direct-selling archetype through network distribution distinct from retail-dependent rivals.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Herbalife Nutrition Inc. |
| Amway Corporation |
| Nestle SA |
| NOW Foods |
| Nature's Bounty Co. |
| GNC Holdings Inc. |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap manufacturers with multi-generational botanical sourcing relationships anchor supply-side discipline across the North America immune health supplements value chain, translating captive raw material access into pricing power that resists commoditization pressures from contract-manufacturing competitors.
Pricing Analysis
Premium positioning for expedited Health Canada site licensing and discounted spot inventory for unregistered botanical lots structure transactional dynamics across the North America immune health supplements market. Subscription-based replenishment models command price premiums through direct-to-consumer data capture, while pharmaceutical-grade manufacturers differentiate via USP verification and FDA cGMP compliance tiers. Cost compression in commodity vitamin categories intensifies as Chinese precursor oversupply feeds spot market liquidity. Employer wellness programs demonstrate lowest price sensitivity through budgeted preventive health allocations, whereas mass retail consumers in United States grocery channels exhibit acute elasticity to promotional cycles.
Supply Chain Analysis
Single-source vulnerability sits with Chinese ascorbic acid and zinc precursor manufacturers, where concentration in Zhejiang and Shandong provinces exposes North American formulators to tariff volatility and logistics disruption. Lactobacillus and Bifidobacterium strain banks draw from Danish and Japanese culture collections, while gelatin capsule shells hinge on bovine hide supply from Argentina and Brazil. Regulatory restriction risk concentrates in FDA New Dietary Ingredient notification backlogs and Health Canada pre-market licensing delays. Distribution runs through refrigerated logistics networks for probiotic cultures and ambient pharmacy-adjacent channels for shelf-stable vitamin and mineral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained strain development capacity and analytical chemistry talent scarcity prop pricing power for manufacturers with existing master files and documented substantiation protocols across the North America immune health supplements market.
For Market Incumbents: Acquire microbiome science capabilities through specialist laboratories with strain-specific safety documentation and metabolomic profiling infrastructure. Consolidate backward integration into elderberry and echinacea cultivation regions to secure botanical supply against FDA enforcement volatility. Defensive positioning requires preemptive Health Canada site licensing to capture mutual recognition pathways into EFSA-regulated European markets. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting United States metropolitan corridors with dense digital health infrastructure and same-day delivery logistics coverage. White-space opportunity concentrates in pediatric liquid formulations with palatability engineering and weight-calibrated dosing, where Health Canada's stricter safety margins deter incumbent expansion. Athlete-focused powder formats with NSF Certified for Sport verification offer penetrable entry through specialty retail bypassing mass retail slotting fee barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor pharmaceutical heritage manufacturers with FDA cGMP infrastructure and existing pharmacovigilance systems in United States manufacturing corridors. Long-term viability across the 5-10 year horizon rests on convergence between preventive immune support and Medicare Advantage reimbursement-adjacent positioning. Monitor FDA enforcement discretion updates on NDI notifications as the inflection indicator for innovation cycle compression benefiting established players with existing master files.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Site Licensing Expansion | Unlocks mutual recognition pathways into EFSA-regulated European markets with reduced technical barriers. |
| Strain-Specific Probiotic Commercialization | Captures premium positioning through microbiome-matched product recommendations enabled by next-generation sequencing. |
| Direct-to-Consumer Platform Development | Displaces traditional retail replenishment cycles through subscription-based replenishment in United States metropolitan corridors. |
| Pharmaceutical-Grade Manufacturing Certification | Leverages FDA cGMP compliance to anchor credibility in clinical nutrition crossover segments. |
| Telehealth Platform Partnership | Captures patient acquisition previously routed through mass retail channels via pharmacy-adjacent digital health services. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North America immune health supplements market analysis, supplemented by primary interviews with quality assurance directors at contract manufacturers, regulatory affairs leads at supplement brands, procurement managers at pharmacy chains, and microbiome research scientists at probiotic developers. FDA warning letters, Health Canada site licensing databases, and United States customs import records provided triangulation against bottom-up manufacturer capacity estimates and top-down retail audit data from Nielsen and Circana.
Data-stream reconciliation across manufacturer shipment records, retail point-of-sale systems, and direct-to-consumer platform analytics informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, formulation format, end-user demographic, and distribution channel, with additional granularity on regulatory pathway clusters distinguishing DSHEA grandfathered ingredients from New Dietary Ingredient notifications. CAGRs were derived from logistic growth curve fitting constrained by aging demographic projections and preventive health expenditure elasticity estimates.
Regulatory enforcement priority shifts, raw material tariff volatility, and microbiome science validation setbacks are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on Health Canada licensing timelines, FDA NDI review throughput, and strain-specific probiotic claim substantiation progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Brazil Whey Protein Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
North America Collagen Supplements Market