
 Asia-Pacific Dietary Supplement Market | 2026-2036
Asia-Pacific Dietary Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dietary Supplement Market Outlook
Premium-grade formulation certification is bifurcating the competitive landscape across the Asia-Pacific Dietary Supplement Market. Abbott Laboratories leverages its pharmaceutical heritage to anchor clinical-grade positioning in therapeutic nutrition segments. Herbalife Nutrition Ltd. sustains direct-selling channel control across Southeast Asian markets. Amway Corporation dominates multi-level distribution networks in China and India through localized product portfolios.
Dietary supplements encompass concentrated sources of vitamins, minerals, herbal extracts, and proteins manufactured through spray-drying, microencapsulation, or cold-pressing processes to deliver measurable physiological benefits beyond basic nutrition. Vitamin and protein segments lead volume flows due to established consumer familiarity and gym culture proliferation across metropolitan centers. Online retail channels capture the fastest expansion trajectory as pharmacy apps and direct-to-consumer platforms reshape purchase behavior in South Korea and Australia.
China's SAMR enforces stricter health-food registration and dual-language labeling mandates that elevate compliance costs for imported formulations. Australia's TGA maintains therapeutic goods standards that restrict certain herbal concentration thresholds. India's FSSAI mandates ingredient disclosure protocols that filter out substandard entrants. Stakeholders must monitor regulatory divergence between national frameworks when designing cross-border product portfolios and manufacturing location strategies.
Market Dynamics
India's FSSAI tightening label-claim verification is elevating compliance costs across the Asia-Pacific Dietary Supplement Market. This regulatory pressure is forcing reformulation investments and third-party certification upgrades among both domestic and imported brands.
Growth Catalysts
- Urban aging demographics:China's tier-one cities host expanding populations of health-conscious professionals over age 45 seeking preventive nutrition solutions.
- SAMR registration streamlining:China's dual-language labeling mandates, while burdensome, are creating clearer pathways for compliant imported formulations to access premium retail channels.
- Spray-drying equipment upgrades:Vietnamese and Indonesian contract manufacturers are deploying advanced drying technologies to improve protein powder solubility and shelf stability.
Market Restraints
- Raw material concentration:Marine-derived omega-3 supply concentrates among Norwegian and Peruvian fisheries, exposing Asia-Pacific formulators to catch-quota volatility and currency fluctuation.
- Herbal concentration thresholds:Australia's TGA maintains strict limits on kava and comfrey alkaloid content that block certain traditional Chinese medicine formulations from therapeutic goods registration.
- Substitution pressure from functional foods:Fortified beverages and protein-enriched snacks in South Korea and Japan are capturing occasions previously served by capsule and tablet supplements.
Strategic Opportunities
- Vietnam's underpenetrated provinces:Outside Ho Chi Minh City and Hanoi, dietary supplement penetration remains below 15% of urban household spend, creating whitespace for pharmacy chain expansion.
- Direct-to-consumer platform convergence:South Korean telehealth apps are integrating supplement subscription workflows with diagnostic biomarker tracking, enabling personalized regimen adherence.
- PLI scheme tailwinds:India's production-linked incentive schemes for pharmaceutical intermediates are reducing excipient costs for domestic capsule and softgel manufacturers.
Industry Challenges
- Formulation scientist scarcity:Southeast Asian markets face acute shortages of professionals skilled in microencapsulation of heat-sensitive probiotics, slowing new product development cycles.
- Cross-border e-commerce compliance:Australia's TGA parallel import restrictions and China's cross-border e-commerce positive list create fragmented fulfillment requirements that complicate regional inventory pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dietary Supplement Market |
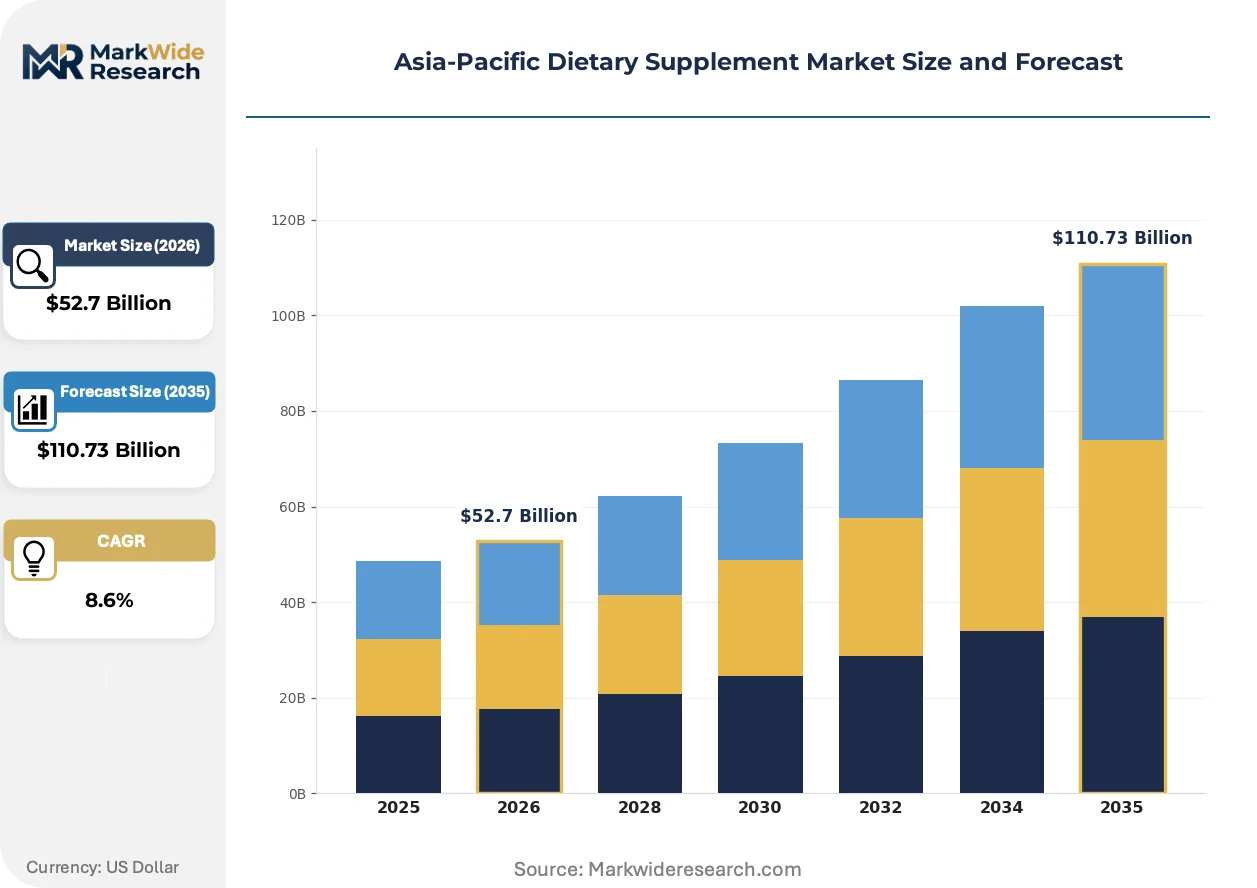
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Proteins End User: Adult Consumers, Athletes, Seniors, Pregnant Women Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Form: Tablets, Powders, Liquids, Gummies |
| Companies Covered | Abbott Laboratories, Herbalife Nutrition Ltd., Amway Corporation, Bayer AG, Haleon Plc, Nestlé, Otsuka Holdings Co., Ltd., Glanbia plc, Blackmores Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dietary Supplement Market Strategic Shifts
Microencapsulation technologies are reshaping bioavailability standards across protein, probiotic, and lipid-based supplement categories. These advances are compressing differentiation timelines and forcing rapid capability upgrades among contract manufacturers.
Liposomal delivery systems are fragmenting absorption benchmarks for fat-soluble vitamins. Premium brands in Australia's pharmacy channel and China's tier-one cities are adopting phospholipid-encapsulated vitamin D and curcumin formats. This technology is fragmenting the competitive landscape by enabling smaller brands to claim equivalence with established clinical-grade positioning.
FSSAI's 2024 ingredient disclosure protocols are mandating quantitative label declarations for all botanical extracts above threshold concentrations. Indian importers must now submit chromatographic fingerprinting data for herbal raw materials. Ayurvedic and traditional Chinese medicine formulations face the steepest compliance burden, with several SKUs withdrawn from Indian e-commerce pending documentation upgrades.
Subscription-based replenishment models are displacing traditional pharmacy and supermarket replenishment cycles among Australian and South Korean consumers. Direct-to-consumer platforms capture recurring revenue through algorithm-driven dosage reminders and personalized bundling. This shift is most visible in Melbourne, Sydney, and Seoul, where gym-affiliated nutrition coaching integrates with automated supplement delivery.
Asia-Pacific Dietary Supplement Market Segmentation
Regulatory divergence across Asia-Pacific jurisdictions fragments formulation requirements by segment, forcing manufacturers to maintain parallel product portfolios. China's SAMR registration pathways and India's FSSAI disclosure mandates create distinct compliance tiers that reshape competitive positioning within each category.
Product Type:
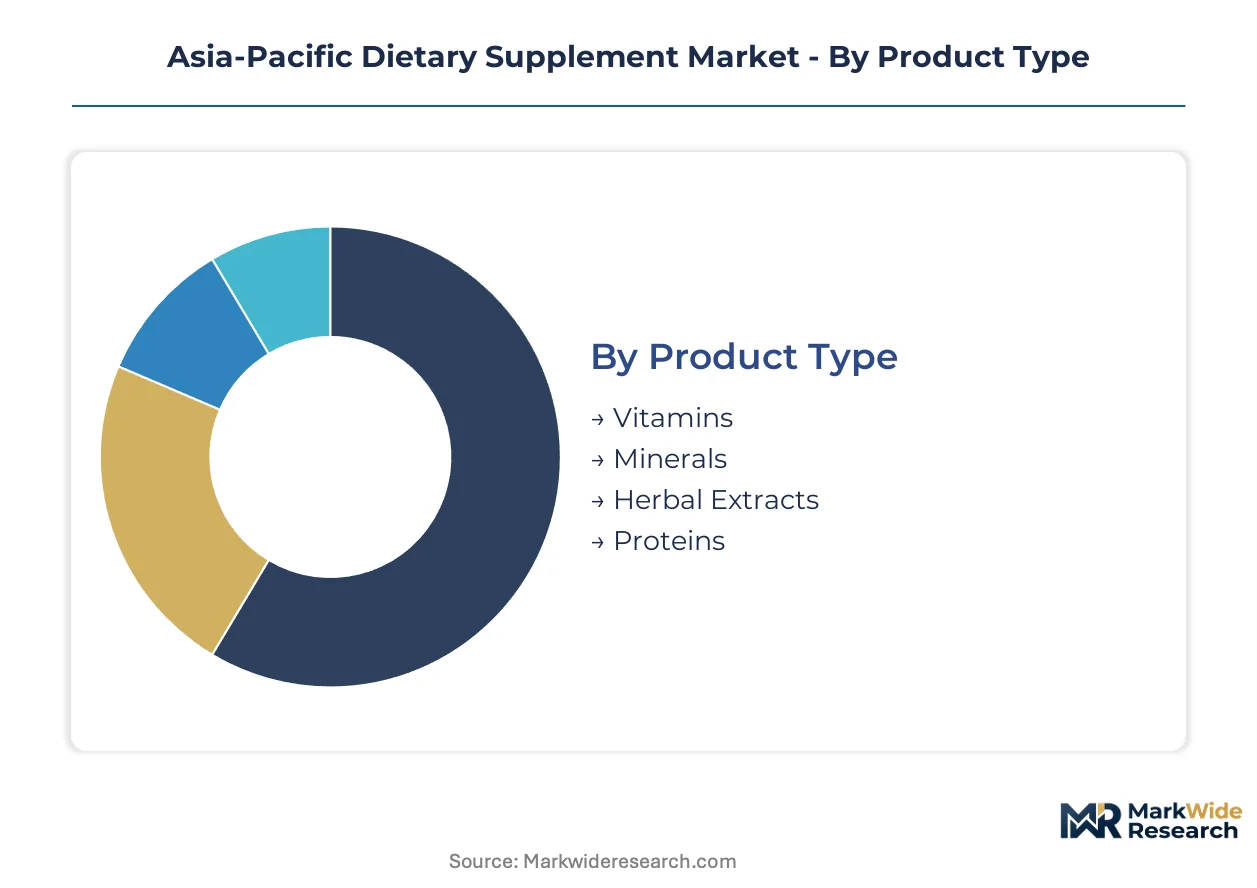
Regulatory differentiation separates therapeutic-grade from general wellness positioning across Asia-Pacific markets, with vitamin and protein categories facing divergent registration burdens.
- Vitamins:Fat-soluble and water-soluble compounds manufactured through spray-drying or microencapsulation processes. Demand concentrates in China's tier-one cities where SAMR-registered formulations command premium pharmacy shelf placement amid dual-language labeling mandates.
- Proteins:Whey, casein, and plant-derived concentrates processed via cold-pressing or advanced drying technologies. Vietnamese and Indonesian contract manufacturers are upgrading solubility specifications to capture gym culture proliferation across Ho Chi Minh City, Jakarta, and Manila metropolitan clusters.
- Minerals:Chelated and inorganic salt forms governed by elemental concentration thresholds in Australia's TGA therapeutic goods framework.
- Herbal Extracts:Botanical concentrates requiring chromatographic fingerprinting documentation under India's FSSAI protocols, with kava and comfrey alkaloid limits blocking certain traditional Chinese medicine formulations from Australian registration.
Established volume favors vitamins; emerging adoption favors proteins.
End User:
Customer-type segmentation maps directly to distribution channel economics, with professional guidance requirements varying sharply by life-stage and activity level.
- Adult Consumers:Health-conscious professionals aged 25-55 seeking preventive nutrition solutions. Australia's pharmacy channel and South Korea's direct-to-consumer platforms capture this cohort through subscription-based replenishment models integrated with diagnostic biomarker tracking.
- Seniors:Aging populations over 65 requiring bioavailable formats for nutrient absorption. China's urban centers drive demand for liposomal vitamin D and curcumin delivery systems amid expanding geriatric care infrastructure.
- Athletes:Performance-focused consumers requiring batch-tested formulations with banned-substance certification.
- Pregnant Women:Pre-natal vitamin and mineral segments governed by strict teratogenic screening protocols in Japan's PMDA and Australia's TGA frameworks.
Pharmacy-channel dependence favors seniors; digital-native purchasing favors adult consumers.
Distribution Channel:
Channel economics fragment fulfillment requirements across regulatory jurisdictions, with cross-border e-commerce facing parallel import restrictions and positive-list compliance.
- Online Retail:Direct-to-consumer platforms and pharmacy apps capturing recurring revenue through algorithm-driven dosage reminders. South Korean telehealth integration and Australian subscription models are displacing traditional replenishment cycles in Melbourne, Sydney, and Seoul.
- Pharmacies:Professional consultation channels dominating therapeutic nutrition segments. China's SAMR registration streamlining creates clearer pathways for compliant imported formulations to access premium retail placement in Beijing and Shanghai.
- Supermarkets:Mass-market vitamin and mineral formats with lower regulatory entry barriers.
- Specialty Stores:Gym-affiliated nutrition coaching and protein-focused retail in Southeast Asian urban centers.
Subscription automation favors online retail; clinical credibility favors pharmacies.
Form:
Manufacturing technology requirements concentrate capability investments among contract manufacturers, with microencapsulation and spray-drying equipment creating tiered supply access.
- Powders:Protein and meal-replacement formats requiring solubility optimization and shelf-stability engineering. Vietnamese and Indonesian manufacturers deploying advanced drying technologies to serve gym culture demand across Southeast Asia.
- Tablets:Compressed vitamin and mineral formats with established excipient supply chains. India's PLI schemes for pharmaceutical intermediates are reducing domestic production costs for capsule and softgel manufacturers.
- Liquids:Liposomal delivery systems for fat-soluble vitamins gaining traction in Australia's pharmacy channel and China's tier-one cities.
- Gummies:Gelatin and pectin-based formats facing sugar-content scrutiny in pediatric and adult wellness segments.
Equipment scale favors tablets; bioavailability innovation favors powders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Asia-Pacific Dietary Supplement Market, with Vietnamese and Indonesian consumers showing high sensitivity to protein powder premiums while Australian and South Korean buyers absorb liposomal delivery surcharges without volume attrition.
China
Urban professionals in Beijing and Shanghai drive preventive nutrition expenditure among aging cohorts over 45. SAMR's dual-language labeling mandates and streamlined health-food registration create clearer compliance pathways for imported formulations seeking premium pharmacy placement. Yangtze River Delta manufacturing clusters host contract producers upgrading microencapsulation capabilities for probiotic stability.
India
Ayurvedic wellness traditions and gym culture expansion in Mumbai and Delhi-NCR fuel parallel demand for herbal extracts and whey proteins. FSSAI's 2024 ingredient disclosure protocols mandate chromatographic fingerprinting for botanical extracts above threshold concentrations, forcing documentation upgrades among importers. Maharashtra's PLI scheme for pharmaceutical intermediates reduces excipient costs for domestic softgel manufacturers.
Australia
Pharmacy-channel dependence and subscription-based replenishment models dominate Melbourne and Sydney consumption patterns. TGA therapeutic goods standards enforce strict kava and comfrey alkaloid limits that block certain traditional Chinese medicine formulations from registration. Sydney's direct-to-consumer platforms integrate diagnostic biomarker tracking with automated supplement delivery workflows.
South Korea
Telehealth app penetration and gym-affiliated nutrition coaching in Seoul drive personalized regimen adherence through algorithm-driven dosage reminders. MFDS regulations govern functional food and supplement labeling convergence as fortified beverages capture occasions previously served by tablets. Seoul Capital Area contract manufacturers deploy advanced spray-drying equipment for protein solubility optimization.
Vietnam
Provincial penetration outside Ho Chi Minh City and Hanoi remains below 15 percent of urban household spend, creating whitespace for pharmacy chain expansion. Provincial health authorities lack enforcement capacity for import documentation standards, enabling gray-market entry of unregistered formulations. Ho Chi Minh City manufacturers upgrade drying technologies to serve Southeast Asian gym culture demand.
Asia-Pacific Dietary Supplement Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Dietary Supplement Market. Pharmaceutical heritage companies anchor clinical-grade positioning through therapeutic nutrition segments, while direct-selling networks sustain channel control across Southeast Asian markets. Multi-level distribution specialists dominate localized product portfolios in China and India. Contract manufacturers compete on spray-drying and microencapsulation capability tiers. Strategic moves concentrate on third-party certification upgrades and cross-border e-commerce fulfillment integration.
Among the named players, Abbott Laboratories exemplifies pharmaceutical-derived clinical-grade positioning, Herbalife Nutrition Ltd. occupies the direct-selling channel control archetype, and Amway Corporation sits within multi-level distribution network dominance across China and India. These three anchors represent distinct competitive vectors rather than overlapping segment contestation. Their geographic and channel specializations reduce direct confrontation while elevating compliance and certification as the primary competitive battleground.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Herbalife Nutrition Ltd. |
| Amway Corporation |
| Bayer AG |
| Haleon Plc |
| Nestlé |
| Otsuka Holdings Co., Ltd. |
| Glanbia plc |
| Blackmores Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for marine-derived omega-3 concentrates lock in both supply access and price visibility for Asia-Pacific formulators, insulating premium vitamin brands from Peruvian catch-quota volatility while exposing economy-tier players to spot-market omega-3 price spikes. India's FSSAI-mandated chromatographic fingerprinting requirements add documentation costs that compress margins for herbal extract importers lacking pre-qualified supplier relationships.
Pricing Analysis
SAMR dual-language labeling mandates dictate the pricing tier structure across China's dietary supplement channels, separating SAMR-registered pharmacy-grade formulations from cross-border e-commerce imports. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment depth, with liposomal delivery formats commanding pharmacy premiums and unregistered powders competing on price in gray-market Vietnam. Pricing pressure stems from India's PLI scheme reducing domestic excipient costs and enabling local manufacturers to undercut imported tablet formats. Adult consumers in South Korea's subscription channels show lowest price sensitivity, absorbing algorithm-personalized bundling surcharges, while Vietnamese provincial households remain most price-responsive.
Supply Chain Analysis
Peruvian anchovy fisheries and Norwegian cod liver oil extraction underwrite omega-3 raw material flows into Asia-Pacific encapsulation plants. Vietnamese and Indonesian contract manufacturers draw from Chinese vitamin premix suppliers and Indian gelatin capsule shell producers. Single-source vulnerability concentrates in marine lipid inputs, with El Niño catch disruptions cascading through Ho Chi Minh City and Jakarta protein powder facilities. Distribution runs through pharmacy chain procurement in Australia and China, direct-to-consumer platforms in South Korea, and multi-level networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific dietary supplement market is recovering from regulatory compliance cost cyclicality, with India's FSSAI disclosure protocols and China's SAMR streamlining together compressing margin recovery timelines for importers.
For Market Incumbents: Shield therapeutic nutrition positioning through third-party certification upgrades that preempt Australia's TGA herbal concentration enforcement. Deepen backward integration into spray-drying equipment capabilities across Yangtze River Delta contract manufacturers to capture protein powder solubility premiums. Lock in chromatographic fingerprinting documentation from Ayurvedic raw material suppliers before India's FSSAI thresholds expand. For New Entrants and Emerging Players: FSSAI fast-track pathways for domestic softgel manufacturers create entry corridors into India's pharmacy channels. White-space concentrates in Vietnam's underpenetrated provinces outside Ho Chi Minh City and Hanoi, where dietary supplement penetration lags metropolitan levels. Target gym-affiliated nutrition coaching partnerships in Jakarta and Manila as a go-to-market anchor for protein format trials. For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturers with microencapsulation capability tiers that serve liposomal vitamin and probiotic stability demands. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone across the analysis window. Monitor India's PLI scheme expansion signals as inflection indicators for domestic manufacturing cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Third-Party Certification Upgrade | TGA and FSSAI compliance investments unlock premium pharmacy shelf placement in Sydney and Mumbai. |
| Microencapsulation Capability Buildout | Probiotic stability technology captures liposomal delivery demand across China's tier-one cities. |
| Direct-to-Consumer Platform Launch | Subscription automation displaces traditional replenishment cycles in Melbourne and Seoul. |
| Backward Integration into Excipient Supply | India's PLI scheme tailwinds reduce gelatin and capsule shell procurement costs. |
| Cross-Border E-Commerce Fulfillment Integration | Positive-list compliance unlocks gray-market conversion in Vietnam's provincial channels. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing pharmacy chain procurement managers, contract manufacturing plant engineers, regulatory affairs specialists at FSSAI and SAMR, and direct-to-consumer platform operators. Secondary validation drew from TGA therapeutic goods registers, FSSAI ingredient disclosure protocols, customs import documentation for dietary supplement raw materials, and Nielsen retail audit data across Australian pharmacy channels. Bottom-up volume modeling triangulated against top-down expenditure surveys.
Across the analysis window, forecasts segment by product type, end user, distribution channel, and form factor, with additional granularity on regulatory compliance tier. CAGRs derive from regression analysis of historical volume flows and elasticity-adjusted price trajectory assumptions. Industry-specific inputs include gym culture penetration indices across Southeast Asian metropolitan clusters and telehealth app subscription conversion rates in South Korea.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity; material deviation in FSSAI documentation timelines or SAMR registration backlogs would warrant model refresh. Practitioners should keep alternative scenarios live as India's PLI scheme expansion and Vietnam's provincial enforcement capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Energy Gel Products Market