
 Flax Protein Powder Market | 2026-2036
Flax Protein Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Flax Protein Powder Market Insights
Clean-label extraction technology is rewriting how flax protein isolates achieve commercial purity without hexane or chemical solvents. Cargill, Incorporated leverages its integrated oilseed processing infrastructure to control input costs across North American crushing operations. Richardson International anchors prairie-origin supply through its farmer network in Manitoba and Saskatchewan. Glanbia Nutritionals competes by specializing in flavor-masked isolates that reduce the grassy off-notes limiting beverage applications.
Flax protein powder is a defatted, milled derivative of Linum usitatissimum seed containing approximately 30-40% protein by weight, with typical commercial isolates reaching 80-90% protein concentration through aqueous or enzymatic extraction; its primary commercial purpose is to fortify plant-based foods, supplements, and nutraceuticals with essential amino acids and omega-3 fatty acids while delivering emulsification and water-binding functional properties. Organic product type commands premium shelf positioning in European health stores and North American natural channel retailers, though conventional isolates dominate volume in cost-sensitive sports nutrition applications. Powder form leads distribution through bulk ingredient sales to food manufacturers, while capsules and bars represent faster-growing finished-product channels as direct-to-consumer brands bypass traditional retail.
USDA organic certification and FDA food additive regulations govern ingredient safety and label claims in the United States, while EFSA novel food assessments and EU organic labeling standards shape market access across European member states. Health Canada and PMRA oversight of pesticide residues on imported flaxseed directly impacts protein powder eligibility for Canadian natural health product registrations. Stakeholders must monitor evolving protein content verification protocols and origin traceability requirements as regenerative agriculture claims become a purchasing criterion for major supplement brands.
Market Dynamics
Clean-label extraction technology is compressing the cost premium between solvent-free and conventional flax protein isolates, while EU F-Gas Regulation and the EU Green Deal are forcing ingredient buyers to document regenerative sourcing credentials across their supply chains.
Growth Catalysts
- EU Green Deal compliance mandates:Food manufacturers across Germany, France, and the Netherlands must reduce Scope 3 emissions, driving procurement of domestically milled flax protein with verifiable carbon footprints.
- Sports nutrition formulation:Clean-label beverage brands are replacing whey and soy with flax isolates in post-workout powders, leveraging the ingredient's complete amino acid profile and omega-3 content.
- Aqueous extraction scale-up:Commercial deployment of enzyme-assisted aqueous processing is eliminating hexane dependency, unlocking organic certification pathways previously blocked by solvent residues.
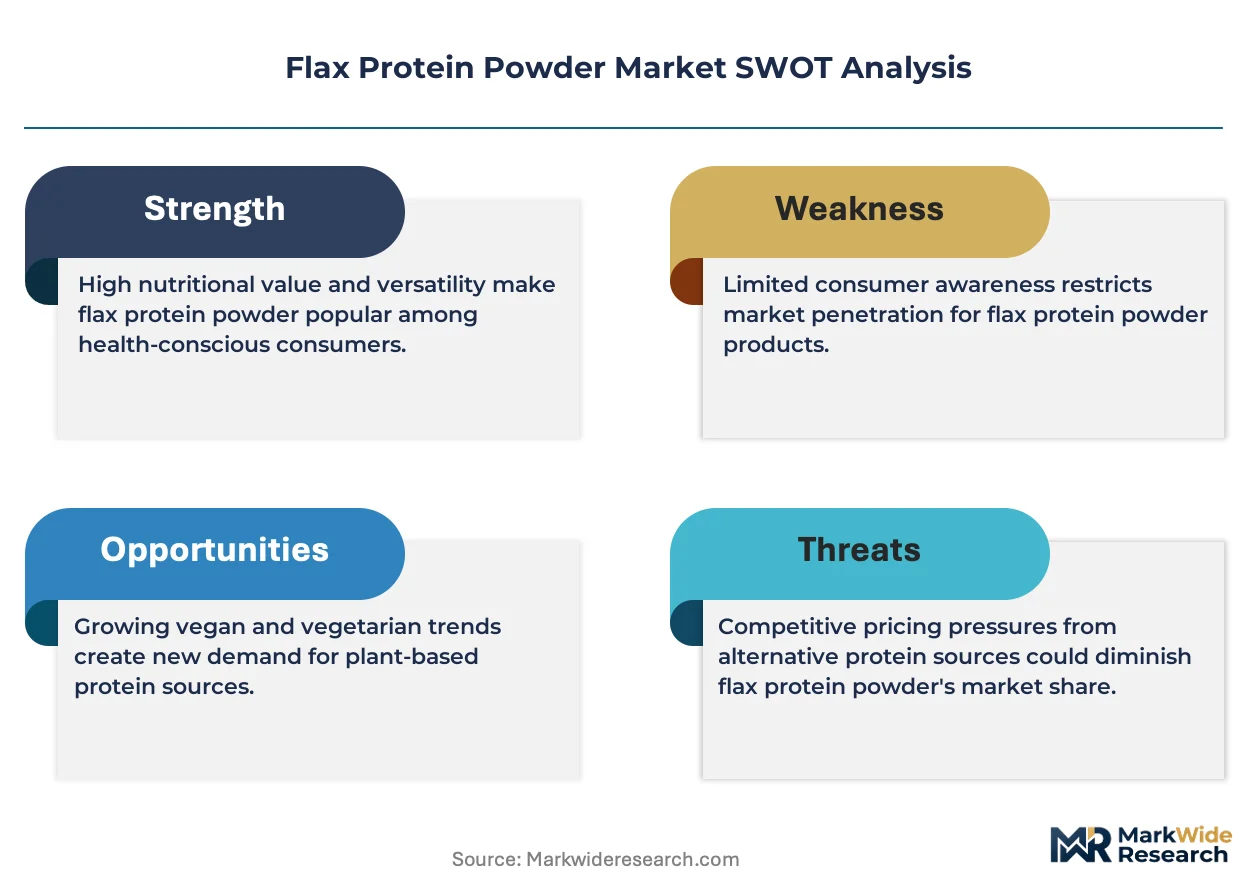
Market Restraints
- Input cost volatility:Flaxseed prices swing with prairie drought cycles in Canada, where Richardson International and farmer cooperatives concentrate origin supply.
- Technical limitation:Grassy off-flavors in standard isolates restrict inclusion rates in flavored beverages below 5% protein contribution without masking systems.
- Substitution threat:Pea and fava protein isolates offer comparable functionality at lower price points, capturing cost-sensitive contract manufacturing slots.
Strategic Opportunities
- Underpenetrated geography:Brazilian functional food brands lack domestic flax protein supply, creating import demand for North American and European exporters.
- Regulatory tailwind:Health Canada's Natural Health Product Directorate is streamlining flax protein registration for omega-3 structure-function claims.
- Distribution innovation:Direct-to-consumer subscription models for protein-fortified bars bypass conventional retail slotting fees and margin stacking.
Industry Challenges
- Certification timeline compression:USDA organic and EU organic label audits now require 18-24 months for new processing facilities, delaying market entry.
- Skill gap in enzymology:Commercial-scale aqueous extraction demands protein biochemists scarce in traditional oilseed crushing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flax Protein Powder Market |
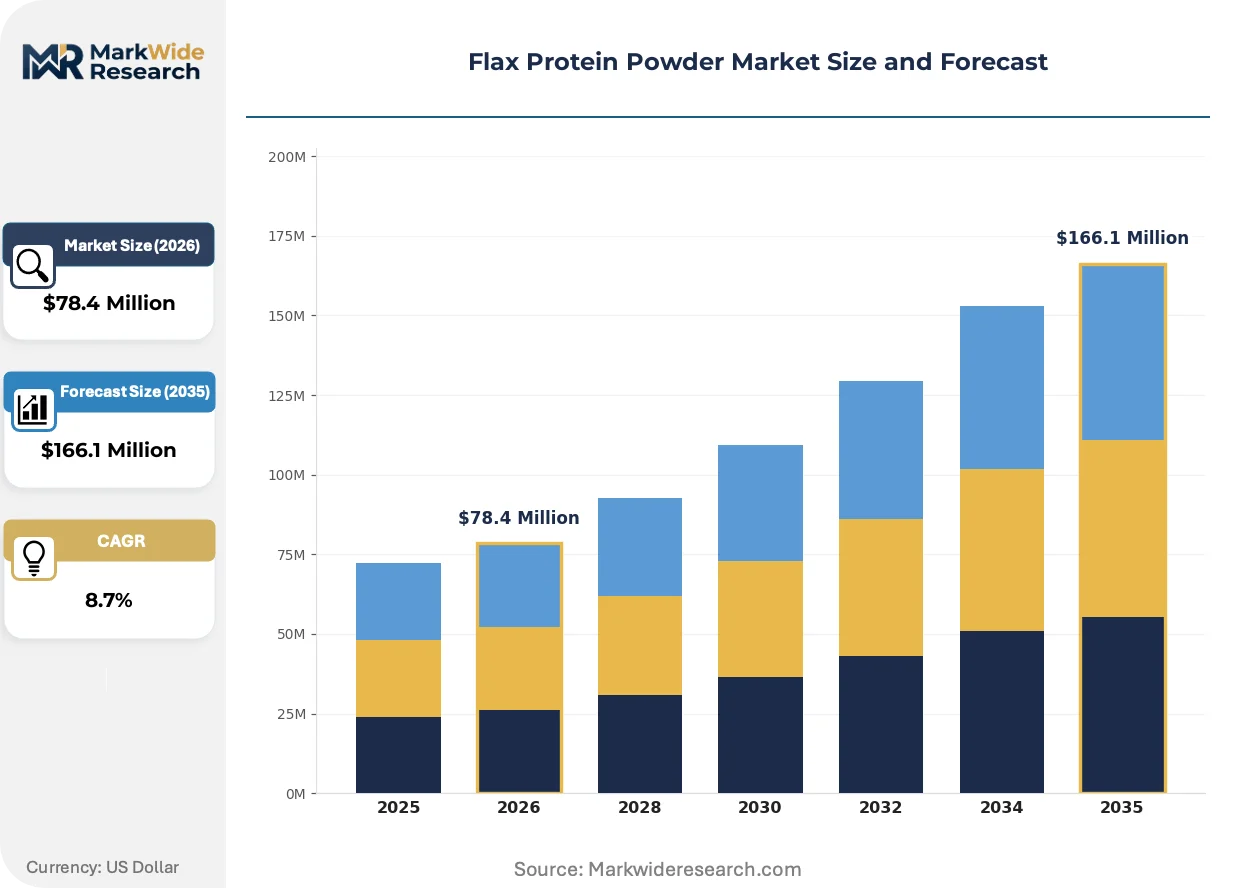
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $166.1 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Isolate, Blend End User: Food Industry, Supplements, Nutraceuticals, Personal Care Form: Powder, Granules, Capsules, Bars Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Glanbia Nutritionals, Austrade Inc., Richardson International, Bioriginal Food & Science Corp., Natunola, Clearspring Ltd., Omega Protein Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flax Protein Powder Market Trends and Innovations
Digital traceability infrastructure and precision fermentation adjacent technologies are rewiring how flax protein achieves price parity with commodity isolates. Three developments dominate the analysis window.
Enzymatic aqueous extraction is virtualizing the traditional hexane-based isolate production model. Mid-size European millers in Hamburg and Copenhagen are retrofitting oilseed plants with membrane filtration skids. This technology is virtualizing capital requirements for organic certification, compressing the investment gap between conventional and clean-label processing from five years to eighteen months.
EFSA novel food assessment protocols are tightening purity verification standards for protein isolates entering EU member states. The regulation now mandates batch-level amino acid profiling and heavy metal screening. German and Dutch ingredient distributors are consolidating supplier lists to those with in-house analytical laboratories, excluding smaller North American exporters without European testing partnerships.
Direct procurement from prairie farmer networks is displacing commodity exchange purchasing among large supplement brands. Cargill's integrated crushing infrastructure and Richardson's cooperative sourcing model are being bypassed by brands establishing captive supply contracts with Saskatchewan organic growers. This pattern concentrates most visibly in Minneapolis and Boulder formulation clusters where R&D teams co-develop seed varieties with specific protein content targets.
Flax Protein Powder Market Segmentation
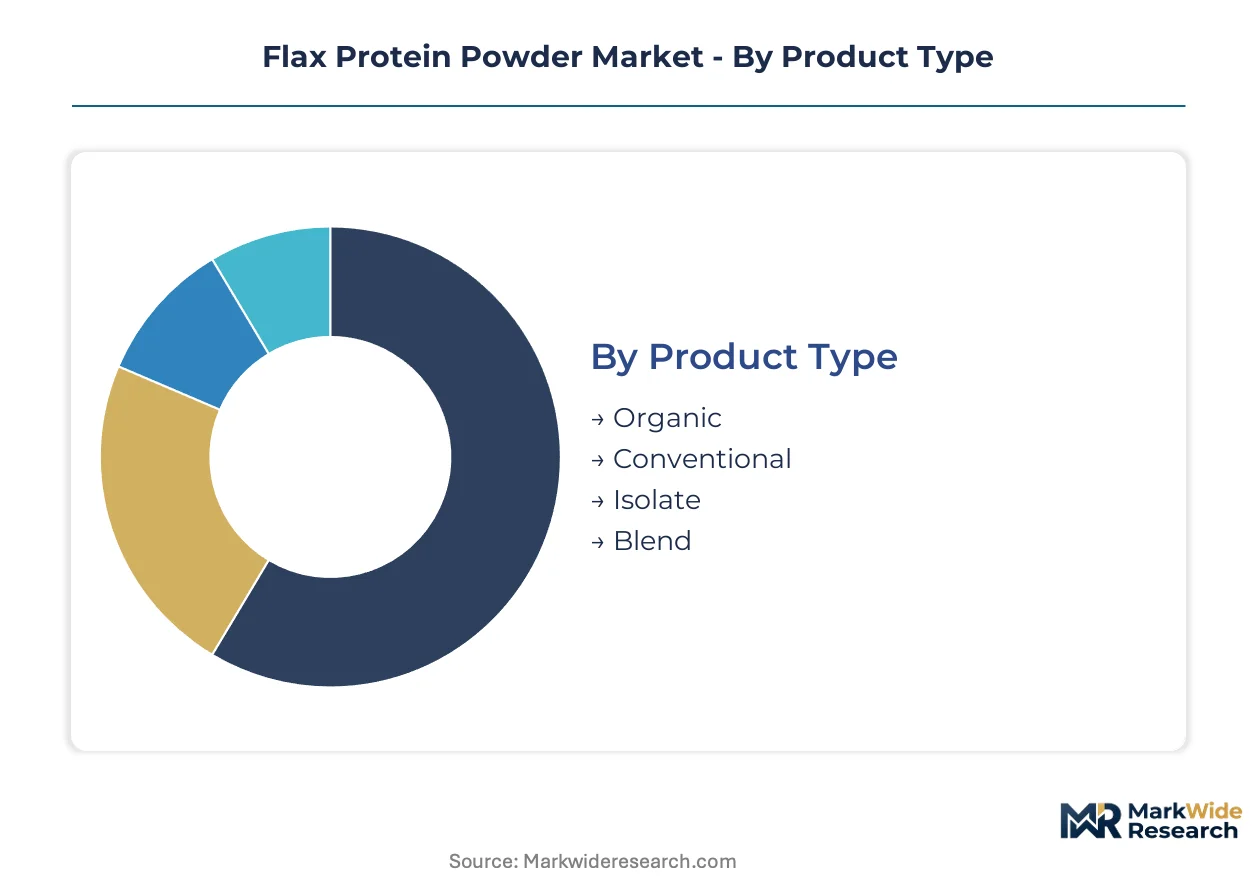
Flax protein powder segmentation reflects divergent technical requirements across extraction methods, end-use applications, and delivery formats. Clean-label extraction capabilities and regulatory certification pathways create distinct competitive arenas within each category.
Product Type:
After-sales service intensity concentrates around organic certification audits and solvent-free processing verification, where buyers demand batch traceability documentation.
- Organic:USDA and EU organic label compliance mandates enzyme-assisted aqueous extraction without hexane residues. German health store chains and Minneapolis formulation clusters drive procurement of certified isolates for premium beverage applications.
- Conventional:Hexane-extracted isolates dominate cost-sensitive sports nutrition manufacturing. Canadian crushing infrastructure supplies volume buyers in contract manufacturing with lower purity thresholds.
- Isolate:80-90% protein concentration achieved through membrane filtration serves functional food fortification.
- Blend:Combination with pea or rice protein addresses amino acid completeness in plant-based meat alternatives.
By volume, Conventional leads. By growth pace, Organic is expanding most quickly.
End User:
Application-driven formulation requirements separate commodity ingredient sales from value-added finished goods.
- Supplements:Post-workout powders and omega-3 structure-function claims dominate demand. Health Canada's Natural Health Product Directorate registration streamlines market access for compliant isolates.
- Food Industry:Plant-based meat and dairy alternatives leverage emulsification properties. Berlin and Hamburg innovation clusters trial domestic milled protein for clean-label bakery applications.
- Nutraceuticals:Capsule and tablet formats target cardiovascular health positioning.
- Personal Care:Hair and skin conditioning applications utilize hydrolyzed fractions.
Food Industry commands volume leadership. Supplements demonstrate the steepest expansion trajectory.
Form:
Customer acquisition economics vary sharply between bulk ingredient procurement and finished consumer goods.
- Powder:Bulk sales to manufacturers dominate throughput. Richardson International and Cargill anchor North American supply through prairie crushing networks.
- Bars:Direct-to-consumer subscription models bypass retail slotting fees. Boulder and Minneapolis brands co-develop seed varieties with Saskatchewan organic growers for captive protein supply.
- Capsules:Nutraceutical brands target omega-3 positioning with encapsulated isolates.
- Granules:Instant beverage applications require rapid dispersibility specifications.
Powder leads by volume. Bars are gaining share fastest among emerging formats.
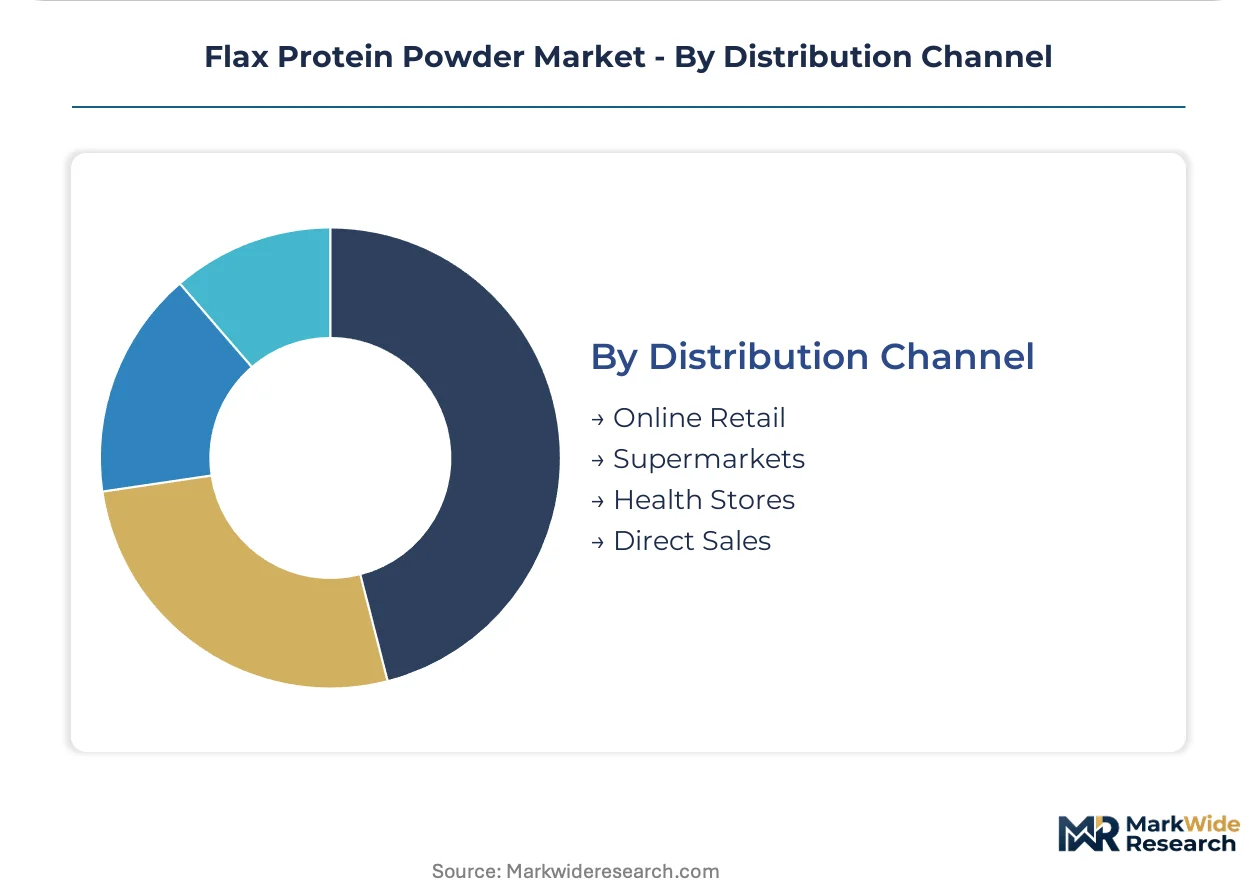
Distribution Channel:
Channel economics determine margin capture and brand control for ingredient suppliers and finished goods manufacturers.
- Online Retail:Amazon and specialized supplement platforms enable direct consumer relationships. Subscription models for protein-fortified products reduce customer acquisition costs versus conventional retail.
- Health Stores:European natural channel retailers command premium shelf positioning for certified organic isolates.
- Supermarkets:Mass-market penetration requires price parity with commodity plant proteins.
- Direct Sales:Bulk ingredient contracts with food manufacturers concentrate in Minneapolis and Boulder formulation clusters.
Supermarkets lead by volume. Online Retail shows the strongest momentum in customer acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian flaxseed shipments to European ingredient processors are accelerating as EU Green Deal compliance deadlines tighten. Prairie crushing infrastructure supplies North American formulation clusters while German millers retrofit plants for aqueous extraction.
United States
Minneapolis and Boulder formulation clusters drive procurement of organic isolates for beverage applications. FDA food additive regulations govern protein content verification and label claims. Sports nutrition brands in Minneapolis co-develop seed varieties with Saskatchewan growers for captive omega-3 supply chains.
Germany
Berlin and Hamburg innovation clusters trial domestic milled protein for clean-label bakery and meat alternative applications. EU F-Gas Regulation and EU Green Deal mandate Scope 3 emissions documentation across ingredient sourcing. Hamburg-based millers retrofit oilseed plants with membrane filtration skids for solvent-free processing.
Canada
Manitoba and Saskatchewan farmer networks anchor prairie-origin supply for North American crushing operations. Health Canada and PMRA oversight of pesticide residues impacts protein powder eligibility for natural health product registrations. Richardson International maintains cooperative sourcing relationships across prairie provinces.
France
Paris-based nutraceutical brands demand EFSA novel food assessment compliance for protein isolate imports. EU organic labeling standards shape market access for certified isolates. Lyon formulation labs test flax-pea protein blends for plant-based meat texture optimization.
Brazil
São Paulo functional food brands lack domestic flax protein supply, creating import demand for North American exporters. ANVISA registration requirements govern novel ingredient market entry. Brazilian contract manufacturers seek certified isolates for sports nutrition export production.
Flax Protein Powder Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Integrated oilseed processors anchor volume supply through farmer network relationships. Mid-size enzymatic extraction specialists capture premium organic certification segments. Competitive moves concentrate on backward integration into seed variety development and capacity expansion for aqueous processing infrastructure.
Among North American integrated processors, Cargill, Incorporated and Richardson International exemplify scale-driven supply chain control. Richardson International occupies a position within the prairie-origin sourcing archetype. Glanbia Nutritionals represents the flavor-masked isolate specialization tier. These three anchors demonstrate how competitive positioning splits between upstream supply control and downstream formulation enablement.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Glanbia Nutritionals |
| Austrade Inc. |
| Richardson International |
| Bioriginal Food & Science Corp. |
| Natunola |
| Clearspring Ltd. |
| Omega Protein Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Hamburg aqueous extraction facilities is compressing lead times for organic-certified isolates and tilting supplier pricing power toward German millers with membrane filtration skids. EU F-Gas Regulation compliance costs are feeding through to procurement premiums, forcing North American brands to choose between expedited European supply or longer-haul prairie-origin logistics.
Pricing Analysis
Hexane-extracted conventional isolates trade at a 40-50% discount to enzyme-assisted aqueous extraction grades, with the technology-generation pricing gap widening as organic certification premiums harden. Three-tier pricing structure across premium organic, standard conventional, and economy hexane-extracted levels stratifies by certification grade and solvent residue thresholds. Pricing pressure stems from pea protein substitution in cost-sensitive contract manufacturing, with sports nutrition brands exhibiting highest price sensitivity and clean-label beverage formulators showing lowest.
Supply Chain Analysis
Export-control regimes on enzymatic processing equipment from Denmark and Germany are constraining capacity expansion in North American facilities, fragmenting technology transfer flows. Supply draws from Canadian prairie crushing networks, German retrofit millers, and emerging Baltic processors. Raw material dependencies center on Saskatchewan organic flaxseed, membrane filtration skids, and food-grade enzyme supplies. Single-source vulnerability concentrates in aqueous extraction engineering talent pools. Distribution runs through bulk ingredient contracts with Minneapolis and Boulder formulation clusters, supplemented by direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flax protein powder markets reward service-attach strategies, with organic certification audit and batch traceability documentation services expanding faster than commodity isolate throughput. Recurring revenue from compliance documentation subscriptions now exceeds hardware margins for mid-size European millers.
For Market Incumbents: Insulate prairie-origin supply relationships through captive contracting with Saskatchewan organic grower cooperatives, neutralizing Richardson International's cooperative sourcing advantage. Invest in Hamburg and Copenhagen enzymatic extraction capacity to preempt EU Green Deal compliance premiums. Certification investment in USDA organic and EU organic dual-labeling defends against emerging Baltic processors with lower regulatory overhead. For New Entrants and Emerging Players: Establish a beachhead in Brazilian functional food import demand, where São Paulo brands lack domestic supply and ANVISA registration creates defendable first-mover positioning. Target direct-to-consumer protein bar subscriptions in Minneapolis and Boulder, bypassing Cargill's bulk ingredient channel control. Go-to-market angle: co-developed seed variety partnerships with prairie organic growers for captive omega-3 supply chains. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across aqueous extraction sub-segments as membrane filtration skids commoditize, compressing returns for greenfield organic facilities. Long-term viability favors backward-integrated processors with farmer network relationships over standalone extraction specialists. Acquisition target archetype: mid-size European millers with EFSA novel food assessment in-house capabilities. Signal to watch: Health Canada Natural Health Product Directorate registration timelines for omega-3 structure-function claims.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Seed Supply | Captive contracting with Saskatchewan growers locks in EU Green Deal-compliant origin traceability. |
| Aqueous Extraction Capacity Expansion | Hamburg and Copenhagen retrofit projects capture organic certification premiums from hexane-free processing. |
| Flavor-Masked Isolate R&D Investment | Glanbia Nutritionals' specialization demonstrates path to beverage inclusion rates above 5% protein contribution. |
| Direct-to-Consumer Subscription Launch | Boulder and Minneapolis brands bypass retail slotting fees and margin stacking through captive protein bar channels. |
| EFSA Novel Food Assessment Partnership | German and Dutch distributors consolidate supplier lists to laboratories with batch-level amino acid profiling capabilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with oilseed processing executives, organic certification auditors, sports nutrition formulators, and agricultural cooperative managers; and secondary validation through USDA organic certification databases, EFSA novel food assessment filings, Health Canada Natural Health Product Directorate registrations, and Canadian Grain Commission trade statistics. Bottom-up volume modeling triangulated against top-down ingredient demand projections from food manufacturer procurement disclosures.
Forecast inputs included extraction technology adoption curves, EU F-Gas Regulation compliance cost trajectories, and substitution elasticity between flax and pea protein isolates across the projection horizon. Segmentation dimensions spanned product type (organic/conventional/isolate/blend), end user (supplements/food industry/nutraceuticals/personal care), form (powder/bars/capsules/granules), and distribution channel (online retail/health stores/supermarkets/direct sales). CAGRs derived from spline-interpolated technology diffusion curves and regulatory deadline impacts.
Stress conditions across Canadian drought frequency, enzyme supply chain disruptions, and EU organic audit timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about aqueous extraction scale-up rates and Health Canada registration streamlining. Cross-checking against Canadian Grain Commission flaxseed export volumes and EFSA novel food assessment approval timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
North America Digestive Health Supplements Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Tryptophan Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Global Protein Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
Calcium HMB Market