
 Energy Gel Products Market | 2026-2036
Energy Gel Products Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Gel Products Market Analysis
EU novel food regulations and FDA dietary supplement labeling requirements are consolidating the cost-of-entry calculus for new energy gel entrants, forcing reformulation investments and third-party certification spending. Science in Sport leverages its British Cycling partnerships to sustain elite-athlete credibility. Maurten dominates hydrogel technology positioning with patented alginate formulations. GU Energy Labs anchors the American mass-market channel through deep specialty retail distribution.
Energy gel products are concentrated carbohydrate-based formulations, typically delivering 20-25 grams of maltodextrin or fructose per serving through viscous semisolid matrices designed for rapid gastric emptying during sustained aerobic exertion. Pouch packaging leads volume due to tear-open ergonomics and minimal weight, though tube formats command margin premiums among ultramarathon and expedition segments. Carbohydrate-dominant gels remain the mature revenue base while caffeine-infused variants represent the fastest-growing ingredient category as ergogenic aid claims gain traction in specialty retail. Online retailers are displacing supermarkets as the primary growth channel, reflecting direct-to-consumer subscription models and Strava-integrated purchase funnels.
FDA Current Good Manufacturing Practices, EFSA health claim substantiation protocols, and ISO 22000 food safety management standards collectively govern product integrity, label accuracy, and cross-border market access. These frameworks elevate compliance spending but simultaneously filter out subscale competitors, concentrating shelf presence among certified manufacturers. Stakeholders must monitor evolving caffeine threshold regulations and emerging state-level extended producer responsibility laws for single-use packaging.
Market Dynamics
Clean-label formulation mandates under FDA and EFSA guidance are forcing ingredient sourcing overhauls, compressing margins for uncertified suppliers while concentrating shelf presence among compliant manufacturers with third-party verification infrastructure.
Growth Catalysts
- Marathon participation surge:Endurance sports registration volumes in the United States, Germany, and Japan are expanding the addressable athlete base for rapid-absorption carbohydrate formulations.
- EFSA health claim substantiation:Validated ergogenic aid declarations are unlocking premium positioning in European specialty retail channels.
- Hydrogel matrix innovation:Patented alginate encapsulation technology is reducing gastric distress incidence during sustained exertion.
Market Restraints
- Fructose supply volatility:Weather-driven corn harvest fluctuations in the US Midwest are compressing formulation cost predictability.
- Single-use packaging liability:Emerging state-level extended producer responsibility laws in California and New York are imposing compliance burdens.
- Caffeine threshold uncertainty:Pending FDA stimulant concentration limits are freezing new product pipeline investments.
Strategic Opportunities
- Japanese aging athlete segment:Masters-category endurance participation is outpacing youth enrollment, creating demand for lower-osmolality formulations.
- Strava-integrated subscription models:Direct-to-consumer platforms are capturing repeat purchase velocity previously held by specialty retailers.
- ISO 22000 certification arbitrage:Cross-border market access barriers are filtering subscale competitors, concentrating distribution leverage among certified manufacturers.
Industry Challenges
- Food technologist scarcity:Formulation chemistry expertise for hydrogel stability under thermal stress is concentrating among a narrow specialist pool.
- Third-party audit backlogs:NSF Certified for Sport and Informed Sport verification timelines are extending new product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Gel Products Market |
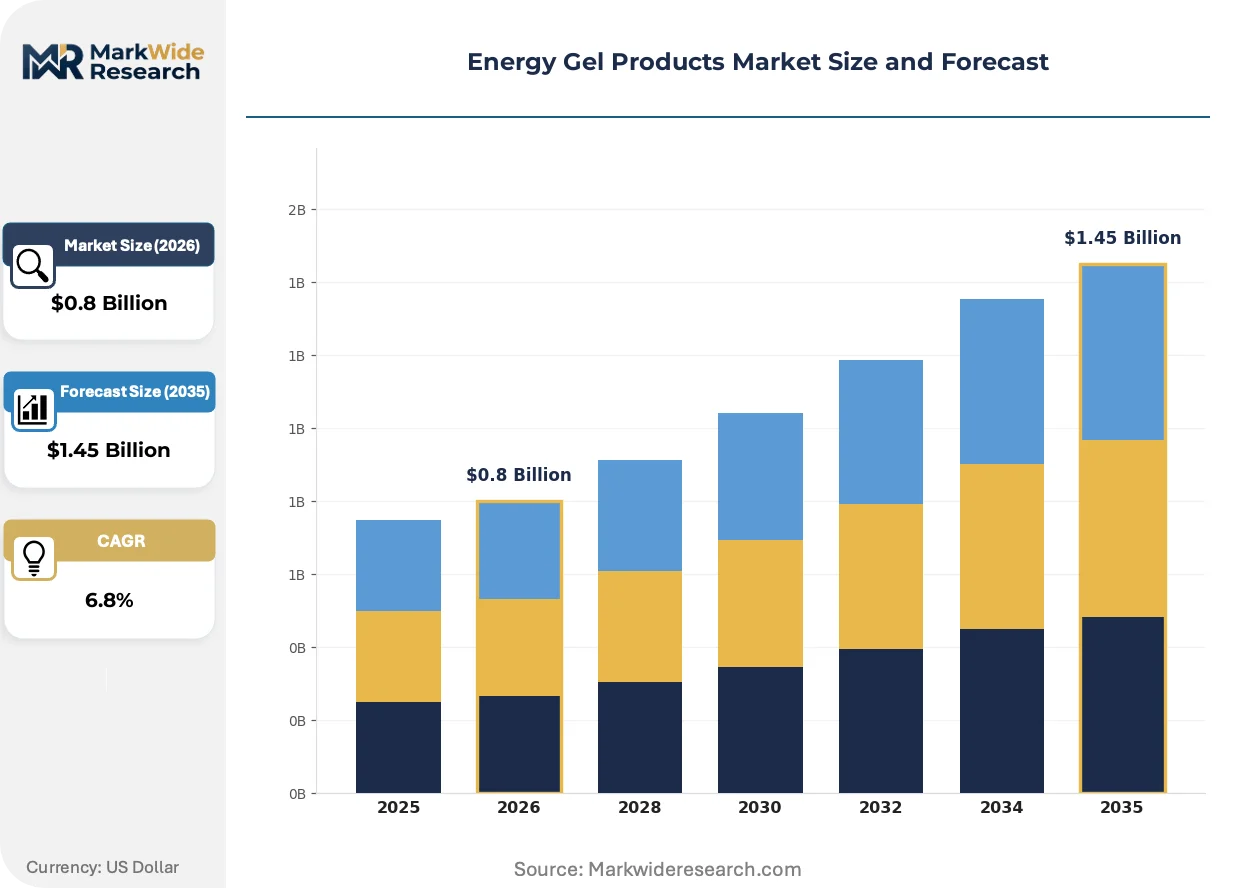
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.45 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavor, Consistency, Brand, Size Packaging Type: Pouch, Tube, Sachet, Bottle Ingredient Type: Carbohydrates, Electrolytes, Proteins, Caffeine Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Gyms |
| Companies Covered | Science in Sport, Maurten, GU Energy Labs, Huma Gel, Honey Stinger, Clif Bar & Company, Hammer Nutrition, Gatorade Company, PowerBar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Gel Products Market Emerging Trajectories
Formulation science and distribution architecture are undergoing simultaneous transformation, with hydrogel chemistry maturation and digital channel migration redefining competitive advantage parameters.
Alginate-based hydrogel technology is absorbing gastric emptying optimization research from pharmaceutical delivery systems. Ultramarathon and expedition athletes are adopting these formulations fastest, tolerating premium pricing for reduced GI distress incidence. The technology is absorbing R&D investment share previously allocated to flavor masking and texture modification.
EFSA novel food classification requirements are reshaping ingredient pre-market approval pathways for plant-derived carbohydrate sources. Manufacturers are consolidating formulation pipelines around grandfathered maltodextrin bases rather than pursuing unproven alternatives. German and French regulatory submissions are experiencing the longest review queues, compressing regional launch timelines.
Subscription-based replenishment models are displacing event-driven bulk purchasing among committed amateur athletes. Specialty running retailers in the United States are losing replenishment frequency to Strava-integrated direct-to-consumer platforms. This behavioral pivot is most pronounced among digitally native runners aged 25-40 in metropolitan coastal markets.
Energy Gel Products Market Segmentation
Energy gel manufacturers configure product portfolios across four intersecting dimensions where formulation chemistry, packaging ergonomics, and channel economics determine margin capture. Athlete-specific use cases drive divergence between mass-market accessibility and elite-performance specialization.
Product Type:
Standardization dominates flavor and size specifications while brand differentiation and texture engineering concentrate premium positioning.
- Flavor:Fruit-based profiles (berry, citrus, tropical) anchor mainstream retail velocity. Demand clusters in Germany and Japan where palate fatigue during ultramarathon events drives rotation purchasing. Clean-label mandates from EFSA are compressing artificial additive formulations and accelerating natural extract sourcing costs.
- Consistency:Viscous semisolid matrices balance rapid gastric emptying with tear-open pouch integrity. Marathon and triathlon athletes in the United States tolerate thinner consistencies for sub-threshold pacing, while expedition segments favor thicker gels that withstand thermal cycling. Hydrogel technology from pharmaceutical delivery research is reshaping texture engineering R&D allocation.
- Brand:Certified manufacturers leverage third-party verification (NSF Certified for Sport, Informed Sport) to command shelf presence. Brand equity concentrates among British Cycling partnerships and patented alginate formulations.
- Size:Standard 32-gram single-serve units dominate event-driven bulk purchasing. Ultramarathon segments tolerate premium pricing for 60-gram expedition formats.
Leading the category by volume: Flavor standardization. Growing fastest: Hydrogel-enabled consistency engineering.
Packaging Type:
Volume economics favor lightweight formats while margin premiums accrue to durability-engineered solutions for extreme conditions.
- Pouch:Tear-open ergonomics and sub-5-gram packaging weight dominate mass-market channel economics. Pouch formats capture the highest shipment volumes through specialty running retailers and Strava-integrated direct-to-consumer platforms. FDA Current Good Manufacturing Practices elevate seal-integrity testing costs for new entrants.
- Tube:Reclosable aluminum or polymer tubes command margin premiums among ultramarathon and expedition athletes requiring multi-dose portability. Tube adoption concentrates in Germany where extended producer responsibility laws are imposing packaging compliance burdens. Thermal stability under alpine conditions drives material specification divergence from pouch formats.
- Sachet:Flat laminated sachets offer cost-minimized entry formats for emerging market trial purchasing. Sachet specifications prioritize barrier properties over ergonomics.
- Bottle:Multi-serve bottles serve team sports and gym-based replenishment scenarios. Bottle formats face displacement from single-serve convenience preferences among individual endurance athletes.
Pouch configurations ship the most units. Tube formats gain share fastest in premium alpine and desert expedition segments.
Ingredient Type:
Carbohydrate chemistry maturity contrasts with stimulant and protein categories facing regulatory uncertainty and formulation stability challenges.
- Carbohydrates:Maltodextrin-fructose blends delivering 20-25 grams per serving constitute the mature revenue base. Patented alginate encapsulation in hydrogel matrices is reducing gastric distress incidence during sustained aerobic exertion. EFSA health claim substantiation protocols are consolidating formulation pipelines around grandfathered carbohydrate sources rather than novel plant-derived alternatives.
- Caffeine:Ergogenic aid claims are gaining traction in specialty retail channels. Pending FDA stimulant concentration limits are freezing new product pipeline investments. Caffeine-infused variants are climbing the fastest among ingredient categories as validated performance declarations unlock premium positioning.
- Electrolytes:Sodium and potassium fortification addresses hyponatremia risk in hot-climate endurance events. Electrolyte specification varies by target geography's typical race conditions.
- Proteins:Branched-chain amino acid inclusion targets recovery-phase positioning. Protein stability in acidic gel matrices constrains shelf-life claims.
Carbohydrate formulations generate the most revenue. Caffeine-enhanced variants are expanding most quickly pending regulatory clarity.
Distribution Channel:
Digital migration is restructuring replenishment frequency while specialty retail retains trial and education functions.
- Online Retailers:Direct-to-consumer subscription models integrated with Strava training data are capturing repeat purchase velocity. Online channels are displacing supermarkets as the primary growth vector. Digitally native runners aged 25-40 in United States metropolitan coastal markets exhibit the highest subscription adoption rates.
- Specialty Stores:Staff expertise and in-person flavor sampling sustain trial conversion for new formulations. Specialty running retailers in the United States are losing replenishment frequency to digital platforms but retaining event-driven bulk purchasing.
- Supermarkets:Mass-market accessibility depends on simplified flavor ranges and prominent shelf placement. Supermarket velocity concentrates in Japan where convenience store integration extends reach to aging masters-category athletes.
- Gyms:Point-of-workout replenishment serves strength-endurance crossover training. Gym channel economics favor smaller format sizes and impulse-display placement.
Online retailers are capturing volume leadership. Specialty stores maintain the steepest expansion trajectory in experiential retail formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marathon and triathlon participation concentrates demand in mature sports nutrition markets. Specialty retail infrastructure depth determines premium product accessibility. Regulatory stringency varies across jurisdictions, reshaping formulation compliance costs.
United States
Endurance sports registration volumes in California and New York metro areas anchor North American demand. FDA Current Good Manufacturing Practices elevate seal-integrity testing costs for pouch manufacturers. Greater Boston hosts specialty running retail clusters where Strava-integrated subscription models capture replenishment velocity from brick-and-mortar channels.
Germany
EFSA health claim substantiation protocols unlock premium positioning for validated ergogenic aid declarations. Extended producer responsibility laws impose packaging compliance burdens on tube format adoption. Bavaria's alpine sports concentration drives demand for thermal-stable formulations among expedition segments.
Japan
Masters-category endurance participation outpaces youth enrollment, creating demand for lower-osmolality formulations. METI guidance shapes food safety management standards for hydrogel matrix imports. Tokyo-Osaka corridor convenience store integration extends reach to aging athlete segments.
United Kingdom
British Cycling partnerships sustain elite-athlete credibility for certified manufacturers. Novel food classification requirements reshape ingredient pre-market approval pathways for plant-derived carbohydrate sources. London specialty retail clusters retain trial conversion functions despite digital channel migration.
Australia
TGA therapeutic goods frameworks intersect with sports nutrition classification for caffeine-infused variants. Hot-climate endurance events in Queensland drive electrolyte fortification specifications. Melbourne-Sydney corridor hosts endurance sports event calendars that sustain event-driven bulk purchasing patterns.
Energy Gel Products Market Vendor Landscape
United States producers anchor mass-market channel penetration through deep specialty retail distribution; European specialists hold premium-tier positioning through patented formulation technology. The vendor base concentrates among certified manufacturers with third-party verification infrastructure. Three archetypes dominate: hydrogel technology specialists, elite-sport partnership licensors, and direct-to-consumer subscription platforms. Geographic expansion and technology licensing represent the dominant competitive moves as regulatory barriers filter subscale entrants.
Within the hydrogel technology tier, Maurten exemplifies patented alginate encapsulation positioning. Among British-based fabricators, Science in Sport occupies a position tied to elite cycling federation partnerships. GU Energy Labs represents the American mass-market archetype with specialty retail channel anchoring.
| Leading Market Players |
|---|
| Science in Sport |
| Maurten |
| GU Energy Labs |
| Huma Gel |
| Honey Stinger |
| Clif Bar & Company |
| Hammer Nutrition |
| Gatorade Company |
| PowerBar |
| Others |
Supply Flow & Price Mechanics
Food technologist concentration in the United States Midwest and Bavaria establishes labor-cost differentials that widen pricing-tier spreads between certified hydrogel specialists and commodity maltodextrin suppliers. FDA Current Good Manufacturing Practices and EFSA novel food compliance investments compress margins at the economy tier while premium alginate formulations command sustained markups.
Pricing Analysis
Volume leadership concentrates in standard 32-gram pouch formats where per-unit transactional pricing dominates event-driven bulk purchasing, while 60-gram expedition tubes and hydrogel-enabled variants capture margin premiums through performance-tier differentiation. Price differentiation hinges on NSF Certified for Sport verification and patented encapsulation technology. Cost compression in the standard pouch tier is intensifying because fructose supply volatility from corn harvest fluctuations compresses formulation cost predictability. Amateur marathon registrants exhibit highest price sensitivity; ultramarathon and expedition athletes show least sensitivity, tolerating premium positioning for reduced gastric distress incidence.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke patterns that position inventory close to endurance event calendars and specialty retail clusters. Maltodextrin feedstock draws from corn processing facilities in the US Midwest; alginate encapsulation materials sources from pharmaceutical-grade suppliers in Japan and Europe. Single-source vulnerability in hydrogel matrix precursor supply concentrates risk among patented formulation holders. Distribution runs through Strava-integrated direct-to-consumer platforms displacing traditional wholesale-to-retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The energy gel market sits in a technology-transition phase where alginate-based hydrogel chemistry replaces legacy maltodextrin-fructose matrices as the performance benchmark. This substitution redefines competitive advantage parameters and reshapes R&D allocation across the vendor base.
For Market Incumbents: Hedge against hydrogel patent expiration exposure by diversifying formulation pipelines around electrolyte fortification and caffeine-enhanced variants pending FDA stimulant clarity. Deepen backward integration into alginate precursor supply to defend margin position against pharmaceutical-industry demand competition for encapsulation materials. For New Entrants and Emerging Players: EFSA novel food classification requirements in Germany and France open a window for grandfathered maltodextrin-based formulations in Southern European markets where regulatory review queues compress faster. Target the Japanese masters-category aging athlete segment with lower-osmolality positioning through convenience store channel partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with ISO 22000-certified manufacturers with existing third-party verification infrastructure given cross-border market access barriers filtering subscale competitors. Watch extended producer responsibility law passage in California and New York as inflection indicator for packaging compliance cost concentration among scaled producers.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogel Technology Licensing | Patented alginate encapsulation transfers pharmaceutical delivery optimization into sports nutrition performance tier. |
| Direct-to-Consumer Platform Integration | Strava training data linkage captures replenishment velocity previously held by specialty running retailers. |
| Third-Party Certification Investment | NSF Certified for Sport and Informed Sport verification filters subscale competitors from shelf presence. |
| Extended Producer Responsibility Compliance | California and New York state-level packaging laws impose cost burdens concentrating distribution leverage. |
| Clean-Label Formulation Repositioning | EFSA and FDA guidance on natural extract sourcing reshapes ingredient procurement and label transparency. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with sports nutrition brand managers, food technology R&D directors, specialty running retail buyers, and endurance event organizers. FDA Current Good Manufacturing Practices documentation, EFSA novel food submission databases, and ISO 22000 certification registries provided compliance benchmarking. Bottom-up shipment data from pouch and tube manufacturers triangulated against top-down retail audit velocity across the analysis window.
Data-stream reconciliation across product type, packaging format, ingredient category, and distribution channel dimensions generated volume and value outputs. CAGRs derived from segment-level growth rate modeling incorporating marathon participation registration trends, hydrogel adoption curves, and digital channel migration patterns. Forecast inputs included endurance sports event calendar density and extended producer responsibility law implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for hydrogel matrix stability under thermal stress would alter the outlook. Forecasts reflect documented assumptions regarding regulatory clarity on caffeine thresholds and fructose supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
South Africa Nutraceuticals Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Choline Supplement Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Garcinia Cambogia Extract Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
Health Supplements Market