
 South America Collagen Supplements Market | 2026-2036
South America Collagen Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
South America Collagen Supplements Market Analytics
Subscription-based replenishment programs is repositioning how collagen brands secure recurring revenue across South America. Rousselot leverages its bovine collagen supply chain to dominate bulk ingredient supply into Brazilian manufacturers. Gelita AG sustains competitive positioning through specialized gelatin and collagen peptide portfolios tailored to regional formulation preferences. PB Leiner anchors its presence via technical service partnerships with local private-label producers.
Collagen supplements comprise hydrolyzed animal-derived proteins—primarily Types I and III—processed through enzymatic hydrolysis to yield peptides with molecular weights below 10 kDa for enhanced bioavailability, serving joint health, skin elasticity, and muscle recovery applications. Hydrolyzed collagen and collagen peptides command the deepest margin pools due to premium positioning among beauty consumers and athletes. Powder and capsule forms lead volume throughput, while liquid collagen drinks represent the fastest-growing format as Brazilian health enthusiasts prioritize convenience.
ANVISA governs dietary supplement registration and health claim substantiation in Brazil, while Argentina's national food safety authority enforces analogous ingredient disclosure mandates; both frameworks elevate compliance costs but filter substandard imports. CSRD-aligned sustainability reporting from European parent companies increasingly influences sourcing transparency expectations among Brazilian distributors. Stakeholders must monitor regulatory divergence between Mercosur harmonization proposals and national-level enforcement intensity.
Market Dynamics
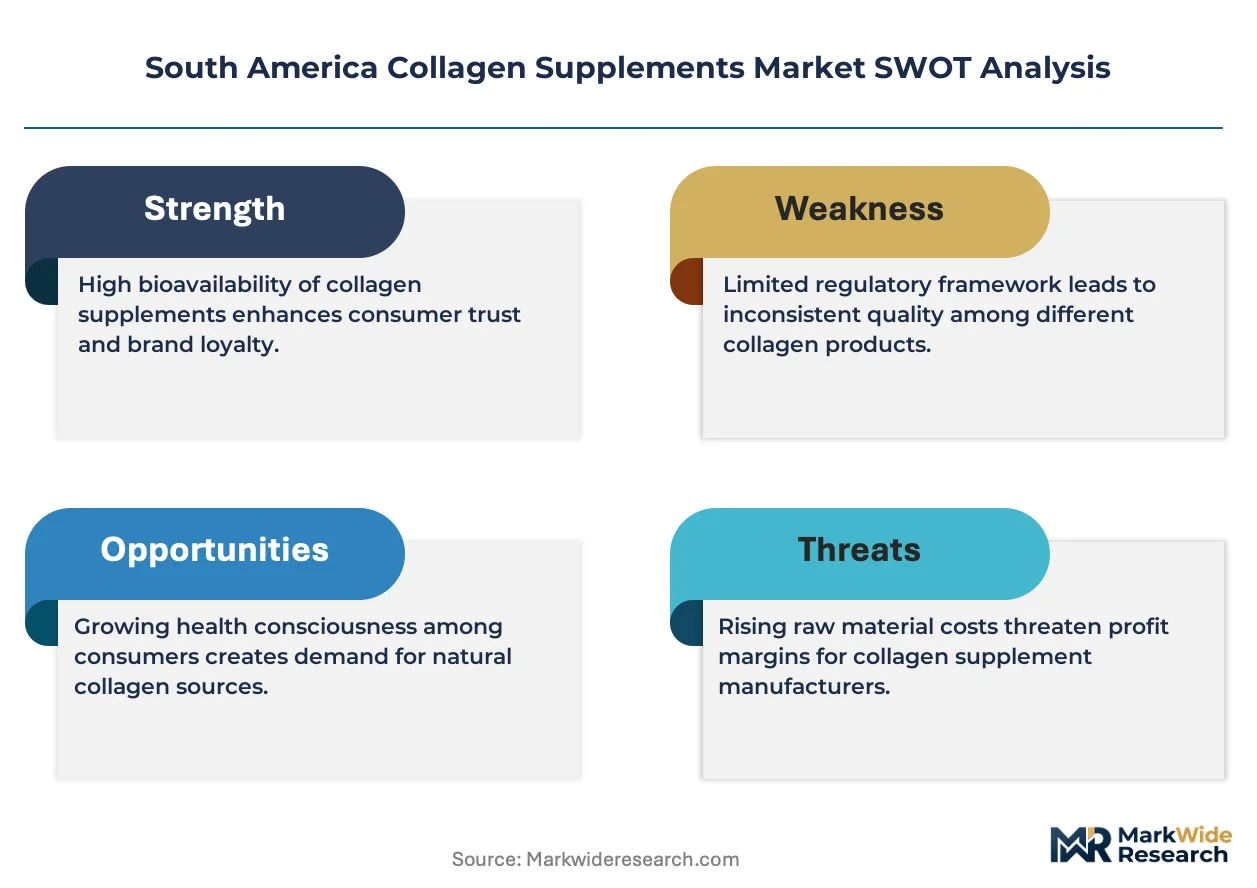
ANVISA's tightening dietary supplement registration protocols are forcing Brazilian collagen brands to restructure compliance investments and reformulation timelines, compressing margins while elevating barriers for import-dependent competitors.
Growth Catalysts
- Fitness Culture Maturation:CrossFit and functional training communities across São Paulo and Rio de Janeiro normalize daily collagen supplementation for joint recovery and tendon resilience.
- CSRD-Aligned Sourcing Transparency:European parent companies of Brazilian distributors now mandate supply chain disclosure, pushing local manufacturers toward certified sustainable bovine and marine collagen sources.
- Hydrolysis Technology Advancement:Enzymatic processing improvements yielding sub-5 kDa peptide fractions enhance bioavailability claims and justify premium positioning among beauty consumers.
Market Restraints
- Bovine Raw Material Concentration:Brazil's collagen supply depends heavily on domestic cattle byproduct streams, exposing processors to livestock cycle volatility and pastureland competition from protein exports.
- Marine Collagen Import Dependency:Tilapia and pangasius scale sourcing from Asian aquaculture operations concentrates supply risk in Vietnamese and Indonesian processing hubs.
- ANVISA Registration Timelines:Novel ingredient approvals now extend 18-24 months, freezing innovation pipelines for startups lacking legacy product portfolios.
Strategic Opportunities
- Argentina Market Underpenetration:Buenos Aires and Córdoba metropolitan areas show collagen adoption rates roughly half those of comparable Brazilian cities, presenting first-mover expansion potential.
- Liquid Collagen Convenience Pivot:Ready-to-drink formats targeting Brazilian health enthusiasts bypass powder preparation friction and command shelf-space premiums in pharmacy chains.
- Mercosur Harmonization Momentum:Pending regulatory alignment proposals could streamline cross-border product registration between Brazil, Argentina, Paraguay, and Uruguay, reducing compliance fragmentation.
Industry Challenges
- Peptide Characterization Expertise Gap:Brazilian quality control laboratories lack standardized HPLC methodologies for molecular weight distribution verification, forcing reliance on European third-party testing.
- Cold Chain Infrastructure Deficits:Liquid collagen stability requirements strain last-mile distribution networks in northeastern Brazil, where temperature-controlled logistics remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Collagen Supplements Market |
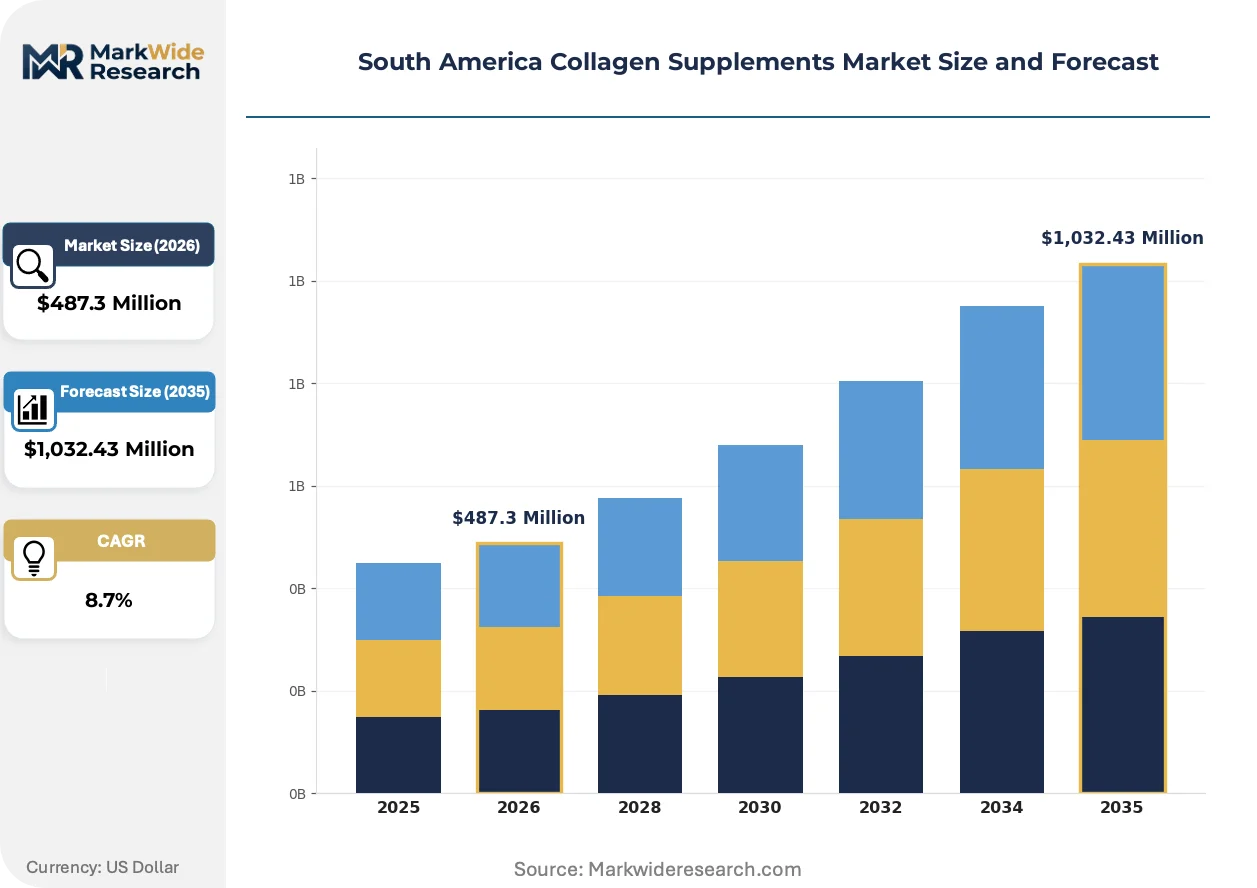
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Collagen Drinks End User: Beauty Consumers, Athletes, Health Enthusiasts, Older Adults Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies Form: Powder, Capsules, Liquid, Gummies |
| Companies Covered | Rousselot, Gelita AG, Novaprom, Hunter & Gather, Optimum Nutrition, Inc, Nitta Gelatin NA Inc, Gelnex B.V, PB Leiner, Darling Ingredients Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Collagen Supplements Market Evolving Landscape
Collagen product development is pivoting toward bioavailability optimization and format convenience, with enzymatic engineering and delivery system innovation compressing traditional powder-dominant consumption patterns.
Microencapsulation technology for collagen peptides is converging with lipid-based delivery systems to enhance intestinal absorption rates. Brazilian nutricosmetic brands now incorporate these complexes into beauty-from-within gummies and effervescent tablets. This convergence is enabling premium positioning at mass-market price points previously occupied by basic hydrolyzed powders.
ANVISA's updated Resolution RDC 423 establishes stricter health claim substantiation requirements for collagen products targeting joint and skin benefits. Manufacturers must now submit clinical trial documentation or systematic reviews supporting specific peptide efficacy. Brazilian brands with established scientific dossiers gain compliance advantages while new entrants face extended market entry timelines.
Subscription-based replenishment models now displace traditional retail purchasing among Brazilian millennial consumers. Direct-to-consumer platforms offer personalized dosing algorithms and auto-ship convenience, capturing recurring revenue streams that pharmacy and supermarket channels struggle to replicate. São Paulo's urban professional cohort drives this behavioral shift most visibly.
South America Collagen Supplements Market Segmentation
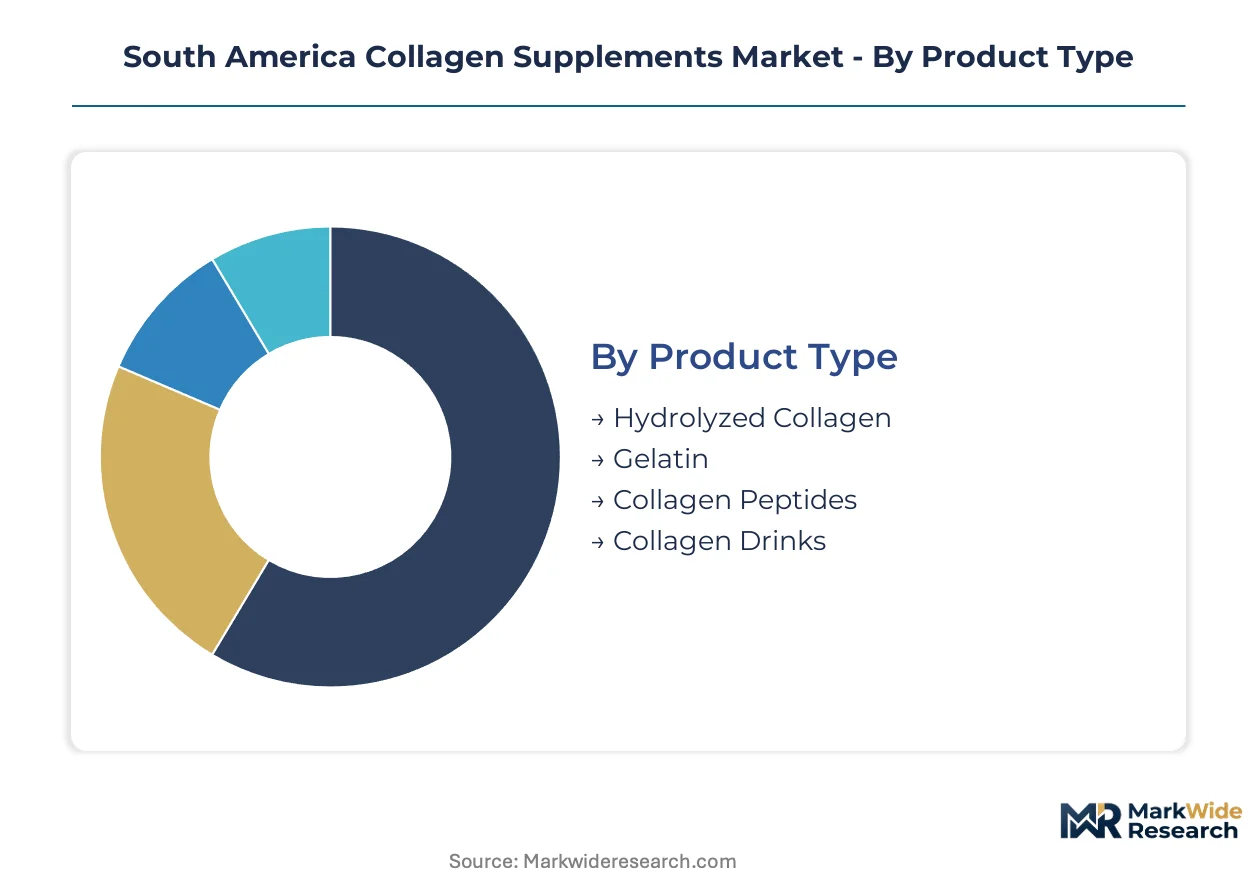
Collagen supplement segmentation across South America reflects divergent consumer priorities between efficacy-focused athletes and convenience-seeking urban professionals. Each dimension shapes formulation investments, channel economics, and regulatory compliance pathways differently.
Product Type:
Hydrolyzed collagen and collagen peptides dominate volume throughput while gelatin anchors economy-tier positioning and collagen drinks capture emerging convenience demand.
- Hydrolyzed Collagen:Enzymatically processed bovine or marine proteins yielding peptide fractions below 10 kDa molecular weight for enhanced bioavailability. Brazilian CrossFit communities across São Paulo metropolitan gyms drive bulk powder purchases for post-workout joint recovery protocols.
- Collagen Peptides:Highly refined protein fragments standardized for specific amino acid profiles, particularly glycine-proline-hydroxyproline ratios. Premium beauty consumers in Rio de Janeiro's Zona Sul district favor these for skin elasticity claims backed by clinical dossiers.
- Gelatin:Partially hydrolyzed collagen with gelling properties, typically serving food and beverage applications rather than dedicated supplementation.
- Collagen Drinks:Ready-to-consume liquid formats with flavor masking and stabilizer systems targeting pharmacy chain distribution.
Mature deployment sits with hydrolyzed collagen powders. Newer deployment is concentrated in collagen drinks.
End User:
Application-driven segmentation separates appearance-motivated consumers from performance-oriented athletes, with older adults representing an emerging clinical positioning opportunity.
- Athletes:Competitive and recreational sports participants prioritizing tendon resilience and joint recovery. Brazilian functional training box affiliates normalize daily 10g dosing protocols, creating predictable replenishment cycles.
- Beauty Consumers:Skincare-focused individuals seeking ingestible solutions for dermal hydration and wrinkle reduction. Argentine urban professionals in Buenos Aires show adoption rates roughly half those of comparable Brazilian cohorts, signaling expansion headroom.
- Health Enthusiasts:General wellness seekers incorporating collagen into broader supplement stacks without sport-specific or cosmetic targeting.
- Older Adults:Age-related joint health and mobility maintenance applications, currently underdeveloped relative to Asian markets.
Volume concentration favors athletes. Steepest expansion trajectory belongs to beauty consumers.
Distribution Channel:
Channel selection determines margin capture, with direct-to-consumer platforms displacing traditional retail among digitally native demographics.
- Online Retail:E-commerce platforms and brand-direct subscription models capturing recurring revenue through auto-ship algorithms. São Paulo's professional cohort drives this behavioral shift most visibly, bypassing pharmacy price premiums.
- Pharmacies:Brick-and-mortar drugstore chains with trained staff consultation, commanding shelf-space premiums for liquid and premium peptide formats.
- Supermarkets:Mass-market grocery channels moving economy-tier powders and gelatin products.
- Specialty Stores:Sports nutrition retailers and beauty boutiques with curated assortments and staff expertise.
Established infrastructure sits with pharmacies. Channel investment is flowing toward online retail.
Form:
Format innovation compresses traditional powder dominance as convenience and palatability drive switching behavior among urban consumers.
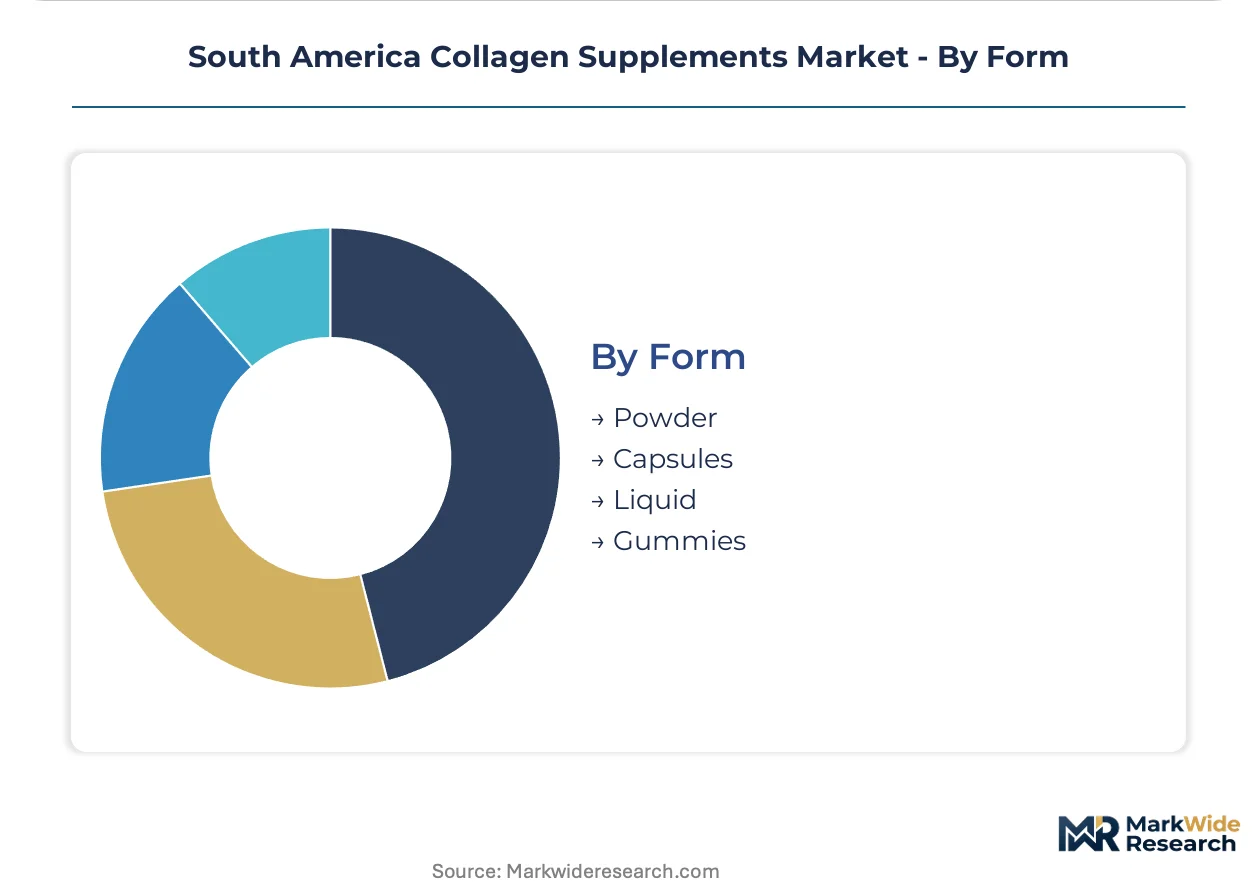
- Powder:Unflavored or flavored bulk formats allowing dose customization, remaining the cost-efficient default for committed users.
- Liquid:Single-serve bottles and shots with stability challenges requiring temperature-controlled logistics, currently gaining share fastest in Brazil's southeastern corridor.
- Capsules:Pre-measured dosing for travel and discretion, appealing to older demographics and professional travelers.
- Gummies:Confectionery-format delivery with collagen-peptide microencapsulation, targeting younger beauty consumers and pill-averse segments.
Format maturity centers on powder. Gummies and liquid formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors South American collagen demand through its metropolitan corridor, where fitness culture and beauty retail density concentrate purchasing power. Brazil's southeastern states generate the majority of regional volume, while Argentina, Chile, Colombia, and Peru present staged expansion opportunities with distinct regulatory and consumer profiles.
Brazil
CrossFit affiliates across São Paulo and Rio de Janeiro normalize daily collagen dosing protocols, creating predictable replenishment cycles among urban professionals. ANVISA's Resolution RDC 423 mandates clinical substantiation for joint and skin health claims, extending registration timelines to 18-24 months for novel ingredients. The southeastern metropolitan corridor spanning São Paulo state and Rio de Janeiro concentrates manufacturing infrastructure and pharmacy chain distribution.
Argentina
Buenos Aires and Córdoba metropolitan areas show collagen adoption rates roughly half those of comparable Brazilian cities, signaling first-mover expansion headroom for beauty-positioned brands. The national food safety authority enforces ingredient disclosure mandates analogous to Brazilian frameworks, elevating compliance costs for imported finished goods. Urban professionals in Palermo and Recoleta districts drive nutricosmetic trial through pharmacy and specialty retail channels.
Chile
Santiago's affluent consumer base demonstrates early receptivity to premium marine collagen formats targeting skin hydration claims. The country's pharmaceutical regulator maintains stringent import documentation requirements for dietary supplements, filtering substandard products from Asian sourcing hubs. Vitacura and Las Condes municipalities concentrate specialty retail and direct-to-consumer brand presence.
Colombia
Bogotá's expanding middle class exhibits rising interest in sports nutrition applications, particularly among functional training communities in the northern districts. National health authority registration pathways remain less burdensome than Brazilian ANVISA protocols, attracting regional distributors seeking faster market entry. The Sabana Centro corridor hosts emerging private-label manufacturing partnerships with Brazilian ingredient suppliers.
Peru
Lima's coastal urban population represents nascent demand concentrated in pharmacy chains and emerging e-commerce platforms. The national health institute's evolving supplement classification system creates regulatory uncertainty for collagen peptide products positioned between food and pharmaceutical categories. Miraflores and San Isidro districts concentrate early adopter households with disposable income for imported premium formats.
South America Collagen Supplements Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South America's collagen landscape, with integrated bovine processors holding supply-side leverage over formulation-focused brands. The market structure tiers between bulk ingredient suppliers commanding raw material economics and finished goods marketers capturing retail margin. Three archetypes dominate: European-headquartered collagen peptide specialists, Brazilian private-label manufacturers, and direct-to-consumer wellness platforms. Competitive intensity centers on enzymatic hydrolysis capabilities and ANVISA registration dossier depth, with strategic partnerships and geographic expansion representing the dominant competitive moves.
Within the European-headquartered tier, Rousselot and Gelita AG exemplify capital-intensive positioning through bovine supply chain control and specialized peptide portfolios. PB Leiner occupies a position anchored in technical service partnerships with regional private-label producers. These three entities represent the upstream concentration that shapes downstream pricing and formulation availability across Brazilian and Argentine manufacturing.
| Leading Market Players |
|---|
| Rousselot |
| Gelita AG |
| Novaprom |
| Hunter & Gather |
| Optimum Nutrition, Inc |
| Nitta Gelatin NA Inc |
| Gelnex B.V |
| PB Leiner |
| Darling Ingredients Inc. |
| Others |
Value Network & Pricing Analysis
Bovine hide and bone procurement costs cascade through South America's collagen supply chain, with Brazilian cattle byproduct streams anchoring upstream economics and enzymatic hydrolysis sophistication determining downstream price tier placement. ANVISA registration dossier depth and peptide molecular weight certification separate premium positioning from commodity-grade competition.
Pricing Analysis
Outcome-based pricing tied to bioavailability claims anchors collagen peptide premiums, with sub-5 kDa molecular weight fractions commanding the highest tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and clinical dossier completeness. Cost compression in standard-tier hydrolyzed powders intensifies as Brazilian private-label manufacturers expand capacity. Beauty consumers in Rio de Janeiro's Zona Sul district show the lowest price sensitivity, while mass-market athletes in São Paulo's functional training communities drive volume at economy positioning.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-sensitive liquid collagen returns remains undeveloped across northeastern Brazil, forcing write-offs rather than refurbishment flows. Upstream concentration centers on Brazilian cattle processing hubs and Vietnamese tilapia scale operations. Enzymatic hydrolysis equipment and HPLC verification capabilities draw from European and North American suppliers. Single-source vulnerability in marine collagen feedstock from Asian aquaculture operations exposes margin volatility. Distribution runs through pharmacy chain consolidation in the southeastern metropolitan corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America's collagen market has become a vertical-integration race, with upstream bovine supply control and downstream direct-to-consumer channel ownership representing the decisive levers for margin capture.
For Market Incumbents: Cement supply security through captive bovine processing partnerships in São Paulo state and Paraná, insulating against livestock cycle volatility. Deepen ANVISA registration dossiers for novel peptide fractions to extend compliance moats against import-dependent challengers. CrossFit affiliate channel control and subscription auto-ship algorithms defend recurring revenue against pharmacy chain price competition. For New Entrants and Emerging Players: ANVISA's Resolution RDC 423 in Brazil opens a window for clinical-trial-backed positioning in liquid collagen formats, where registration barriers filter legacy powder competitors. Argentina's Buenos Aires metropolitan area presents the most penetrable geography, with adoption rates trailing comparable Brazilian cities by half. Direct-to-consumer platforms with personalized dosing algorithms offer the clearest go-to-market angle for bypassing established pharmacy distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor Brazilian private-label manufacturers with ANVISA-approved peptide portfolios and existing Rousselot or Gelita supply agreements. Long-term viability hinges on backward integration into certified sustainable bovine sourcing and CSRD-aligned transparency reporting. Watch for Mercosur harmonization momentum as the signal for cross-border scale economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Bovine Sourcing | Captive supply from São Paulo state processors secures margin against livestock export competition. |
| Direct-to-Consumer Platform Launch | Subscription auto-ship algorithms capture recurring revenue that pharmacy channels cannot replicate. |
| ANVISA Registration Dossier Expansion | Clinical substantiation for sub-5 kDa peptide claims extends compliance moats against import entrants. |
| Liquid Collagen Format Introduction | Ready-to-drink convenience commands shelf-space premiums in Brazilian pharmacy chains. |
| Argentina Geographic Expansion | First-mover positioning in Buenos Aires leverages underpenetrated beauty-consumer adoption gaps. |
Research Methodology
ANVISA regulatory filings, Brazilian customs trade records, and pharmaceutical distributor procurement databases formed the secondary backbone for market sizing. Primary interviews with collagen peptide R&D directors, ANVISA regulatory consultants, pharmacy chain category buyers, and CrossFit affiliate owners validated demand assumptions. Bottom-up volume triangulation across powder, liquid, capsule, and gummy formats converged with top-down value estimates from ingredient supplier revenue disclosures.
Historical trendline analysis of Brazilian dietary supplement registration timelines and collagen peptide import volumes established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type, end-user application, distribution channel, and regional metropolitan cluster dimensions. CAGRs derived from weighted average of volume trajectory and price evolution assumptions, with enzymatic hydrolysis technology advancement and ANVISA compliance cost inflation as key forecast inputs.
Caveats apply where ANVISA registration timeline extensions, Mercosur harmonization delays, or marine collagen supply disruptions from Asian aquaculture could materially shift the outlook. Forecasts reflect assumptions about fitness culture maturation and subscription commerce penetration that remain sensitive to macroeconomic conditions in Brazil and Argentina. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Camu Camu Extract Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Omega 3 Market