
 Health Supplements Market | 2026-2036
Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Health Supplements Market Outlook
FDA's New Dietary Ingredient notification requirements is recalibrating the cost-of-entry calculus for supplement manufacturers, forcing smaller entrants to absorb heavier compliance burdens. Nestlé Health Science leverages its pharmaceutical-grade manufacturing infrastructure to navigate these thresholds with relative ease. Abbott Laboratories anchors its position through science-backed clinical validation protocols that preempt regulatory scrutiny. Glanbia PLC specializes in sports nutrition formulations, differentiating through third-party certification programs that exceed baseline federal requirements.
Health supplements comprise biologically active compounds—including vitamins, minerals, amino acids, botanical extracts, and probiotic cultures—formulated into dosage forms intended to augment dietary intake and support physiological functions. Manufacturing employs granulation, encapsulation, and cold-press tableting to preserve thermolabile bioactive integrity through shelf life. Vitamins and protein powders occupy the largest revenue pools, reflecting established consumer familiarity and repeat purchase behavior. Gummies represent the fastest-expanding delivery mode, displacing traditional pills among younger demographics who prioritize palatability and convenience. Athletes and fitness enthusiasts concentrate margin-rich demand for performance-positioned formulations with specialized amino acid profiles.
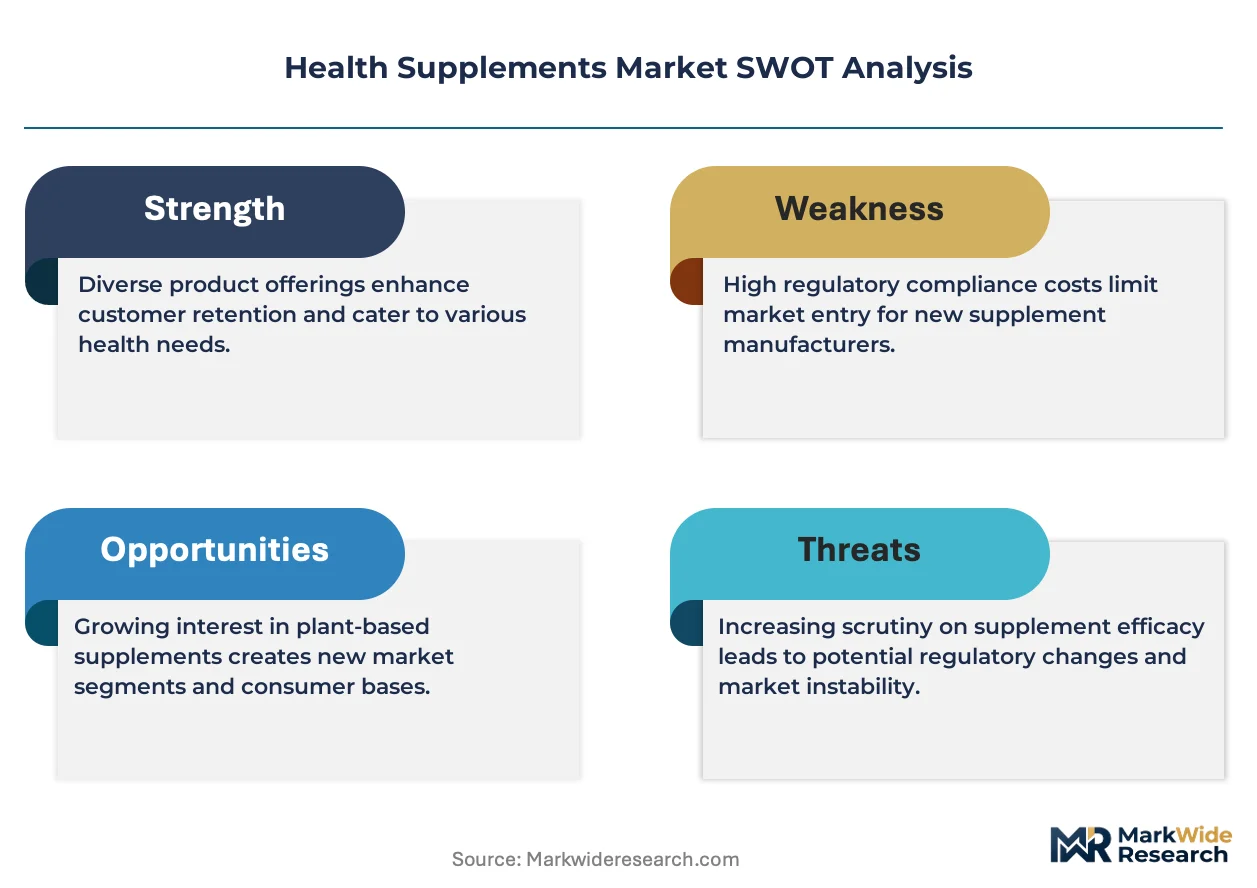
FDA's Current Good Manufacturing Practice regulations, alongside NSF International certification standards and USP verification protocols, collectively govern product quality, label accuracy, and contaminant thresholds across domestic commerce. These frameworks elevate compliance costs but simultaneously create competitive shelter for operators with validated quality systems and transparent supply chains. Stakeholders must monitor emerging state-level labeling mandates and potential pre-market notification expansions that could reshape competitive dynamics irrespective of federal policy inertia.
Market Dynamics
FDA's New Dietary Ingredient notification framework is recalibrating entry economics, forcing capital reallocation toward compliance infrastructure and away from R&D velocity. This structural pressure favors scaled operators with validated quality systems.
Growth Catalysts
- Aging Demographics:Senior populations in the United States and Japan prioritize preventive wellness regimes, expanding the addressable consumer base for condition-specific formulations targeting cardiovascular and cognitive health.
- CGMP Harmonization:FDA's Current Good Manufacturing Practice regulations elevate baseline quality thresholds, creating competitive shelter for operators with transparent supply chains and third-party certifications.
- Direct-to-Consumer Subscriptions:Pharmacy retail integration and recurring revenue models deepen product penetration among convenience-seeking households in urban United States markets.
Market Restraints
- Input Cost Volatility:Botanical extract prices fluctuate with climate-dependent harvest yields in India and China, compressing margin predictability for natural-positioned portfolios.
- Regulatory Friction:FDA's evolving enforcement framework around structure-function claims creates litigation exposure and label revision costs for marketing-heavy entrants.
- Substitution Threat:Food fortification programs and functional beverage innovation in Western Europe divert consumer spending from standalone supplement formats.
Strategic Opportunities
- Underpenetrated Markets:India's FSSAI regulatory maturation is opening organized retail channels for standardized formulations previously confined to unregulated traditional medicine markets.
- Technology Convergence:Microbiome sequencing and AI-driven personalization are enabling bespoke probiotic blends targeting individual gut profiles.
- Channel Innovation:Telehealth platforms in Brazil are integrating supplement recommendations into prescription workflows, creating embedded distribution access.
Industry Challenges
- Certification Timeline Compression:NSF International and USP verification protocols demand 12-18 month validation cycles that delay product launches and tie up working capital.
- Supply Chain Reconfiguration:Reliance on single-source gelatin suppliers for encapsulation creates vulnerability to animal-disease outbreaks and religious certification conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Supplements Market |
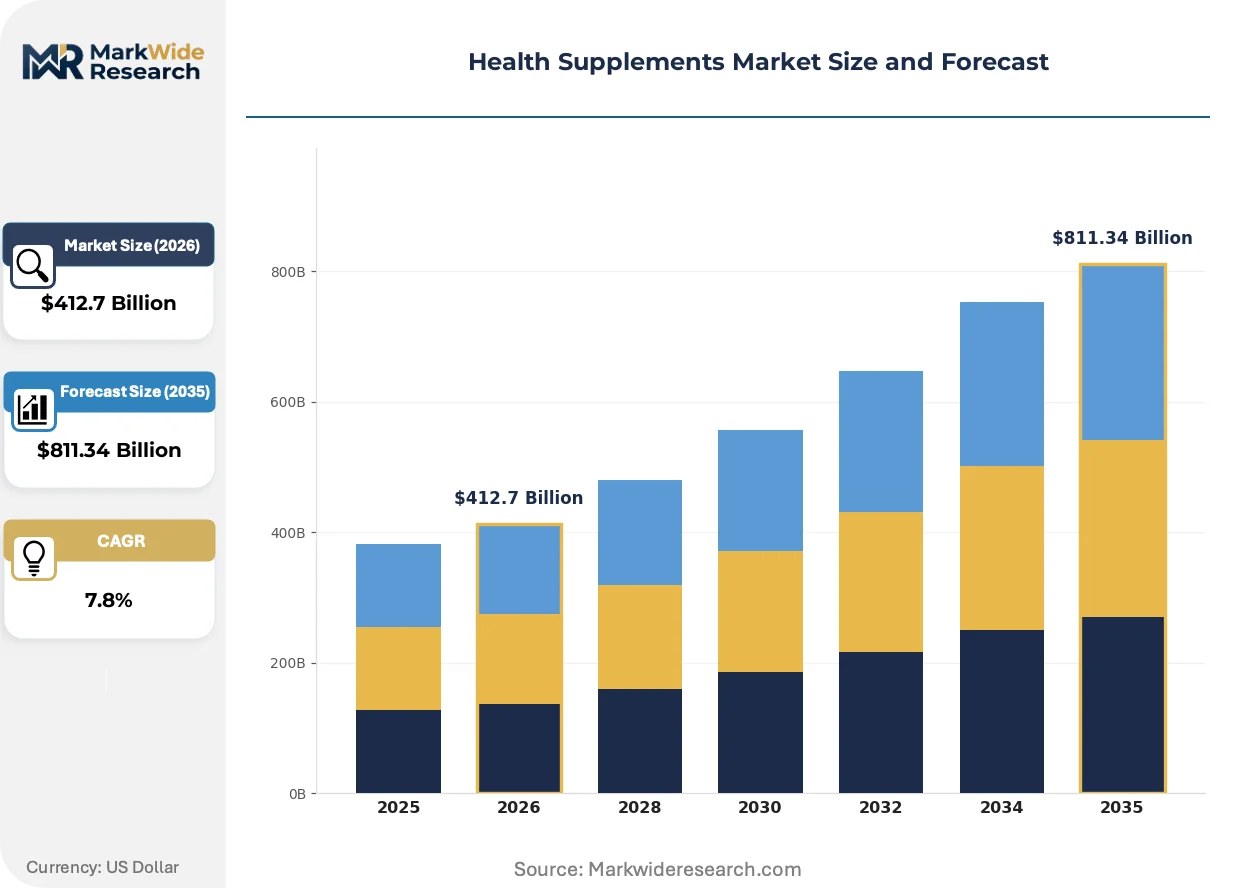
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $811.34 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Protein Powders, Herbal Extracts Delivery Mode: Pills, Powders, Gummies, Liquids End User: Athletes, Seniors, Busy Professionals, Fitness Enthusiasts Packaging Type: Bottles, Pouches, Blisters, Jars |
| Companies Covered | Nestlé Health Science, Abbott Laboratories, Amway Corporation, Glanbia PLC, Herbalife Nutrition Ltd., Bayer AG, Haleon plc, GNC Holdings, Otsuka Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Supplements Market Strategic Shifts
Delivery format innovation and regulatory technology adoption are restructuring how bioactive compounds reach consumers. These shifts compress development timelines while raising quality assurance stakes.
Liposomal encapsulation technology is absorbing investment across premium vitamin portfolios. Wellness-focused millennials in the United States and Germany are adopting these formulations at accelerating rates despite 40-60% price premiums. This absorption pattern is compressing market share for standard tablet formats in the beauty-from-within and immune support categories.
REACH registration requirements for novel botanical extracts are tightening substance documentation obligations across EU commerce. Industrial consequence includes forced reformulation of legacy products containing unregistered plant matrices. Sports nutrition applications face the steepest compliance burden, with German and French operators accelerating substitution toward GRAS-status compounds.
Subscription-based replenishment models are displacing pharmacy impulse purchases among chronic-condition managers. Direct-to-consumer platforms in the United States and United Kingdom are capturing recurring revenue from diabetes and cardiovascular supplement users. This behavioral shift concentrates customer lifetime value with digital-native brands while eroding traditional retail foot traffic.
Health Supplements Market Segmentation
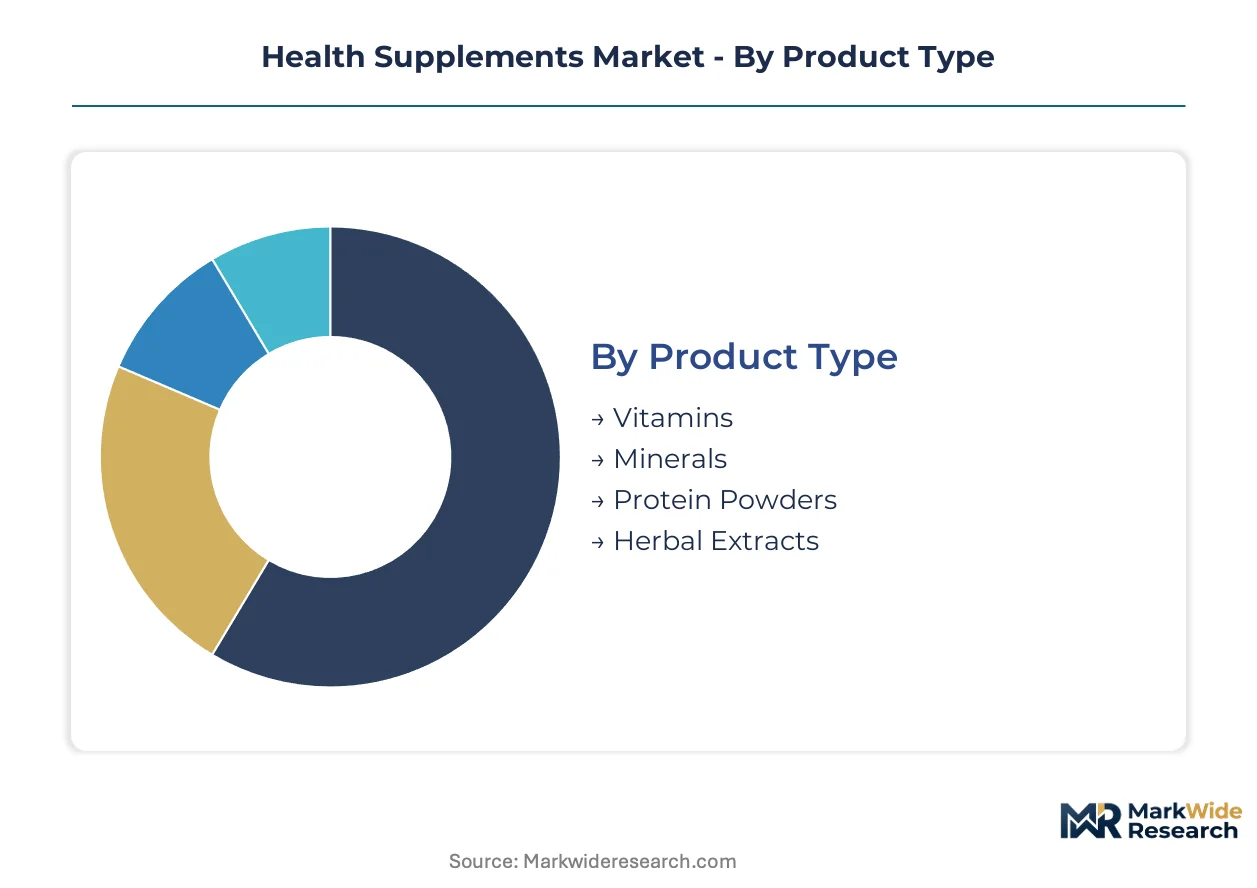
Segmentation in health supplements reveals distinct manufacturing requirements and channel economics across product categories. Delivery formats and packaging configurations determine shelf-life engineering, while end-user profiles shape formulation complexity and price positioning.
Product Type:
Standalone vitamin and mineral formulations operate as commodity-adjacent segments with established supply chains, while protein powders and herbal extracts embed into functional food systems and condition-specific wellness protocols.
- Vitamins:Synthetic and natural isolates including fat-soluble (A, D, E, K) and water-soluble (B-complex, C) compounds. Demand concentrates among senior consumers in the United States and Japan pursuing preventive cardiovascular and cognitive health regimens, with FDA CGMP compliance creating competitive shelter for validated manufacturers.
- Minerals:Chelated and inorganic forms including calcium, magnesium, zinc, and iron compounds. Athletes and fitness enthusiasts in Germany and the United Kingdom drive margin-rich demand for bioavailable mineral complexes targeting electrolyte replacement and bone density maintenance.
- Protein Powders:Whey, casein, plant-based, and collagen hydrolysate formulations.
- Herbal Extracts:Standardized botanical concentrates including ashwagandha, turmeric, and ginseng matrices.
Volume placements concentrate in Vitamins; the faster expansion belongs to Protein Powders.
Delivery Mode:
Cost tier stratification separates premium-positioned liposomal liquids and gummies from economy-standard tablets and bulk powders, with manufacturing complexity and packaging requirements driving price differentiation.
- Pills:Compressed tablets and two-piece hard-shell capsules employing granulation and encapsulation processes. Seniors in Japan and the United States sustain repeat purchase behavior for condition-specific cardiovascular and joint health formulations, though palatability limitations accelerate share loss among younger demographics.
- Powders:Bulk and single-serve sachet formats requiring moisture-barrier packaging and flow-agent engineering. Fitness enthusiasts and athletes in the United States and Brazil concentrate demand for branched-chain amino acid and creatine monohydrate products with transparent supply chain documentation.
- Gummies:Gelatin and pectin-based chewable matrices with flavor masking and stability challenges.
- Liquids:Liposomal suspensions and tinctures with enhanced bioavailability claims.
Production volume favors Pills; Gummies are climbing the fastest among convenience-seeking millennial households.
End User:
Application context distinguishes performance-optimization segments from maintenance-oriented consumption, with clinical validation requirements and channel access varying sharply across user profiles.
- Athletes:Competitive and recreational performers requiring NSF Certified for Sport or Informed Sport verification. Demand concentrates in the United States and Australia for banned-substance-tested formulations, with procurement shifting toward direct-to-consumer subscription platforms to ensure batch consistency.
- Seniors:Aging populations prioritizing preventive wellness and polypharmacy management. Cardiovascular, cognitive, and bone health formulations dominate purchasing in Japan and the United States, with pharmacy retail integration deepening product penetration among Medicare-eligible households.
- Busy Professionals:Time-constrained urban consumers seeking convenience formats.
- Fitness Enthusiasts:Recreational exercisers pursuing body composition and recovery goals.
Revenue concentration sits with Seniors; the steepest expansion trajectory belongs to Athletes as sports nutrition mainstreams.
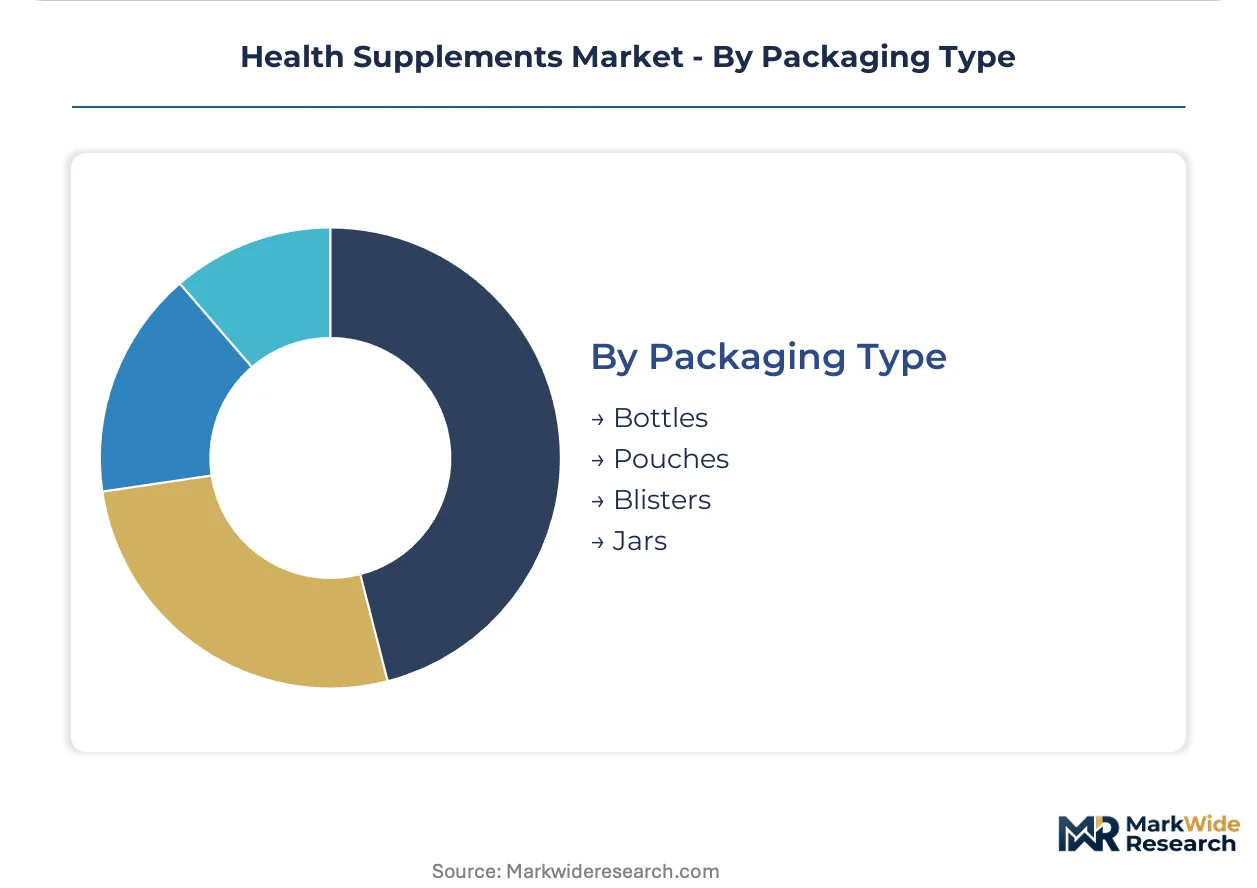
Packaging Type:
Supply concentration in pharmaceutical-grade bottle manufacturing and flexible film conversion creates geographic clustering of packaging procurement, with sustainability mandates reshaping material specifications.
- Bottles:HDPE and PET containers with desiccant integration and child-resistant closures. Pharmacy retail and mass-market channels in the United States and Germany standardize on bottle formats for vitamin and mineral portfolios, with post-consumer recycled content mandates from EFSA-aligned jurisdictions forcing material requalification.
- Pouches:Multi-layer flexible films with high-barrier metallization or aluminum lamination. Direct-to-consumer subscription models in the United Kingdom and Australia favor pouch formats for protein powder and powdered botanical deliveries, reducing shipping cube and enabling portion-controlled dosing.
- Blisters:Cold-form aluminum and PVC thermoformed units for unit-dose compliance packaging.
- Jars:Wide-mouth containers for scoop-accessed powder and gummy formats.
Unit volume concentrates in Bottles; Pouches are gaining share fastest through e-commerce channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for health supplements concentrates in the United States, where direct-to-consumer subscription models and pharmacy retail integration deepen product penetration. Aging demographics in Japan and Germany sustain preventive wellness purchasing, while emerging regulatory frameworks in India and Brazil reshape competitive access.
United States
Senior consumers and fitness enthusiasts drive dual demand streams for cardiovascular formulations and sports nutrition products. FDA's Current Good Manufacturing Practice regulations elevate compliance costs, creating competitive shelter for operators with validated quality systems. Utah and California host dense clusters of contract manufacturers and direct-to-consumer brands scaling subscription fulfillment infrastructure.
Japan
Aging populations prioritize preventive wellness regimes targeting cognitive and bone health outcomes. Japan's Ministry of Health, Labour and Welfare maintains strict FOSHU (Foods for Specified Health Uses) certification requirements that extend product development timelines. The Kanto region surrounding Tokyo concentrates domestic formulation R&D and specialized retail pharmacy networks serving polypharmacy households.
Germany
Athletes and recreational fitness consumers concentrate margin-rich demand for banned-substance-tested formulations with transparent supply chains. REACH registration requirements for novel botanical extracts tighten substance documentation obligations, forcing reformulation of legacy products. Bavaria and North Rhine-Westphalia anchor pharmaceutical-grade manufacturing infrastructure serving EU-wide distribution.
India
Middle-class urban households expand adoption of standardized formulations previously confined to unregulated traditional medicine markets. FSSAI regulatory maturation opens organized retail channels for quality-assured domestic and imported products. Maharashtra and Karnataka host emerging contract manufacturing clusters supporting both export-oriented and domestic-label production.
Brazil
Telehealth platforms integrate supplement recommendations into prescription workflows, creating embedded distribution access for chronic-condition managers. ANVISA maintains evolving registration requirements that extend market entry timelines for foreign entrants. São Paulo and Rio de Janeiro concentrate pharmacy retail chains and direct-to-consumer logistics infrastructure serving Southeast population centers.
Health Supplements Market Competitive Environment
United States producers anchor one tier; European specialists hold differentiated positions through pharmaceutical-grade manufacturing infrastructure. The vendor base fragments across science-backed clinical validators, sports nutrition formulators, and direct-to-consumer digital natives. Three strategic archetypes dominate: multinational nutrition conglomerates with validated quality systems, specialized sports nutrition operators with third-party certification programs, and subscription-native brands with embedded customer data platforms. Competitive dynamics center on M&A consolidation of niche formulators and capacity expansion into microbiome-personalized production lines.
Within the multinational tier, Nestlé Health Science and Abbott Laboratories exemplify operators leveraging pharmaceutical-grade infrastructure to navigate FDA compliance thresholds with relative ease. Glanbia PLC occupies a specialist position in sports nutrition formulations, differentiating through certification programs that exceed baseline federal requirements. These three anchors represent distinct competitive vectors: conglomerate scale, clinical validation depth, and athletic-community credibility.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Abbott Laboratories |
| Amway Corporation |
| Glanbia PLC |
| Herbalife Nutrition Ltd. |
| Bayer AG |
| Haleon plc |
| GNC Holdings |
| Otsuka Holdings Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up contract manufacturers in Utah and California concentrate ownership of encapsulation and tableting capacity, enabling disciplined pricing through volume commitments to branded marketers while compressing margins for independent formulators lacking scale leverage.
Pricing Analysis
Short lead-time premiums of 15-25% apply to rush orders for NSF Certified for Sport formulations, while spot inventory of standard vitamin tablets clears at discounted rates through pharmacy wholesale channels. Three-tier pricing structure across premium liposomal liquids, standard compressed tablets, and economy bulk powders reflects certification grade and bioavailability claims. Cost compression in botanical extracts is intensifying because climate-dependent harvest yields in India fluctuate unpredictably. Chronic-condition managers in Medicare-eligible households demonstrate lowest price sensitivity, while convenience-seeking millennials in urban markets arbitrage aggressively across subscription platforms.
Supply Chain Analysis
Ocean freight cost volatility from China and India to United States West Coast ports directly shapes landed costs for gelatin encapsulation materials and standardized herbal matrices. Raw material sourcing draws from Chinese vitamin precursor manufacturers, Indian botanical extract processors, and Brazilian probiotic culture suppliers. Single-source vulnerability concentrates in animal-derived gelatin supply chains, where religious certification conflicts and disease outbreak risks create disruption exposure. Distribution runs through direct-to-consumer subscription fulfillment centers in Utah and California, bypassing traditional pharmacy wholesale tiers for recurring revenue customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health supplements constitute a vertical-integration race where captive control over pharmaceutical-grade manufacturing infrastructure separates scaled operators from marketing-dependent entrants exposed to FDA compliance cost inflation.
For Market Incumbents: Anchor market position through backward integration into probiotic culture banking and cold-chain distribution networks, insulating against ANVISA registration delays affecting Brazilian import-dependent competitors. Defend margin structure by acquiring third-party certification capacity in-house, reducing NSF International validation cycle exposure that delays product launches for smaller rivals. For New Entrants and Emerging Players: Enter via India's FSSAI-maturing organized retail channels, where middle-class urban households transition from unregulated traditional medicine toward standardized formulations with transparent supply chains. White-space concentration sits with microbiome-personalized probiotic blends targeting individual gut profiles, enabled by AI-driven personalization platforms with lower capital requirements than pharmaceutical-grade manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor sports nutrition specialists with Informed Sport verification infrastructure in Germany and Australia, where REACH registration burdens force smaller competitors toward exit. Long-term viability hinges on embedded customer data platforms capturing recurring subscription revenue with predictable lifetime value metrics. Watch FDA pre-market notification expansion proposals as the critical inflection signal for compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Manufacturing Scale-Up | Nestlé Health Science leverages validated quality systems to absorb FDA New Dietary Ingredient compliance costs that burden smaller entrants. |
| Direct-to-Consumer Subscription Platform Launch | Digital-native brands capture recurring revenue from diabetes and cardiovascular supplement users, eroding traditional pharmacy foot traffic. |
| Third-Party Certification Investment | Glanbia PLC differentiates sports nutrition portfolios through NSF Certified for Sport programs exceeding baseline federal requirements. |
| Microbiome Personalization Technology Integration | AI-driven bespoke probiotic blends target individual gut profiles, compressing development timelines while raising quality assurance stakes. |
| Backward Integration into Gelatin Encapsulation | Captive supply of pharmaceutical-grade capsule materials mitigates single-source vulnerability to animal-disease outbreaks and religious certification conflicts. |
Study Parameters
Document review covered FDA warning letters, NSF International certification databases, and FSSAI registration filings, complemented by interviews with contract manufacturing executives, regulatory affairs directors at branded marketers, pharmacy retail category buyers, and direct-to-consumer fulfillment operations managers. Secondary validation drew from customs import records, USP verification protocols, and clinical trial registries for structure-function claim substantiation. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments across Utah and California manufacturing clusters.
Cross-referencing historical volume trajectories against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end-user application, packaging configuration, and regional regulatory maturity tier. CAGRs derived from trend-line extrapolation of senior demographic purchasing patterns and sports nutrition mainstreaming velocity, calibrated against input cost indices for botanical extracts and protein isolates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA pre-market notification expansion or FSSAI enforcement acceleration scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Sea Moss Supplements Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market