
 Europe Omega-3 Products Market | 2026-2036
Europe Omega-3 Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Omega-3 Products Market Foresight
Sports nutrition buyers are reorganizing the Europe omega-3 demand landscape as endurance athletes and CrossFit practitioners shift from general wellness positioning to performance-recovery claims. BASF SE anchors its position through captive algal oil fermentation technology in Germany. Croda International PLC specializes in high-concentration EPA/DHA esters for pharmaceutical-grade applications. Royal DSM competes via its life'sOMEGA portfolio targeting clean-label vegan formulations across Nordic markets.
Europe omega-3 products comprise concentrated long-chain polyunsaturated fatty acids—principally eicosapentaenoic acid and docosahexaenoic acid—extracted through molecular distillation or supercritical CO2 processing from marine biomass, then stabilized against oxidation for human and animal consumption. Fish oil dominates volume throughput due to established triglyceride conversion infrastructure and cost-efficient raw material access from North Atlantic fisheries. Algal oil captures margin expansion as vegan certification and allergen-free positioning command pharmacy-tier pricing in Germany and the Netherlands. Softgel delivery leads unit sales through pharmacy and health store channels, while liquid formats gain traction in pediatric and geriatric segments seeking dose flexibility.
EFSA novel food assessments and REACH compliance for marine lipid derivatives shape ingredient approval timelines and label claim permissibility across EU member states. The EU Green Deal fisheries sustainability criteria and F-Gas Regulation restrictions on processing refrigerants are tightening supply chain environmental disclosures for omega-3 manufacturers. Stakeholders must monitor ECHA biocidal substance reviews affecting preservation systems in liquid formulations and prepare for CSRD-aligned supply chain reporting obligations that will differentiate compliant suppliers from opaque traders.
Market Dynamics
EFSA novel food approvals for algal DHA sources are compressing ingredient qualification timelines from years to months, enabling pharmacy chains and direct-to-consumer brands to accelerate SKU expansion across Germany and Nordic markets.
Growth Catalysts
- Sports nutrition demand:Endurance athletes and CrossFit practitioners are shifting from general wellness positioning to performance-recovery claims, forcing brands to reformulate omega-3 SKUs with higher EPA ratios.
- EFSA novel food streamlining:The assessment pathway for algal-sourced DHA is reducing regulatory friction for vegan-certified products entering German pharmacy channels.
- Clean-label convergence:Germany's pharmacy chains are building dedicated omega-3 shelf space to capture allergen-free and vegan-certified premiums.
Market Restraints
- Fish oil supply concentration:North Atlantic fisheries provide cost-efficient raw material, but quota restrictions and seasonal variability create input volatility for triglyceride conversion infrastructure.
- F-Gas Regulation compliance costs:REACH-aligned restrictions on processing refrigerants are forcing molecular distillation facilities to retool solvent recovery systems.
- Algal fermentation capex intensity:Captive fermentation capacity requires sustained capital deployment, limiting margin expansion for mid-scale producers without pharmaceutical-grade partnerships.
Strategic Opportunities
- Pediatric liquid formats:Dose-flexible delivery systems are gaining traction in the Netherlands and Germany as parents seek alternatives to softgel choking hazards.
- CSRD-aligned supply chain reporting:The EU Green Deal's sustainability criteria are creating differentiation premiums for omega-3 manufacturers with transparent North Atlantic fishery sourcing.
- Geriatric channel innovation:Direct-to-consumer subscription models are penetrating underserved segments in France and Spain where pharmacy access remains fragmented.
Industry Challenges
- ECHA biocidal substance reviews:Preservation systems in liquid formulations face regulatory uncertainty as active substance approvals undergo re-evaluation.
- Supercritical CO2 technical talent scarcity:Equipment operation and process optimization expertise concentrates among German and Dutch engineering clusters, constraining facility expansion elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Omega-3 Products Market |
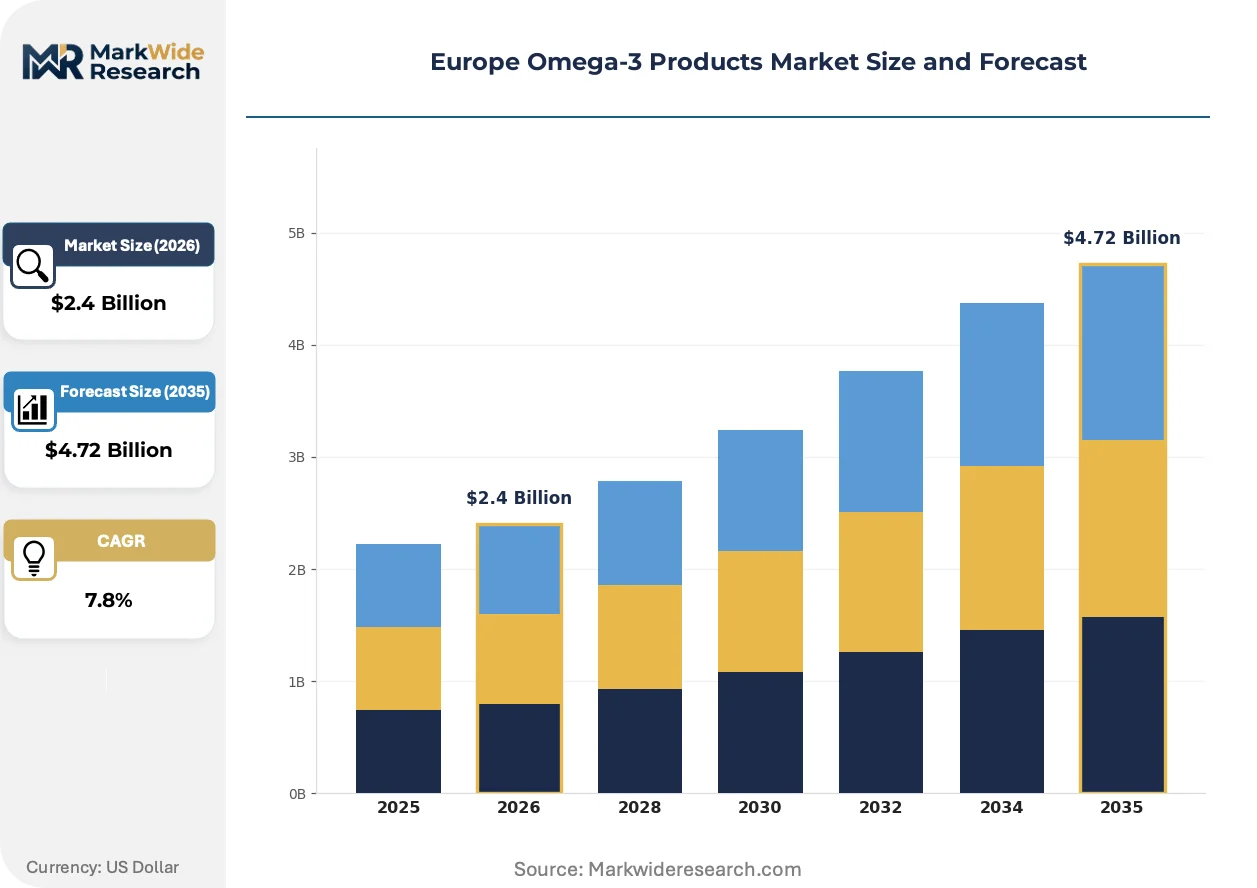
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Krill Oil, Algal Oil, Flaxseed Oil Delivery Mode: Capsule, Liquid, Powder, Softgel End User: Healthcare, Sports Nutrition, Dietary Supplements, Pet Care Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | Nestle SA, Herbalife International of America, Inc., Royal DSM, Reckitt Benckiser Group PLC, Sanofi SA, BASF SE, Amway Corporation, Croda International PLC, Unilever Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Omega-3 Products Market Shifts & Advancements
Algal oil extraction technologies and novel food regulatory pathways are compressing the traditional fish-oil value chain, while athlete-driven demand is forcing delivery format diversification beyond standard softgels.
Supercritical CO2 processing is supplanting molecular distillation as the preferred extraction method for high-concentration EPA/DHA esters. German pharmaceutical-grade manufacturers are adopting this technology to preserve heat-sensitive fatty acid structures. The shift is enabling cleaner label claims and reducing solvent residue concerns in premium pharmacy-tier products.
REACH compliance for marine lipid derivatives is tightening environmental disclosure requirements across EU member states. Manufacturers must now document F-Gas Regulation adherence for processing refrigerants and fishery sustainability credentials under EU Green Deal criteria. German and Dutch omega-3 suppliers are investing in blockchain-traceable sourcing systems to preempt audit demands from retail pharmacy chains.
Pharmacy buyers in Germany are consolidating shelf space around certified-sustainable and allergen-free omega-3 SKUs, displacing undifferentiated fish oil generics. Direct-to-consumer brands are responding with subscription-based liquid formats targeting pediatric and geriatric segments. This channel rotation is most visible in urban German markets where pharmacy chain consolidation has reduced independent retailer access.
Europe Omega-3 Products Market Segmentation
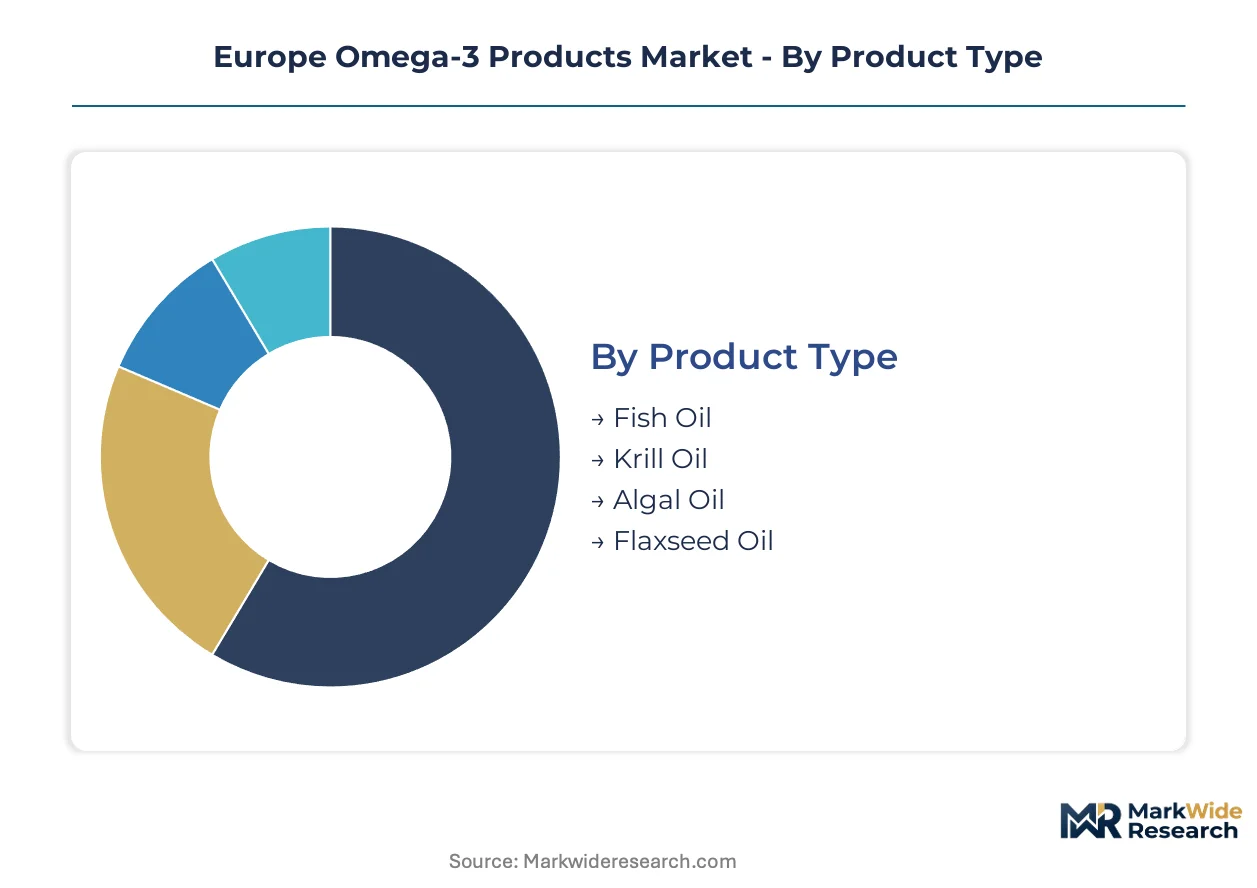
Omega-3 product segmentation in Europe reflects divergent channel economics and regulatory pathways. Pharmacy-tier certifications command premium positioning, while mass-market channels compete on unit accessibility and dosing convenience.
Product Type:
Fish oil concentrates dominate pharmacy and mass-market channels through established triglyceride infrastructure, while algal oil penetrates vegan-certified premium tiers via EFSA novel food pathways.
- Fish Oil:Concentrated EPA/DHA triglycerides and ethyl esters extracted from North Atlantic biomass remain the volume backbone. German pharmacy chains and Dutch health stores stock standardized 1000mg softgel formats as shelf-stable entry points, though quota volatility in North Atlantic fisheries creates input cost pressure for molecular distillation facilities.
- Algal Oil:Fermentation-derived DHA from Schizochytrium species captures vegan-certified premiums in Germany and the Netherlands. EFSA novel food streamlining has compressed approval timelines, enabling pharmacy chains to build dedicated allergen-free shelf space with transparent supply chain credentials under EU Green Deal criteria.
- Krill Oil:Phospholipid-bound EPA/DHA from Antarctic Euphausia superba offers superior bioavailability claims in Nordic premium segments.
- Flaxseed Oil:ALA-rich vegetarian positioning serves price-sensitive health store channels in France and Spain with limited conversion to long-chain omega-3s.
By volume, fish oil leads. By growth pace, algal oil is expanding most quickly.
Delivery Mode:
Softgel and liquid formats split across customer life stages, with dose-flexibility requirements driving pediatric and geriatric liquid adoption while adult maintenance segments favor portability.
- Softgel:Gelatin or plant-based capsule shells encapsulating 500-1000mg EPA/DHA concentrates dominate German pharmacy throughput. CrossFit practitioners and endurance athletes in Nordic markets are shifting toward higher-EPA ratio softgels as sports nutrition brands reformulate recovery-positioned SKUs.
- Liquid:Pump-dispensed or dropper formats enable precise pediatric dosing and geriatric compliance without choking hazards. Dutch parents and French direct-to-consumer subscribers are driving subscription-based liquid adoption where pharmacy access remains fragmented.
- Capsule:Hard-shell two-piece formats serve cost-conscious health store segments with lower fill weights.
- Powder:Microencapsulated formats integrate into functional foods and pet care applications with extended shelf stability.
Softgel maintains volume leadership. Liquid formats are climbing the fastest on pediatric and geriatric demand.
End User:
Application-specific formulation requirements create tiered margin structures, with pharmaceutical-grade specifications commanding the steepest premiums and pet care operating on commodity input economics.
- Healthcare:Prescription-strength EPA/DHA concentrates for cardiovascular and cognitive indications require EMA-aligned pharmaceutical manufacturing. German and Dutch facilities with supercritical CO2 extraction capabilities supply hospital and specialty pharmacy channels with documented purity certifications.
- Sports Nutrition:Endurance athletes and CrossFit practitioners in Germany and the Nordics are forcing brands toward higher-EPA recovery formulations with anti-inflammatory positioning. Clean-label vegan certifications differentiate premium SKUs in this segment.
- Dietary Supplements:General wellness positioning serves mass-market health store and supermarket channels with standardized potency claims.
- Pet Care:Companion animal omega-3s for coat and joint health operate through veterinary and specialty pet retail with lower concentration requirements.
Healthcare commands the highest unit values. Sports nutrition is gaining share fastest on athlete-driven SKU expansion.
Distribution Channel:
Channel consolidation in Germany is concentrating demand among pharmacy chains with sustainability audit requirements, while direct-to-consumer models penetrate underserved geographies.
- Pharmacies:German pharmacy chain consolidation has created dedicated omega-3 shelf space with blockchain-traceable sourcing prerequisites. EFSA novel food approvals and REACH compliance documentation are mandatory for shelf placement, filtering out undifferentiated fish oil generics.
- Online Retail:Direct-to-consumer subscription models are penetrating fragmented pharmacy access in France and Spain. Pediatric liquid formats and geriatric compliance packaging drive repeat purchase automation in urban markets.
- Health Stores:Independent and chain health food retailers in the Netherlands and Belgium serve vegan-certified and allergen-free demand with educated staff consultation.
- Supermarkets:Mass-market softgel formats compete on price-per-unit in grocery channels with limited differentiation beyond basic EPA/DHA potency labeling.
Pharmacies lead by value concentration. Online retail is expanding most quickly on subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German algal oil fermentation facilities supply pharmacy chains across the Netherlands and Nordic markets, creating a west-to-north trade corridor that concentrates premium omega-3 distribution within the continent.
Germany
Pharmacy chain consolidation and dedicated omega-3 shelf space expansion drive demand concentration. EFSA novel food assessments for algal DHA streamline ingredient qualification timelines. BASF SE operates captive fermentation capacity in Ludwigshafen, supplying pharmaceutical-grade DHA to domestic pharmacy networks.
Netherlands
Pediatric liquid format adoption and subscription-based direct-to-consumer models accelerate channel rotation. REACH compliance documentation for marine lipid derivatives shapes supplier selection criteria. Rotterdam logistics clusters handle North Atlantic fish oil imports for triglyceride conversion facilities.
United Kingdom
Sports nutrition brands reformulate SKUs with higher EPA ratios for CrossFit practitioner recovery claims. MHRA-aligned pharmaceutical manufacturing standards govern prescription-strength concentrate distribution. London-based direct-to-consumer brands penetrate fragmented pharmacy access with geriatric-targeted liquid formats.
France
Underserved geriatric segments and fragmented rural pharmacy access create subscription model opportunities. ANSM biocidal substance reviews generate regulatory uncertainty for liquid formulation preservation systems. Lyon health food retail clusters serve vegan-certified demand with educated staff consultation.
Sweden
Nordic clean-label vegan formulations and krill oil bioavailability positioning command premium tiers. EU Green Deal fisheries sustainability criteria tighten supply chain environmental disclosure requirements. Stockholm pharmacy chains consolidate shelf space around blockchain-traceable sourcing credentials.
Europe Omega-3 Products Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification depth, creating a tiered structure where pharmaceutical-grade manufacturers hold pricing power over commodity traders. Three archetypes dominate: integrated chemical conglomerates with captive fermentation infrastructure, pharmaceutical-grade extraction specialists with supercritical CO2 capabilities, and direct-to-consumer wellness brands with subscription logistics. Capacity expansion and regulatory certification acceleration represent the dominant competitive moves.
Among diversified chemical conglomerates, BASF SE and Royal DSM exemplify the integrated archetype through in-house algal oil fermentation and life'sOMEGA portfolio positioning. Croda International PLC occupies the pharmaceutical-grade specialist tier with high-concentration EPA/DHA ester capabilities. These three entities anchor the competitive spectrum from industrial-scale supply to premium pharmacy-tier differentiation.
| Leading Market Players |
|---|
| Nestle SA |
| Herbalife International of America, Inc. |
| Royal DSM |
| Reckitt Benckiser Group PLC |
| Sanofi SA |
| BASF SE |
| Amway Corporation |
| Croda International PLC |
| Unilever Plc |
| Others |
Supply & Pricing Matrix
Algal oil fermentation replacing fish oil triglyceride conversion redraws supply geography toward German biotech clusters while compressing the traditional North Atlantic fishery-to-pharmacy pricing ladder. EFSA novel food streamlining accelerates this substitution by collapsing regulatory qualification timelines from years to months, enabling pharmacy chains to capture vegan-certified premiums that previously required protracted approval investments.
Pricing Analysis
Extraction-technology pricing gaps separate molecular distillation facilities from supercritical CO2 adopters and emerging algal fermentation operators. Three-tier pricing structure across pharmaceutical-grade, pharmacy-certified, and mass-market economy levels reflects certification depth and purity documentation. Cost compression in economy-tier fish oil concentrates intensifies as North Atlantic quota restrictions tighten raw material access. Sports nutrition buyers exhibit lowest price sensitivity, prioritizing EPA ratio customization and clean-label vegan positioning over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg logistics clusters constrains North Atlantic fish oil inbound flows to German triglyceride conversion facilities. Supply concentration centers on Germany for algal fermentation, the Netherlands for pediatric liquid formulation, and Norway for krill oil phospholipid extraction. Raw material dependencies include Schizochytrium biomass for algal DHA, North Atlantic anchovy and sardine fisheries for fish oil, and Antarctic krill harvests for phospholipid-bound EPA/DHA. Single-source vulnerability runs through EFSA novel food approval holders for vegan-certified ingredients. Distribution runs through pharmacy chain consolidation in Germany, direct-to-consumer subscription models in France, and health store networks in the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
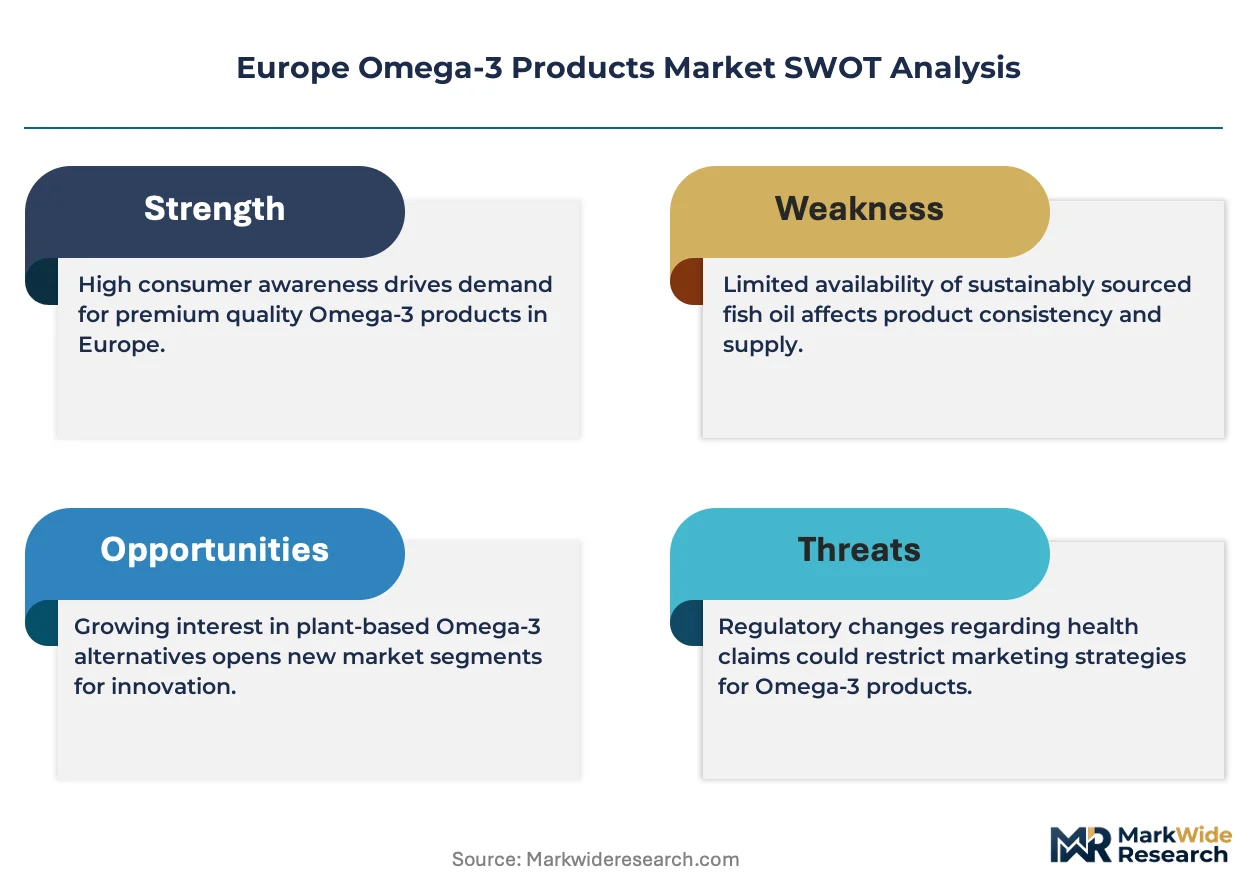
Regulatory entrenchment around EFSA novel food approvals and REACH compliance documentation constructs formidable defensive moats for qualified suppliers, as pharmacy chain shelf-space prerequisites filter out undifferentiated competitors lacking certification depth.
For Market Incumbents: Fortify captive fermentation capacity in Ludwigshafen and comparable German clusters to preempt algal oil supply constraints as vegan demand accelerates. Deepen backward integration into Schizochytrium strain development to secure proprietary DHA yields that emerging fermentation operators cannot replicate. Channel control through exclusive pharmacy chain partnerships remains essential as German retail consolidation reduces independent access points.
For New Entrants and Emerging Players: Differentiate on pediatric liquid format innovation with dose-flexible delivery systems that incumbent softgel-centric portfolios underserve. Target France and Spain where fragmented pharmacy access and subscription-model readiness create penetrable whitespace absent dominant incumbent presence. Pursue direct-to-consumer go-to-market positioning with automated repeat-purchase logistics to bypass pharmacy chain gatekeeping.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed algal fermentation specialists possessing EFSA approvals but lacking pharmaceutical-grade manufacturing partnerships. Long-term viability across the analysis window hinges on CSRD-aligned supply chain transparency investments that differentiate compliant suppliers from opaque traders. Monitor ECHA biocidal substance review outcomes as inflection indicators for liquid formulation preservation system viability.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Approval Acceleration | Compresses ingredient qualification timelines from years to months for algal DHA entrants. |
| Supercritical CO2 Capacity Expansion | Preserves heat-sensitive fatty acid structures for pharmaceutical-grade EPA/DHA ester production. |
| Blockchain-Traceable Sourcing Implementation | Preempts EU Green Deal audit demands from German pharmacy chain procurement officers. |
| Pediatric Liquid Format Development | Captures dose-flexibility premiums in Netherlands and German subscription channels. |
| CSRD-Aligned Supply Chain Reporting | Differentiates transparent North Atlantic fishery sourcing from undifferentiated commodity traders. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, pharmacy chain category buyers, regulatory affairs specialists at EFSA-aligned consultancies, and sports nutrition brand formulation directors; alongside secondary validation through EFSA novel food approval databases, REACH compliance registries, EU customs trade data for marine lipid imports, and SEC filings from listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates derived from pharmacy channel throughput analysis.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning extraction technology tier, delivery format type, end-use application, and distribution channel concentration. CAGRs were derived from trend extrapolation of pharmacy shelf-space expansion rates, athlete-driven SKU proliferation patterns, and EFSA approval velocity indicators. Forecast inputs incorporated F-Gas Regulation compliance cost trajectories and ECHA biocidal substance review timelines.
Material uncertainties — North Atlantic fishery quota volatility, EFSA approval pathway delays, and ECHA preservation system re-evaluations — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory streamlining continuity and pharmacy chain consolidation trajectories. Practitioners should keep alternative scenarios live as EU Green Deal sustainability criteria enforcement intensity evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
Whey Protein Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Tongkat Ali Extract Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Global Proanthocyanidins Market