
 Diet Pills Market | 2026-2036
Diet Pills Market Size, Share, and Industry Trends Forecast 2026-2036
Diet Pills Market Analysis
North American pharmaceutical manufacturing is restructuring its peptide synthesis capacity to serve the surge in GLP-1-based diet pill demand. Novo Nordisk anchors this expansion through its integrated active pharmaceutical ingredient production in Denmark and the United States. Eli Lilly competes via differentiated dual GIP/GLP-1 receptor agonist technology. Abbott sustains its position in over-the-counter nutrition and weight management through established retail pharmacy distribution.
Diet pills comprise pharmacological and botanical formulations designed to reduce appetite, inhibit nutrient absorption, or elevate energy expenditure through mechanisms such as lipase inhibition or incretin pathway modulation. Prescription segments lead value generation as GLP-1 agonists command premium reimbursement, while over-the-counter categories dominate volume through mass retail and e-commerce channels. Herbal and dietary formulations occupy niche positions where consumers seek non-prescription alternatives with fewer regulatory barriers.
FDA oversees prescription diet pill approval through the Center for Drug Evaluation and Research, requiring cardiovascular outcome trials for obesity therapeutics. EMA applies parallel scrutiny through its Committee for Medicinal Products for Human Use, influencing formulation standards that manufacturers must satisfy for transatlantic market access. Stakeholders must monitor evolving pharmacovigilance mandates and reimbursement policy shifts that will determine which delivery formats and active ingredients secure sustainable commercial traction.
Market Dynamics
GLP-1 receptor agonist supply concentration is restructuring competitive positioning across prescription and over-the-counter channels, forcing manufacturers to secure peptide synthesis capacity or exit premium segments entirely.
Growth Catalysts
- Cardiovascular Outcome Trial Requirements:FDA mandates for obesity therapeutics are elevating clinical evidence standards that filter out undercapitalized entrants and reward sponsors with robust safety databases.
- Employer-Sponsored Coverage Expansion:Large self-insured employers in the United States are adding GLP-1 agonists to formularies, creating direct demand pull through benefits administration channels.
- Continuous Manufacturing Adoption:Peptide synthesis facilities are deploying flow chemistry platforms that compress batch cycle times and reduce solvent waste disposal liabilities.
Market Restraints
- Semaglutide API Supply Bottleneck:Active pharmaceutical ingredient production concentrates in Denmark and North Carolina facilities, creating single-source vulnerability for dependent formulators.
- Reimbursement Authorization Friction:United States commercial payers impose step-therapy requirements and prior authorization burdens that delay therapy initiation and increase administrative abandonment.
- Generic Orlistat Price Compression:Commoditized lipase inhibitors in over-the-counter channels erode margin pools available for innovation investment in adjacent metabolic categories.
Strategic Opportunities
- India Outpatient Clinic Integration:CDSCO regulatory pathways for fixed-dose combinations present first-mover potential for sponsors willing to establish local clinical trial infrastructure.
- Digital Therapeutic Adjuvants:Prescription digital health applications paired with pharmacotherapy are securing unique device designation from FDA, opening reimbursement codes separate from drug pricing.
- Direct-to-Consumer Subscription Models:Telehealth platforms bypass traditional pharmacy benefit manager channels, capturing patient lifetime value through recurring revenue structures.
Industry Challenges
- Peptide Chemist Talent Scarcity:Large-scale solid-phase synthesis expertise resides at a handful of contract development and manufacturing organizations, inflating compensation and extending project timelines.
- Cold Chain Integrity Requirements:GLP-1 agonist stability mandates for refrigerated distribution strain last-mile logistics networks and complicate patient self-administration programs.
- Pharmacovigilance Signal Detection:Post-market surveillance for thyroid C-cell tumors and pancreatitis demands dedicated epidemiology teams that smaller sponsors cannot resource internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diet Pills Market |
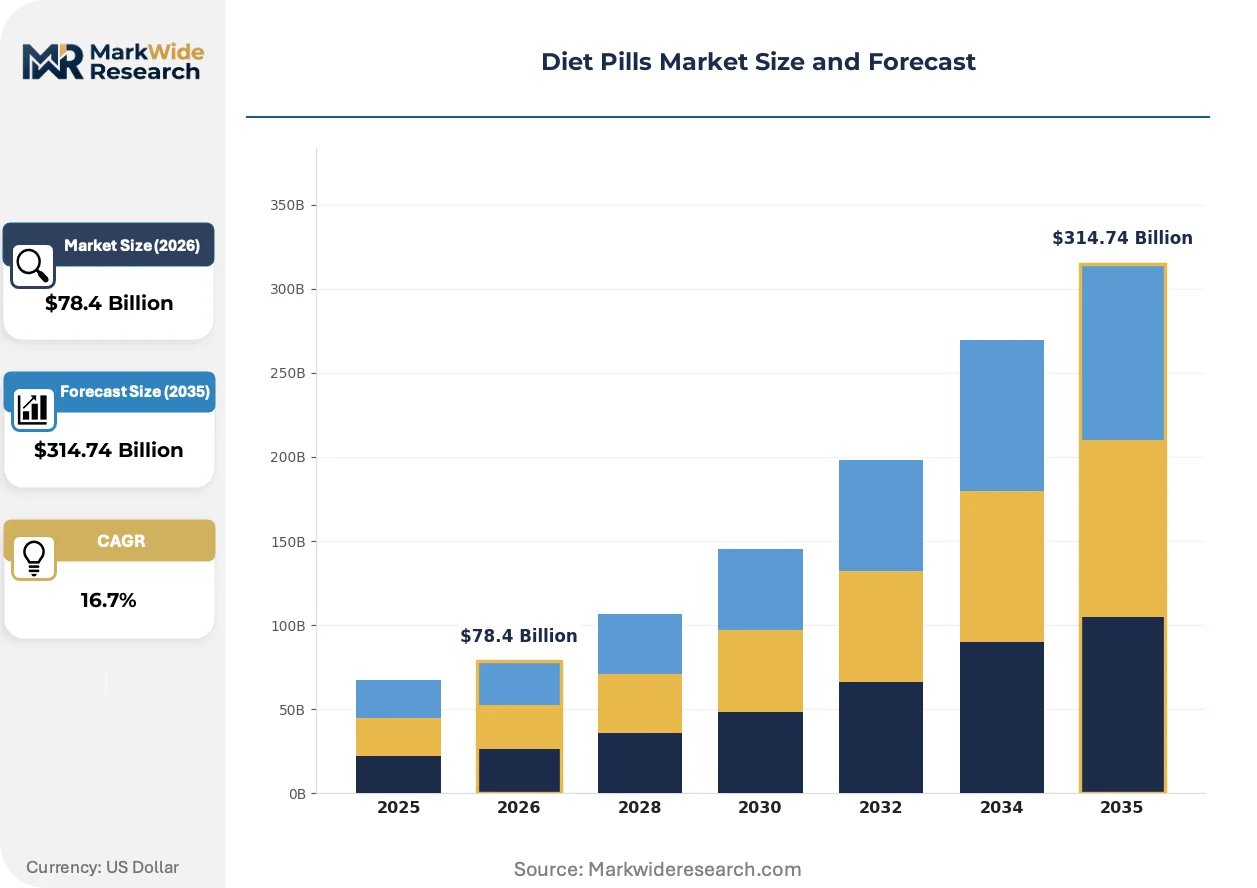
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $314.74 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription, Over-the-Counter, Herbal, Dietary Form: Pills, Capsules, Powders, Gummies Active Ingredient: Orlistat, Phentermine, Garcinia Cambogia, Green Tea Extract Target Demographic: Adults, Seniors, Athletes, Busy Professionals |
| Companies Covered | Novo Nordisk, Eli Lilly, Abbott, Herbalife International of America, Amway Corp, Nature’s Sunshine Products, American Health, Nu Skin, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diet Pills Market Emerging Trajectories
Dual and triple incretin receptor targeting is displacing single-mechanism approaches, while regulatory scrutiny of cardiovascular safety signals intensifies across all metabolic drug development programs.
Oral small-molecule GLP-1 receptor agonists are expanding into patient populations that refuse injectable therapy or lack refrigeration access. Primary care physicians in Medicaid-heavy United States counties are prescribing these formulations at rates exceeding specialist adoption. This expansion is compressing the historical divide between prescription obesity management and primary diabetes care, forcing endocrinology practices to redefine service differentiation.
EMA's accelerated assessment pathway for medicines addressing unmet medical need is compressing regulatory timelines for sponsors with robust cardiovascular outcome data. The industrial consequence is a funding preference shift toward Phase III-ready assets over early discovery platforms. Obesity therapeutics with established MACE benefit are receiving conditional marketing authorization decisions within twelve months of submission, pressuring FDA to align review cadence.
Patients are aggregating demand through employer-sponsored digital health platforms that bundle telehealth consultation, prescription fulfillment, and outcome tracking. Traditional retail pharmacy channels are losing script volume to vertically integrated direct-to-consumer models. This concentration is most visible in United States metropolitan corridors where large employers have active wellness program procurement cycles and established relationships with telehealth vendors.
Diet Pills Market Segmentation
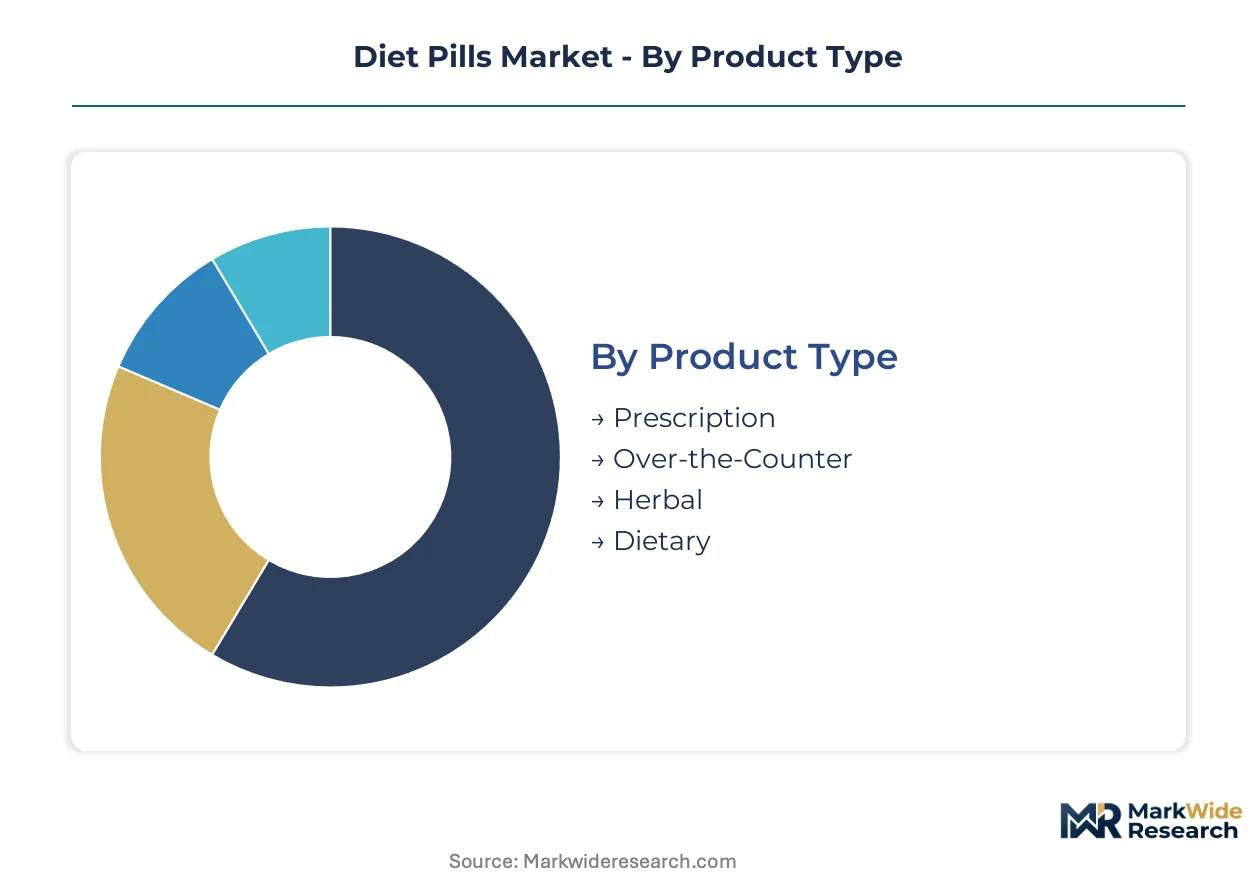
Product differentiation in diet pills reflects divergent regulatory pathways and patient self-selection patterns. Manufacturers must align formulation investments with reimbursement eligibility, distribution channel requirements, and consumer willingness to navigate prescription access barriers.
Product Type:
Upgrade cycles differentiate sharply across prescription and non-prescription categories, with reimbursement policy shifts triggering portfolio rebalancing.
- Prescription:GLP-1 receptor agonists and phentermine-topiramate combinations dominate clinical obesity management. Employer-sponsored coverage in United States metropolitan markets drives concentrated demand pull through specialty pharmacy networks.
- Over-the-Counter:Alli and comparable lipase inhibitors occupy mass retail shelves with minimal pharmacist intervention. Volume concentrates in United States drugstore chains where consumers bypass physician consultation entirely.
- Herbal:Botanical formulations exploit regulatory gaps between food and drug classifications. FSSAI in India and FDA dietary supplement oversight create heterogeneous compliance burdens for cross-border sellers.
- Dietary:Meal replacement and micronutrient-fortified formulations straddle nutrition and weight management categories. EFSA health claim assessments in Europe constrain marketing language that manufacturers deploy in member states.
Volume placements concentrate in Over-the-Counter; the faster expansion belongs to Prescription.
Form:
Patient adherence patterns and cold chain requirements reshape formulation preferences across delivery formats.
- Pills:Compressed tablets dominate prescription GLP-1 agonist development pipelines. Novo Nordisk and Eli Lilly prioritize tablet stability profiles that withstand ambient distribution in United States Medicaid networks.
- Capsules:Gelatin and vegetable-based shells accommodate moisture-sensitive actives like green tea catechins. Powdered extract demand from Chinese manufacturers concentrates capsule production in Zhejiang province facilities.
- Powders:Meal replacement formulations leverage bulk packaging for gym and wellness channel distribution. Protein-spiked weight management powders compete with dedicated diet pill categories in Australian pharmacy retail.
- Gummies:Palatability-driven formats capture younger demographics and polypharmacy-averse seniors. Sugar alcohol content creates formulation trade-offs that TGA in Australia scrutinizes for gastrointestinal tolerability claims.
Manufacturing scale clusters in Pills; gummies are climbing the fastest as palatability premiums justify unit economics.
Active Ingredient:
Patent cliffs and API sourcing concentration determine margin sustainability across mechanism classes.
- Orlistat:Lipase inhibition mechanism faces generic price compression in over-the-counter channels. Teva and Sandoz production of 60mg formulations erodes originator returns in United States mass retail.
- Phentermine:Sympathomimetic amine scheduling creates distribution controls that limit telehealth expansion. DEA quota restrictions in United States constrain volume growth regardless of demand signals.
- Garcinia Cambogia:Hydroxycitric acid extracts from Indonesian and Indian supply regions face adulteration scrutiny. Third-party certification demand from United States consumers drives USP verification program enrollment.
- Green Tea Extract:EGCG standardization requirements vary across Japanese, Chinese, and South Korean sourcing markets. Liver toxicity signal detection by EMA has triggered formulation reformulation in European markets.
Orlistat commands placement volume; phentermine formulations gain share fastest where scheduling permits telehealth prescribing.
Target Demographic:
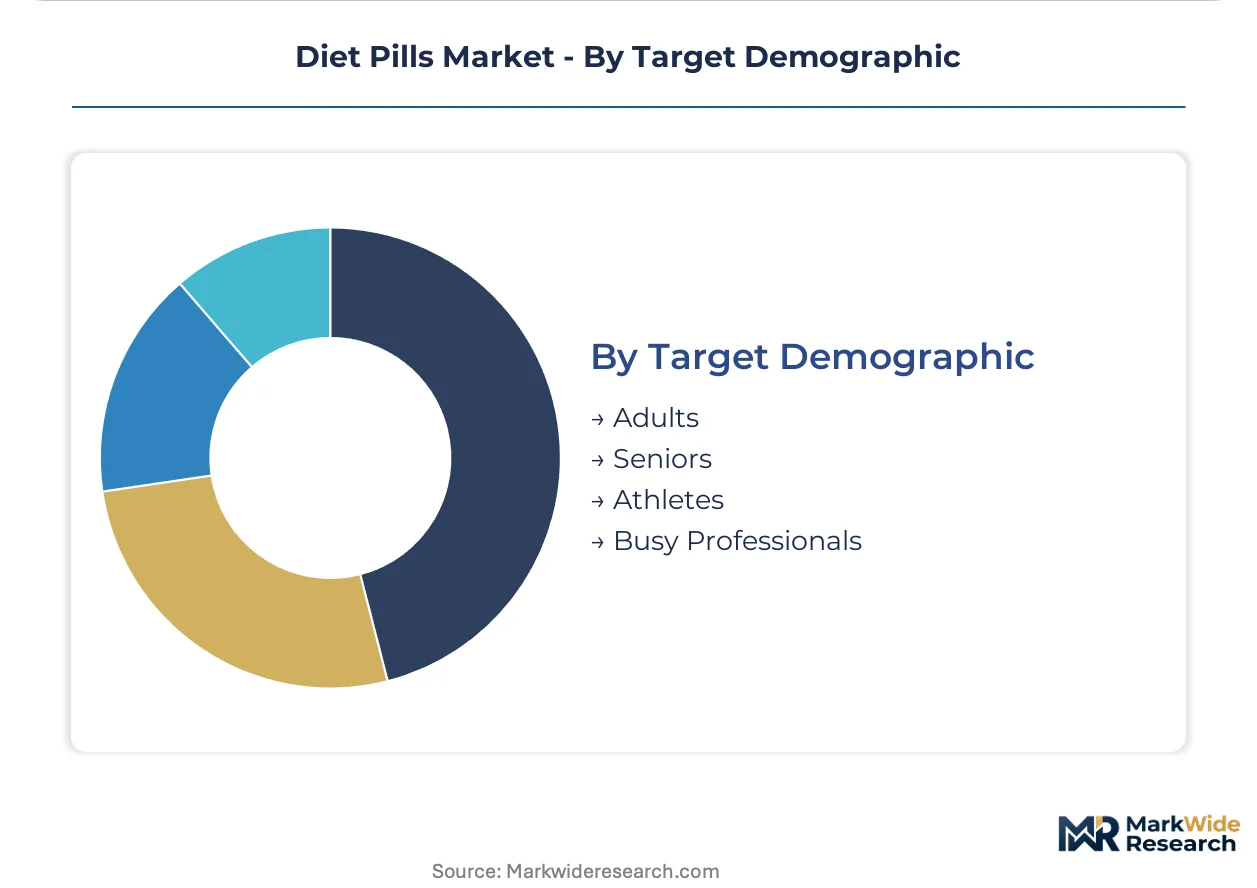
Life stage and occupational constraints segment addressable populations into distinct channel and messaging requirements.
- Adults:Prime working-age populations drive prescription GLP-1 agonist demand through employer wellness programs. United States self-insured employers in technology and finance sectors add these therapies to formularies at accelerating rates.
- Seniors:Medicare Part D coverage gaps and polypharmacy risks limit prescription uptake. Over-the-counter fiber and meal replacement formulations capture preference where drug interaction concerns dominate.
- Athletes:Informed Sport and NSF Certified for Sport programs govern supplement selection in competitive contexts. WADA monitoring of stimulant-adjacent compounds creates formulation exclusion lists that manufacturers must navigate.
- Busy Professionals:Subscription and telehealth-integrated models target time-constrained urban populations. Direct-to-consumer platforms in United States coastal metropolitan areas bundle consultation, prescription, and delivery.
Adults account for dominant volume placements; busy professionals represent the steepest expansion trajectory as convenience premiums sustain subscription economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide synthesis feedstock from Danish and North Carolina facilities anchors prescription GLP-1 agonist distribution networks. Regulatory divergence across FDA, EMA, and national health technology assessment bodies fragments market access timelines. Cold chain infrastructure investments concentrate in metropolitan corridors with employer-sponsored coverage density.
United States
Employer-sponsored coverage expansion in technology and finance sectors drives concentrated demand for prescription GLP-1 agonists. FDA cardiovascular outcome trial mandates filter undercapitalized entrants from obesity therapeutic development. Specialty pharmacy networks in Boston and San Francisco metropolitan areas anchor distribution infrastructure for refrigerated formulations.
Germany
EMA centralized marketing authorization procedures compress regulatory timelines for sponsors with established MACE benefit data. Germany's Federal Joint Committee (G-BA) health technology assessments determine reimbursement eligibility for obesity therapeutics. Industrial peptide manufacturing clusters in Bavaria and North Rhine-Westphalia expand contract development capacity for GLP-1 API production.
Denmark
Integrated active pharmaceutical ingredient production facilities supply semaglutide to dependent formulators across European and North American markets. Danish Medicines Agency pharmacovigilance requirements align with EMA standards for thyroid C-cell tumor surveillance. Copenhagen-region biologics manufacturing infrastructure anchors Novo Nordisk's captive peptide synthesis operations.
India
CDSCO regulatory pathways for fixed-dose combinations attract sponsors establishing local clinical trial infrastructure in outpatient clinic networks. FSSAI dietary supplement oversight creates compliance heterogeneity for herbal formulation cross-border sellers. Contract manufacturing clusters in Maharashtra and Gujarat expand peptide synthesis capabilities to serve export demand.
Japan
PMDA accelerated review pathways for medicines addressing unmet medical need compress timelines for obesity therapeutics with cardiovascular benefit. METI industrial policy supports domestic biologics manufacturing capacity expansion. Pharmaceutical production corridors in Kanto and Kansai regions develop cold chain infrastructure for incretin-based formulations.
Diet Pills Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue telehealth-integrated direct-to-consumer channels. The market consolidates around three structural tiers: integrated pharmaceutical conglomerates with captive API production, specialized biologics manufacturers dependent on contract synthesis, and mass-market nutrition brands with retail pharmacy distribution. Competitive dynamics center on peptide synthesis capacity acquisition and reimbursement authorization capabilities. Consolidation pressure intensifies as supply bottlenecks force formulators to secure backward integration or exit premium segments.
Among integrated pharmaceutical conglomerates, Novo Nordisk and Eli Lilly exemplify the capacity-anchored archetype with captive peptide production infrastructure. Abbott occupies a position within the mass-market nutrition tier through established retail pharmacy distribution networks. These three entities represent divergent strategic postures: pharmaceutical integration versus consumer health scale versus biologics specialization.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly |
| Abbott |
| Herbalife International of America |
| Amway Corp |
| Nature's Sunshine Products |
| American Health |
| Nu Skin |
| Amgen |
| Others |
Supply Flow & Price Mechanics
Flow chemistry platform deployment in peptide synthesis facilities is compressing batch cycle times while simultaneously concentrating production capacity among sponsors with capital to retrofit existing infrastructure. This technological transition rewards Novo Nordisk and Eli Lilly with unit cost advantages that smaller formulators cannot replicate, amplifying pricing power divergence between integrated and dependent manufacturers.
Pricing Analysis
Warranty and service bundling separates prescription GLP-1 agonists from commoditized over-the-counter alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects reimbursement eligibility, cold chain integrity guarantees, and telehealth consultation inclusion. Pricing pressure stems from generic Orlistat price compression in mass retail channels. Employer-sponsored coverage segments exhibit lowest price sensitivity; uninsured cash-pay patients in Medicaid-heavy counties face highest abandonment rates due to prior authorization friction.
Supply Chain Analysis
Refrigerated freight costs for GLP-1 agonist distribution strain last-mile logistics networks, particularly in United States metropolitan corridors with employer-sponsored coverage density. Active pharmaceutical ingredient production draws from Denmark and North Carolina facilities, with contract manufacturing expansion in Maharashtra and Gujarat serving export demand. Semaglutide API single-source vulnerability represents the dominant structural risk. Distribution runs through specialty pharmacy networks for prescription segments and mass retail chains for over-the-counter formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around peptide synthesis capacity ownership, with supply bottlenecks forcing undercapitalized formulators toward exit or niche repositioning.
For Market Incumbents: Deepen backward integration into active pharmaceutical ingredient production to defend against Novo Nordisk's captive supply advantages. Secure peptide chemist talent through acquisition of specialized contract development and manufacturing organizations. Prioritize cardiovascular outcome trial investment to satisfy FDA pharmacovigilance mandates that filter weaker competitors.
For New Entrants and Emerging Players: Launch via direct-to-consumer telehealth subscription models that bypass pharmacy benefit manager channels and capture patient lifetime value. Target India's outpatient clinic networks where CDSCO fixed-dose combination pathways offer first-mover positioning. Bundle prescription digital therapeutics to secure unique device designation and separate reimbursement codes.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated pharmaceutical conglomerates seeking peptide synthesis capacity. Long-term viability hinges on sponsors with Phase III-ready assets and established MACE benefit data. Watch for EMA accelerated assessment pathway decisions as inflection indicators for FDA review cadence alignment.
| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Synthesis Capacity Expansion | Captive API production insulates Novo Nordisk from semaglutide supply bottlenecks affecting dependent formulators. |
| Cardiovascular Outcome Trial Investment | FDA mandates reward sponsors with robust safety databases and filter undercapitalized obesity therapeutic entrants. |
| Direct-to-Consumer Telehealth Launch | Vertically integrated platforms bypass pharmacy benefit managers and capture recurring revenue in employer-sponsored markets. |
| Digital Therapeutic Adjuvant Development | Prescription digital health applications paired with pharmacotherapy secure unique device designation from FDA. |
| India Clinical Trial Infrastructure Buildout | CDSCO regulatory pathways for fixed-dose combinations attract sponsors establishing local outpatient clinic networks. |
Methodological Framework
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from SEC 10-K disclosures, hospital procurement databases, and GPO contracts. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated to produce volume and value estimates.
Output generation employed treatment line, dosage form, administration route, and regional regulatory cluster segmentation across the modeling period. CAGRs were derived from epidemiological trend extrapolation, reimbursement policy scenario analysis, and patent expiry impact assessment. Forecast inputs incorporated employer-sponsored coverage expansion rates and peptide synthesis capacity utilization assumptions.
Regulatory approval delays, supply chain disruptions, and reimbursement authorization friction are the dominant revision risks to projection accuracy. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Protein Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Ashwagandha Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Sports Food Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market