
 Australia Protein Market | 2026-2036
Australia Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Protein Market Outlook
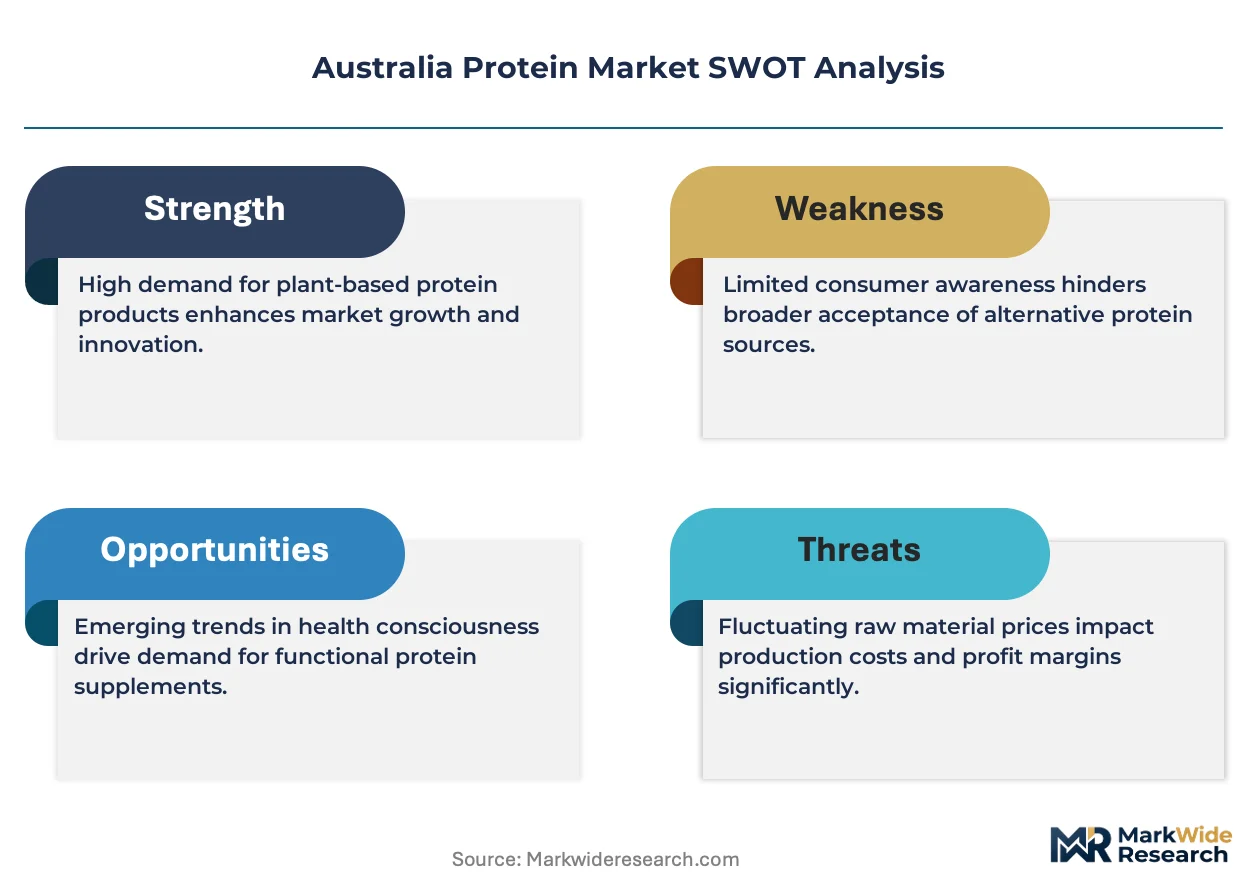
FSANZ Standard 1.5.2 novel food certification is redrawing competitive access for plant-based entrants without established safety dossiers. Fonterra Co-operative Group leverages its dairy protein infrastructure to dominate whey and casein supply across Australasia. Australian Plant Proteins PTY LTD anchors domestic pea protein extraction with a dedicated facility in regional Victoria. Kerry Group competes on taste-masked formulations that extend its ingredient reach into functional foods and ready-to-drink applications.
Australia protein encompasses nitrogenous macromolecules derived from animal and plant sources, typically comprising amino acid chains with digestibility-corrected amino acid scores above 0.75 for high-quality grades, manufactured through enzymatic hydrolysis, membrane filtration, or dry fractionation for muscle protein synthesis support and satiety modulation. Whey protein concentrates and isolates retain the largest margin pools due to sports nutrition premiums, while pea protein isolates show the fastest volume trajectory as dairy-alternative formulations gain shelf space. Functional foods applications now absorb ingredient volumes once confined to powder supplements, with meal replacement bars and fortified beverages reshaping demand patterns.
FSANZ governs compositional standards and health claims under the Australia New Zealand Food Standards Code, while the ACCC enforces anti-competitive conduct and misleading labelling in protein marketing, and the TGA regulates therapeutic claims crossing into medical food territory. Tighter protein content verification and origin labelling requirements are raising compliance costs for importers and rewarding domestic traceability investments. Stakeholders must monitor pending FSANZ reviews on novel protein fermentation methods and decide whether to build in-house regulatory affairs capabilities or outsource pre-market approvals.
Market Dynamics
FSANZ novel food certification requirements are compressing market access timelines for imported plant-based proteins while concentrating formulation expertise in Victoria and New South Wales.
Growth Catalysts
- Sports Nutrition Demand:Fitness enthusiasts and amateur athletes nationwide are expanding consumption of whey isolates and plant-based alternatives for muscle protein synthesis support.
- FSANZ Standard 1.5.2:Established safety dossiers for dairy proteins create regulatory clarity that accelerates product registration versus novel plant entrants.
- Melbourne-Sydney Corridor:Dense clustering of protein formulation facilities and specialty retailers in these cities reduces logistics costs for domestic brands.
Market Restraints
- Pea Protein Input Volatility:Regional Victoria crop yields fluctuate with irrigation access, squeezing margins for domestic extraction facilities.
- Novel Food Compliance Costs:FSANZ pre-market approval timelines and safety study requirements impose capital burdens on fermentation-derived protein innovators.
- Dairy Protein Dominance:Fonterra's whey and casein infrastructure across Australasia limits price competition in premium sports nutrition segments.
Strategic Opportunities
- Queensland Underpenetration:Brisbane and Gold Coast lack dedicated protein formulation clusters, creating white space for regional production investment.
- Functional Foods Convergence:Meal replacement bars and fortified beverages are absorbing ingredient volumes previously confined to powder supplements.
- Taste-Masked Formulations:Kerry Group's approach signals demand for palatable plant proteins in ready-to-drink applications beyond core athletic users.
Industry Challenges
- Regulatory Affairs Talent Scarcity:FSANZ novel food approval expertise concentrates in Melbourne and Sydney, limiting regional applicant capacity.
- Traceability Infrastructure Capex:Tightened origin labelling mandates require domestic processors to invest in supply chain verification systems.
- Enzymatic Hydrolysis Scale-Up:Membrane filtration capacity constraints at existing facilities delay volume expansion for emerging brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Protein Market |
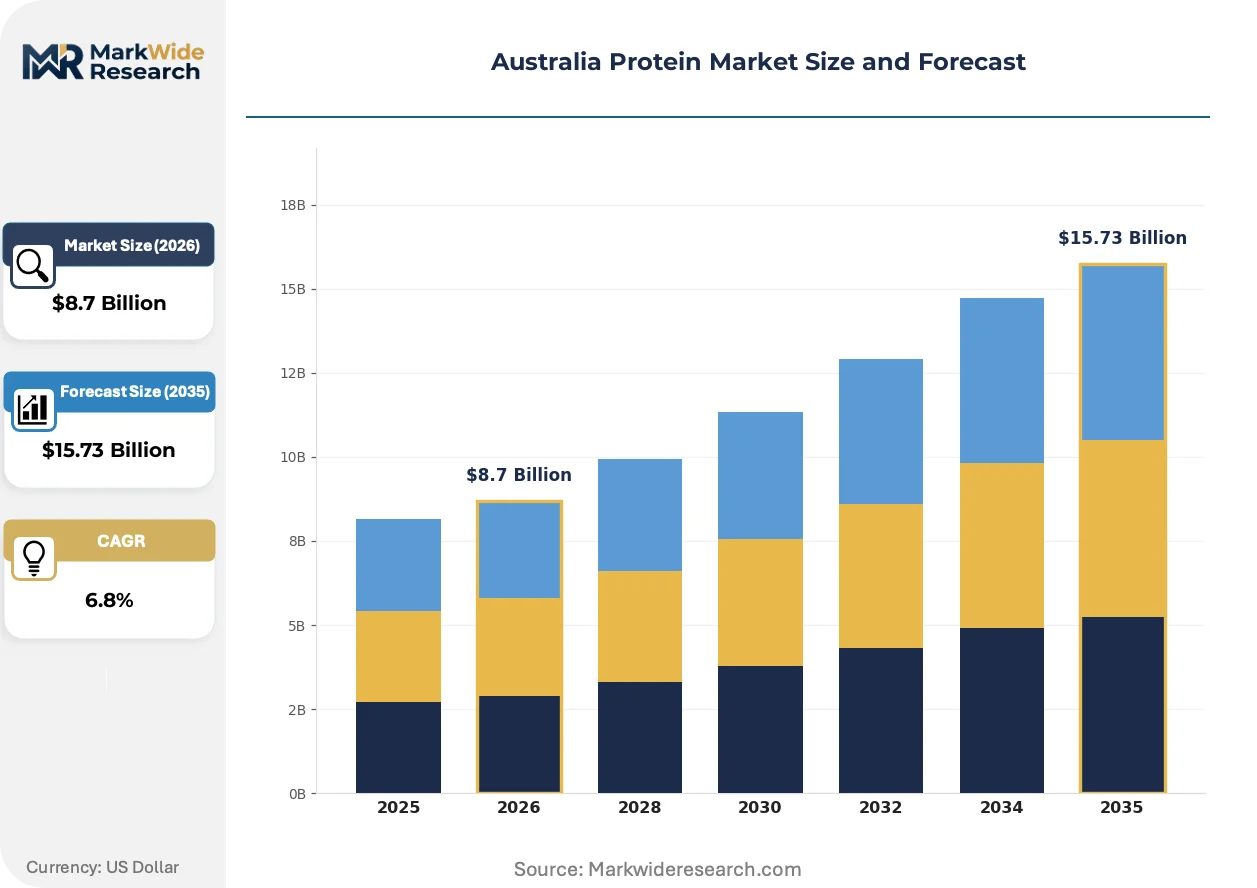
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein Application: Sports Nutrition, Meal Replacement, Supplements, Functional Foods End User: Fitness Enthusiasts, Athletes, Health-Conscious Individuals, Bodybuilders Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Glanbia, Archer Daniels Midland Company, Fonterra Co-operative Group, Australian Plant Proteins PTY LTD, Cargill, Kerry Group, DuPont, Bulk Nutrients, Freedom Foods Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Protein Market Strategic Shifts
Precision fermentation and enzymatic processing methods are redrawing ingredient sourcing maps while FSANZ labelling mandates force transparency investments across the value chain.
Precision fermentation for dairy-identical proteins is decomposing traditional whey supply dependencies. Specialty ingredient buyers in sports nutrition and functional foods are piloting these inputs at pilot-scale volumes. The technology is decomposing Fonterra's historical grip on premium protein supply by enabling domestic production without herd infrastructure.
FSANZ reviews on novel protein fermentation methods are tightening pre-market data requirements. Manufacturers must submit comprehensive safety dossiers before commercial distribution, extending registration timelines. Plant-based entrants without established histories face the steepest compliance burdens, advantaging dairy incumbents with existing approvals.
Amateur athletes and recreational fitness consumers are consolidating purchases through direct-to-subscription channels. Traditional specialty retailers in Melbourne and Sydney are losing traffic to personalized nutrition platforms with algorithm-driven formulation. Queensland and Western Australia show the fastest channel migration as geographic distance from physical clusters increases digital preference.
Australia Protein Market Segmentation
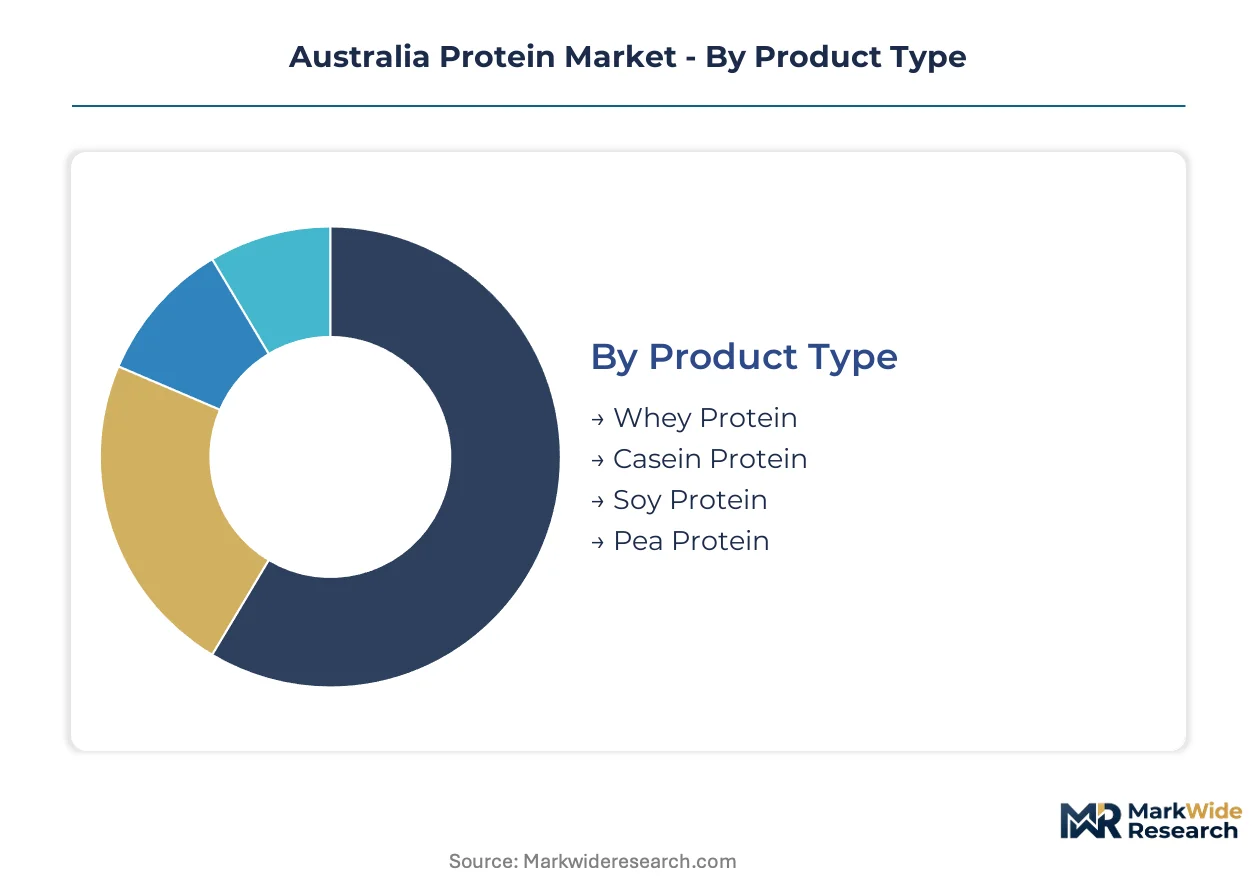
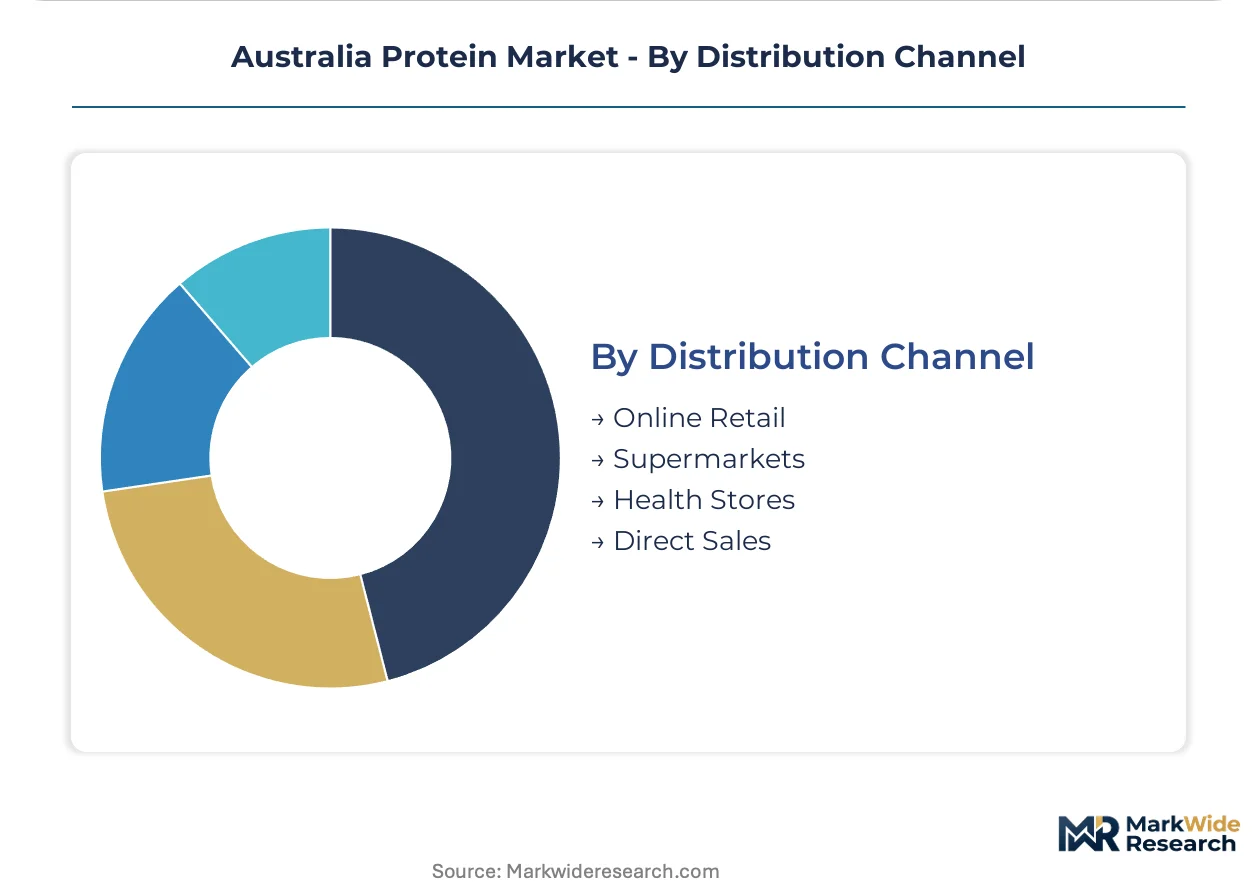
Channel mix in the Australia protein market diverges sharply between Melbourne-Sydney specialty retail clusters and emerging digital platforms. Each segment category carries distinct margin profiles and regulatory compliance burdens under FSANZ standards.
Product Type:
Whey and casein proteins flow predominantly through sports nutrition specialty channels in Victoria and New South Wales, while plant-based alternatives gain traction in online direct-to-consumer subscriptions.
- Whey Protein:Derived from cheese manufacturing byproducts with protein concentrations ranging from 80% in concentrates to 90%+ in isolates. Demand concentrates among amateur athletes in Sydney and Melbourne seeking rapid post-exercise amino acid absorption. FSANZ's established safety dossiers accelerate product registration versus novel entrants.
- Pea Protein:Isolates extracted via dry fractionation achieve 85% protein content with digestibility-corrected amino acid scores approaching 0.89. Australian Plant Proteins PTY LTD's regional Victoria facility anchors domestic supply for dairy-alternative formulations expanding through health stores and online channels.
- Casein Protein:Micellar structures enable slow-release amino acid delivery valued by overnight recovery protocols in bodybuilding communities.
- Soy Protein:Concentrates and isolates face declining shelf space as pea protein gains preference among consumers seeking non-GMO and allergen-friendly alternatives.
Whey protein dominates installed base. Pea protein is where expansion concentrates.
Application:
Cost tier differentiation separates premium sports nutrition from mass-market functional foods, with formulation complexity driving margin stratification.
- Sports Nutrition:Powders, ready-to-drink beverages, and bars targeting muscle protein synthesis with leucine-enriched formulations. Melbourne and Sydney specialty retailers command premium pricing for certified products.
- Functional Foods:Fortified beverages and meal replacement formats absorb ingredient volumes previously confined to supplements. Kerry Group's taste-masked formulations extend palatability beyond core athletic users into mainstream grocery channels.
- Meal Replacement:Calorie-controlled formulations with complete amino acid profiles serve weight management segments through subscription platforms.
- Supplements:Capsule and tablet formats face compression as consumers shift toward food-integrated delivery systems.
Sports nutrition commands premium margins. Functional foods is gaining share fastest.
End User:
Volume concentration tracks fitness participation rates, with amateur athletes representing the fastest-expanding cohort versus professional bodybuilders.
- Fitness Enthusiasts:Recreational exercisers consuming protein for general wellness and body composition goals. Queensland and Western Australia show steepest digital channel migration as geographic distance from physical clusters increases.
- Health-Conscious Individuals:Consumers prioritizing clean-label and plant-based options, driving pea protein demand through online retail and health store channels.
- Athletes:Organized sports participants requiring batch-tested products with anti-doping certification.
- Bodybuilders:Specialized consumers demanding high-dose leucine formulations with established brand loyalty.
Fitness enthusiasts dominate addressable population. Health-conscious individuals is where product innovation concentrates.
Distribution Channel:
Geographic reach constraints favor digital platforms outside Victoria and New South Wales, with supply chain verification investments tightening origin labelling compliance.
- Online Retail:Direct-to-subscription platforms with algorithm-driven personalization capture Queensland and Western Australia demand. FSANZ traceability mandates require robust supply chain documentation for interstate shipping.
- Health Stores:Specialty retailers in Melbourne and Sydney clusters provide formulation expertise and taste sampling that digital channels cannot replicate.
- Supermarkets:Mass-market penetration for functional foods and meal replacement formats with simplified label claims.
- Direct Sales:Gym-affiliated and practitioner channels serving personalized nutrition protocols.
Health stores dominate premium product distribution. Online retail is where geographic expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSANZ novel food certification and the Australia New Zealand Food Standards Code create distinct compliance environments across Australian states. Protein formulation capacity clusters around established dairy infrastructure and emerging plant-based extraction facilities.
New South Wales
Sydney anchors the eastern seaboard's sports nutrition demand through dense specialty retail networks and direct-to-consumer distribution hubs. The state's Food Authority enforces supplementary labelling requirements beyond FSANZ baseline standards. Parramatta and Western Sydney industrial zones host contract manufacturing facilities serving both domestic brands and Asia-Pacific export orders.
Victoria
Melbourne's fitness culture drives concentrated consumption of whey isolates and functional food formats among amateur athletes. Regional irrigation districts north of the city support Australian Plant Proteins PTY LTD's pea protein extraction infrastructure. Geelong and Ballarat manufacturing corridors supply ingredient intermediates to formulation facilities across the Melbourne metropolitan area.
Queensland
Brisbane and Gold Coast populations show accelerating digital channel migration for protein purchases as geographic distance from physical retail clusters increases. The Queensland Health department coordinates with FSANZ on novel food safety assessments for fermentation-derived entrants. Limited dedicated protein formulation infrastructure creates white space for regional production investment targeting northern markets.
Western Australia
Perth's isolation drives highest per-capita online subscription penetration for personalized nutrition platforms among Australian states. The Department of Health Western Australia maintains parallel enforcement of FSANZ standards with additional emphasis on import verification at Fremantle port facilities. Limited local extraction capacity forces reliance on interstate supply chains with tightened origin documentation requirements.
South Australia
Adelaide's health-conscious demographics support growing demand for plant-based and clean-label protein alternatives through independent retail channels. Primary Industries and Regions SA administers agricultural quality schemes that feed into protein ingredient traceability systems. The Barossa Valley and Adelaide Hills regions lack dedicated protein processing infrastructure, importing formulated products from eastern states.
Australia Protein Market Competitive Environment
Listed leaders compete with private specialists across regulatory compliance capabilities and formulation expertise. ASX-listed entities leverage capital market access for traceability infrastructure investments while private operators concentrate on niche taste-masked technologies. The market structures around three archetypes: dairy cooperative incumbents with established FSANZ dossiers, plant-based extraction specialists with regional agricultural integration, and global ingredient houses with taste modulation IP. Dominant competitive moves include backward integration into raw material supply and strategic partnerships with direct-to-consumer platforms.
Among dairy cooperative structures, Fonterra Co-operative Group anchors premium whey and casein supply across Australasia through existing safety approvals. Kerry Group exemplifies the taste-masked formulation specialist archetype, extending ingredient reach into functional foods and ready-to-drink applications beyond core athletic segments. Australian Plant Proteins PTY LTD occupies a position within the domestic plant extraction tier, leveraging regional Victoria agricultural proximity for supply security.
| Leading Market Players |
|---|
| Glanbia |
| Archer Daniels Midland Company |
| Fonterra Co-operative Group |
| Australian Plant Proteins PTY LTD |
| Cargill |
| Kerry Group |
| DuPont |
| Bulk Nutrients |
| Freedom Foods Group |
| Others |
Value Chain & Pricing Dynamics
Membrane filtration capacity utilization at Australian extraction facilities creates scale advantages that compress unit costs for domestic whey and casein producers while elevating price floors for novel plant-based entrants lacking established FSANZ dossiers. This scale asymmetry concentrates margin capture among dairy incumbents and forces fermentation-derived protein innovators to absorb higher per-unit compliance burdens.
Pricing Analysis
Certification level (FSANZ-established versus novel food status) creates the primary spread between premium whey isolates and emerging plant alternatives. Three-tier pricing structure separates sports nutrition specialty products from functional foods and mass-market retail formats. Cost compression in plant-based tiers is intensifying because pre-market approval timelines extend commercialization windows and dilute early-mover returns. Amateur athletes through direct-to-subscription channels show lowest price sensitivity, while supermarket functional food buyers exhibit highest elasticity.
Supply Chain Analysis
New Zealand and Australia anchor dairy protein supply through Fonterra's cross-Tasman infrastructure and Victorian whey processing corridors. Raw material flows draw from Murray-Dairy irrigation districts for domestic pea cultivation and North Island dairy cooperatives for whey feedstock. Single-source vulnerability concentrates in membrane filtration equipment and enzymatic hydrolysis catalysts imported from European suppliers. Distribution runs through Melbourne-Sydney specialty retail clusters for premium tiers and algorithm-driven subscription platforms for interstate penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia protein market tracks a cyclical recovery pattern as sports nutrition demand rebounds from pandemic-era gym closures and FSANZ regulatory clarity stabilizes following novel food review completions.
For Market Incumbents: Fortify traceability infrastructure investments ahead of tightened origin labelling mandates, locking in domestic supply chain verification that importers cannot replicate. Deepen backward integration into regional Victorian irrigation networks to secure pea protein input stability against yield volatility. Channel control through direct-to-subscription platforms defends margin position against specialty retail consolidation.
For New Entrants and Emerging Players: Anchor in Queensland's underpenetrated Brisbane-Gold Coast corridor where geographic distance from Melbourne-Sydney clusters accelerates digital channel migration. Target taste-masked functional food formulations for ready-to-drink applications, leveraging Kerry Group's demonstrated demand expansion beyond core athletic users. Go-to-market execution favors personalized nutrition platforms with algorithm-driven subscription mechanics over physical retail buildout.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-derived protein specialists with pilot-scale validation and pending FSANZ novel food pathways. Long-term viability across a 5-10 year window rests on regulatory approval velocity and agricultural input security rather than brand equity accumulation. Acquisition target archetype: domestic plant extraction facilities with secured irrigation access and established health store distribution. Signal to watch: FSANZ publication of final guidance on precision fermentation safety dossier requirements as inflection indicator for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FSANZ Novel Food Dossier Investment | Accelerates market access timelines for fermentation-derived protein entrants versus competitors awaiting approval. |
| Backward Integration into Victorian Irrigation Networks | Secures pea protein input supply against yield volatility squeezing domestic extraction facility margins. |
| Direct-to-Subscription Platform Launch | Captures Queensland and Western Australia demand as geographic distance from physical clusters increases digital preference. |
| Taste-Masked Formulation Partnership | Extends plant protein palatability into functional foods and ready-to-drink applications beyond core athletic users. |
| Traceability Infrastructure Deployment | Meets tightened origin labelling mandates under Australia New Zealand Food Standards Code compliance requirements. |
Study Parameters
The analysis maps whey protein concentrates, pea protein isolates, casein micellar structures, and precision fermentation inputs, each validated through formulation chemists, regulatory affairs specialists, sports nutrition brand managers, and specialty retail buyers. Primary interviews with ingredient procurement leads at functional food manufacturers and secondary validation through FSANZ novel food register entries, ACCC enforcement actions, TGA therapeutic claim determinations, and Australia New Zealand Food Standards Code amendment tracking enabled bottom-up and top-down triangulation.
Consistency checks against customs trade data for protein concentrate imports and Australian Bureau of Agricultural and Resource Economics crop yield statistics validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, application format, end-user fitness participation level, and distribution channel geography. CAGRs were derived from installed base growth rates and substitution elasticity parameters, with forecast inputs incorporating irrigation access projections for Victorian pea cultivation and sports participation survey trends from Fitness Australia.
Material uncertainties — FSANZ regulatory timeline revisions, Murray-Darling Basin irrigation allocation changes, and precision fermentation scale-up failures — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained amateur athlete participation growth and stable dairy cooperative supply structures. Recalibration cycles align with material shifts in FSANZ novel food approval velocity and agricultural input cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Europe Moringa Supplement Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Tongkat Ali Extract Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Testosterone Booster Market
Nutritional Supplements
Vitamin D Supplements Market