
 Pet Dietary Supplements Market | 2026-2036
Pet Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Dietary Supplements Market Outlook
North American manufacturing capacity expansion is reshaping competitive dynamics in pet dietary supplements. Nutramax Laboratories leverages its veterinary channel relationships to sustain clinical credibility. Mars Incorporated anchors retail shelf presence through pet specialty and mass-market networks. Zoetis Inc. competes by extending its animal health expertise into nutritional therapeutics.
Pet dietary supplements comprise formulated ingestible products containing bioactive compounds, including glucosamine, omega-3 fatty acids, and probiotic cultures, manufactured through cold-press extrusion or spray-drying to preserve viability, and intended to support physiological functions beyond basic nutrition in companion animals. Probiotics and omega fatty acids command expanding shelf space as pet owners prioritize digestive and dermatological wellness. Chews dominate the form category due to palatability engineering and dosing convenience. Veterinary clinics capture premium margin pools by dispensing condition-specific formulations under professional guidance.
The FDA's Center for Veterinary Medicine enforces labeling accuracy and substantiation of structure-function claims, while the National Animal Supplement Council operates a quality seal program that shapes retailer procurement criteria. State feed control officials in the United States administer AAFCO model regulations that determine product registration requirements. Stakeholders must monitor evolving enforcement priorities around cannabinoid and novel ingredient submissions.
Market Dynamics
Veterinary channel consolidation is compressing distribution layers and elevating clinical endorsement as the primary purchase trigger for condition-specific formulations.
Growth Catalysts
- Pet Humanization Trajectory:Companion animal owners in the United States now allocate discretionary spending toward preventive physiological support, expanding addressable demand beyond reactive therapeutic use.
- FDA Center for Veterinary Medicine Labeling Enforcement:Tightened substantiation requirements for structure-function claims are filtering substandard competitors and concentrating volume among quality-verified suppliers.
- Cold-Press Extrusion Advancement:Manufacturing process innovation preserves probiotic viability through shelf-stable delivery formats, unlocking veterinary clinic dispensing for live culture products.
Market Restraints
- Anchovy and Krill Supply Volatility:Omega-3 fatty acid raw material costs fluctuate with Peruvian and Antarctic fishery quotas, compressing margin stability for marine-derived formulations.
- Single-Source Probiotic Strain Dependency:Limited qualified suppliers of veterinary-specific Lactobacillus and Bifidobacterium cultures create concentration risk in digestive health product lines.
- State Feed Control Official Registration Heterogeneity:AAFCO model regulation adoption varies across United States jurisdictions, multiplying compliance burden for interstate distribution.
Strategic Opportunities
- Veterinary Telehealth Integration:Remote consultation platforms enable supplement recommendation at scale, bypassing physical clinic capacity constraints in underserved United States counties.
- Feline Underpenetration:Canine-centric formulation history leaves digestive and dermatological support for cats as white space with premium pricing tolerance.
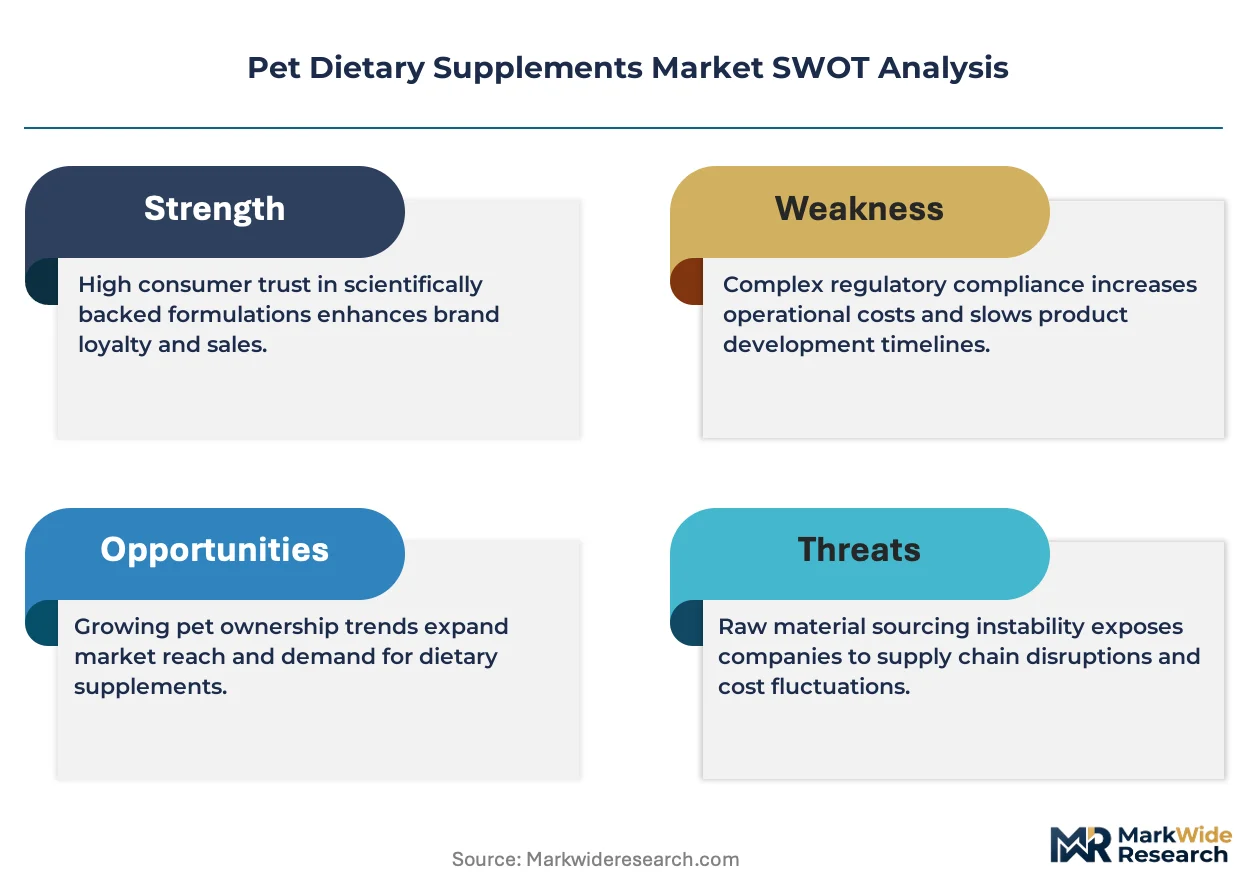
- National Animal Supplement Council Quality Seal Expansion:Retailer procurement criteria increasingly favor third-party verified products, creating competitive moat for seal-bearing suppliers.
Industry Challenges
- Veterinary Nutritional Pharmacology Training Gap:Clinician education in supplement-drug interaction assessment lags behind recommendation volume, exposing liability exposure.
- Legacy ERP Integration with Traceability Mandates:Batch-level ingredient sourcing documentation requirements strain small and mid-tier manufacturers with dated inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Dietary Supplements Market |
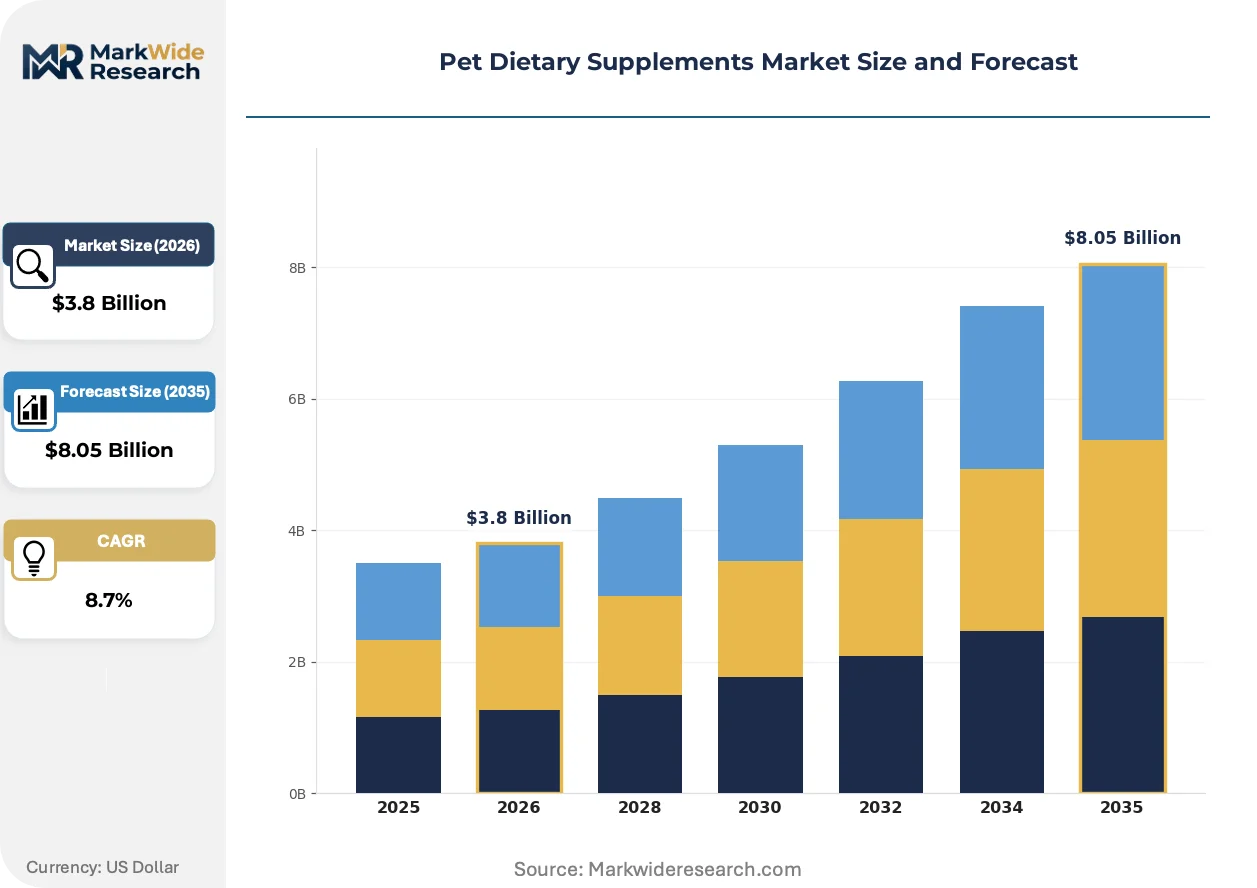
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Probiotics, Omega Fatty Acids Animal Type: Dogs, Cats, Birds, Rabbits Form: Pills, Chews, Powders, Liquids Distribution Channel: Online Retail, Pet Stores, Veterinary Clinics, Supermarkets |
| Companies Covered | General Mills Inc., Nutramax Laboratories, Mars Incorporated, Zoetis Inc., Elanco Animal Health, Nestlé, H&H Group, FoodScience LLC, Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Dietary Supplements Market Strategic Shifts
Formulation science is converging with delivery engineering to reshape how bioactive compounds reach companion animal physiology. Palatability masking and dose precision now determine competitive viability as much as ingredient efficacy.
Microencapsulation technology is migrating from pharmaceutical applications into pet supplement manufacturing. This spray-drying variant shields heat-sensitive probiotics and omega oils from gastric degradation. Premium veterinary clinic dispensers are adopting shelf-stable live culture products at accelerated rates. The technology is migrating from niche therapeutic use toward mainstream preventive formulations, compressing cold-chain dependency and expanding retail distribution feasibility.
The FDA Center for Veterinary Medicine has intensified scrutiny of cannabinoid and novel botanical ingredient submissions. This enforcement priority creates compliance friction for hemp-derived product lines. Manufacturers with existing New Animal Drug Application pathways gain structural advantage. United States-based suppliers are responding by diverting R&D spend toward GRAS-affirmed ingredients with established safety profiles.
Subscription-based replenishment models are displacing episodic retail purchasing among urban companion animal owners. Direct-to-consumer platforms capture recurring revenue while veterinary clinics defend position through autoship programs tied to wellness plans. This behavioral shift concentrates most visibly in United States coastal metropolitan markets where pet humanization indices peak.
Pet Dietary Supplements Market Segmentation
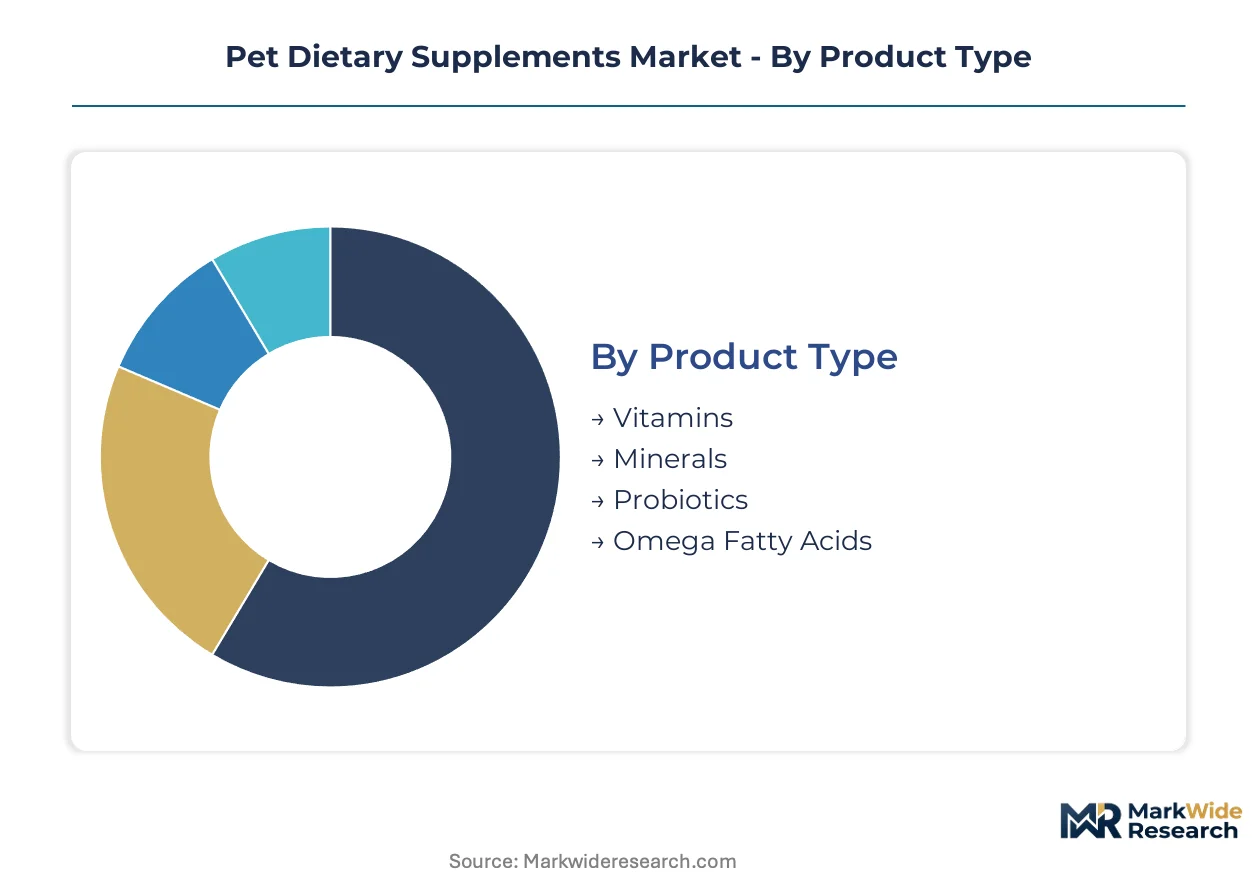
Pet dietary supplement manufacturers engineer distinct formulations around species-specific physiology and owner administration preferences. Segmentation discipline separates volume-driven commodity products from premium clinical-grade offerings.
Product Type:
After-sales service intensity varies sharply across product categories, with probiotics demanding cold-chain consulting and omega fatty acids requiring oxidation monitoring protocols.
- Probiotics:Live culture formulations containing Lactobacillus and Bifidobacterium strains require viability preservation through microencapsulation or refrigerated logistics. Veterinary clinics in the United States concentrate demand for shelf-stable variants that bypass cold-chain dependency. Cold-press extrusion advancement is filtering substandard suppliers unable to guarantee colony-forming unit counts at expiration.
- Omega Fatty Acids:Marine-derived eicosapentaenoic acid and docosahexaenoic acid concentrates target dermatological and anti-inflammatory support. Anchovy and krill supply volatility from Peruvian and Antarctic fisheries compresses margin stability for manufacturers dependent on single-source marine procurement.
- Vitamins:Synthetic and natural isolate blends address nutritional gaps in commercial pet food formulations.
- Minerals:Chelated and inorganic salt forms support skeletal development and metabolic enzyme function.
By volume, vitamins lead due to commoditized pricing and universal application. By growth pace, probiotics are gaining share fastest as veterinary endorsement accelerates.
Animal Type:
Cost tier stratification separates species markets, with canine formulations commanding premium pricing and feline products historically underinvested.
- Dogs:Large-breed joint support and senior cognitive formulations dominate R&D allocation. United States pet humanization trends drive discretionary spending toward preventive physiological support beyond reactive therapeutic use.
- Cats:Digestive and dermatological support historically lags canine development, creating white space with premium pricing tolerance. Palatability engineering challenges have constrained manufacturer entry due to finicky consumption patterns.
- Birds:Feather condition and calcium supplementation target avian-specific metabolic requirements.
- Rabbits:Fiber-adjunct digestive aids address hindgut fermentation support in companion lagomorphs.
Canine segments absorb the majority of clinical trial investment. Feline applications show the steepest expansion trajectory as formulation science closes palatability gaps.
Form:
Application context determines format selection, with veterinary clinics prioritizing dose precision and retail channels favoring palatability masking.
- Chews:Palatability-engineered matrices combine bioactive delivery with treat-like consumption experience. United States urban companion animal owners prioritize administration convenience in subscription-based replenishment models.
- Pills:Compressed tablets and gelatin capsules offer cost-efficient manufacturing with precise dosing. Veterinary clinics capture premium margin pools by dispensing condition-specific formulations under professional guidance.
- Powders:Top-dress formats enable flexible dosing across multiple animal sizes.
- Liquids:Pump-dispensers and droppers facilitate mixing with wet food or water.
Chews dominate unit volume through mass-market accessibility. Powders are climbing the fastest as raw feeders and home-prepared diet adherents seek flexible integration.
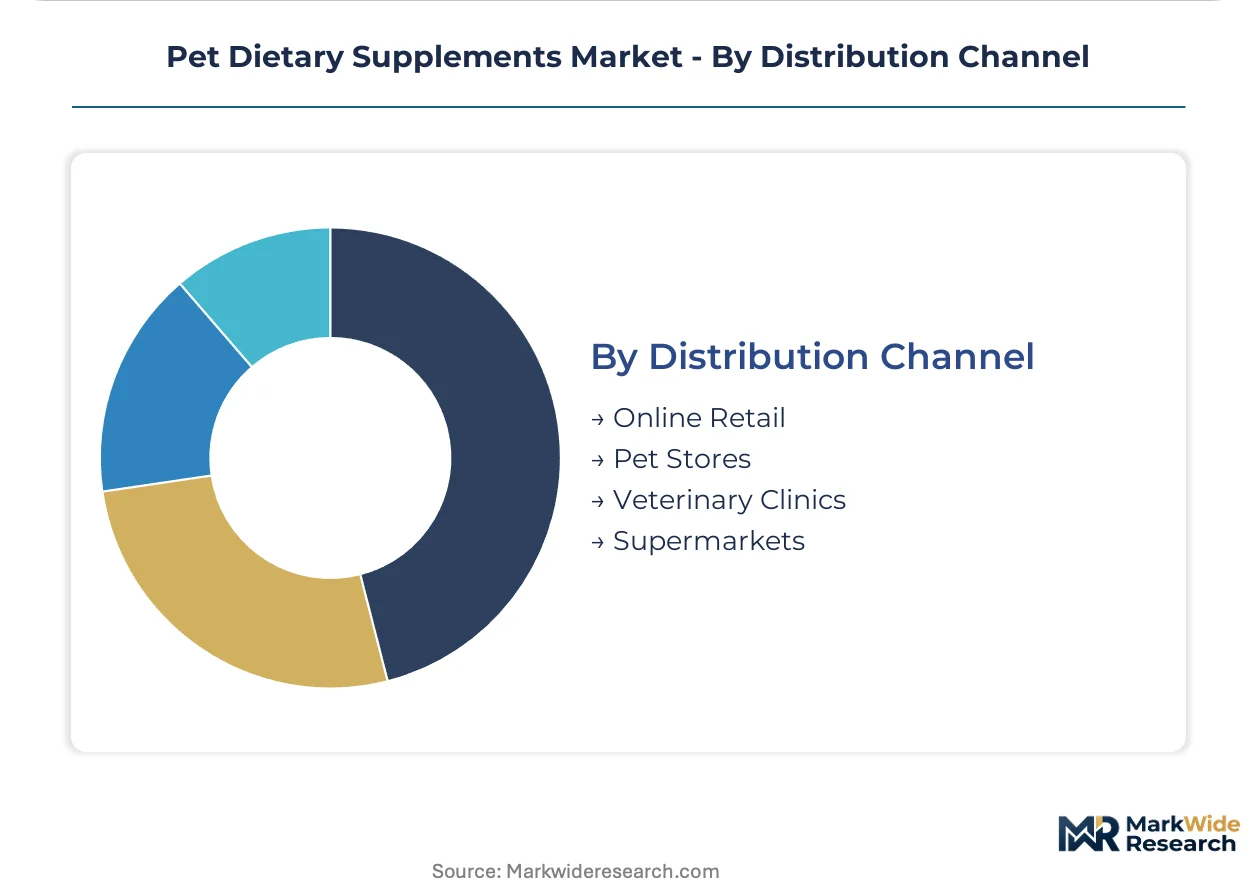
Distribution Channel:
Customer type fragmentation splits between clinically-guided purchasers and self-directed retail buyers with divergent information needs.
- Veterinary Clinics:Professional dispensing channels capture premium margin pools through condition-specific recommendation. FDA Center for Veterinary Medicine labeling enforcement filters substandard competitors and concentrates volume among quality-verified suppliers.
- Online Retail:Direct-to-consumer platforms and veterinary telehealth integration enable supplement recommendation at scale. Subscription-based replenishment models displace episodic purchasing among urban United States companion animal owners.
- Pet Stores:Specialty retailers curate premium and mid-tier assortments with staff consultation.
- Supermarkets:Mass-market placement drives commodity vitamin and mineral volume through impulse and routine purchase.
Veterinary clinics lead by value capture per transaction. Online retail is expanding most quickly as telehealth platforms bypass physical capacity constraints in underserved United States counties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine labeling enforcement anchors the United States as the dominant geography, while manufacturing capacity expansion across North America reshapes competitive dynamics in pet dietary supplements.
United States
Pet humanization trends drive discretionary spending toward preventive physiological support in companion animals. The FDA Center for Veterinary Medicine tightened substantiation requirements for structure-function claims, filtering substandard competitors. Kansas City and Omaha host expanding manufacturing clusters where cold-press extrusion facilities preserve probiotic viability for veterinary clinic dispensing.
Germany
Companion animal owners allocate premium spending toward dermatological and joint support formulations. EFSA guidelines on novel food ingredients shape ingredient approval pathways for cross-border EU distribution. Bavaria's industrial corridor concentrates spray-drying equipment manufacturers serving microencapsulation technology migration.
United Kingdom
Veterinary telehealth platforms enable supplement recommendation at scale in underserved counties. The Veterinary Medicines Directorate coordinates with FSA on cannabinoid ingredient enforcement priorities. London's direct-to-consumer subscription platforms capture recurring revenue from urban companion animal owners.
Japan
Aging pet demographics expand demand for senior cognitive and mobility support formulations. PMDA oversight of functional food claims extends to pet supplement labeling substantiation. Osaka's fermentation technology cluster supplies veterinary-specific Lactobacillus cultures for digestive health products.
Australia
Raw feeding adherents drive flexible-dose powder format demand for home-prepared diet integration. TGA guidance on complementary medicines informs state-level pet product registration requirements. Melbourne's specialty pet retail chains curate premium assortments with staff consultation on condition-specific formulations.
Pet Dietary Supplements Market Competitive Environment
Capability concentration sits with veterinary channel specialists; scale advantage sits with consumer packaged goods conglomerates. The market structures around three tiers: clinical-credibility players with veterinary relationships, retail-shelf dominators through mass-market networks, and animal health extenders leveraging nutritional therapeutics expertise. Strategic moves concentrate on veterinary telehealth integration and microencapsulation technology licensing.
Within the clinical-credibility tier, Nutramax Laboratories and Zoetis Inc. exemplify veterinary channel anchoring, while Mars Incorporated occupies a position bridging pet specialty and mass-market retail presence. These three represent distinct archetypes: the veterinary-dispensed formulation specialist, the animal health pharmaceutical extender, and the consumer goods scale player diversifying into companion animal nutrition.
| Leading Market Players |
|---|
| General Mills Inc. |
| Nutramax Laboratories |
| Mars Incorporated |
| Zoetis Inc. |
| Elanco Animal Health |
| Nestlé |
| H&H Group |
| FoodScience LLC |
| Colgate-Palmolive Company |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific container freight corridors from Peruvian anchovy fisheries to United States cold-press extrusion facilities concentrate cost volatility in marine-derived omega formulations, compressing margin pools for manufacturers lacking backward integration while amplifying price spreads between veterinary-dispensed premium tiers and mass-market commodity vitamins.
Pricing Analysis
United States coastal metropolitan markets command 15-25% premiums over inland distribution zones due to cold-chain logistics and subscription-model density. Three-tier pricing structure across premium, standard, and economy levels separates NASC seal-bearing veterinary formulations from retailer-exclusive mid-tier products and supermarket commodity vitamins. Price differentiation hinges on certification grade and clinical endorsement density. Pricing pressure stems from anchovy and krill supply quota volatility. Mass-market supermarket buyers exhibit highest price sensitivity; veterinary clinic purchasers show lowest elasticity due to professional recommendation dependency.
Supply Chain Analysis
Tariff exposure between Peru and United States dominates raw material cost volatility for marine-derived omega concentrates. Supply concentrates in United States heartland manufacturing clusters, Japanese fermentation technology corridors, and Peruvian fishery zones. Probiotic production draws from Lactobacillus strain banks in Osaka and spray-drying equipment manufacturers in Bavaria. Single-source vulnerability concentrates in veterinary-specific Bifidobacterium culture suppliers. Distribution runs through veterinary clinic dispensing networks, direct-to-consumer subscription platforms, and mass-market retail shelf placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures around regulatory entrenchment as its defensive moat. FDA Center for Veterinary Medicine labeling enforcement and NASC quality seal procurement criteria create switching costs that filter substandard competitors and concentrate volume among pre-qualified suppliers.
For Market Incumbents: Pre-empt feline formulation white space through palatability engineering R&D before competitors close consumption-pattern gaps. Lock in veterinary telehealth platform partnerships to bypass physical clinic capacity constraints in underserved United States counties. Anchor backward integration into probiotic strain development to reduce single-source supplier dependency. Defend margin pools by accelerating microencapsulation technology licensing to filter substandard live culture competitors. For New Entrants and Emerging Players: Australian raw feeding adherent communities present the most penetrable white space for flexible-dose powder formats targeting home-prepared diet integration. United Kingdom veterinary telehealth platforms enable supplement recommendation at scale without physical distribution infrastructure. Feline digestive and dermatological support historically lags canine investment, creating premium pricing tolerance for first movers. Pursue NASC quality seal acquisition as primary go-to-market credential to unlock retailer procurement criteria. For Investors and Strategic Acquirers: Carve-out targets emerge from consumer packaged goods conglomerates divesting non-core companion animal nutrition assets lacking veterinary channel anchoring. Long-term viability favors clinical-credibility players with FDA-substantiated structure-function claims and cold-press extrusion manufacturing capabilities. Target acquisition archetype: mid-tier manufacturers with dated ERP systems but established AAFCO registration portfolios, where operational turnaround unlocks value. Watch FDA enforcement priority shifts on cannabinoid and novel botanical ingredient submissions as inflection indicator for portfolio risk reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Spray-drying variant migration from pharmaceutical applications unlocks shelf-stable probiotic viability for veterinary clinic dispensing. |
| Veterinary Telehealth Platform Partnership | Remote consultation integration bypasses physical clinic capacity constraints in underserved United States counties. |
| NASC Quality Seal Acquisition | Third-party verification credential shapes retailer procurement criteria and filters substandard competitors from premium shelf placement. |
| Cold-Press Extrusion Capacity Expansion | Manufacturing process innovation preserves live culture counts through shelf-stable delivery formats, concentrating volume among quality-verified suppliers. |
| Feline Formulation R&D Investment | Palatability engineering breakthroughs close historical underpenetration in digestive and dermatological support with premium pricing tolerance. |
Study Parameters
A standing panel of veterinary nutrition specialists, FDA regulatory affairs consultants, pet specialty retail category buyers, and cold-press extrusion equipment manufacturers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA Center for Veterinary Medicine enforcement guidance documents, NASC quality seal program standards, AAFCO model regulation adoption tracking, and United States customs import data for anchovy and krill meal. Bottom-up demand modeling from veterinary clinic dispensing volumes triangulated against top-down market sizing from manufacturer production disclosures.
Scenario-bracketing framed projections across the analysis window through sensitivity testing of anchovy fishery quota volatility, probiotic strain supplier concentration risk, and veterinary telehealth adoption velocity. Segmentation dimensions modeled encompass product type, animal species, delivery form, and distribution channel granularity. CAGRs derived from logarithmic trend fitting of historical volume trajectories adjusted for structural shifts in pet humanization spending patterns and regulatory enforcement intensity. Industry-specific forecast inputs incorporated cold-chain logistics cost indices and microencapsulation technology diffusion rates.
Macroeconomic conditions sit as an overlay; deviation in discretionary consumer spending power and trans-Pacific freight rates would shift the trajectory. Forecasts reflect documented assumptions around FDA enforcement continuity and NASC seal program expansion. Material shifts in AAFCO model regulation adoption heterogeneity across United States state jurisdictions or Peruvian fishery quota administration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Pulse Protein Market
Nutritional Supplements
Collagen Supplements Market
Nutritional Supplements
Canada Whey Protein Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Folate Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
Tongkat Ali Extract Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Global Proanthocyanidins Market