
 Mushroom Powders Market | 2026-2036
Mushroom Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Mushroom Powders Market Foresight
The EU Green Deal is hardening sustainability requirements across European food ingredient supply chains. MycoTechnology Inc. leverages precision fermentation capabilities to reduce agricultural land intensity in mycelium production. GanoHerb Group anchors its competitive position through backward integration into organic reishi cultivation across Fujian Province. Four Sigmatic differentiates via direct-to-consumer subscription models that bypass conventional wholesale markups in functional beverage retail.
Mushroom powders are dehydrated, milled preparations of fungal fruiting bodies or mycelial biomass, typically standardized to polysaccharide content and processed through hot-water or dual-extraction methods to enhance bioactive compound availability. These powders serve as adaptogenic ingredients in functional foods, dietary supplements, and cosmetic formulations where beta-glucan and triterpenoid content delivers targeted physiological effects. Organic product type commands premium shelf positioning in North American health stores as clean-label procurement intensifies among supplement formulators. Nutraceuticals application leads volume absorption as clinical validation of lion's mane and reishi bioactives expands through peer-reviewed pharmacology journals. Online retail distribution channels are capturing margin pools previously held by specialty shops, driven by subscription replenishment algorithms and influencer-backed educational content.
FDA GRAS self-affirmation pathways and EFSA Novel Food authorizations jointly determine market access timelines for new mushroom-derived ingredients in transatlantic commerce. USDA Organic certification and EU Organic Regulation 2018/848 establish cultivation and processing standards that filter supplier eligibility for premium contract manufacturing. ISO 22000 and HACCP frameworks govern extraction facility audits that buyers mandate before qualifying vendors. Stakeholders must monitor evolving pharmacovigilance requirements as adaptogenic health claims face intensified scrutiny from national advertising regulators across major demand centers.
Market Dynamics
Precision fermentation is compressing production timelines for mycelial biomass while EU Novel Food Regulation reforms accelerate ingredient approval velocity, forcing legacy cultivators to retool extraction infrastructure or cede contract manufacturing share to biotech-enabled competitors.
Growth Catalysts
- EFSA Novel Food streamlining:The EU's consolidated safety assessment pathways reduce authorization timelines for mushroom-derived bioactives, enabling faster product launches across German and French nutraceutical markets.
- Functional beverage procurement:North American drink manufacturers are locking multi-year supply agreements for adaptogenic extracts as clean-label formulations displace synthetic nootropics in cognitive health positioning.
- Hot-water extraction standardization:Dual-extraction protocols achieving consistent beta-glucan titers are qualifying suppliers for pharmaceutical-grade contracts previously reserved for synthetic compounds.
Market Restraints
- Organic substrate cost volatility:Hardwood sawdust and grain spawn prices fluctuate with forestry harvest cycles, squeezing margin structures for non-integrated cultivators in Pacific Northwest growing regions.
- Geographic supply concentration:Fujian Province dominates reishi cultivation, creating single-source vulnerability for premium organic grades demanded by EU formulators.
- Wildcrafting substitution threat:Foraged mushroom harvesting in Eastern European forests competes on cost with cultivated powders, pressuring certified organic pricing premiums.
Strategic Opportunities
- Cosmeceutical application expansion:Truffle-derived melanin inhibitors and tremella polysaccharide hydrators are penetrating K-beauty formulations as functional skincare pivots from synthetic to fungal bioactives.
- Direct-to-consumer subscription channels:Replenishment algorithms bypass wholesale markups, capturing margin pools previously held by natural products retailers in urban Canadian markets.
- USDA Organic certification arbitrage:Domestic cultivation capacity expansion qualifies suppliers for federal procurement preferences as military and institutional foodservice programs adopt adaptogenic ingredients.
Industry Challenges
- Mycologist talent scarcity:Industrial-scale spawn production and contamination control require specialized fungal biology expertise that outpaces university training program output.
- Pharmacovigilance documentation burden:Adaptogenic health claims face intensified scrutiny from national advertising regulators, requiring clinical substantiation investments that strain mid-tier marketing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mushroom Powders Market |
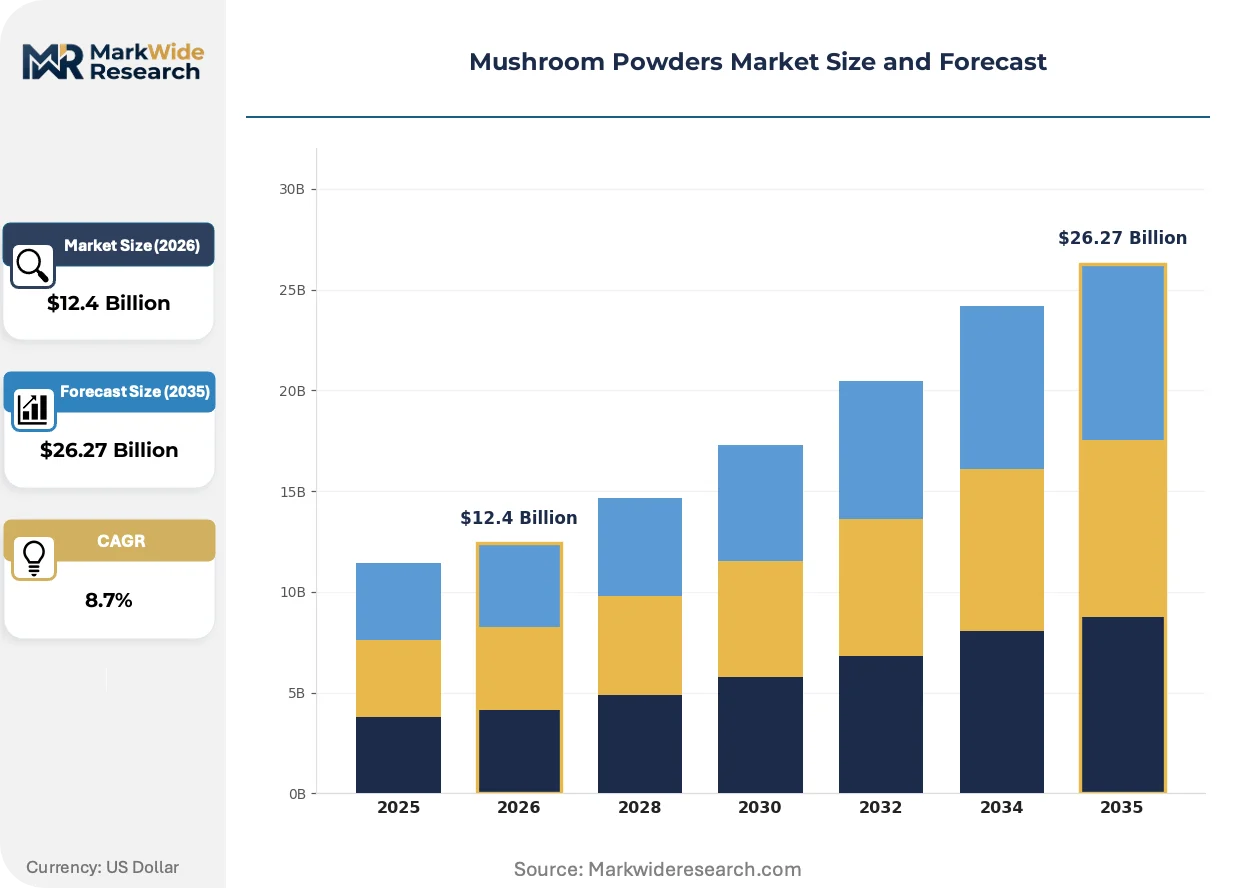
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Extracted, Blended Application: Food & Beverage, Nutraceuticals, Cosmetics, Pharmaceuticals Form: Powder, Capsule, Liquid, Granules Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | MycoTechnology Inc., M2 Ingredients, Om Mushroom Superfood, Mitoku Company Ltd, GanoHerb Group, Four Sigmatic, Monterey Nutra (Monterey Mushrooms), Hokkaido Reishi Co. Ltd, Nammex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mushroom Powders Market Shifts & Advancements
Bioprocess engineering and extraction technology convergence are compressing the gap between agricultural cultivation and pharmaceutical-grade ingredient production, while regulatory harmonization efforts reshape competitive qualification criteria across transatlantic commerce.
Precision fermentation of mycelial biomass is rewriting supplier economics by decoupling bioactive production from seasonal fruiting body harvests. Biotech-enabled ingredient houses now deliver consistent triterpenoid profiles year-round, attracting formulation contracts from nutraceutical manufacturers previously tethered to Chinese cultivation cycles. This capability is compressing price volatility and enabling just-in-time inventory models for functional beverage producers.
EU Green Deal sustainability requirements are hardening across European food ingredient supply chains, mandating carbon footprint disclosure and agricultural land-use intensity reductions. The CSRD reporting framework now captures Scope 3 emissions from mycelium substrate sourcing, pressuring non-integrated suppliers to document cultivation practices or forfeit premium contract eligibility. German and Dutch formulators are prioritizing vendors with verified organic processing and renewable energy-powered extraction facilities.
Subscription replenishment algorithms are displacing conventional retail stocking patterns as primary customer acquisition mechanisms. Influencer-backed educational content on TikTok and Instagram drives trial conversion for lion's mane and cordyceps powders, with direct-to-consumer brands capturing lifetime value through automated reorder cycles. This channel shift concentrates in North American urban markets where convenience positioning outweighs price sensitivity for wellness-focused demographics.
Mushroom Powders Market Segmentation
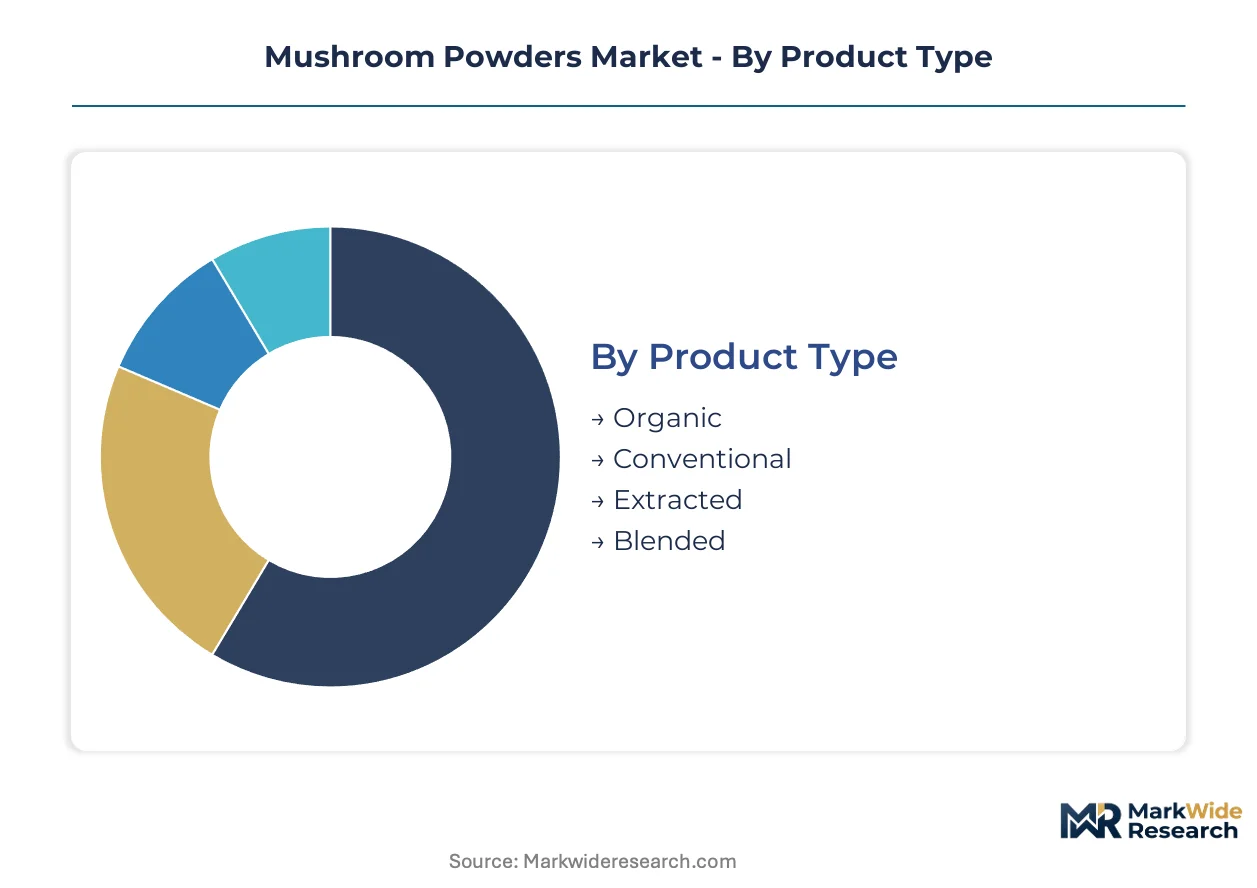
Segmentation in mushroom powders reveals divergent capital requirements across cultivation, extraction, and formulation stages. Procurement patterns vary sharply between pharmaceutical-grade buyers demanding certificate-of-analysis documentation and mass-market channels prioritizing price-per-gram efficiency.
Product Type:
Capital intensity peaks in certified organic processing chains requiring multi-year substrate conversion and third-party audit infrastructure.
- Organic:Hardwood substrate cultivation and multi-year transition periods for soil certification create barrier-to-entry costs that filter out small-scale competitors. German and Dutch formulators absorb the majority of premium organic volumes as EU Green Deal sustainability mandates harden procurement criteria.
- Extracted:Dual-extraction infrastructure—hot water for beta-glucans, ethanol for triterpenoids—demands seven-figure equipment investments that concentrate supplier bases in Fujian Province and Pacific Northwest clusters. Pharmaceutical contract manufacturers in Switzerland and Canada lock multi-year supply agreements for standardized polysaccharide titers.
- Conventional:Grain-spawn cultivation on agricultural byproducts minimizes upfront investment, serving price-sensitive foodservice blenders.
- Blended:Pre-formulated adaptogenic combinations reduce R&D burden for mid-tier functional beverage startups.
Organic absorbs the bulk of installed capacity; extracted is expanding most quickly.
Application:
Customer sophistication determines margin capture, with clinical substantiation requirements separating pharmaceutical buyers from commodity food processors.
- Nutraceuticals:Lion's mane and reishi powders standardized to hericenones and ganoderic acids command formulation slots in cognitive health and immune support SKUs. North American direct-to-consumer brands drive volume absorption through subscription replenishment models.
- Pharmaceuticals:Investigational new drug applications for fungal polysaccharides require current Good Manufacturing Practice compliance and pharmacovigilance documentation that only integrated cultivator-extractors can sustain. FDA GRAS self-affirmation pathways filter supplier eligibility for US drug development pipelines.
- Food & Beverage:Clean-label adaptogenic positioning in ready-to-drink formulations displaces synthetic nootropics in urban Canadian and US coastal markets.
- Cosmetics:Tremella polysaccharide hydrators and truffle-derived melanin inhibitors penetrate K-beauty and prestige skincare lines as functional ingredients pivot from synthetic to fungal bioactives.
Nutraceuticals dominates current revenue contribution; pharmaceuticals shows the steepest expansion trajectory.
Form:
Processing complexity and bioavailability engineering separate high-value formats from commodity presentations.
- Powder:Hot-water and dual-extraction protocols yield dehydrated, milled preparations standardized to polysaccharide content, serving bulk ingredient procurement by supplement formulators and functional food manufacturers.
- Capsule:Encapsulation infrastructure adds fill-weight precision and enteric coating capabilities for pharmaceutical-grade dosing requirements.
- Liquid:Glycerin-based tinctures and aqueous suspensions target convenience-positioned wellness demographics in direct-to-consumer channels.
- Granules:Agglomerated formats improve dispersibility in instant beverage applications for foodservice and hospitality sectors.
Powder commands the greatest production volume; liquid formats are climbing the fastest.
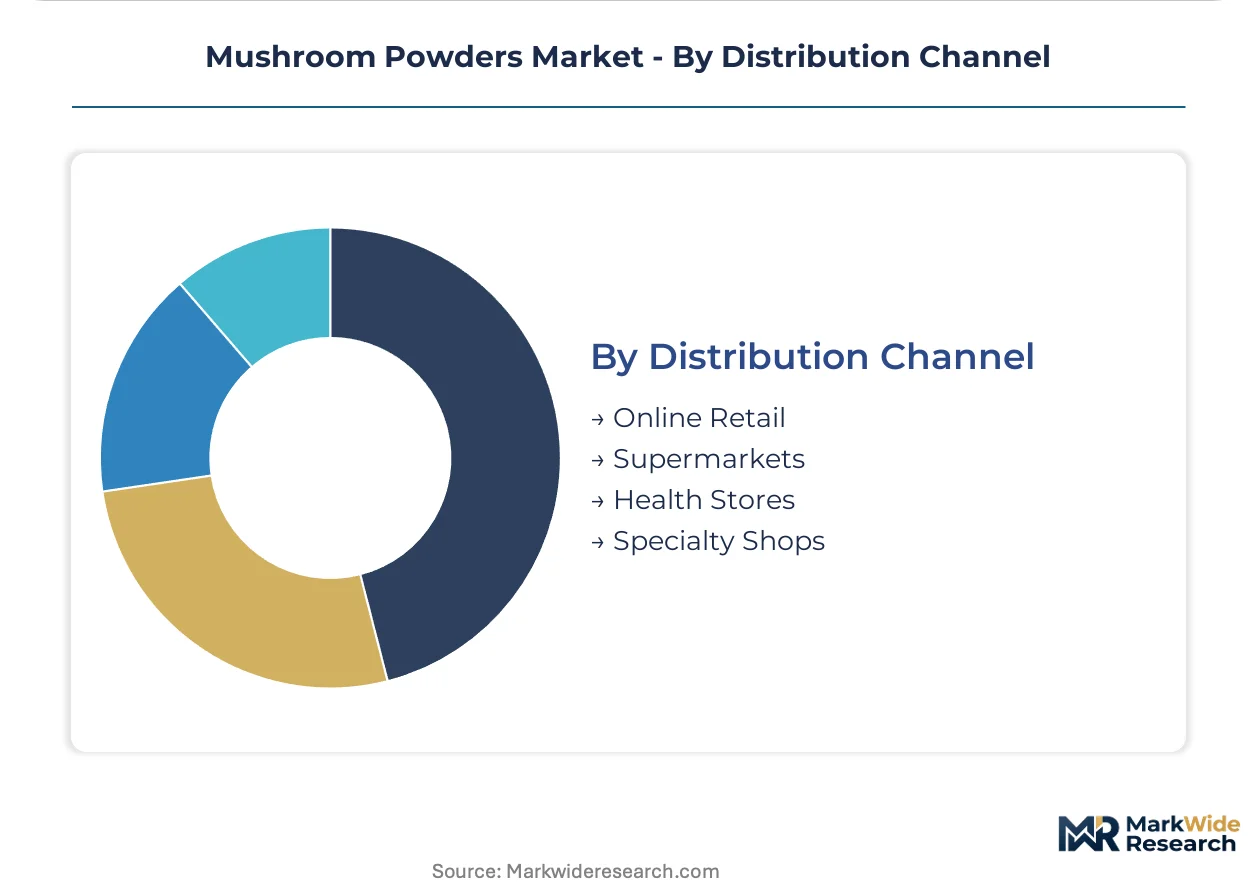
Distribution Channel:
Channel economics determine margin retention, with vertical integration into direct sales capturing pools previously held by wholesale intermediaries.
- Online Retail:Subscription replenishment algorithms and influencer-backed educational content on TikTok and Instagram drive trial conversion for lion's mane and cordyceps powders. Automated reorder cycles capture lifetime value in North American urban markets where convenience positioning outweighs price sensitivity.
- Health Stores:Staff-trained consultation environments support premium pricing for certified organic and dual-extracted products in Germany, where traditional mycotherapy intersects with modern nutraceutical retail channels.
- Supermarkets:Mass-market placement demands price-per-gram competitiveness and clean-label packaging for functional beverage and pantry ingredient adjacencies.
- Specialty Shops:Curated assortments in urban wellness districts serve discovery-oriented consumers seeking single-origin or small-batch provenance.
Online retail is gaining share fastest; health stores retain the highest margin per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fujian Province anchors global reishi cultivation capacity, with precision fermentation clusters emerging in the Netherlands and British Columbia as biotech-enabled production scales.
United States
Functional beverage manufacturers in California and New York Metro accelerate procurement of adaptogenic mushroom ingredients. FDA GRAS self-affirmation pathways determine market access timelines for new bioactive formulations. Pacific Northwest cultivation clusters around Oregon and Washington face hardwood substrate cost volatility from forestry harvest cycles.
Germany
Traditional mycotherapy intersects with modern nutraceutical retail channels in Berlin and Munich health stores. EFSA Novel Food streamlining reduces authorization timelines for mushroom-derived ingredients under EU consolidated safety assessment pathways. CSRD reporting frameworks now capture Scope 3 emissions from mycelium substrate sourcing across Bavarian processing facilities.
China
Fujian Province dominates organic reishi cultivation, creating single-source vulnerability for premium grades demanded by EU formulators. SAMR and national food safety standards govern extraction facility compliance for domestic and export markets. Zhejiang and Jiangsu provinces expand dual-extraction infrastructure to serve pharmaceutical-grade contract manufacturing.
Canada
Direct-to-consumer subscription channels concentrate in Toronto and Vancouver urban markets where convenience positioning outweighs price sensitivity. Health Canada and PMRA regulate novel food ingredients and natural health product licensing for adaptogenic powders. British Columbia precision fermentation startups attract formulation contracts from nutraceutical manufacturers seeking year-round bioactive consistency.
Netherlands
EU Green Deal sustainability requirements harden procurement criteria for Dutch formulators prioritizing verified organic processing. EMA and EFSA regulatory harmonization accelerates ingredient approval velocity for mycelium-derived bioactives. Rotterdam and Amsterdam logistics hubs facilitate just-in-time inventory models for European functional beverage distribution.
Mushroom Powders Market Competitive Landscape
The competitive structure tilts toward vertically integrated cultivator-extractors with certified organic processing chains. Tiered supplier bases separate pharmaceutical-grade contract manufacturers from commodity foodservice blenders. Three archetypes dominate: precision fermentation biotechs, backward-integrated Asian cultivators, and direct-to-consumer subscription brands. Capacity expansion and regulatory qualification investments constitute the primary competitive moves as EFSA and FDA pathways filter vendor eligibility.
Among North American biotech-enabled players, MycoTechnology Inc. and Monterey Nutra occupy positions emphasizing precision fermentation capabilities. GanoHerb Group represents the backward-integrated archetype with Fujian-based organic cultivation infrastructure. Four Sigmatic exemplifies direct-to-consumer channel concentration through subscription replenishment models.
| Leading Market Players |
|---|
| MycoTechnology Inc. |
| M2 Ingredients |
| Om Mushroom Superfood |
| Mitoku Company Ltd |
| GanoHerb Group |
| Four Sigmatic |
| Monterey Nutra (Monterey Mushrooms) |
| Hokkaido Reishi Co. Ltd |
| Nammex |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade contract manufacturers in Switzerland and Canada anchor demand for standardized beta-glucan titers, locking in value-based pricing premiums that cascade through dual-extracted supply tiers. This buyer concentration concentrates pricing power among integrated cultivator-extractors with certified organic processing chains, while commodity foodservice blenders absorb residual spot-market volatility.
Pricing Analysis
Outcome-linked pricing for cognitive health and immune support formulations anchors premium tiers, with hericenone-standardized lion's mane and ganoderic acid-calibrated reishi commanding formulation slots based on clinical substantiation rather than input cost. Certification grade—USDA Organic versus conventional substrate—and extraction protocol sophistication separate pharmaceutical-grade contracts from mass-market powder procurement. Cost compression in conventional grain-spawn cultivation is intensifying as hardwood substrate volatility squeezes Pacific Northwest growers. Commodity foodservice blenders exhibit highest price sensitivity, while Swiss and Canadian pharmaceutical buyers absorb premiums for certificate-of-analysis documentation.
Supply Chain Analysis
Hardwood sawdust and grain spawn inputs rest on forestry harvest cycles in the Pacific Northwest and agricultural byproduct streams in the American Midwest. Geographic supply concentrates in Fujian Province for organic reishi, British Columbia for precision fermentation startups, and the Netherlands for EU-facing extraction infrastructure. Single-source vulnerability in Fujian creates structural risk for premium organic grades demanded by German formulators. Distribution runs through Rotterdam and Amsterdam logistics hubs serving just-in-time inventory models for European functional beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mycologist talent scarcity constrains industrial-scale spawn production capacity, propping pricing premiums for qualified suppliers as university training program output lags field demand.
For Market Incumbents: Cement backward integration into organic substrate cultivation to buffer hardwood sawdust cost volatility from forestry harvest cycles. Lock multi-year supply agreements with North American functional beverage manufacturers before precision fermentation competitors achieve scale. Prioritize EFSA Novel Food authorization investments to defend contract manufacturing share against biotech-enabled entrants. For New Entrants and Emerging Players: Precision fermentation capabilities offer entry wedge into pharmaceutical-grade contract manufacturing previously reserved for seasonal fruiting body harvests. Target cosmeceutical applications in K-beauty formulations where tremella polysaccharide hydrators face limited incumbent competition. Pursue direct-to-consumer subscription channels with replenishment algorithms to bypass wholesale markups in urban Canadian markets. For Investors and Strategic Acquirers: The window for entry favors precision fermentation biotechs with year-round bioactive consistency and CSRD-compliant carbon footprint documentation. Vertically integrated cultivator-extractors with Fujian-based organic infrastructure and Swiss pharmaceutical-grade certifications represent prime acquisition archetypes. Monitor EFSA authorization velocity as inflection indicator for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Extraction Infrastructure Investment | Hot-water and ethanol processing capabilities qualify suppliers for pharmaceutical-grade contracts under FDA GRAS pathways. |
| Precision Fermentation Scale-Up | Biotech-enabled production decouples bioactive consistency from Chinese cultivation cycles, attracting nutraceutical formulation contracts. |
| EFSA Novel Food Authorization | Streamlined EU safety assessment pathways accelerate market access for mushroom-derived ingredients in German retail channels. |
| Direct-to-Consumer Channel Launch | Subscription replenishment algorithms capture lifetime value in North American urban wellness markets through TikTok-driven trial conversion. |
| USDA Organic Certification Expansion | Federal procurement preferences open military and institutional foodservice programs for domestic adaptogenic ingredient suppliers. |
Research Methodology
Multi-period observation of EFSA authorization timelines, FDA GRAS self-affirmation pathways, and hardwood substrate cost indices anchored the trend analysis, supplemented by interviews with extraction facility operators, functional beverage formulation directors, certified organic auditors, and pharmaceutical contract manufacturing procurement leads. Secondary validation drew from customs and trade data, SEC filings of publicly traded ingredient suppliers, EU Novel Food application databases, and CSRD sustainability disclosure frameworks. Bottom-up volume modeling across cultivation clusters triangulated against top-down value projections from nutraceutical and cosmeceutical end-use markets.
Input-output matrices mapped substrate sourcing through extraction processing to end-use formulation, with segmentation across organic versus conventional grades, pharmaceutical versus nutraceutical versus foodservice applications, and powder versus liquid versus capsule formats. CAGRs were derived from regression analysis of historical procurement patterns and projected substitution effects for synthetic nootropics. Forecast inputs incorporated precision fermentation capacity buildout timelines and EU Green Deal carbon intensity disclosure requirements.
Several conditions sit outside the modeled scope, including unforeseen pharmacovigilance enforcement actions, wildcrafting substitution shocks from Eastern European foraging, and abrupt shifts in influencer-driven consumer preference on social platforms. Forecasts reflect documented assumptions regarding regulatory harmonization pace and biotechnology scale-up economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market