
 Caps and Closures Market | 2026-2036
Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Caps and Closures Market Intelligence
Price differentiation between high-specification dispensing caps and commodity screw caps is decoupling from raw material costs. Specialized applications in personal care and pharmaceuticals demand complex, multi-part closures, creating a premium segment. AptarGroup Inc. specializes in this high-margin dispensing systems niche. In contrast, Berry Global Inc. leverages massive scale in the production of standard closures for the food and beverage industry, while Crown Holdings Inc. dominates the metal closure segment.
Caps and closures are devices designed to provide a seal for containers like bottles, jars, and tubes, preventing leakage and contamination. Their effectiveness depends on factors like thread profile integrity and the durometer of the sealing liner. While standard screw caps for the beverage application remain the largest volume segment, they offer lower margins. Higher value is captured in dispensing caps and complex closures for the pharmaceutical and personal care sectors, which represent the fastest-growing categories.
Regulatory frameworks significantly influence material composition and product design. In the United States, the FDA's regulations govern materials in contact with food and drugs. Concurrently, the European Union's REACH and single-use plastics directives are forcing a shift towards recyclable and recycled-content materials. Navigating these divergent and evolving sustainability mandates while maintaining product performance and safety is the central challenge for manufacturers.
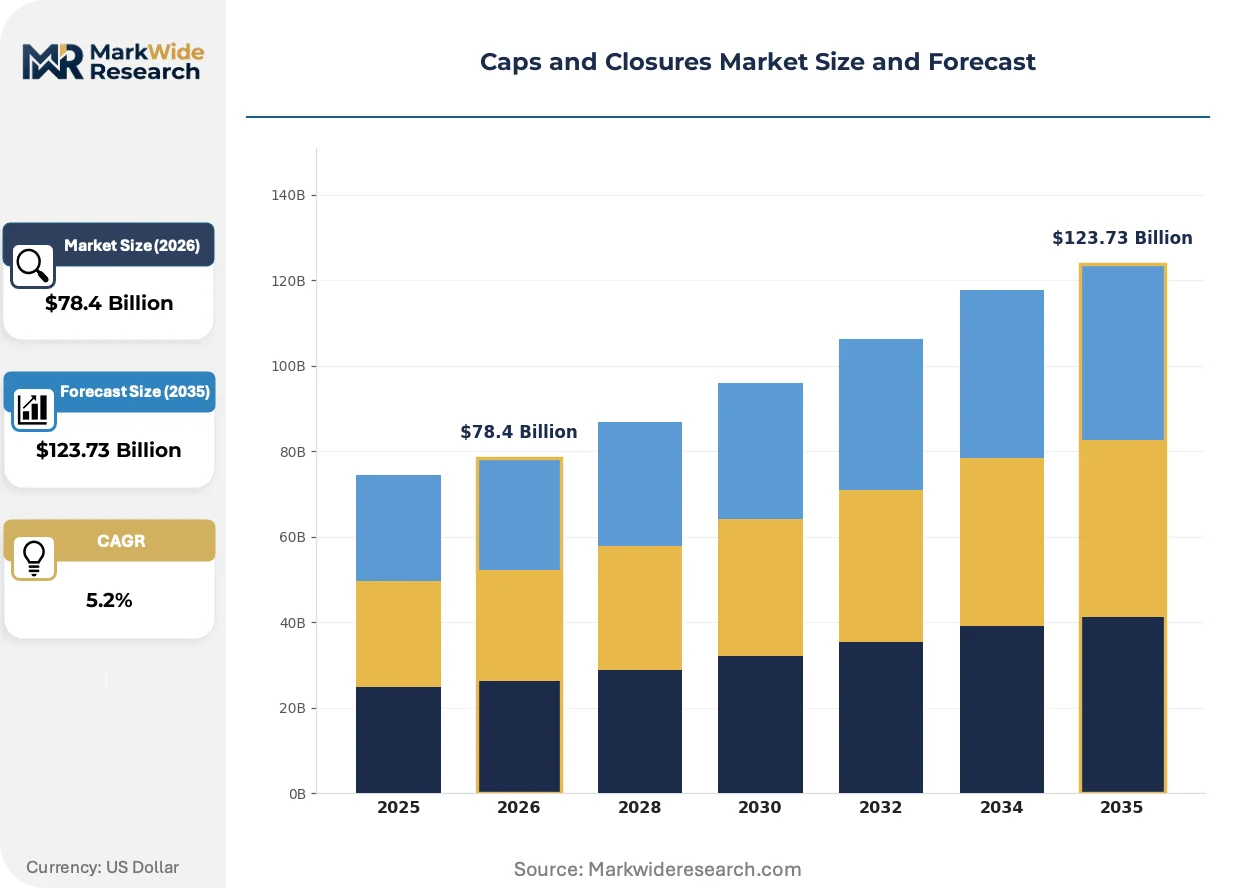
Market Dynamics
The core tension shaping the caps and closures market is the conflict between aggressive sustainability mandates pushing for material simplification and the rising complexity demanded by high-value pharmaceutical and personal care applications requiring multi-component, high-performance seals.
Growth Catalysts
- Pharmaceutical Demand:The expansion of the global pharmaceutical industry drives requirements for advanced closures that ensure sterility, tamper evidence, and precise dosing, such as those governed by regulators like the CDSCO in India or the FDA in the United States.
- Regulatory Mandates:The European Union's Single-Use Plastics Directive, specifically its requirement for tethered caps on beverage containers, is compelling a massive design and retooling cycle across the beverage industry.
- E-commerce Packaging:Growth in direct-to-consumer shipping of liquid products in personal care and food creates demand for highly reliable dispensing pumps and closures that prevent leakage during transit.
Market Restraints
- Raw Material Volatility:Manufacturer margins are constrained by price fluctuations in key feedstocks like polypropylene and polyethylene, which are tied to volatile global energy and chemical markets.
- Manufacturing Concentration:Extreme concentration of production capacity in specific industrial zones within China introduces significant supply chain fragility and exposes buyers to geopolitical and logistical disruptions.
- Performance of Sustainable Materials:The transition to recycled and bio-based plastics is hindered by their lower performance characteristics, including reduced durability and inconsistent barrier properties, which can compromise product integrity.
Strategic Opportunities
- Smart Closures:Integrating NFC or QR technologies into closures offers a pathway for brand protection, consumer engagement, and supply chain traceability, particularly for high-value spirits and pharmaceutical products.
- Refill and Reuse Systems:The circular economy movement creates an opportunity for closures designed for durability and repeated use, supporting new business models for brands in home care and personal care.
- Geographic Expansion:Rising disposable incomes in markets like Brazil and Indonesia are expanding the consumer base for packaged foods, beverages, and personal care items, creating new volume opportunities.
Industry Challenges
- Divergent Regulatory Compliance:Manufacturers face significant complexity in designing products that comply with conflicting sustainability regulations, such as the EU's REACH framework versus individual state-level mandates in the United States.
- High Capital Investment:The industry-wide shift towards new designs like tethered caps and the adoption of new materials require substantial, front-loaded capital expenditure on mold modifications and new production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caps and Closures Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Flip-Top Caps, Dispensing Caps, Pump Caps, Corks Material: Polyethylene, Polypropylene, Metal, Glass, Biodegradable Plastics, Elastomers Application: Beverages, Personal Care, Pharmaceuticals, Chemicals, Food Processing, Automotive Fluids End User: Packaging Manufacturers, Cosmetic Firms, Pharmaceutical Companies, Chemical Suppliers, Food & Beverage Producers |
| Companies Covered | Silgan Holdings Inc., AptarGroup Inc., Berry Global Inc., Crown Holdings Inc., Amcor Plc, BERICAP Holding GmbH, Guala Closures S.p.A, Closure Systems International, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caps and Closures Market Strategic Shifts & Innovations
The convergence of material science and digital technology is redefining the function of a closure beyond simple containment. This shift transforms the component from a passive seal into an active interface for brand protection, supply chain visibility, and consumer interaction.
Smart closures integrate technologies like Near Field Communication (NFC) chips directly into the cap. Pharmaceutical and luxury beverage brands are early adopters, seeking to combat counterfeiting and enhance consumer engagement. This integration is electrifying the previously analog supply chain, providing item-level data on product location, authenticity, and opening status from production to consumption.
Mandates from the European Union's Single-Use Plastics Directive require that plastic caps remain attached to beverage containers. This regulation forces a complete redesign of neck finishes and closure systems for the entire beverage sector. Consequently, beverage producers across Europe are accelerating capital investment in new molds and assembly lines to meet compliance deadlines.
A significant design preference shift towards mono-material solutions is gaining momentum, driven by brand owners' recyclability goals. This trend disrupts the market for complex dispensing pumps that use multiple materials, such as metal springs, which contaminate recycling streams. The personal care sector in Europe is leading this transition, favoring innovative all-polyolefin pump designs.
Caps and Closures Market Segmentation
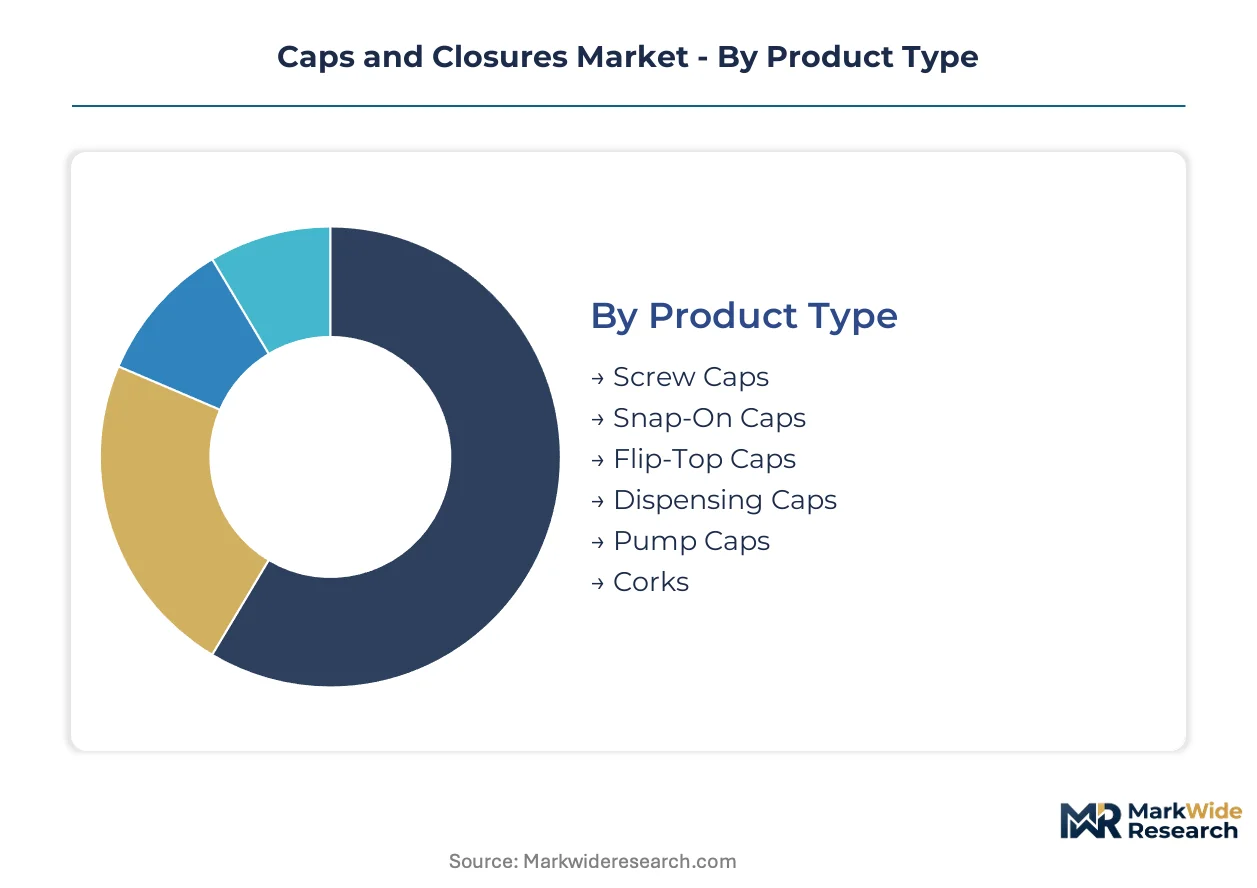
The caps and closures market exhibits distinct segmentation patterns, reflecting diverse functional requirements and material preferences across various end-use sectors. Understanding these segments clarifies the interplay between design complexity, material innovation, and regulatory compliance. Each category reveals specific competitive dynamics and value capture points for manufacturers.
Product Type:
Production capacity for standard screw caps is highly concentrated in large-scale facilities, driving commodity pricing. Specialized dispensing and pump closures, however, require more complex manufacturing processes.
- Screw Caps:These closures feature a threaded design, providing a secure, reclosable seal for bottles and jars. Demand from the beverage industry for high-volume applications drives significant production scale, though margins remain constrained.
- Dispensing Caps:Multi-component closures designed for controlled product delivery, often incorporating flip-top or push-pull mechanisms. The personal care and pharmaceutical sectors increasingly demand these for precise dosing and enhanced user experience, representing a high-value segment.
- Snap-On Caps:These closures provide a friction-fit seal, often used for convenience and ease of access. They find common application in dairy products and some cosmetic containers.
- Flip-Top Caps:Integrated hinge mechanisms allow for single-handed opening and closing, popular in personal care and food packaging for convenience.
- Pump Caps:Mechanical dispensing systems that deliver controlled doses of liquid products, widely used for lotions, soaps, and other viscous formulations.
- Corks:Traditional closures primarily for wine and spirits, valued for their natural material properties and aesthetic appeal in premium segments.
Today's leader: Screw Caps. Tomorrow's challenger: Dispensing Caps.
Material:
Margin structures in the caps and closures market are heavily influenced by raw material costs and the processing complexity of different polymers and metals.
- Polypropylene:A versatile thermoplastic polymer widely used for its chemical resistance, durability, and cost-effectiveness in various closure types. Demand remains strong across food and beverage applications.
- Biodegradable Plastics:Materials derived from renewable resources or designed to decompose naturally, gaining traction due to strict environmental mandates and brand sustainability goals. Performance limitations currently constrain wider adoption but innovation is accelerating.
- Polyethylene:A lightweight and flexible thermoplastic, frequently employed for snap-on and flip-top caps due to its excellent moisture barrier properties. It is a staple in the food and personal care sectors.
- Metal:Aluminum and steel closures offer superior barrier properties and tamper-evidence, predominantly used for carbonated beverages, food jars, and aerosol cans.
- Glass:Primarily used for pharmaceutical vials and high-end spirits, glass closures offer inertness and premium aesthetics.
- Elastomers:Flexible, rubber-like materials used for liners, septa, and specialized seals requiring high elasticity and chemical resistance, particularly in medical applications.
The shift towards Biodegradable Plastics is reshaping material selection, while Polypropylene maintains its foundational role.
Application:
Volume requirements for caps and closures vary dramatically across end-use applications, dictating production scale and design priorities for manufacturers.
- Beverages:This segment accounts for the largest volume of caps and closures, primarily driven by standard screw caps for bottled water, soft drinks, and juices. Regulatory changes like tethered caps are forcing significant redesigns.
- Pharmaceuticals:Requires highly specialized, tamper-evident, and child-resistant closures to ensure drug safety and integrity. Regulations from the FDA and EMA drive stringent material and design specifications for these high-value products.
- Personal Care:Demands aesthetically pleasing and functional dispensing solutions, including flip-top, pump, and fine mist spray caps. Consumer convenience and brand differentiation are key drivers.
- Chemicals:Requires closures with high chemical resistance and robust sealing properties to prevent leakage of corrosive or hazardous substances.
- Food Processing:Utilizes a wide range of closures, from standard screw caps for sauces to specialized snap-on lids for dairy products, prioritizing food safety and shelf-life extension.
- Automotive Fluids:Closures for engine oils, coolants, and other automotive liquids must withstand harsh chemicals and temperature fluctuations, ensuring product integrity.
Demand from Beverages continues to drive scale, while Pharmaceuticals offers premiumization opportunities.
End User:
Customer type significantly influences the procurement strategies and product specifications for caps and closures, from high-volume commodity buyers to specialized solution seekers.
- Food & Beverage Producers:These companies are the largest purchasers of caps and closures, prioritizing cost-efficiency, high-speed compatibility, and compliance with food contact regulations. Volume consistency is paramount.
- Pharmaceutical Companies:Require closures that meet stringent regulatory standards for sterility, tamper evidence, and child resistance. Customization for specific drug delivery systems is common, often involving multi-component designs.
- Packaging Manufacturers:Often integrate closures into complete packaging solutions for their diverse client base, seeking reliable supply and design flexibility.
- Cosmetic Firms:Focus on aesthetic appeal, brand differentiation, and functional dispensing mechanisms for their products, driving demand for innovative and visually attractive closures.
- Chemical Suppliers:Require durable and chemically resistant closures that ensure safe containment and dispensing of industrial and household chemicals.
Strategic partnerships with Food & Beverage Producers are critical for volume, whereas serving Pharmaceutical Companies requires specialized product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled manufacturing workforces across China anchor global production volumes for caps and closures. This global market experiences significant demand shifts driven by evolving consumer preferences and stringent regulatory frameworks. Material innovation and design complexity are central to regional market dynamics.
China
Demand for caps and closures in China remains robust, driven by the massive food and beverage sector and an expanding personal care market. Government initiatives like the dual carbon goals influence material selection and manufacturing processes. Major production facilities in the Yangtze River Delta region continue to drive high-volume output.
United States
The United States market prioritizes advanced closures for pharmaceuticals and premium personal care products. FDA regulations govern material safety and tamper-evident features for drug packaging. Innovation clusters in the Midwest and Northeast focus on developing specialized dispensing solutions.
Germany
Germany's caps and closures sector is significantly impacted by European Union directives, particularly the Single-Use Plastics Directive for tethered caps on beverages. The EU REACH framework influences material composition, pushing for sustainable alternatives. Advanced manufacturing hubs in Bavaria and North Rhine-Westphalia lead in retooling for new designs.
India
India's pharmaceutical industry drives substantial demand for secure and compliant closures, regulated by the CDSCO. A rapidly expanding consumer base also fuels requirements for food, beverage, and personal care packaging. Industrial zones in Maharashtra and Gujarat are seeing increased investment in packaging manufacturing capacity.
Brazil
Brazil's growing middle class and expanding packaged food and beverage industries create significant demand for caps and closures. ANVISA regulations influence material standards for products in contact with food and pharmaceuticals. Manufacturing activity in the São Paulo state supports diverse packaging requirements across the region.
Caps and Closures Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the caps and closures market. This industry exhibits a tiered structure, ranging from high-volume commodity manufacturers to specialized providers of complex dispensing systems. Strategic archetypes include large-scale plastic converters, niche metal closure specialists, and innovative dispensing solution developers. Companies pursue capacity expansion and portfolio diversification to maintain competitive positioning.
Specialized dispensing system providers like AptarGroup Inc. occupy a premium segment, focusing on high-value applications in personal care and pharmaceuticals. In contrast, Berry Global Inc. demonstrates expertise in large-scale production of standard closures, particularly for the food and beverage industry. Crown Holdings Inc. dominates the metal closure segment, serving beverage and food processing applications with robust sealing solutions.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| AptarGroup Inc. |
| Berry Global Inc. |
| Crown Holdings Inc. |
| Amcor Plc |
| BERICAP Holding GmbH |
| Guala Closures S.p.A |
| Closure Systems International |
| Ball Corporation |
| Others |
Cost & Logistics Intelligence
The European Union's Single-Use Plastics Directive, mandating tethered caps, gates both qualified supply and premium-tier pricing access for beverage packaging. This regulatory shift forces significant capital investment and retooling across the supply chain, impacting cost structures.
Pricing Analysis
The complex versus commodity product pricing models define market value. Per-unit transactional pricing dominates standard screw caps, while contract-based long-term offtake agreements secure specialized dispensing systems. Customization level and FDA/EMA certification significantly drive price differentiation, reflecting specialized manufacturing and regulatory compliance costs. Pricing pressure stems from volatile raw material costs, particularly polypropylene and polyethylene. Food & Beverage producers demonstrate the highest price sensitivity, contrasting with pharmaceutical companies that prioritize performance and regulatory adherence over cost.
Supply Chain Analysis
Logistics and freight costs significantly impact the delivered price of caps and closures, especially given globalized production. Geographic supply concentration centers in China, Germany, and the United States, creating regional dependencies. Raw material supply draws from key feedstocks like polypropylene and polyethylene, which are tied to global energy markets. Geopolitical and logistical disruptions, alongside commodity price volatility, represent a structural supply chain risk. Distribution runs through direct-to-manufacturer channels for large volume buyers and packaging integrators for diverse client bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The caps and closures market acts as a regulatory compounder, with the European Union's Single-Use Plastics Directive driving substantial design and production overhauls.
For Market Incumbents:
Acquire specialized manufacturing capabilities in bio-based and recycled materials to meet evolving sustainability mandates. Consolidate market share in high-growth regions like Southeast Asia through strategic partnerships or local capacity expansion. Invest heavily in R&D for next-generation mono-material dispensing solutions to counter the threat of complex multi-material designs being phased out. Focus on enhancing automation to mitigate raw material volatility and labor cost pressures.
For New Entrants and Emerging Players:
Direct-to-consumer brands often seek agile suppliers offering innovative, sustainable packaging solutions. Target this underserved buyer archetype by providing specialized, certified closures for personal care and nutraceuticals. Focus on developing high-performance, bio-based plastic closures that address current material performance limitations. A direct sales model emphasizing material science expertise and rapid prototyping can offer a strong go-to-market angle.
For Investors and Strategic Acquirers:
Roll-up economics work for financial sponsors because market fragmentation persists across specialized niches, offering consolidation opportunities. Long-term viability over a 5-10 year window favors companies with strong intellectual property in sustainable materials and advanced dispensing technologies. Target specialized dispensing system providers and manufacturers with established positions in pharmaceutical or personal care segments. The signal to watch is increased M&A activity within the bio-plastics and tethered cap technology space.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Tethered Cap Production | Increases compliance readiness for beverage clients facing EU Single-Use Plastics Directive mandates. |
| R&D in Mono-Material Dispensing Systems | Addresses brand owner demand for enhanced recyclability, particularly in personal care applications. |
| Strategic Partnership with Bio-Plastic Suppliers | Secures access to innovative, sustainable feedstocks, reducing reliance on virgin fossil-based polymers. |
| Geographic Expansion into Emerging Markets | Captures growing demand from expanding consumer bases for packaged goods in Brazil and India. |
| Investment in Smart Closure Technology | Offers brand protection and consumer engagement features for high-value pharmaceutical and spirits products. |
Research Approach
Direct dialogue with packaging engineers, procurement leads, and regulatory compliance officers provided qualitative grounding for market trends. This primary research was complemented by extensive secondary validation using FDA regulations, EU directives, trade association reports, and corporate sustainability disclosures. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy across various market segments.
Market size and growth projections were generated through a robust analytical framework, integrating historical data with forecast models. Segmentation dimensions modeled included product type, material, application, end-user, and geographic region across the analysis window. Compound annual growth rates were derived from historical trends, market growth drivers, and expert consensus. Pharmaceutical R&D spending and packaged food consumption rates served as key industry-specific forecast inputs.
Inputs from public financial disclosures and trade publications were available through the study window; gaps in emerging material performance data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements, regulatory stability, and economic conditions. Stakeholders should weigh these assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Cap Seals Market
Caps and Closures
Europe Metal Caps and Closures Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Foam End Caps Market