
 United States Plastic Caps and Closure Market | 2026-2036
United States Plastic Caps and Closure Market Size, Share, and Industry Trends Forecast 2026-2036
United States Plastic Caps and Closure Market Intelligence
A shift from single-source resin procurement toward multi-source polymer sourcing is realigning supplier relationships across the Midwest and Southeast. Silgan Holdings Inc. leverages captive blow-molding capacity to control cost volatility in polyethylene-based closures. AptarGroup, Inc. differentiates through precision dispensing technologies for personal care applications. Amcor plc anchors its position via integrated recycling streams that feed post-consumer resin back into closure production lines.
Plastic caps and closures are threaded or snap-fit sealing devices, typically injection-molded or compression-molded from thermoplastic resins, designed to preserve product integrity, enable controlled dispensing, and support tamper-evident functionality across liquid and semi-solid packaged goods. Polypropylene dominates material selection for hot-fill beverage applications due to thermal stability and hinge-flex performance in flip-top formats. Screw caps retain the largest volume share in pharmaceutical and household segments where resealability and child-resistant mechanisms command premium positioning. Snap-on closures represent the fastest-growing product configuration in single-serve beverage and on-the-go personal care formats where convenience and production speed outweigh threaded security requirements.
FDA regulations under 21 CFR 177 govern indirect food-additive status for polyolefin closures, while EPA guidelines on post-consumer recycled content are pressuring converters to validate rPP and rPE streams for direct-contact applications. State legislation in California and New York is accelerating extended producer responsibility frameworks that obligate closure manufacturers to fund collection and reprocessing infrastructure. OSHA lockout/tagout standards and NHTSA child-resistance testing protocols further constrain design freedom for pharmaceutical and automotive chemical closures. Stakeholders must monitor how fragmented state-level recycled-content thresholds will force capital allocation toward dual-track virgin and recycled resin processing capabilities before federal harmonization emerges.
Market Dynamics
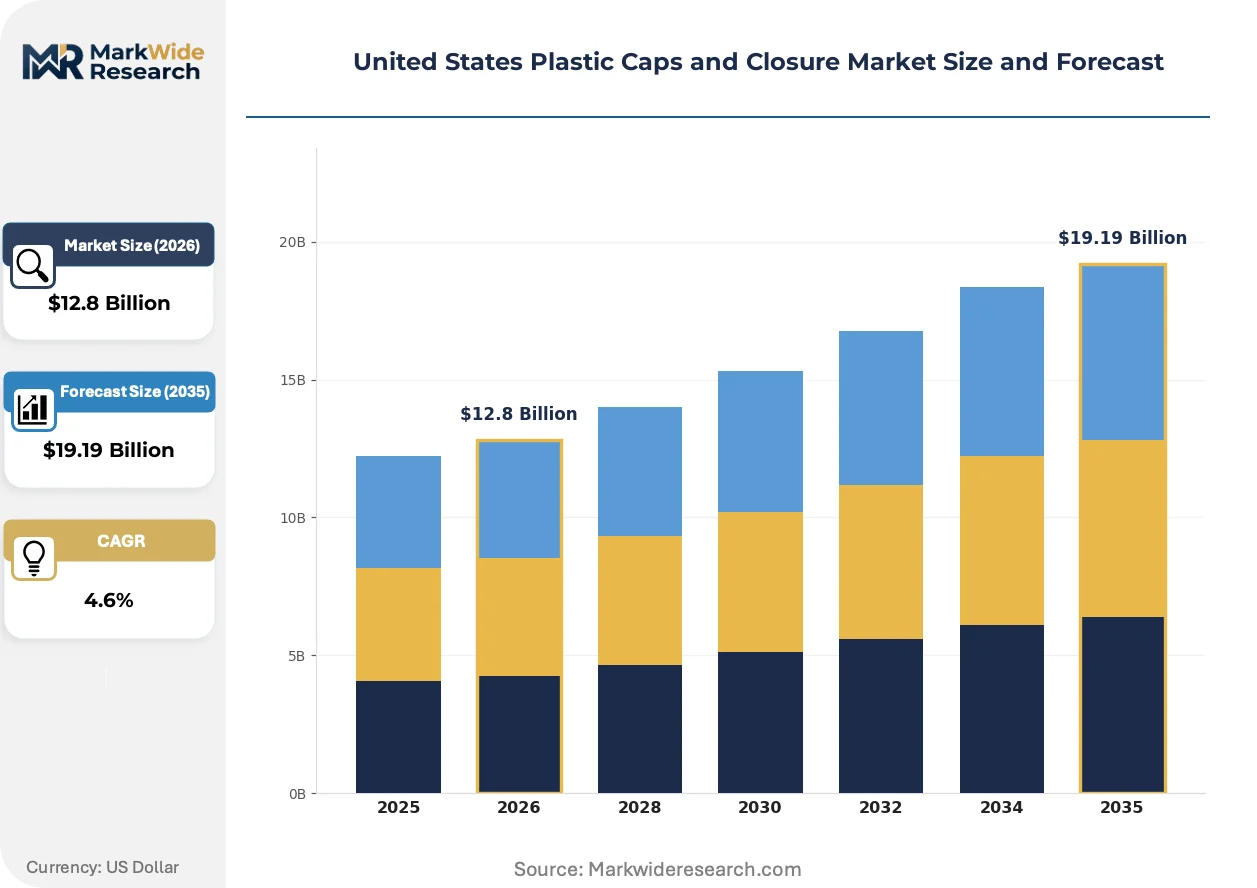
State-level recycled-content mandates are forcing converters to reconfigure resin procurement and validate dual-track virgin and recycled processing lines before federal harmonization emerges. This regulatory fragmentation is the dominant structural force reshaping capital allocation and supplier relationships across the United States.
Growth Catalysts
- California SB 54 Implementation:Extended producer responsibility frameworks obligate closure manufacturers to fund collection infrastructure, accelerating rPP and rPE validation for direct-contact applications.
- Lightweighting Technologies:Beverage bottlers are expanding adoption of reduced-weight closures, cutting resin consumption per unit while maintaining seal integrity and tamper-evident performance.
- Great Lakes Manufacturing Corridor Concentration:Dense clustering of injection-molding capacity and blow-molding integration creates cost efficiencies and rapid prototyping capabilities for regional brand owners.
Market Restraints
- Propylene Feedstock Volatility:Gulf Coast petrochemical hub concentration exposes converters to hurricane disruption and ethane-to-propylene cracking economics that swing resin pricing unpredictably.
- FDA 21 CFR 177 Compliance Burden:Indirect food-additive validation for recycled polyolefin streams requires extensive migration testing, slowing rPP and rPE qualification timelines.
- Aluminum Can Substitution:Beverage brand owners are expanding aluminum bottle and can formats with integrated pull-tabs, displacing threaded plastic closures in premium sparkling water segments.
Strategic Opportunities
- IRA Clean Manufacturing Credits:Section 45X advanced manufacturing production credits incentivize domestic recycling infrastructure investment, lowering effective cost basis for post-consumer resin processing.
- Precision Dispensing Convergence:Integration of flip-top hinge-flex designs with metered-dose mechanisms opens pharmaceutical and personal care applications requiring exact volume control.
- Gulf Coast Chemical Recycling Scale-Up:Pyrolysis and depolymerization facilities under construction in Texas and Louisiana will expand feedstock availability for food-grade rPP production.
Industry Challenges
- Dual-Track Processing Capital Requirements:Validating parallel virgin and recycled resin streams demands duplicate extrusion and quality-control lines, stretching mid-cap converter balance sheets.
- Child-Resistance Certification Complexity:NHTSA testing protocols for pharmaceutical closures require iterative design cycles, extending product development timelines and raising engineering headcount needs.
- Fragmented State Thresholds:California, New York, and Washington maintain divergent recycled-content percentages and compliance timelines, complicating national SKU rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Plastic Caps and Closure Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top Caps, Spout Caps, Screw Caps, Snap-On Caps Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others Application: Beverages, Personal Care, Pharmaceuticals, Household End User: Food & Beverage, Cosmetics, Medicine, Cleaning Products |
| Companies Covered | Silgan Holdings Inc., AptarGroup, Inc., Amcor plc, Closure Systems International Inc., Berry Global Inc., Crown Holdings Inc., Albéa S.A., TriMas Corporation, BERICAP GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Plastic Caps and Closure Market Strategic Shifts & Innovations
Digital manufacturing and materials science are converging to compress development cycles and enable mass customization of closure geometries. Three developments are restructuring how converters compete on speed, compliance, and functional differentiation.
Digital twin simulation of injection-mold flow patterns is modularizing how toolmakers optimize cooling channel design and cycle times. Closure manufacturers serving beverage and personal care segments are adopting cloud-based mold simulation platforms to reduce physical prototyping iterations. This technology is modularizing the traditional sequential design-to-tooling handoff, compressing time-to-market from months to weeks.
EPA guidelines on post-consumer recycled content are pressuring converters to validate rPP and rPE streams for direct-contact food applications. The industrial consequence is accelerated investment in chemical recycling and advanced mechanical sorting to achieve FDA-compliant purity levels. Beverage bottlers in California and New York are responding by specifying certified recycled content minimums in procurement contracts.
Brand owner consolidation is compressing supplier negotiation cycles and consolidating purchase volumes with fewer converters. Large beverage and pharmaceutical buyers are unbundling closure supply from bottle contracts, creating direct relationships with specialized closure manufacturers. This pattern is most visible in the Midwest, where CPG headquarters concentration enables face-to-face supplier performance reviews and rapid specification changes.
United States Plastic Caps and Closure Market Segmentation
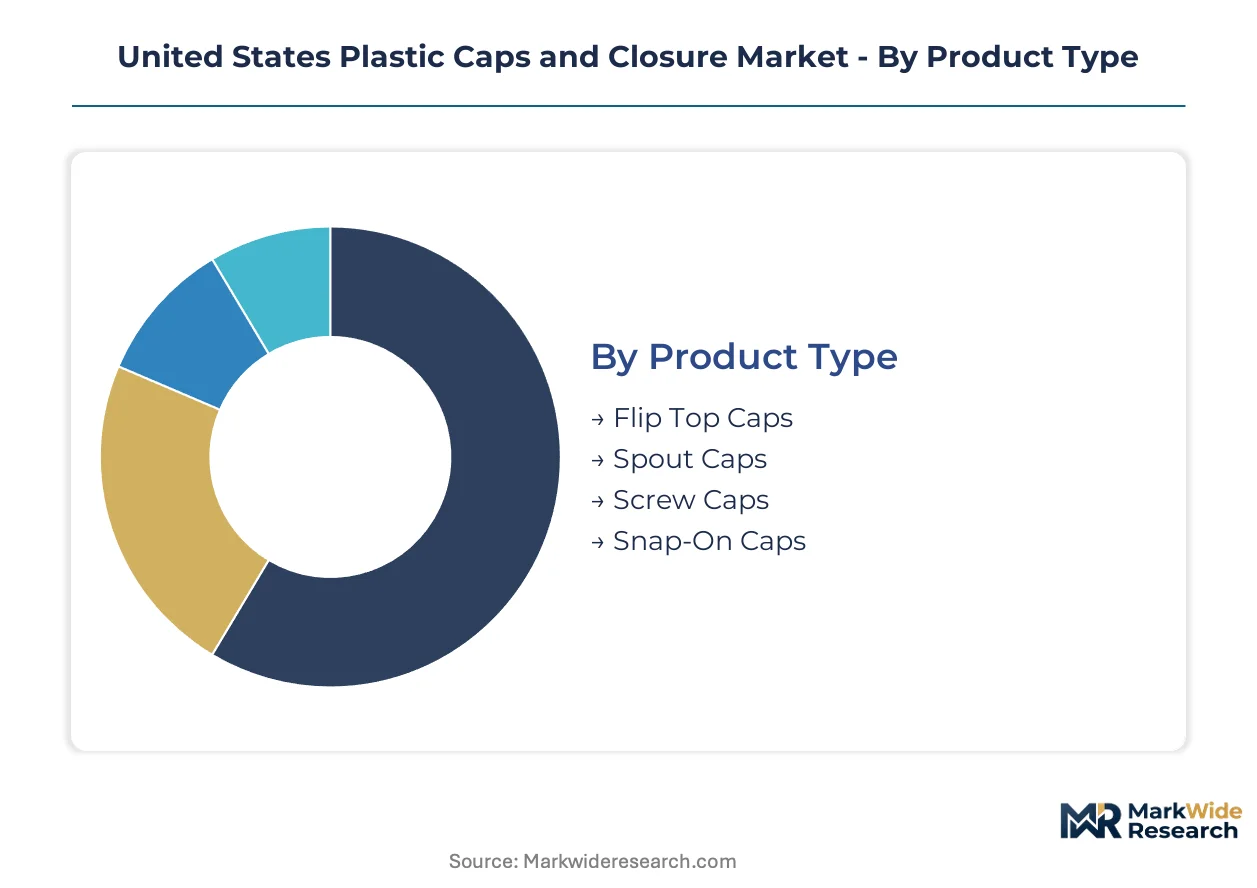
Plastic caps and closures segment along functional, material, and demand dimensions that determine procurement patterns and margin structures. Understanding these splits reveals where converters must build specialized tooling capabilities versus commodity scale.
Product Type:
Buyers select closure formats based on resealability requirements, production line speed, and tamper-evidence needs across liquid and semi-solid applications.
- Screw Caps:Threaded designs with precision pitch tolerances dominate pharmaceutical and household segments where resealability and child-resistant mechanisms command premium positioning. Demand concentrates in Midwest CPG corridors where blow-molding integration enables rapid specification changes for regional brand owners.
- Snap-On Caps:Compression-fit configurations eliminate threading operations, accelerating line speeds for single-serve beverage and on-the-go personal care formats. Gulf Coast bottlers are expanding adoption where convenience and throughput outweigh threaded security requirements.
- Flip Top Caps:Hinge-flex designs integrate dispensing control with one-handed operation for condiments and personal care products.
- Spout Caps:Directional flow geometries target controlled-pour applications in automotive and industrial chemical packaging.
Screw caps lead on scale; snap-on caps lead on momentum.
Material:
Resin selection hinges on thermal stability, chemical resistance, and recycled-content compliance timelines facing FDA validation.
- Polypropylene:Semi-crystalline thermoplastic with hinge-flex fatigue resistance dominates hot-fill beverage applications and flip-top living hinges. California and New York procurement contracts are accelerating rPP validation for direct-contact food applications under state extended producer responsibility frameworks.
- Polyethylene:Lower density and superior moisture barrier properties anchor screw-cap and snap-on production for pharmaceutical and household segments. Silgan Holdings controls cost volatility through captive blow-molding capacity integrated with Gulf Coast petrochemical supply.
- Polyvinyl Chloride:Rigid formulation serves niche chemical resistance requirements in industrial and agricultural chemical closures.
- Others:PET and bio-based polymers occupy emerging sustainability-driven specifications with limited current volume.
Polypropylene dominates current throughput; polyethylene holds the steepest expansion trajectory as chemical recycling scales.
Application:
End-use performance standards dictate migration testing depth, child-resistance certification, and dispensing precision requirements.
- Beverages:Carbonated and still water formats drive highest unit volumes with lightweighting pressure and tamper-evident band specifications. FDA 21 CFR 177 compliance burdens slow recycled-content adoption despite California SB 54 procurement mandates.
- Pharmaceuticals:Metered-dose and child-resistant mechanisms require NHTSA testing protocols and iterative design cycles that extend development timelines. AptarGroup differentiates through precision dispensing technologies serving this specification-intensive segment.
- Personal Care:Flip-top and pump-integrated formats prioritize aesthetic differentiation and ergonomic dispensing for cosmetics and toiletries.
- Household:Bleach and cleaner closures emphasize chemical compatibility and venting features for reactive formulations.
Beverages lead on unit volume; pharmaceuticals lead on margin capture.
End User:
Customer consolidation patterns determine contract structure, with large buyers unbundling closure supply from bottle procurement.
- Food & Beverage:National bottlers and private-label retailers command lowest unit costs through concentrated Midwest purchasing power and direct converter relationships. Great Lakes manufacturing corridor clustering enables rapid prototyping and specification changes.
- Medicine:FDA-regulated drug manufacturers impose stringent migration testing and lot-traceability requirements that favor qualified suppliers with validated quality systems.
- Cosmetics:Premium brand owners prioritize dispensing precision and shelf differentiation over per-unit cost minimization.
- Cleaning Products:Private-label and contract manufacturers balance chemical compatibility with high-volume cost efficiency.
Food & beverage leads on procurement scale; medicine leads on supplier stickiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing closure production across U.S. sub-regions as converters seek cost-of-compliance advantages under fragmented state mandates. The Great Lakes corridor and Gulf Coast petrochemical hubs anchor current capacity, while California and New York procurement rules are forcing qualification investments that favor larger integrated players.
Great Lakes Manufacturing Corridor
Illinois, Michigan, and Ohio concentrate injection-molding capacity serving Midwest CPG headquarters and rapid prototyping demand. FDA 21 CFR 177 compliance burdens favor established converters with validated quality systems in this cluster. Chicago and Detroit metropolitan areas host blow-molding integration that enables specification changes for regional beverage brand owners.
Gulf Coast Petrochemical Hub
Texas and Louisiana anchor polyethylene and polypropylene resin supply with proximity to ethane feedstock from shale gas production. OSHA lockout/tagout standards and hurricane disruption exposure create operational complexity for converters dependent on this cluster. Houston and Lake Charles chemical recycling facilities under construction will expand food-grade rPP feedstock availability.
California
SB 54 extended producer responsibility frameworks obligate closure manufacturers to fund collection infrastructure, accelerating rPP and rPE validation timelines. The state's recycled-content mandates are forcing national converters to maintain dual-track processing capabilities for California-bound SKUs. Los Angeles and Bay Area bottlers specify certified recycled content minimums in procurement contracts.
New York Metro
State-level recycled-content thresholds diverge from California timelines, complicating national SKU rationalization for converters serving Northeast markets. FDA migration testing requirements for recycled polyolefin streams slow qualification for direct-contact applications. New Jersey and Pennsylvania satellite facilities support just-in-time delivery to CPG headquarters in Manhattan and Connecticut.
Southeast
Florida and Georgia are attracting blow-molding capacity expansion as beverage bottlers seek logistics advantages for southeastern distribution. Lower state-level regulatory burdens compared to California and New York offer compliance cost arbitrage for commodity closure production. Atlanta and Tampa metropolitan areas concentrate personal care and household product manufacturing that drives snap-on closure demand.
United States Plastic Caps and Closure Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue chemical recycling integration and precision dispensing specialization. The market structures around three tiers: integrated resin-to-closure converters with captive supply chains, mid-cap specialists serving pharmaceutical and personal care niches, and regional commodity producers competing on logistics proximity. Dominant competitive moves include backward integration into blow-molding capacity and strategic partnerships with chemical recycling ventures to secure food-grade recycled resin streams.
Within the integrated converter tier, Silgan Holdings Inc. and Berry Global Inc. exemplify scale-driven positioning through captive manufacturing infrastructure. AptarGroup, Inc. represents the precision-specialist archetype, occupying a position defined by dispensing technology differentiation. Amcor plc anchors the sustainability-integrated segment, sitting within the group of converters investing in closed-loop recycling streams. These three patterns—scale integration, functional specialization, and circular infrastructure—capture the competitive vectors reshaping supplier relationships across the United States.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| AptarGroup, Inc. |
| Amcor plc |
| Closure Systems International Inc. |
| Berry Global Inc. |
| Crown Holdings Inc. |
| Albéa S.A. |
| TriMas Corporation |
| BERICAP GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Captive blow-molding integration by Silgan Holdings and Berry Global anchors both supply security and pricing power for polyethylene-based closures, insulating converters from Gulf Coast resin volatility while compressing channel margins for non-integrated competitors. This structural choice concentrates cost advantage among vertically positioned players serving Midwest beverage bottlers.
Pricing Analysis
Retailer markup compression in private-label beverage procurement dominates price formation, with contract-based long-term offtake structures prevailing for national bottlers. Price differentiation rests on FDA 21 CFR 177 certification tier and volume scale, with pharmaceutical-grade closures commanding premium positioning over commodity beverage formats. Cost compression in standard-grade screw caps is intensifying because California SB 54 compliance investments are stretching mid-cap converter balance sheets. Food and beverage brand owners exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize supplier stickiness over per-unit cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast ethane feedstock concentration, where hurricane exposure and ethane-to-propylene cracking economics swing polypropylene resin availability unpredictably. Geographic supply concentration centers on Texas, Louisiana, and Ohio, with Illinois and Michigan providing injection-molding capacity buffers. Raw material dependencies draw from shale gas derivatives, recycled polyolefin streams, and chemical recycling pyrolysis oil. Tariff exposure on imported resin grades compounds procurement risk. Distribution runs through direct-to-OEM relationships unbundled from bottle supply contracts, consolidating purchase volumes with fewer specialized closure manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States plastic caps and closure market functions as a stable compounder, with extended producer responsibility mandates under California SB 54 and analogous state frameworks driving steady reinvestment in dual-track virgin and recycled processing capabilities.
For Market Incumbents: Deepen captive blow-molding capacity in the Great Lakes corridor to defend against aluminum can substitution in premium sparkling water segments. Prioritize FDA 21 CFR 177 compliance certification for rPP and rPE streams ahead of federal harmonization, locking in preferred-supplier status with California and New York procurement officers.
For New Entrants and Emerging Players: Capture Southeast logistics advantages by locating snap-on closure production near Atlanta and Tampa personal care manufacturing clusters, where lower state-level regulatory burdens offer compliance cost arbitrage. Target precision dispensing integration for pharmaceutical applications, where AptarGroup's technology differentiation leaves white space for specialized metered-dose mechanisms.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap mechanical converters because fragmented state recycled-content thresholds prevent national SKU rationalization, favoring scaled players with dual-track processing capabilities. Monitor chemical recycling facility commissioning in Texas and Louisiana as the inflection signal for food-grade rPP feedstock cost normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blow-Molding Capacity | Captive resin conversion insulates margin from Gulf Coast propylene volatility. |
| Dual-Track Virgin and Recycled Processing Investment | California SB 54 compliance enables continued access to state-mandated procurement contracts. |
| Chemical Recycling Feedstock Partnership | Pyrolysis oil offtake agreements secure FDA-compliant rPP supply for direct-contact applications. |
| Precision Dispensing Technology Development | Metered-dose mechanisms capture pharmaceutical segment premium pricing. |
| Southeast Manufacturing Footprint Expansion | Georgia and Florida proximity reduces logistics cost for personal care brand owners. |
Research Approach
Multiple input streams — converter plant manager interviews, beverage procurement lead discussions, and chemical recycling facility development tracking — were reconciled against secondary validation. Primary fieldwork engaged closure manufacturing executives, FDA regulatory affairs specialists, and Midwest CPG supply chain directors. Secondary sources included EPA post-consumer recycled content guidelines, FDA 21 CFR 177 indirect food-additive regulations, state extended producer responsibility filings, and SEC 10-K disclosures from integrated packaging converters. Bottom-up unit economics and top-down market sizing were triangulated to bound value estimates.
Historical volume trajectories were cross-referenced against panel input from resin procurement specialists and blow-molding equipment suppliers. Segmentation dimensions modeled across the analysis window encompass product type, material grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporated California SB 54 implementation timelines and IRA Section 45X credit qualification criteria.
Propylene feedstock price shocks, FDA migration testing delays for recycled polyolefin streams, and aluminum packaging substitution acceleration are the dominant revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Cap Seals Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
PCR Closures Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Box Latch Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Europe Plastic Caps and Closures Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
IBC Caps Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Egypt Plastic Caps and Closures Market