
 Malaysia Container Glass Market | 2026-2036
Malaysia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Container Glass Market Insights
Malaysia's halal certification framework is shifting the cost-of-entry calculus for container glass converters serving food and beverage brands. O-I BJC Glass Malaysia Sdn Bhd leverages its integrated furnace operations to sustain volume leadership across Peninsular Malaysia. Malaya Glass Products Sdn Bhd anchors its position through specialized amber and flint glass production for pharmaceutical clients. SCHOTT Glass Malaysia competes on borosilicate technical competence for laboratory and cosmetic applications.
Container glass in Malaysia comprises soda-lime silica formulations manufactured through IS machine blowing or press-and-blow processes, with thermal shock resistance typically rated at 42°C differential and wall thickness calibrated to 3-4mm for carbonated beverage service. The bottles segment dominates volume throughput, while the pharmaceuticals end-user category captures the highest per-unit margin pools due to stringent USP Type I compliance requirements. Jars and vials represent the fastest-expanding product types as cosmetic brands and generic drug manufacturers expand local sourcing.
Malaysia's Department of Standards Malaysia (DSM) enforces MS 1137 for food-contact glass safety, while the Department of Islamic Development Malaysia (JAKIM) governs halal material traceability from raw batch to finished container. The Ministry of Health's National Pharmaceutical Regulatory Agency (NPRA) mandates ASEAN Common Technical Dossier alignment for pharmaceutical glass primary packaging. Stakeholders must monitor how JAKIM's evolving halal supply chain rules interact with DSM's circular economy material-content thresholds to determine capital allocation for furnace rebuilds versus lightweighting investments.
Market Dynamics
Malaysia's container glass sector faces intensifying pressure from JAKIM's evolving halal traceability mandates, which now require furnace-level batch documentation that smaller converters cannot retrofit without furnace rebuild capital.
Growth Catalysts
- Halal certification expansion:JAKIM's 2024 supply chain transparency rules compel multinational beverage brands to source Malaysian glass for ASEAN halal product lines, locking in volume commitments.
- Pharmaceutical localization:NPRA's ASEAN Common Technical Dossier alignment requirements push generic drug manufacturers toward domestic primary packaging suppliers to accelerate approval timelines.
- Peninsular industrial corridor concentration:The Shah Alam-Johor Bahru belt offers integrated logistics access to Port Klang and Tanjung Pelepas, reducing inland freight costs for export-bound converters.
Market Restraints
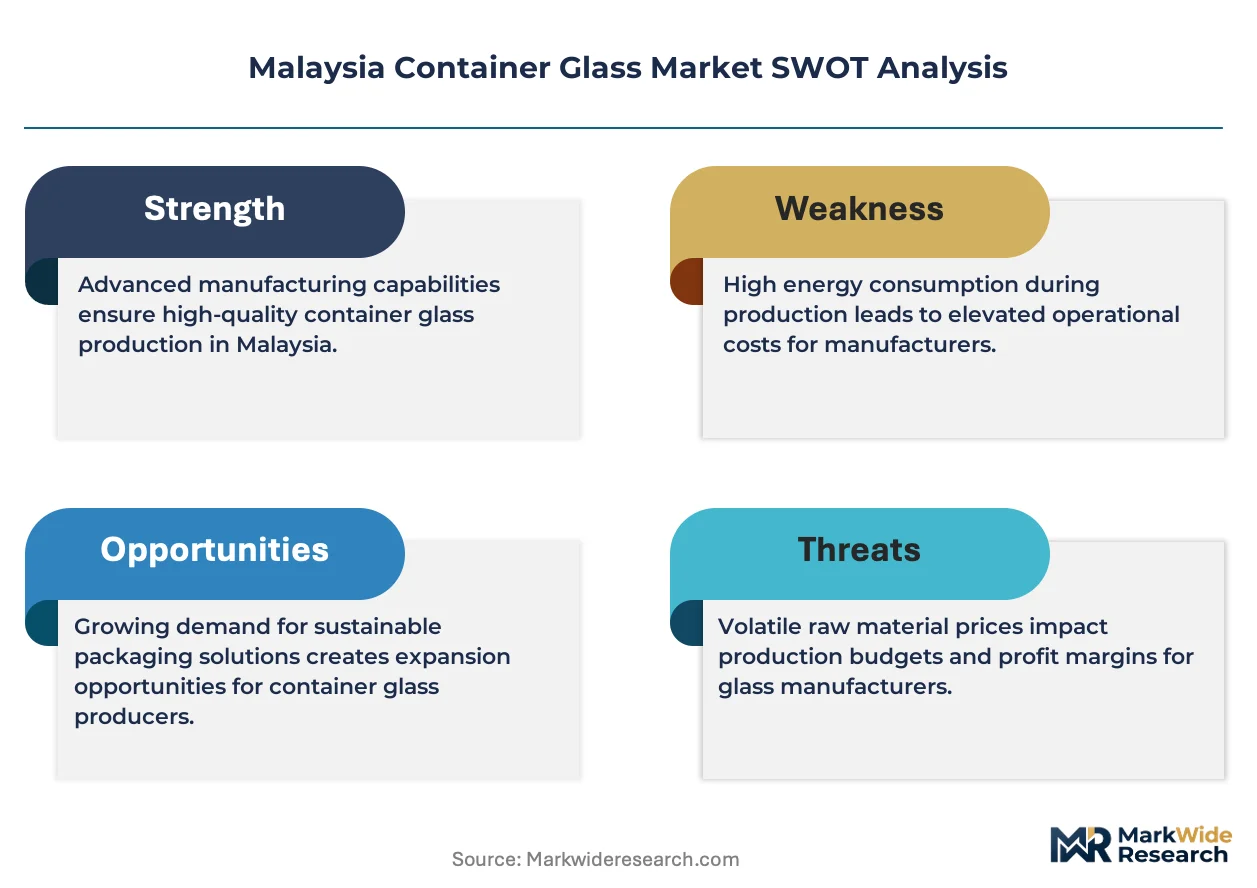
- Natural gas price volatility:Furnace operations depend on Petronas pipeline supply, with industrial tariff fluctuations compressing margin visibility for continuous-melt producers.
- Import dependency for soda ash:Malaysia lacks domestic sodium carbonate production, exposing batch cost structures to Turkish and Chinese supplier pricing.
- Plastic substitution in mass-market beverages:rPET bottle economics undercut glass for volume carbonated soft drinks, constraining glass penetration below premium price tiers.
Strategic Opportunities
- Sarawak secondary manufacturing:East Malaysia's underdeveloped converter base offers first-mover positioning for borosilicate technical glass serving Bintulu's petrochemical laboratories.
- Cosmetic ampoule demand surge:K-beauty brand contract manufacturing in Selangor creates pull for USP Type I compliant vials with silk-screen decoration capability.
- Circular economy material thresholds:DSM's proposed recycled content benchmarks reward early furnace investments with post-consumer cullet handling systems.
Industry Challenges
- Refractory engineering talent scarcity:Furnace rebuild cycles require specialized ceramic welding expertise concentrated among retired European technicians, extending downtime windows.
- Halal audit timeline compression:JAKIM's expanded documentation requirements stretch certification cycles from 90 to 180 days, delaying new product launches for seasonal beverage programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Container Glass Market |
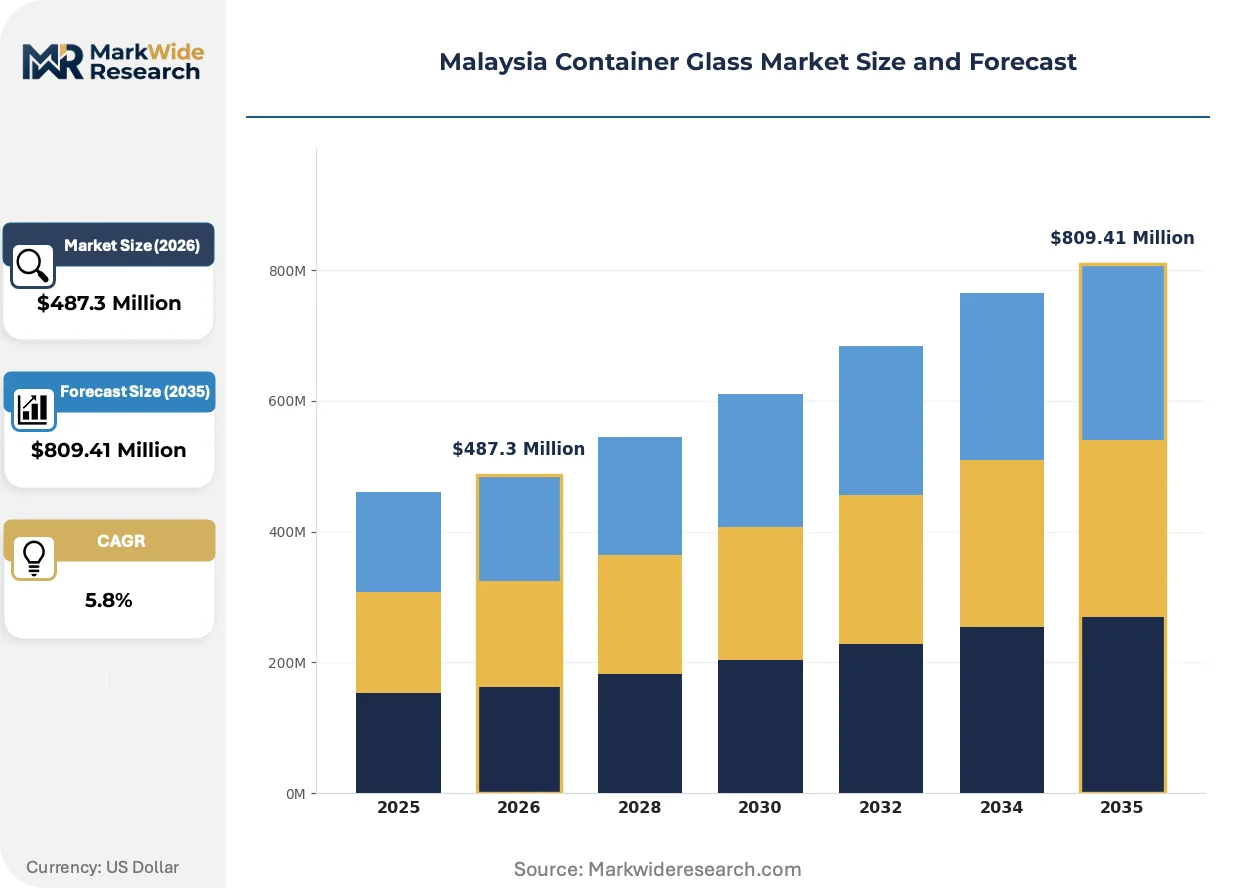
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Beverage, Food, Pharmaceuticals, Cosmetics Capacity: 50ml, 100ml, 250ml, 1L Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Joyi Link Sdn Bhd, Malaya Glass Products Sdn Bhd, O-I BJC Glass Malaysia Sdn Bhd, SCHOTT Glass Malaysia, Nippon Electric Glass, JG Containers (Malaysia) Sdn Bhd, DSM Packaging Sdn Bhd, Berli Jucker, Glass & Plastic Packaging Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Container Glass Market Trends and Innovations
Electrification of melting technology and digital batch traceability systems are compressing the traditional furnace economics that have defined Malaysian container glass manufacturing for decades.
Hybrid oxy-fuel furnace architecture is unifying combustion efficiency with carbon intensity reduction targets. Peninsular Malaysia's largest beverage-glass converters are retrofitting end-fired units with oxygen-enriched burners to meet DSM's emerging emissions benchmarks. This technology is unifying environmental compliance with halal certification requirements by enabling precise batch-temperature logging that satisfies JAKIM's material traceability audits.
JAKIM's 2024 Halal Supply Chain Integrity Guidelines impose furnace-to-shelf documentation mandates on all food-contact packaging. The regulation forces converters to deploy serialized batch coding systems linked to raw material certificates. Pharmaceutical glass producers face the steepest compliance costs, as NPRA simultaneously demands USP Type I validation data that conflicts with halal audit timelines.
Direct converter relationships are displacing traditional distributor intermediaries in beverage procurement. Heineken Malaysia and Carlsberg Malaysia now negotiate annual volume contracts directly with Shah Alam furnace operators, bypassing the Penang-based trading houses that historically managed glass logistics. This channel compression is most visible in the carbonated beer segment, where just-in-time delivery requirements favor geographic proximity over distributor inventory buffers.
Malaysia Container Glass Market Segmentation
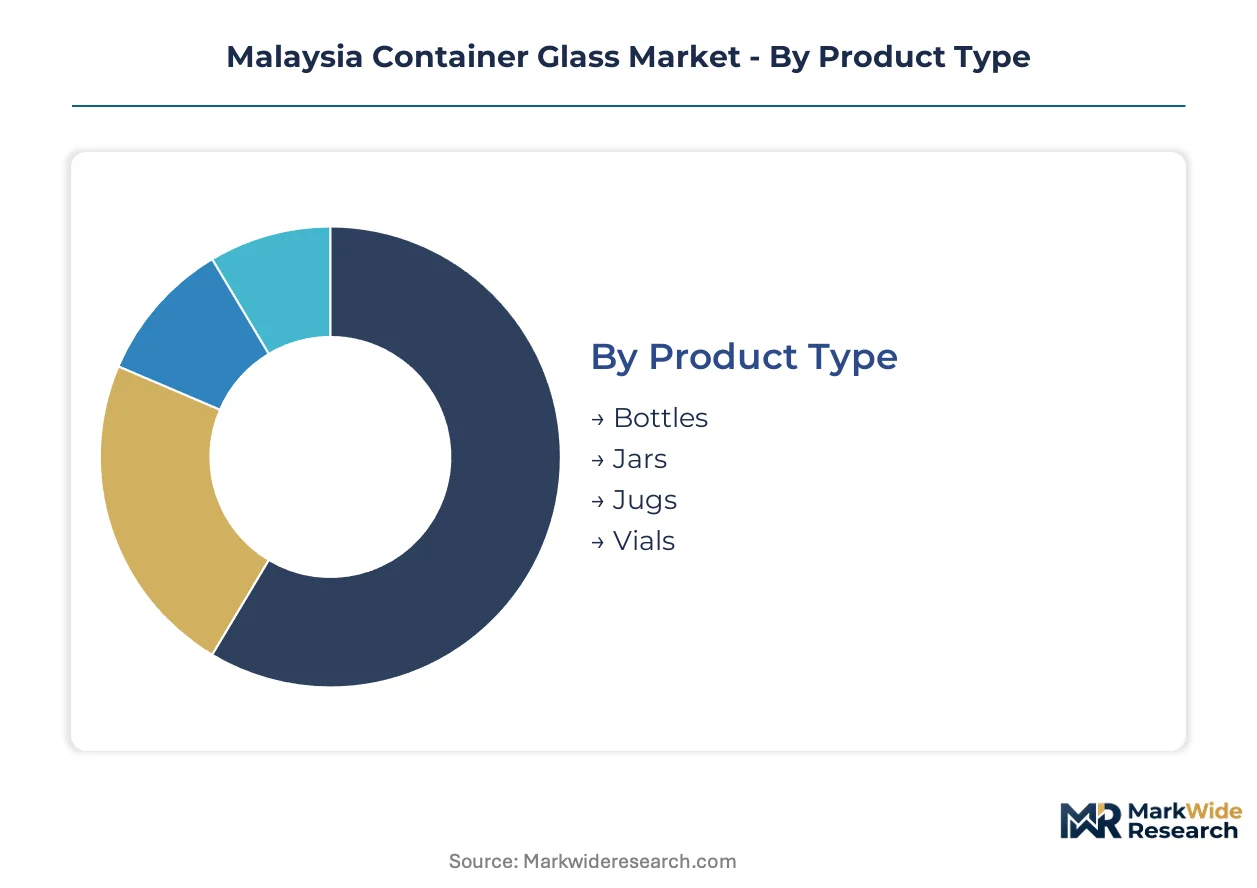
Malaysia's container glass segmentation reflects divergent compliance burdens across product categories. JAKIM halal traceability, NPRA pharmaceutical validation, and DSM food-contact standards each impose distinct documentation requirements that reshape converter investment priorities.
Product Type:
Certification intensity varies sharply by product form, with pharmaceutical vials demanding dual NPRA-JAKIM alignment while beverage bottles face lighter halal documentation loads.
- Bottles:Soda-lime silica construction with 3-4mm wall thickness calibrated for carbonated beverage pressure resistance. Demand concentrates in Peninsular Malaysia's Shah Alam-Johor Bahru corridor, where Heineken Malaysia and Carlsberg Malaysia negotiate direct annual volume contracts with furnace operators.
- Jars:Wide-mouth press-and-blow formations with thermal shock ratings at 42°C differential. Food packagers in Selangor drive procurement for halal-certified sauces and condiments, though JAKIM's 180-day audit timelines compress seasonal product launch windows.
- Jugs:Reinforced shoulder designs for liquid detergent and edible oil bulk packaging. Domestic converters supply Malaysian household brands with BIS-equivalent structural integrity standards.
- Vials:Borosilicate or soda-lime formulations requiring USP Type I compliance for pharmaceutical primary packaging. NPRA's ASEAN Common Technical Dossier alignment creates approval bottlenecks that favor established producers with validated batch documentation systems.
Bottles sit at the top of the volume ranking, with vials climbing the fastest.
End User:
Margin structures diverge across end-use categories, with pharmaceutical applications capturing premium pricing for compliance-intensive specifications while beverage volume scales dilute per-unit returns.
- Beverage:Carbonated soft drinks, beer, and premium spirits packaging. Malaysian bottlers shift from plastic to glass for premium positioning, though rPET economics constrain glass penetration below price-tier thresholds.
- Food:Halal-certified sauces, preserves, and condiments in jar and bottle formats. JAKIM's 2024 supply chain transparency rules compel multinational brands to source Malaysian glass for ASEAN halal product lines.
- Pharmaceuticals:USP Type I compliant primary packaging for generic drug manufacturers. NPRA mandates accelerate domestic sourcing to compress approval timelines, locking volume commitments with local converters.
- Cosmetics:K-beauty contract manufacturing in Selangor pulls silk-screen decorated ampoules and vials. Demand expands for borosilicate technical competence in laboratory and premium skincare applications.
Beverage commands the volume base, with cosmetics expanding most quickly.
Capacity:
Production economics favor mid-range formats where furnace throughput efficiency balances tooling changeover frequency against per-unit material yields.
- 50ml:Pharmaceutical vials and cosmetic ampoules requiring precision press-and-blow forming. NPRA validation requirements dominate specification setting for this high-margin, low-volume segment.
- 100ml:Single-serve beverage and pharmaceutical liquid formats. Malaysian generic drug manufacturers standardize on this capacity for export-bound ASEAN markets.
- 250ml:Standard beverage and condiment jar sizing. Furnace operators optimize batch runs around this capacity point to minimize IS machine changeover downtime.
- 1L:Edible oil and liquid detergent bulk packaging. Jug formations in this capacity face competition from HDPE alternatives in mass-market price tiers.
250ml holds the throughput crown, with 50ml gaining share fastest.
Distribution Channel:
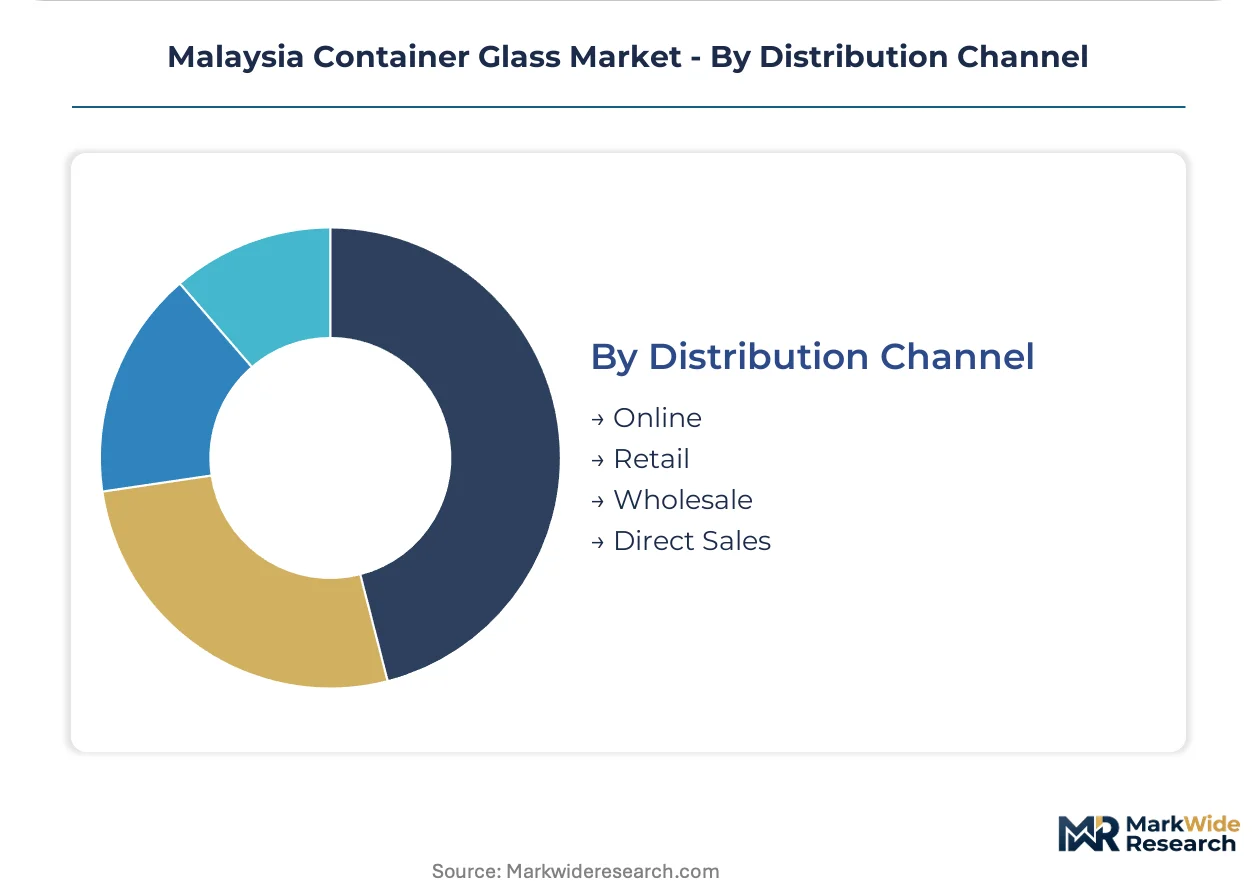
Channel structure reflects customer scale and delivery reliability requirements, with direct relationships displacing intermediaries where just-in-time logistics prove critical.
- Online:E-procurement platforms serving small-batch cosmetic and specialty food brands. Digital batch traceability systems enable JAKIM compliance documentation for fragmented buyer bases.
- Retail:Hardware and packaging supply stores for replacement and artisan glassware. Limited penetration in industrial container procurement due to volume and specification complexity.
- Wholesale:Penang-based trading houses historically managing glass logistics for dispersed beverage accounts. Channel compression erodes this intermediary role as direct converter contracts expand.
- Direct Sales:Annual volume contracts between Shah Alam furnace operators and Heineken Malaysia, Carlsberg Malaysia, and multinational beverage anchors. Geographic proximity to the Peninsular industrial corridor determines supplier selection.
Direct sales leads by volume contribution, with online channels showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized refractory engineering talent concentrates along Peninsular Malaysia's industrial corridor, anchoring furnace rebuild capabilities that smaller East Malaysian converters cannot replicate without external technical support.
Shah Alam Industrial Zone
Beverage bottlers Heineken Malaysia and Carlsberg Malaysia drive container glass procurement through direct annual volume contracts. JAKIM's 2024 halal supply chain transparency rules compel these anchors to source locally for ASEAN product lines. Furnace operators in this Selangor cluster leverage Port Klang proximity to reduce inland freight costs for export-bound shipments.
Johor Bahru Manufacturing Belt
Generic drug manufacturers expanding local primary packaging sourcing create pull for USP Type I compliant vials. NPRA's ASEAN Common Technical Dossier alignment requirements accelerate domestic supplier qualification timelines. Tanjung Pelepas port access enables just-in-time delivery to Singapore pharmaceutical distributors.
Penang Trading Hub
Historical glass logistics intermediaries face channel compression as direct converter contracts displace wholesale relationships. Digital batch traceability systems now enable JAKIM compliance documentation without traditional distributor documentation buffers. The state's electronics manufacturing base generates incidental demand for borosilicate laboratory glassware.
Sarawak Secondary Manufacturing
Bintulu's petrochemical laboratories create latent demand for technical borosilicate glass that Peninsular converters struggle to serve economically. The underdeveloped local converter base offers first-mover positioning for specialized producers. DSM's proposed recycled content benchmarks would require costly cullet handling infrastructure investments for any new market entrant.
Selangor Cosmetic Contract Manufacturing
K-beauty brand production in this state pulls silk-screen decorated ampoules and premium skincare vials. Halal certification requirements extend to cosmetic packaging as JAKIM expands material traceability mandates beyond food-contact applications. Local converters with USP Type I validation data capture margin premiums from dual pharmaceutical-cosmetic compliance.
Malaysia Container Glass Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Malaysia's container glass sector, creating a tiered structure where integrated furnace operators hold volume advantages and specialized converters capture compliance-intensive niches. The market consolidates around three strategic archetypes: multinational joint ventures with captive beverage relationships, domestic specialists in amber and flint pharmaceutical glass, and technical borosilicate producers serving laboratory and cosmetic applications. Competitive dynamics center on furnace rebuild timing to meet JAKIM's evolving halal documentation requirements and strategic partnerships with generic drug manufacturers seeking NPRA-aligned domestic sourcing.
Among Malaysia-based specialists, Malaya Glass Products Sdn Bhd exemplifies the pharmaceutical-focused archetype through its specialized amber and flint production capabilities, while O-I BJC Glass Malaysia Sdn Bhd occupies a position as the volume leader leveraging integrated furnace operations across Peninsular Malaysia. SCHOTT Glass Malaysia represents the technical competence tier, anchoring borosilicate applications for laboratory and cosmetic end-uses where compliance requirements diverge from standard soda-lime specifications.
| Leading Market Players |
|---|
| Joyi Link Sdn Bhd |
| Malaya Glass Products Sdn Bhd |
| O-I BJC Glass Malaysia Sdn Bhd |
| SCHOTT Glass Malaysia |
| Nippon Electric Glass |
| JG Containers (Malaysia) Sdn Bhd |
| DSM Packaging Sdn Bhd |
| Berli Jucker |
| Glass & Plastic Packaging Sdn Bhd |
| Others |
Pricing and Supply Chain Analysis
Captive furnace operations along Peninsular Malaysia's Shah Alam-Johor Bahru corridor anchor both supply security and pricing leverage for volume converters serving Heineken Malaysia and Carlsberg Malaysia. This integration choice insulates batch cost structures from Turkish and Chinese soda ash volatility while enabling direct annual contract negotiations that bypass Penang-based trading house margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Malaysian container glass procurement, with USP Type I pharmaceutical vials commanding the top tier and mass-market beverage bottles facing the steepest compression. Price differentiation hinges on JAKIM halal certification grade and NPRA validation status, with seasonal beverage programs absorbing the highest buyer price sensitivity due to compressed product launch windows. Pricing pressure stems from Petronas natural gas tariff fluctuations that erode continuous-melt furnace margins.
Supply Chain Analysis
Dual-sourcing requirements from multinational beverage anchors mandate furnace-level batch documentation that smaller converters cannot satisfy without capital-intensive rebuilds. Geographic supply concentration draws from Turkey and China for soda ash, with Malaysian converters lacking domestic sodium carbonate production. Raw material dependencies center on soda ash, limestone, and cullet feedstock. Single-source vulnerability runs through Petronas pipeline supply for furnace fuel. Distribution runs through direct annual volume contracts between Shah Alam furnace operators and anchor beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian container glass presents a late-cycle quality story as JAKIM's 2024 halal supply chain transparency rules shift procurement toward validated domestic converters with furnace-level documentation systems.
For Market Incumbents: Acquire refractory engineering expertise to compress furnace rebuild downtime windows. O-I BJC Glass Malaysia and Malaya Glass Products should backward integrate into post-consumer cullet handling systems ahead of DSM's proposed recycled content benchmarks. NPRA's ASEAN Common Technical Dossier alignment requirements create defensive moats for established pharmaceutical glass producers with validated batch documentation. For New Entrants and Emerging Players: Sarawak-based petrochemical laboratories represent an underserved buyer archetype demanding technical borosilicate glass that Peninsular converters serve uneconomically. Bintulu's laboratory cluster offers first-mover positioning for specialized producers willing to absorb cullet handling infrastructure investments. Go-to-market execution should emphasize JAKIM compliance documentation capabilities that East Malaysian buyers currently source from distant Peninsular suppliers. For Investors and Strategic Acquirers: Roll-up economics work for pharmaceutical-focused specialists because NPRA validation timelines and JAKIM audit cycles create switching costs that lock generic drug manufacturers into established supplier relationships. Long-term viability favors converters with dual USP Type I and halal certification capabilities. The signal to watch is JAKIM's expansion of material traceability mandates into cosmetic packaging applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cullet Handling | DSM's recycled content benchmarks reward early furnace investments with post-consumer material processing systems. |
| Halal Certification Infrastructure | JAKIM's 180-day audit timelines favor converters with serialized batch coding and furnace-to-shelf documentation. |
| Pharmaceutical Validation Investment | NPRA's ASEAN Common Technical Dossier alignment locks volume commitments with domestic USP Type I compliant suppliers. |
| Sarawak Market Entry | Bintulu's petrochemical laboratories create latent demand for technical borosilicate glass from first-mover positioning. |
| Direct Converter Relationships | Heineken Malaysia and Carlsberg Malaysia now bypass Penang trading houses for just-in-time Shah Alam furnace contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with furnace operations managers, pharmaceutical packaging procurement leads, JAKIM certification auditors, and beverage supply chain directors with secondary validation from Department of Standards Malaysia circulars, NPRA regulatory filings, Petronas industrial tariff disclosures, and customs import records for soda ash. Bottom-up furnace capacity modeling and top-down end-use demand segmentation provided triangulation anchors.
Comparable-period anchoring tied projection assumptions to historical batch cost structures, furnace utilization patterns, and certification timeline compression across the analysis window. Segmentation dimensions modeled include product type, end-use category, capacity tier, and distribution channel, with JAKIM halal compliance grade and NPRA validation status as industry-specific overlay variables. CAGRs derived from furnace throughput efficiency curves and end-use demand elasticity estimates, incorporating Petronas natural gas pricing scenarios and Turkish soda ash supply volatility as key forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical vials and direct sales channels carry tighter precision than artisan retail and online procurement due to documentation system maturity. Forecasts reflect assumptions about JAKIM audit timeline stability and DSM recycled content threshold implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
India Container Glass Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Mason Jars Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
North America Amber Glass Packaging Market
Glass Packaging
Glass Veil Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Glass Liquor Bottles Market