
 Global Policy Management in Telecom Market | 2026-2036
Global Policy Management in Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Global Policy Management in Telecom Market Outlook
The gap between premium policy control platforms and commodity subscriber management tools is hardening as 5G standalone deployments demand real-time session management with sub-ten-millisecond latency. Amdocs Limited leverages its BSS integration heritage to anchor complex charging-policy convergence for tier-one operators. Huawei Technologies Co., Ltd. sustains R&D intensity in AI-driven traffic classification engines that differentiate its portfolio in markets with strict data sovereignty rules.
Policy management in telecom encompasses the software systems that enforce business rules on network resources, subscriber profiles, and service quality parameters through interfaces such as the 3GPP-standardized Policy and Charging Rules Function. These systems govern bandwidth allocation, roaming permissions, and zero-touch provisioning across multi-vendor radio access networks. Cloud-based deployment models are capturing the fastest expansion as operators migrate policy functions to containerized edge architectures, while on-premises installations retain dominance in government and defense verticals where air-gapped infrastructure remains mandatory. Analytics Solutions within the product type dimension are emerging as the highest-margin segment, since real-time streaming telemetry enables predictive congestion management and dynamic tariff optimization.
The Federal Communications Commission in the United States mandates lawful intercept capabilities and net neutrality transparency disclosures that shape vendor product roadmaps, while the European Telecommunications Standards Institute drives interoperability benchmarks for cross-border roaming policy exchange. The EU AI Act imposes algorithmic accountability requirements on automated policy decisions affecting subscriber access, compelling vendors to embed explainability modules into machine-learning-based traffic prioritization engines. Stakeholders must monitor how spectrum auctions in India and Brazil reshape operator capital cycles and therefore policy software procurement timelines.
Market Dynamics
5G standalone core deployments are forcing mobile network operators to replace legacy policy decision engines with sub-ten-millisecond latency architectures that can enforce dynamic quality-of-service rules across network slices in real time.
Growth Catalysts
- EU AI Act Algorithmic Accountability:Automated policy decisions affecting subscriber access must embed explainability modules, accelerating replacement of opaque traffic prioritization systems with auditable machine-learning platforms.
- Network Slicing Orchestration:Enterprise verticals manufacturing connected vehicles and industrial automation require guaranteed bandwidth isolation that policy management platforms enforce through 3GPP-standardized interfaces.
- German Operator Investment Concentration:Deutsche Telekom and Vodafone have deployed advanced policy and charging rules function architectures, establishing procurement benchmarks that neighboring European operators now replicate.
Market Restraints
- Semiconductor Supply Concentration:Specialized ASICs for packet inspection and traffic classification face sourcing constraints from Taiwan and South Korea foundries, extending deployment timelines for high-throughput policy enforcement nodes.
- GDPR Data Localization Mandates:Subscriber profile storage and processing must remain within EU jurisdictional boundaries, fragmenting cloud-native policy architectures that assumed centralized data lakes.
- Legacy Diameter Protocol Entrenchment:Existing charging interfaces in 4G networks resist migration to HTTP/2 service-based architectures, forcing parallel infrastructure maintenance during transition periods.
Strategic Opportunities
- Brazilian Spectrum Auction Cycle:ANATEL's 3.5 GHz and 26 GHz allocations will trigger capital expenditure waves among Claro, TIM, and Vivo that include policy control modernization in deployment roadmaps.
- Edge Container Convergence:Kubernetes-orchestrated policy functions deployed at multi-access edge computing nodes enable ultra-low-latency enforcement for augmented reality and cloud gaming applications.
- Indian Defence Vertical:Air-gapped policy management installations for military communications networks present high-margin opportunities isolated from price pressure in commercial telecom segments.
Industry Challenges
- Telecom BSS Integration Complexity:Policy management platforms must interoperate with charging systems, customer relationship management, and revenue assurance tools from disparate vendors accumulated through decades of operator mergers.
- Real-Time Analytics Talent Scarcity:Streaming telemetry processing for predictive congestion management requires data engineering expertise that competes with fintech and hyperscaler compensation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Policy Management in Telecom Market |
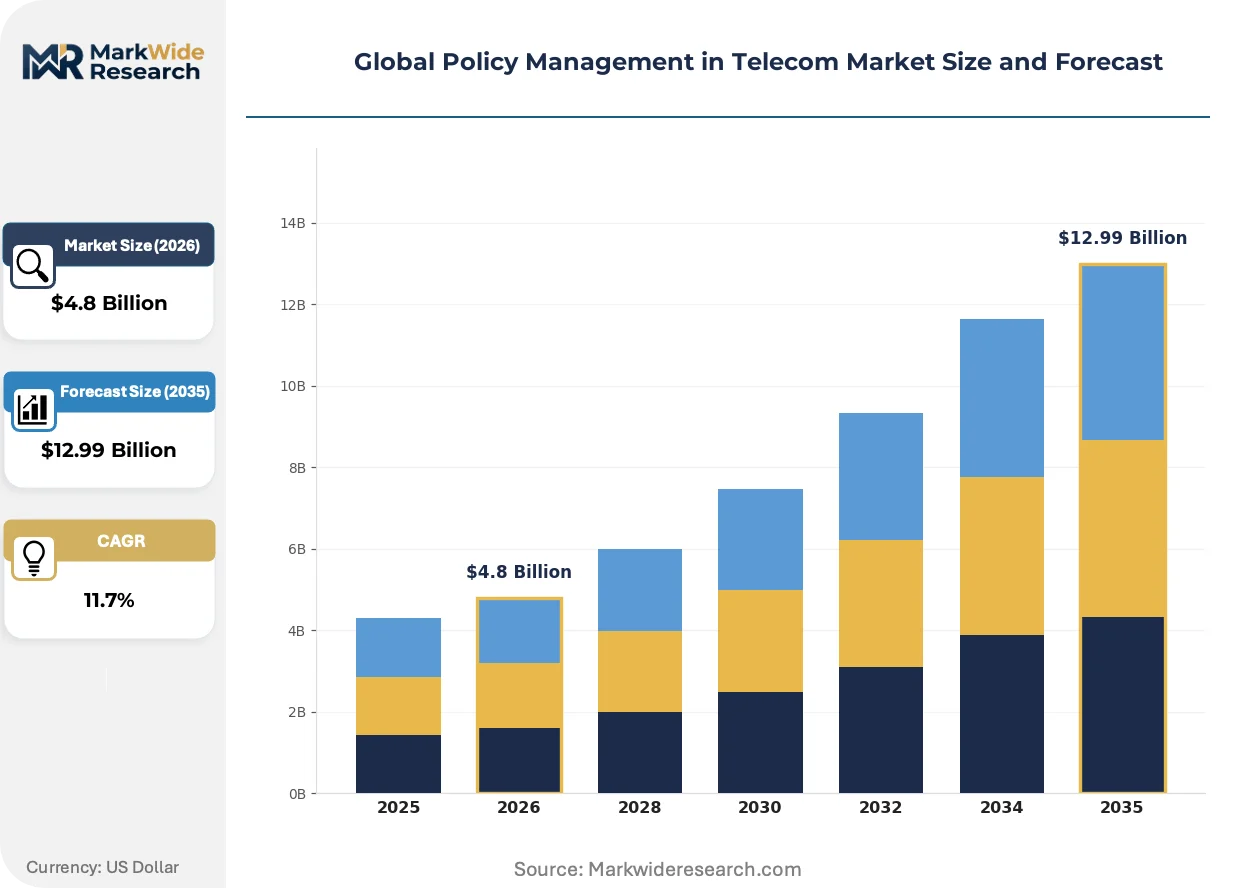
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Policy Control, Subscriber Management, Data Governance, Analytics Solutions Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services End User: Telecom Operators, Enterprises, Government Agencies, Resellers Technology: 5G, AI, IoT, ML |
| Companies Covered | Amdocs Limited, Telefonaktiebolaget LM Ericsson, Huawei Technologies Co., Ltd., Oracle Corporation, Cisco Systems, Inc., Nokia Corporation, ZTE Corporation, Netcracker Technology Corporation, CSG International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Policy Management in Telecom Market Strategic Shifts
Containerized deployment models are displacing virtual machine-based policy functions as operators pursue elastic scaling and reduced operational overhead across distributed radio access networks.
Cloud-native policy control is consolidating standalone network functions into unified platforms that combine session management, charging triggers, and subscriber data repository access. Tier-one operators in Germany and Japan are migrating production traffic to these architectures, compressing vendor margins on discrete point solutions while elevating systems integrators who can orchestrate multi-vendor interoperability. The structural consequence is vendor base reduction as procurement teams favor comprehensive platforms over best-of-breed component assembly.
REACH chemical substance restrictions and the EU AI Act's risk classification framework are reshaping hardware sourcing and algorithmic design requirements for European deployments. Equipment vendors must now document supply chain provenance for server components and maintain technical files demonstrating conformity assessment for machine-learning models embedded in traffic classification engines. Operators in France and the Netherlands are front-loading compliance costs into procurement specifications, filtering supplier pools before technical evaluation begins.
Subscription-based commercial models are displacing perpetual license purchases as operators prioritize operational expenditure alignment with subscriber revenue volatility. Managed service contracts for policy platform operations now include uptime guarantees and feature velocity commitments that internal engineering teams struggle to match. This shift concentrates procurement influence among vendor professional services organizations, particularly visible in Australian and Canadian operator transformations where staff augmentation constraints limit in-house platform engineering scale.
Global Policy Management in Telecom Market Segmentation
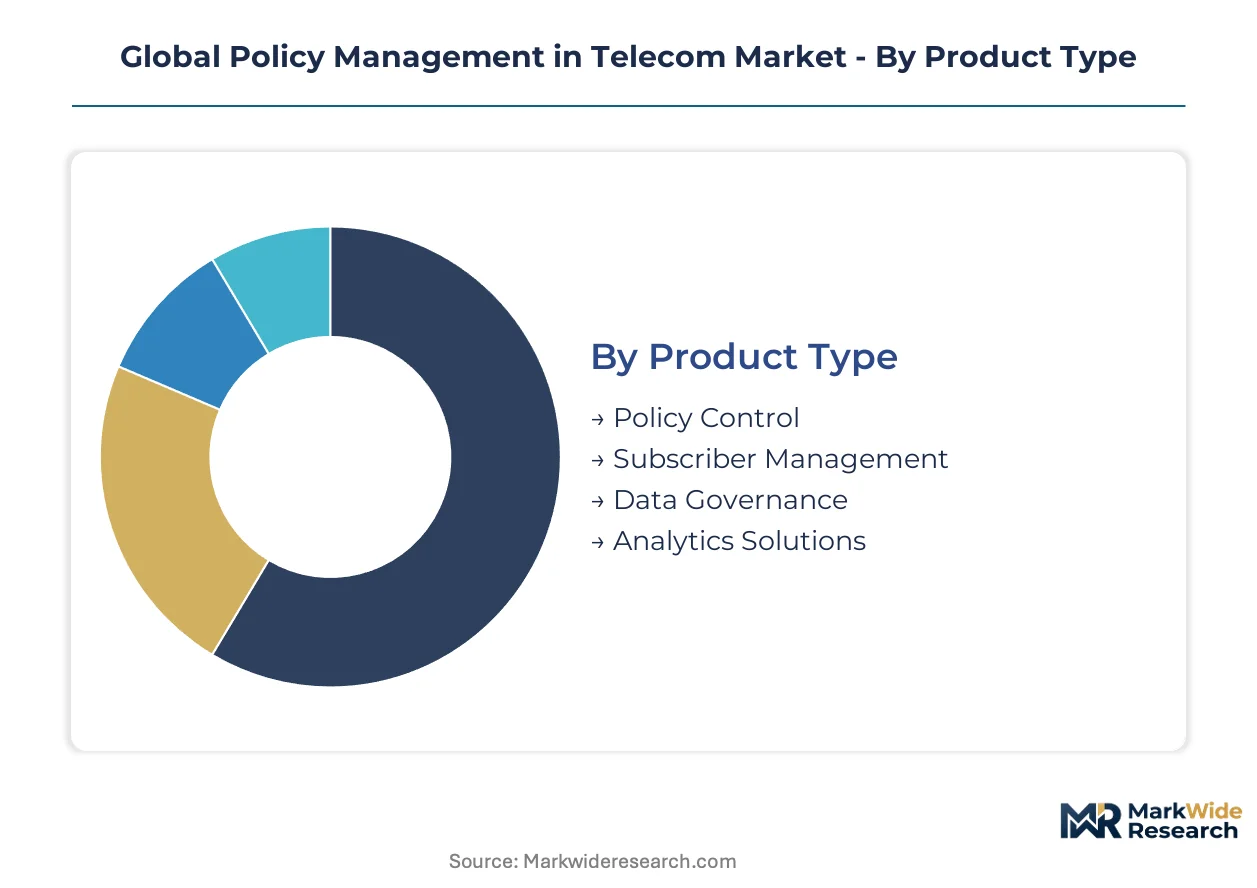
Policy management architectures fragment across four critical dimensions that determine procurement priorities for mobile network operators. Deployment model choices reshape vendor commercial relationships, while technology adoption curves separate early 5G standalone adopters from legacy infrastructure maintainers. Understanding these splits reveals where margin concentrates and where commoditization threatens.
Product Type:
Volume concentrates in foundational control layers, while premium margins flow to intelligence and governance functions that operators cannot build in-house.
- Policy Control:Core enforcement engines implementing 3GPP-standardized Policy and Charging Rules Function protocols across network slices. Deutsche Telekom and Vodafone in Germany anchor procurement demand as they replace legacy diameter-based systems with sub-ten-millisecond service-based architectures for 5G standalone cores.
- Analytics Solutions:Real-time streaming telemetry platforms processing subscriber behavior patterns to enable predictive congestion management and dynamic tariff optimization. Demand clusters among Japanese operators pursuing cloud gaming and augmented reality service guarantees, where machine-learning-driven traffic classification commands pricing premiums.
- Subscriber Management:Unified profile repositories governing authentication, roaming permissions, and zero-touch provisioning workflows.
- Data Governance:Automated compliance platforms enforcing GDPR subscriber data localization and EU AI Act algorithmic accountability requirements.
Today's leader: Analytics Solutions. Tomorrow's challenger: Data Governance.
Deployment Model:
Cost tier separation runs deepest here, with capital-intensive on-premises installations defending high-security verticals against operational-expenditure-aligned cloud migrations.
- Cloud-based:Containerized policy functions orchestrated through Kubernetes at distributed edge nodes, enabling elastic scaling across multi-vendor radio access networks. Australian and Canadian operators drive adoption through managed service contracts featuring uptime guarantees and feature velocity commitments that internal engineering teams cannot match.
- On-premises:Air-gapped infrastructure mandatory for government and defense verticals where data sovereignty requirements preclude third-party cloud access. Indian military communications networks represent high-margin opportunities isolated from commercial telecom price pressure.
- Hybrid:Split architectures preserving sensitive subscriber data on-premises while bursting compute-intensive analytics to public cloud.
- Managed Services:Vendor-operated policy platforms with professional services organizations assuming operational responsibility.
Cloud-based deployments expand most quickly, though on-premises retains irreplaceable security premiums.
End User:
Customer type determines feature complexity, with enterprise verticals demanding guaranteed bandwidth isolation that consumer-facing operators rarely enforce.
- Telecom Operators:Mobile network operators and fixed-line carriers implementing subscriber-wide policy enforcement across millions of concurrent sessions.
- Enterprises:Manufacturing, automotive, and industrial automation verticals requiring network slice orchestration with guaranteed quality-of-service for connected vehicle and robotics applications.
- Government Agencies:National regulators and defense ministries mandating lawful intercept capabilities and air-gapped infrastructure.
- Resellers:Systems integrators and managed service providers assembling multi-vendor policy stacks for mid-market operators lacking in-house engineering scale.
Telecom Operators dominate current procurement volume. Enterprises show the steepest expansion trajectory as private 5G networks proliferate.
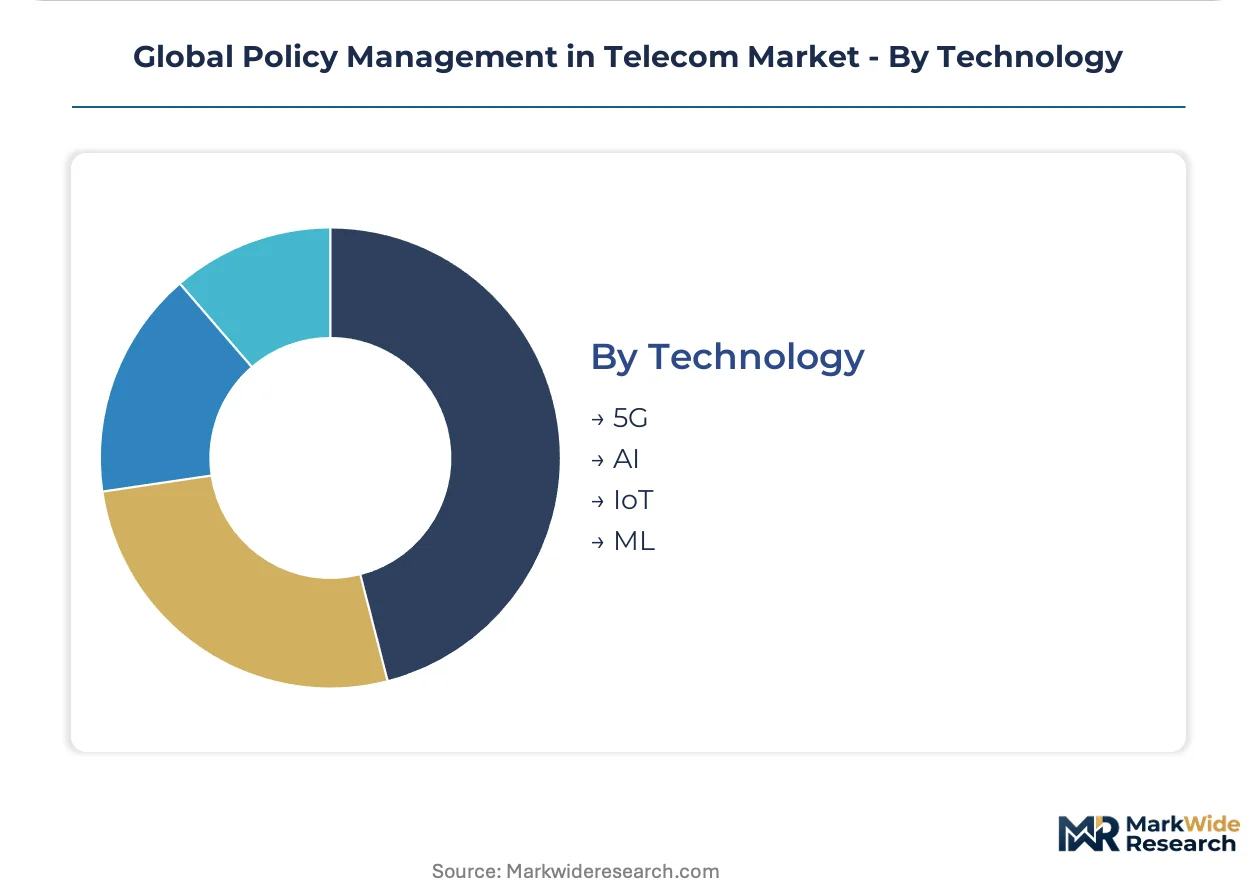
Technology:
Maturity separates established radio standards from emerging intelligence layers, with AI and ML adoption constrained by explainability mandates and talent scarcity.
- 5G:Standalone core deployments requiring sub-ten-millisecond policy decision latency across network slices. Brazilian spectrum auctions for 3.5 GHz and 26 GHz allocations will trigger capital expenditure waves among Claro, TIM, and Vivo including policy control modernization.
- AI:Machine-learning traffic classification engines facing EU AI Act algorithmic accountability requirements. Vendors must embed explainability modules to replace opaque prioritization systems, front-loading compliance costs into French and Dutch procurement specifications.
- IoT:Massive machine-type communication policy enforcement for sensor networks and industrial telemetry.
- ML:Predictive models for congestion management competing with fintech and hyperscaler compensation packages for scarce data engineering talent.
5G infrastructure commands immediate capital allocation. AI faces regulatory friction before achieving projected penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in policy management procurement intensity, with German operators consolidating advanced 5G standalone architectures while US carriers navigate fragmented federal-state regulatory layers. Japan and India represent contrasting acceleration patterns in Asia-Pacific, driven by cloud gaming demand and defense vertical requirements respectively. Brazil's spectrum auction cycle is reshaping Latin American capital allocation timelines.
Germany
Deutsche Telekom and Vodafone anchor European demand through deployed Policy and Charging Rules Function architectures that neighboring operators now replicate. The EU AI Act imposes algorithmic accountability requirements on automated traffic prioritization, compelling explainability module integration. Berlin and Düsseldorf host concentrated vendor engineering centers serving Central European operator modernization programs.
United States
Mobile network operators expand policy control investments to manage 5G network slicing across distributed radio access networks. The Federal Communications Commission mandates lawful intercept capabilities and net neutrality transparency disclosures that shape vendor product roadmaps. Seattle and Dallas-Fort Worth clusters concentrate cloud-native policy development talent competing with hyperscaler compensation packages.
Japan
NTT Docomo and KDDI drive Analytics Solutions demand for cloud gaming and augmented reality service guarantees requiring machine-learning traffic classification. The Ministry of Economy, Trade and Industry promotes interoperability benchmarks for cross-border roaming policy exchange. Tokyo and Osaka metropolitan areas concentrate real-time streaming telemetry engineering expertise.
India
Bharat Sanchar Nigam Limited and Reliance Jio prepare policy control modernization aligned with spectrum auction capital cycles and private 5G network proliferation. The Telecom Regulatory Authority of India governs subscriber data governance frameworks affecting procurement specifications. Bengaluru and Hyderabad clusters concentrate software development capabilities for containerized edge deployments.
Brazil
Claro, TIM, and Vivo anticipate capital expenditure waves following ANATEL's 3.5 GHz and 26 GHz spectrum allocations with policy control modernization embedded in deployment roadmaps. ANATEL regulations shape lawful intercept and data retention requirements for vendor compliance. São Paulo anchors Latin American procurement decision-making and systems integration capacity.
Global Policy Management in Telecom Market Competitive Environment
Top-tier vendors anchor integrated platform provision, while specialized component suppliers defend niche positions in traffic classification and subscriber data governance. The vendor base separates between BSS-heritage systems integrators and cloud-native challengers pursuing containerized edge architectures. Three archetypes dominate: converged charging-policy platform providers, AI-driven traffic classification engine specialists, and managed services operators assuming operational responsibility. Competitive moves concentrate on multi-vendor interoperability certification and professional services scale expansion.
Within the converged platform tier, Amdocs Limited and Oracle Corporation exemplify BSS integration heritage applied to complex charging-policy convergence for tier-one operators. Huawei Technologies Co., Ltd. occupies a distinct position through sustained R&D intensity in AI-driven traffic classification, differentiating its portfolio in markets with strict data sovereignty rules. These three entities represent the structural fault line between integrated platform consolidation and best-of-breed component assembly strategies.
| Leading Market Players |
|---|
| Amdocs Limited |
| Telefonaktiebolaget LM Ericsson |
| Huawei Technologies Co., Ltd. |
| Oracle Corporation |
| Cisco Systems, Inc. |
| Nokia Corporation |
| ZTE Corporation |
| Netcracker Technology Corporation |
| CSG International |
| Others |
Value Chain & Pricing Dynamics
Real-time streaming telemetry engineering talent concentration in Tokyo and Bengaluru creates labor-cost differentials that widen pricing-tier spreads between premium AI-driven traffic classification platforms and commodity subscriber management tools.
Pricing Analysis
Bundled managed service contracts are displacing unbundled perpetual license purchases as operators prioritize operational expenditure alignment with subscriber revenue volatility. Pricing stratifies across premium analytics solutions, standard policy control platforms, and economy-tier subscriber management tools based on integration complexity and machine-learning capability depth. Cost compression in the standard tier is intensifying because cloud-native challengers are compressing margins on discrete point solutions. Government and defense verticals show least price sensitivity due to air-gapped infrastructure mandates, while mid-market resellers face acute budget constraints.
Supply Chain Analysis
India's phased manufacturing program and local-content mandates for telecom infrastructure are reshaping sourcing patterns for server hardware and specialized ASICs. Supply concentrates in Taiwan and South Korea for packet inspection semiconductors, with secondary sourcing from Japan for high-reliability components. Specialized ASICs for traffic classification, edge compute nodes, and subscriber data repository hardware draw from concentrated foundry capacity. Single-source vulnerability from Taiwan-based semiconductor fabrication represents the dominant structural risk. Distribution runs through systems integrators serving operator procurement teams in Germany, Japan, and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Policy management in telecom operates as a stable compounder, with 5G standalone core deployments driving steady replacement cycles and recurring managed service revenue streams.
For Market Incumbents: Acquire AI-driven traffic classification engine specialists to close capability gaps against cloud-native challengers. Embed explainability modules into machine-learning platforms ahead of EU AI Act enforcement deadlines. Secure multi-vendor interoperability certifications to defend against systems integrators consolidating procurement influence.
For New Entrants and Emerging Players: Capture edge container orchestration opportunities at multi-access edge computing nodes where latency requirements exceed incumbent virtual machine architectures. Target Brazilian operators modernizing policy control following ANATEL spectrum auctions. Lead with Kubernetes-native deployment models and professional services partnerships.
For Investors and Strategic Acquirers: BSS-heritage systems integrators are the most active acquirer in this space, consolidating best-of-breed component vendors into unified platforms. The long-term viability window favors vendors with proven multi-vendor interoperability and managed services scale. Monitor EU AI Act compliance certification timelines as inflection indicators for vendor filtering and procurement specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Containerized policy functions at edge nodes enable sub-ten-millisecond latency for Deutsche Telekom and Vodafone deployments. |
| AI Explainability Module Integration | Embedded audit trails satisfy EU AI Act algorithmic accountability requirements for French and Dutch operators. |
| Managed Services Contract Expansion | Uptime guarantees and feature velocity commitments address Australian and Canadian operator staff augmentation constraints. |
| Multi-Vendor Interoperability Certification | 3GPP-standardized interfaces enable policy exchange across heterogeneous radio access networks in Japanese deployments. |
| Defense Vertical Specialization | Air-gapped installations for Indian military communications networks capture high-margin opportunities isolated from commercial price pressure. |
Study Parameters
Multiple input streams — primary interviews with network architecture executives, policy platform product managers, and telecom procurement officers; secondary validation through 3GPP standards documentation, ANATEL regulatory filings, and operator capital expenditure disclosures; plus customs data on semiconductor imports — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeled by deployment model, end-user vertical, technology maturity tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to operator replacement cycle analysis and spectrum auction capital expenditure timing. Forecast inputs incorporated 5G standalone core deployment trajectories and EU AI Act compliance cost front-loading patterns.
Semiconductor supply disruptions, spectrum auction schedule delays, and algorithmic accountability enforcement timing are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on operator cloud migration velocity and vendor consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Telecom Radio System Software Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Turkey Telecom Market
Telecommunications
Cloud Telephony Service Market
Telecommunications
Colombia Telecom Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Underwater Modems Market
Telecommunications
Indonesia Volte Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
Brazil Telecom Market
Telecommunications
Australia Telecom Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
South Africa Telecom Market