
 Telecommunication Service Market | 2026-2036
Telecommunication Service Market Size, Share, and Industry Trends Forecast 2026-2036
Telecommunication Service Market Outlook
India is tilting toward massive fiber and 5G infrastructure deployment to close rural-urban digital divides. China Mobile anchors its position through captive spectrum holdings and state-backed capital intensity for nationwide 5G coverage. Verizon differentiates via premium enterprise edge computing bundles paired with millimeter-wave density in US metros. Deutsche Telekom navigates dual-market complexity across European wholesale and US consumer segments through its T-Mobile US arm.
Telecommunication service encompasses the provisioning of voice, data, and video transmission through wired and wireless infrastructure operating across licensed spectrum bands from 600 MHz to 39 GHz and fiber-optic cores with single-mode latency below 5 milliseconds per 100 kilometers. Its primary commercial purpose is enabling real-time information exchange for consumers, businesses, and machines at scale. Mobile services and broadband services command the largest revenue pools, while fiber optic deployment and 5G technology represent the fastest-expanding infrastructure layers where capital recovery cycles now stretch eight to twelve years. Enterprise end users generate superior margins compared to residential segments due to customized SLA requirements and managed security attachments.
The FCC governs spectrum auctions and net neutrality enforcement in the United States, while EMA and national telecom regulators across Europe enforce the EU AI Act's risk classifications for automated network management systems. India's TRAI mandates infrastructure sharing and tariff transparency, directly compressing carrier margins while accelerating rural access timelines. Stakeholders must weigh spectrum renewal costs against open RAN migration timelines to preserve capital efficiency.
Market Dynamics
Enterprise migration to 5G standalone architectures is compressing carrier revenue models while expanding addressable service layers through network slicing and edge computing attachments.
Growth Catalysts
- India's rural broadband mandate:TRAI infrastructure-sharing directives accelerate fiber-to-the-home deployment in underserved districts, expanding subscriber pools for tier-two carriers.
- EU AI Act risk classification:Automated network management systems face new compliance tiers, creating demand for certified AI governance tools among European operators.
- Millimeter-wave spectrum densification:Urban enterprise zones in US metros adopt high-band 5G for private wireless networks, driving specialized installation and maintenance contracts.
Market Restraints
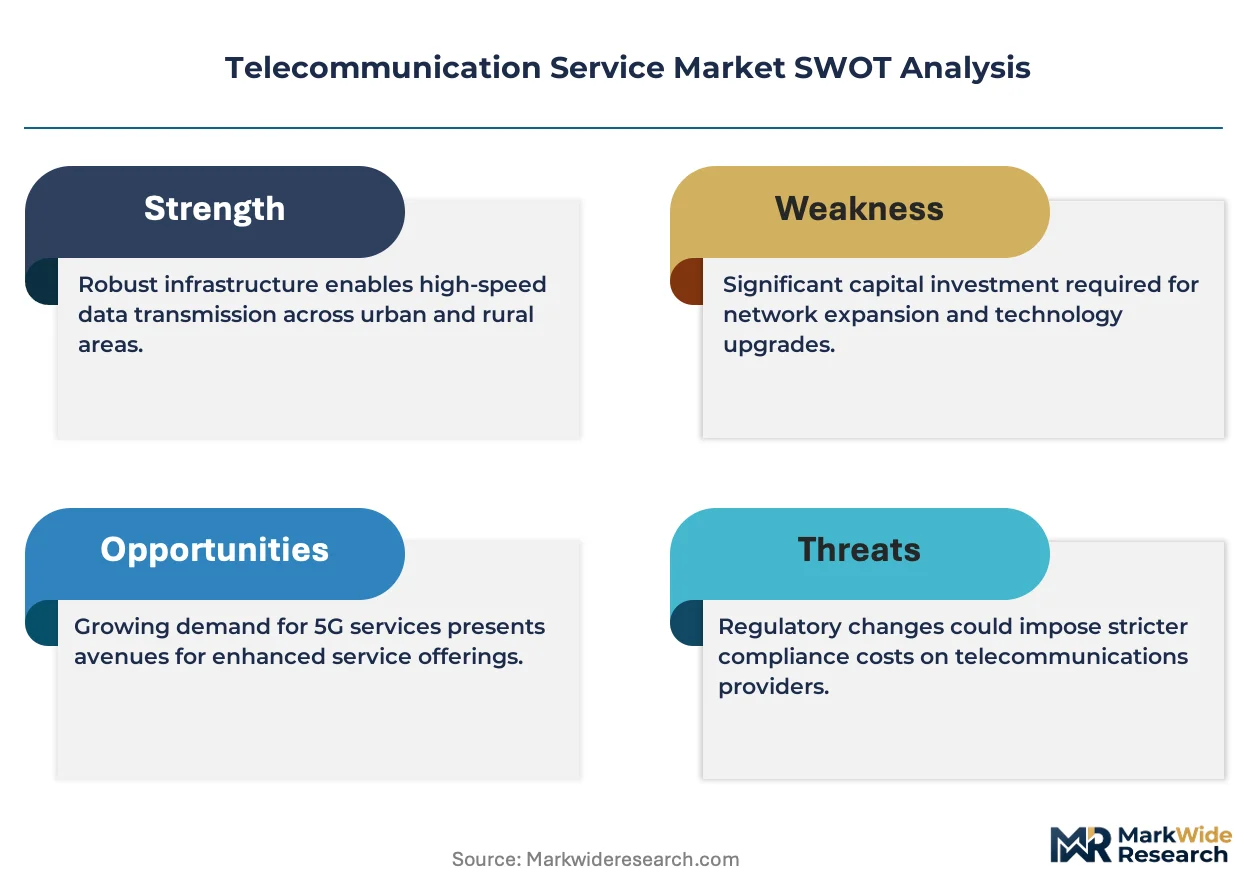
- Licensed spectrum renewal costs:FCC auction prices for mid-band holdings strain balance sheets, forcing capital rationing between coverage expansion and technology refresh cycles.
- Fiber optic cable supply concentration:Manufacturing capacity clusters in East Asian production hubs, exposing deployment timelines to geopolitical friction and shipping volatility.
- Open RAN interoperability gaps:Disaggregated hardware-software stacks introduce integration complexity, delaying cost savings promised by vendor diversification.
Strategic Opportunities
- Private 5G for manufacturing:German automotive plants and US Gulf Coast petrochemical complexes seek campus-wide wireless replacing Wi-Fi and wired Ethernet for mobile robotics.
- India's production-linked incentive scheme:Domestic telecom equipment manufacturing subsidies reduce import dependency for base stations and optical transmission gear.
- Network-as-a-service channels:Hyperscale cloud marketplaces enable consumption-based connectivity purchasing, bypassing traditional carrier-direct sales cycles.
Industry Challenges
- Legacy billing system migration:Decades-old postpaid platforms resist API integration with modern OSS/BSS stacks, complicating real-time usage metering for dynamic network slices.
- Field technician specialization:Millimeter-wave antenna alignment and fiber splicing skills concentrate in aging workforces, constraining deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecommunication Service Market |
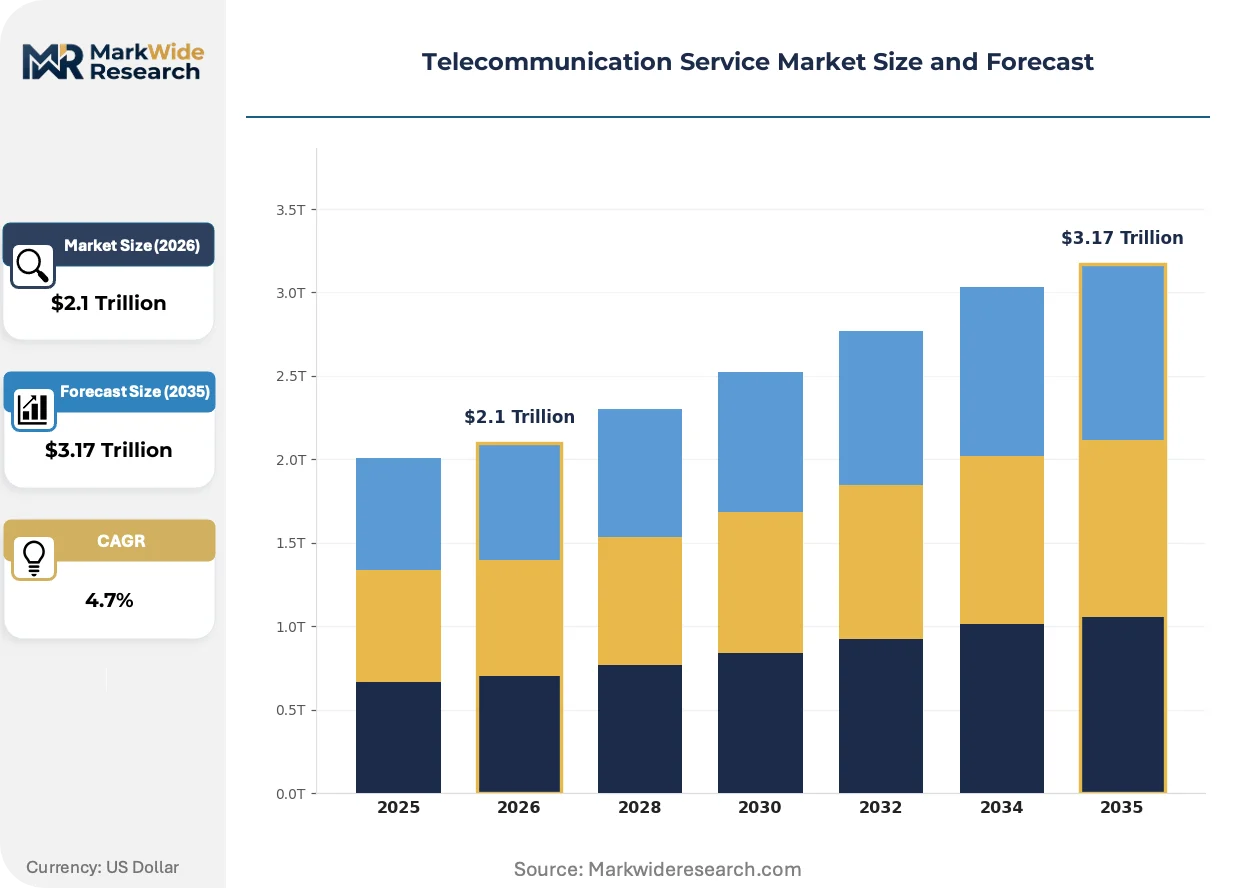
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $3.17 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
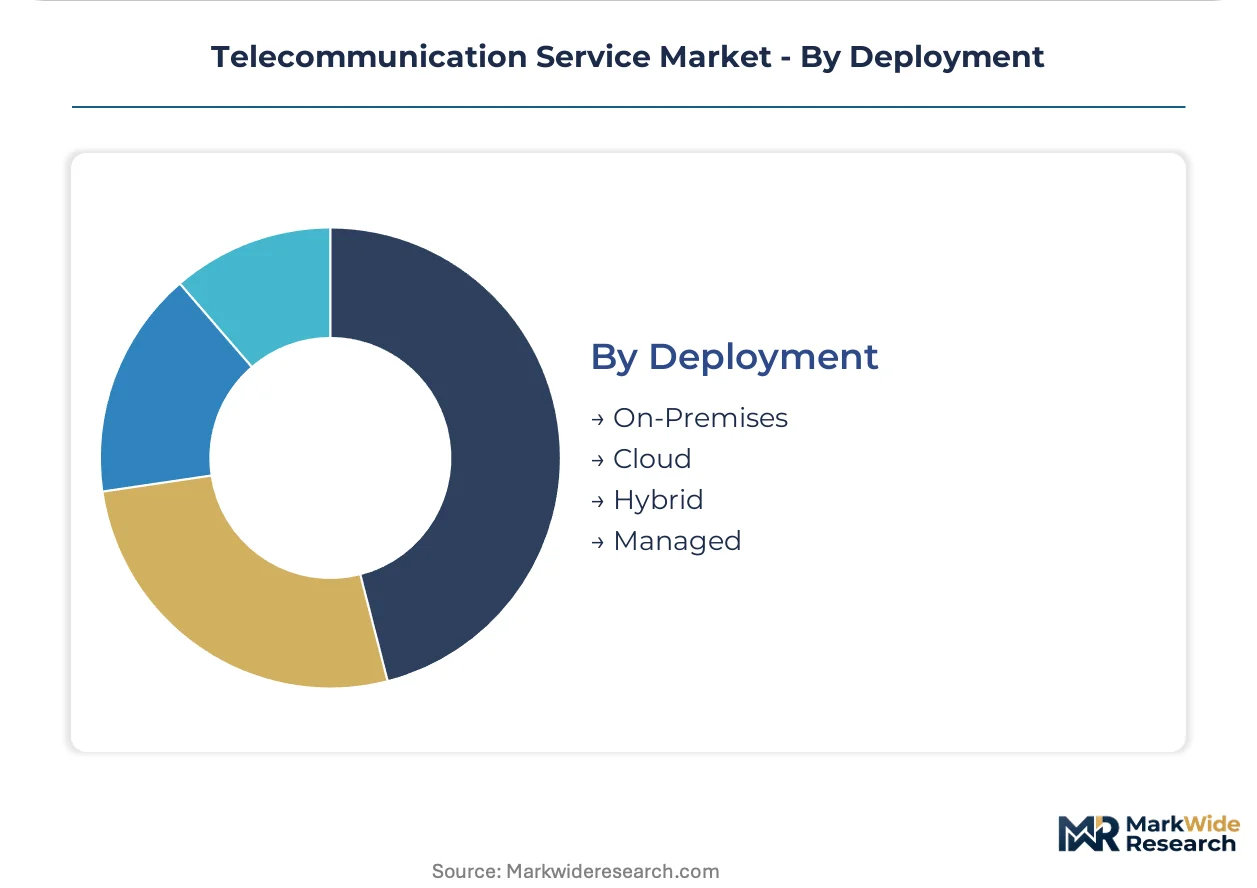
| Segmentation | Service Type: Mobile Services, Fixed Line Services, Broadband Services, VoIP Services End User: Residential, SMEs, Enterprises, Government Technology: 5G, LTE, Fiber Optic, Satellite Deployment: On-Premises, Cloud, Hybrid, Managed |
| Companies Covered | China Mobile, Verizon, AT&T, Deutsche Telekom, T-Mobile US, China Telecom, Vodafone, Orange, Nippon Telegraph and Telephone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecommunication Service Market Strategic Shifts
Telecommunication infrastructure is undergoing functional disaggregation as software-defined layers separate from proprietary hardware, enabling programmable service delivery at the network edge.
Open RAN architectures are digitizing radio access network economics by replacing integrated base stations with interoperable subcomponents from multiple vendors. Tier-one carriers in Germany and Japan pilot multi-vendor deployments to reduce supplier lock-in. This modularization is digitizing procurement patterns, shifting capital allocation from single-source equipment buys toward systems integration and software licensing.
The EU AI Act's risk-based classification for automated network optimization is mandating algorithmic transparency in European operations. Carriers must document decision logic for traffic management AI to regulators. German and French operators now embed compliance checkpoints in DevOps pipelines, treating AI governance as a core operational discipline rather than aftermarket documentation.
Enterprise buyers are consolidating connectivity spend under managed service contracts spanning multiple geographies and access technologies. Manufacturing multinationals in automotive and pharmaceuticals now procure global WANs through single-source integrators, displacing country-by-country carrier relationships. This concentration is most visible in Germany and the US, where procurement teams prioritize unified SLAs over lowest-unit pricing.
Telecommunication Service Market Segmentation
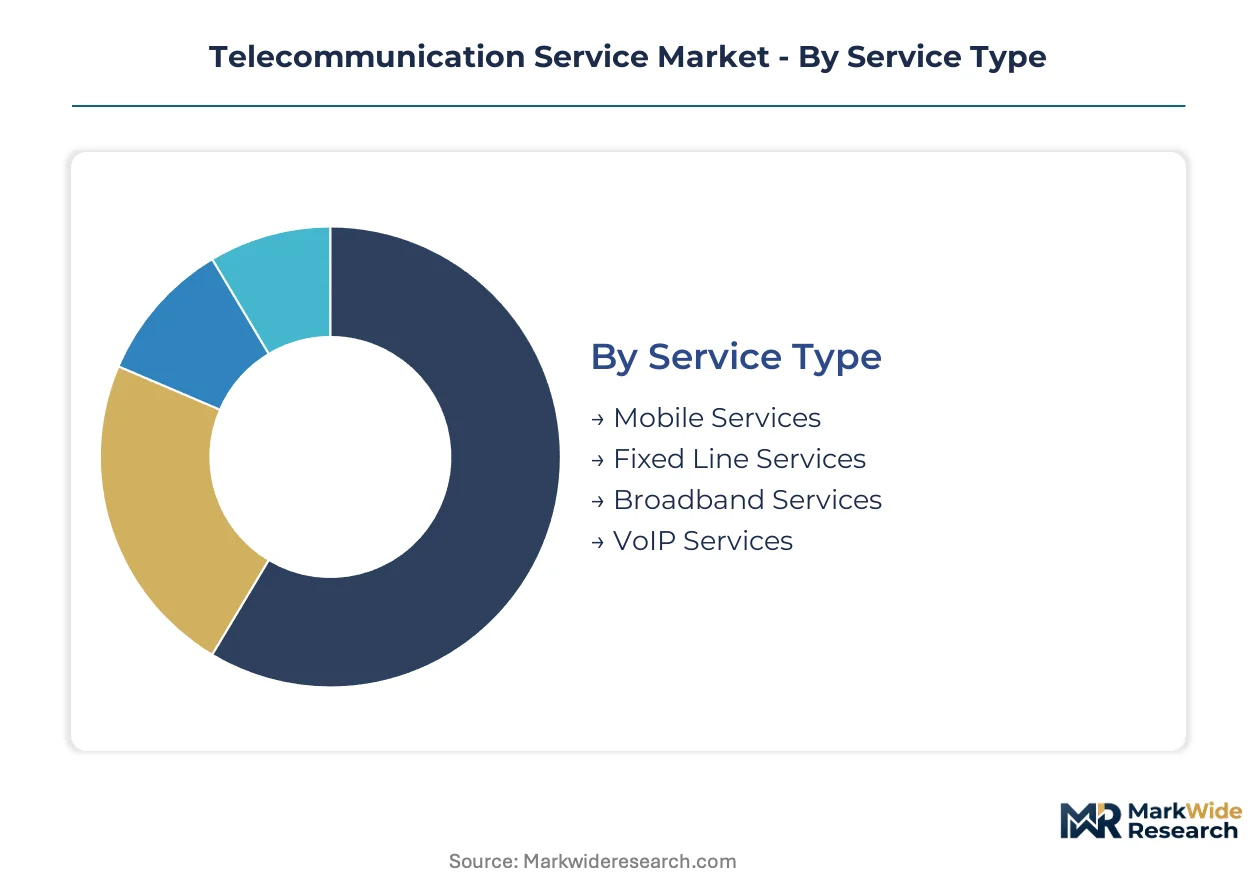
Telecommunication service segmentation reveals divergent margin profiles across connectivity modes and customer tiers. Infrastructure deployment choices and technology generations create distinct capital intensity requirements that reshape carrier investment priorities.
Service Type:
The use-case spectrum spans consumer mobility to enterprise-grade dedicated circuits with sharply differing SLA obligations.
- Mobile Services:Voice and data transmission over licensed cellular spectrum from 600 MHz to 39 GHz supports ubiquitous consumer access. Indian rural broadband mandates and US millimeter-wave densification are driving carrier infrastructure investments toward standalone 5G cores.
- Broadband Services:High-speed internet delivery through fiber-to-the-home and cable DOCSIS infrastructure achieves sub-5 millisecond latency per 100 kilometers. TRAI infrastructure-sharing directives in India accelerate fiber deployment timelines for tier-two carriers in underserved districts.
- Fixed Line Services:Traditional copper-based PSTN and ISDN circuits serve legacy enterprise voice requirements.
- VoIP Services:Packet-switched voice over IP networks enables cost arbitrage for international calling and unified communications platforms.
The dominant share belongs to Mobile Services, while Broadband Services is closing the gap fastest.
End User:
Customer type determines pricing power through customized SLA complexity and security attachment rates.
- Enterprises:Multinational manufacturing and pharmaceutical firms procure global WANs through single-source integrators with unified SLAs spanning multiple geographies. German automotive plants and US Gulf Coast petrochemical complexes drive private 5G campus network demand.
- SMEs:Small and medium enterprises adopt managed connectivity bundles through hyperscale cloud marketplaces, bypassing traditional carrier-direct sales cycles with consumption-based purchasing models.
- Residential:Consumer households generate volume but compress margins through price-sensitive prepaid and postpaid plans.
- Government:Public sector contracts mandate certified security tiers and domestic data residency requirements.
Enterprises command premium pricing, though SME cloud marketplace adoption is climbing the fastest.
Technology:
Generational infrastructure layers create overlapping coverage footprints with diverging capital recovery timelines.
- 5G:Standalone architectures with network slicing and edge computing capabilities enable enterprise private wireless deployments. Millimeter-wave spectrum densification in US metros and nationwide coverage mandates in China anchor capital allocation toward high-band infrastructure.
- Fiber Optic:Single-mode and multi-mode glass cores with amplification nodes support terabit-scale backhaul and access networks. Manufacturing capacity concentration in East Asian production hubs exposes deployment timelines to geopolitical friction.
- LTE:4G advanced networks provide fallback coverage and IoT narrowband connectivity for legacy device ecosystems.
- Satellite:Low-earth orbit constellations address rural and maritime coverage gaps beyond terrestrial infrastructure economics.
Fiber Optic holds the largest installed base, while 5G shows the steepest expansion trajectory.
Deployment:
Operational responsibility models shift capital burden between carriers and enterprise IT organizations.
- Managed:Carriers assume full lifecycle responsibility for infrastructure, operations, and security compliance under multi-year contracts. EU AI Act risk classifications for automated network management systems create demand for certified AI governance tools among European operators.
- Cloud:Network-as-a-service delivery through hyperscale marketplaces enables consumption-based purchasing with API-driven provisioning.
- On-Premises:Enterprise-owned infrastructure retains control over physical security and data sovereignty for regulated industries.
- Hybrid:Split architectures combine carrier-managed core networks with on-premises edge computing for latency-sensitive applications.
Managed deployment captures the dominant contract value, though Cloud delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TRAI infrastructure-sharing directives in India anchor the dominant geography, compressing carrier margins while accelerating rural broadband deployment timelines across underserved districts.
United States
Millimeter-wave densification in urban enterprise zones and private 5G campus networks for Gulf Coast petrochemical complexes drive specialized installation demand. FCC spectrum auction prices for mid-band holdings strain carrier balance sheets. Verizon anchors premium enterprise edge computing bundles in metropolitan corridors.
Germany
Automotive manufacturing plants seek campus-wide private 5G replacing Wi-Fi for mobile robotics. EU AI Act risk classifications mandate algorithmic transparency for automated network optimization systems. Deutsche Telekom navigates dual-market complexity across European wholesale operations.
China
Nationwide 5G coverage mandates and state-backed capital intensity drive infrastructure investment at scale. MIIT spectrum allocation frameworks favor integrated operator ecosystems. China Mobile leverages captive spectrum holdings for metropolitan and rural network expansion.
India
Rural broadband expansion and enterprise digitization concentrate carrier infrastructure investments in tier-two markets. TRAI tariff transparency mandates directly compress operator margins. Production-linked incentive schemes for domestic telecom equipment manufacturing reduce import dependency for base stations.
Japan
Multi-vendor Open RAN pilot deployments reduce supplier lock-in for tier-one carriers. METI industrial policy supports software-defined network modernization. Nippon Telegraph and Telephone anchors fiber-optic and 5G infrastructure layers in metropolitan corridors.
Telecommunication Service Market Competitive Environment
Integrated national carriers and regional wholesale specialists split the market along capital intensity and geographic scope lines. The structure concentrates around spectrum-rich incumbents with captive infrastructure assets and managed service capabilities. Tier-one integrated operators, cloud-aligned challengers, and state-backed national champions define the three dominant archetypes. Competitive moves center on multi-year enterprise managed service contracts and hyperscale cloud marketplace partnerships.
Among Asia-Pacific-based integrated operators, China Mobile exemplifies the state-backed national champion archetype through spectrum depth and infrastructure scale. Verizon and Deutsche Telekom occupy positions spanning premium enterprise segments across North American and European markets respectively. AT&T anchors a hybrid model bridging consumer mobility with managed business connectivity.
| Leading Market Players |
|---|
| China Mobile |
| Verizon |
| AT&T |
| Deutsche Telekom |
| T-Mobile US |
| China Telecom |
| Vodafone |
| Orange |
| Nippon Telegraph and Telephone |
| Others |
Value Chain & Pricing Dynamics
Fiber optic cable supply concentration in East Asian production hubs creates cascading exposure that widens pricing tiers between expedited and standard delivery contracts while compressing carrier procurement flexibility. TRAI infrastructure-sharing mandates in India and FCC spectrum auction structures in the United States feed divergent cost pressures that reshape how operators balance capital deployment against service tier positioning.
Pricing Analysis
North American enterprise connectivity commands substantial premiums over Indian rural broadband tariffs, with millimeter-wave private 5G installations in US metros pricing at multiples of fiber-to-the-home consumer plans. Three-tier pricing structure across premium, standard, and economy levels segments by SLA stringency, security certification grade, and geographic coverage density. Price erosion runs through residential mobile segments as Jio and Airtel compete for subscriber volume in Indian tier-two cities. SMEs exhibit highest price sensitivity, while multinational manufacturing firms prioritize unified global WAN contracts over unit cost minimization.
Supply Chain Analysis
Optical fiber preform and base station semiconductor fabrication draw from concentrated manufacturing footprints in China, South Korea, and Japan, with specialized coating materials and amplification components tethered to Japanese and German chemical suppliers. Raw material dependencies span high-purity silica, rare-earth doping elements for fiber amplification, and advanced compound semiconductors for 5G radio units. Single-source vulnerability concentrates in submarine cable landing stations and millimeter-wave antenna substrate production. Distribution runs through carrier-direct procurement teams, systems integrators for enterprise campus deployments, and hyperscale cloud marketplaces for consumption-based NaaS purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telecommunication infrastructure investment cycles are recovering from capital rationing pressures as 5G standalone network economics mature and enterprise private wireless demand accelerates replacement timelines.
For Market Incumbents: Pre-empt margin compression from open RAN interoperability gaps by accelerating in-house systems integration capabilities and certifying multi-vendor deployment expertise before challenger integrators capture enterprise campus contracts. Anchor spectrum renewal strategies against captive fiber depth in metropolitan corridors to defend position against wholesale-only competitors. For New Entrants and Emerging Players: Pursue white-space opportunities in India's production-linked incentive scheme for domestic base station manufacturing, where import substitution subsidies reduce capital barriers for equipment vendors. Target SME connectivity aggregation through hyperscale cloud marketplace channels, bypassing carrier-direct sales cycles with API-driven consumption models. For Investors and Strategic Acquirers: The market sits at a capital-recovery phase that favors infrastructure-heavy operators with captive spectrum and fiber assets over pure-service challengers. Long-term viability hinges on 5G standalone network density and edge computing attachment rates. Monitor TRAI tariff transparency enforcement and FCC mid-band auction structures as inflection signals for carrier margin trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Systems Integration | Multi-vendor deployment capability reduces supplier lock-in for European and Japanese tier-one carriers. |
| Private 5G Campus Network Deployment | German automotive plants and US Gulf Coast petrochemical complexes seek wireless replacement for mobile robotics. |
| Domestic Equipment Manufacturing Scale-Up | India's PLI scheme subsidies reduce import dependency for base stations and optical transmission gear. |
| Network-as-a-Service Marketplace Partnership | Hyperscale cloud channels enable consumption-based purchasing bypassing traditional carrier-direct sales. |
| AI Governance Compliance Certification | EU AI Act risk classifications mandate algorithmic transparency for automated network optimization systems. |
Study Parameters
Operator-level perspectives from network planning executives, enterprise procurement officers, regulatory affairs specialists, and field deployment engineers anchored the qualitative base. Primary interviews combined with secondary validation against FCC spectrum auction records, TRAI tariff orders, EU AI Act implementation guidance, and carrier capex disclosures. SEC filings from Verizon, Deutsche Telekom, and China Mobile provided financial trajectory benchmarks. Bottom-up service revenue modeling triangulated against top-down infrastructure investment forecasts.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning service type, end-user tier, technology generation, and deployment responsibility model. CAGRs derived from carrier-reported subscriber additions, ARPU trajectories, and infrastructure depreciation schedules. Open RAN deployment timelines and private 5G contract win rates served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments for infrastructure financing and geopolitical friction affecting East Asian component supply would shift the trajectory. Forecasts reflect documented assumptions about spectrum allocation continuity and enterprise digitization pace. Cross-checking against carrier-reported capital intensity ratios and regulator-published infrastructure deployment targets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Italy Telecom Market
Telecommunications
IP Telephony Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
5G Equipment Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
South Korea Telecom Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
Vietnam ICT Market
Telecommunications
Myanmar Telecom Market
Telecommunications
5G Radio Access Network Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Cambodia Telecom Tower Market