
 North America Gene Synthesis Market | 2026-2036
North America Gene Synthesis Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gene Synthesis Market Insights
Pharmaceutical firms is recalibrating the North America gene synthesis demand profile as cell and gene therapy programs multiply. Twist Bioscience leverages silicon-based DNA synthesis platforms to compress turnaround times for complex constructs. Thermo Fisher Scientific anchors its position through integrated workflow solutions spanning synthesis to downstream analytics. GenScript competes aggressively on price-performance metrics in the custom gene synthesis segment.
Gene synthesis encompasses the de novo chemical assembly of nucleic acid sequences from oligonucleotide precursors, typically achieving lengths from hundreds to thousands of base pairs with error-correction protocols ensuring sequence fidelity above 99.9%. The process serves as a foundational enabler for protein engineering, pathway construction, and synthetic biology applications across industrial and therapeutic domains. Gene libraries command premium pricing due to combinatorial complexity and intellectual property value, while custom gene synthesis generates the highest transaction volumes across academic and commercial accounts. Biotechnology research remains the dominant application channel, though therapeutics development exhibits the steepest growth trajectory as CRISPR-based therapies advance through clinical stages.
The FDA exercises primary oversight through its Center for Biologics Evaluation and Research, while Health Canada and PMRA govern Canadian product standards and environmental release protocols for engineered organisms. The USDA and EPA jointly regulate agricultural gene synthesis applications, creating a multi-agency compliance landscape that elevates vendor documentation burdens. Stakeholders must monitor emerging FDA guidance on synthetic DNA quality specifications and cross-border material transfer agreements between the United States, Canada, and Mexico.
Market Dynamics
Cell and gene therapy pipelines are compressing development timelines and forcing synthesis vendors to reconfigure capacity for clinical-grade material production. The FDA's evolving synthetic biology guidance is simultaneously elevating documentation burdens while clarifying pathway requirements for engineered DNA products.
Growth Catalysts
- Cell therapy manufacturing scale-up:CDMOs and pharmaceutical firms require kilogram-scale plasmid DNA production for lentiviral vector manufacturing, pulling demand toward high-throughput synthesis platforms.
- EPA coordinated framework expansion:The agency's clarified oversight of engineered microorganisms for industrial applications is reducing regulatory uncertainty for biocatalysis and agricultural biotechnology developers.
- CRISPR guide RNA standardization:Therapeutic developers are consolidating procurement around validated synthesis workflows to ensure reproducibility across clinical sites.
Market Restraints
- Phosphoramidite supply concentration:Three chemical manufacturers control the majority of North American nucleoside phosphoramidite production, creating input vulnerability for synthesis providers.
- Sequence screening compliance costs:The Department of Commerce's Export Administration Regulations and Select Agent Rules impose screening infrastructure that disproportionately burdens smaller synthesis shops.
- Long-oligo fidelity ceiling:Chemical synthesis error rates accumulate beyond 200 base pairs, forcing hybrid assembly workflows that extend turnaround times for complex constructs.
Strategic Opportunities
- Mexico biotech manufacturing expansion:Nearshoring incentives under the USMCA are attracting gene therapy developers to Baja California and Querétaro for lower-cost GMP synthesis capacity.
- DNA data storage commercialization:Archival storage providers are contracting synthesis vendors for petabyte-scale oligo pool production, opening non-biological revenue streams.
- USDA BioPreferred program alignment:Synthetic biology-derived agricultural inputs qualify for federal procurement preference, creating pull-through demand for engineered microbial strains.
Industry Challenges
- GMP-grade quality control staffing:The shortage of analytical chemists experienced in FDA-compliant sequence verification is extending batch release timelines for therapeutic-grade material.
- Cross-border material transfer documentation:US-Canada-Mexico permit harmonization remains incomplete, creating customs delays for temperature-sensitive oligonucleotide shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gene Synthesis Market |
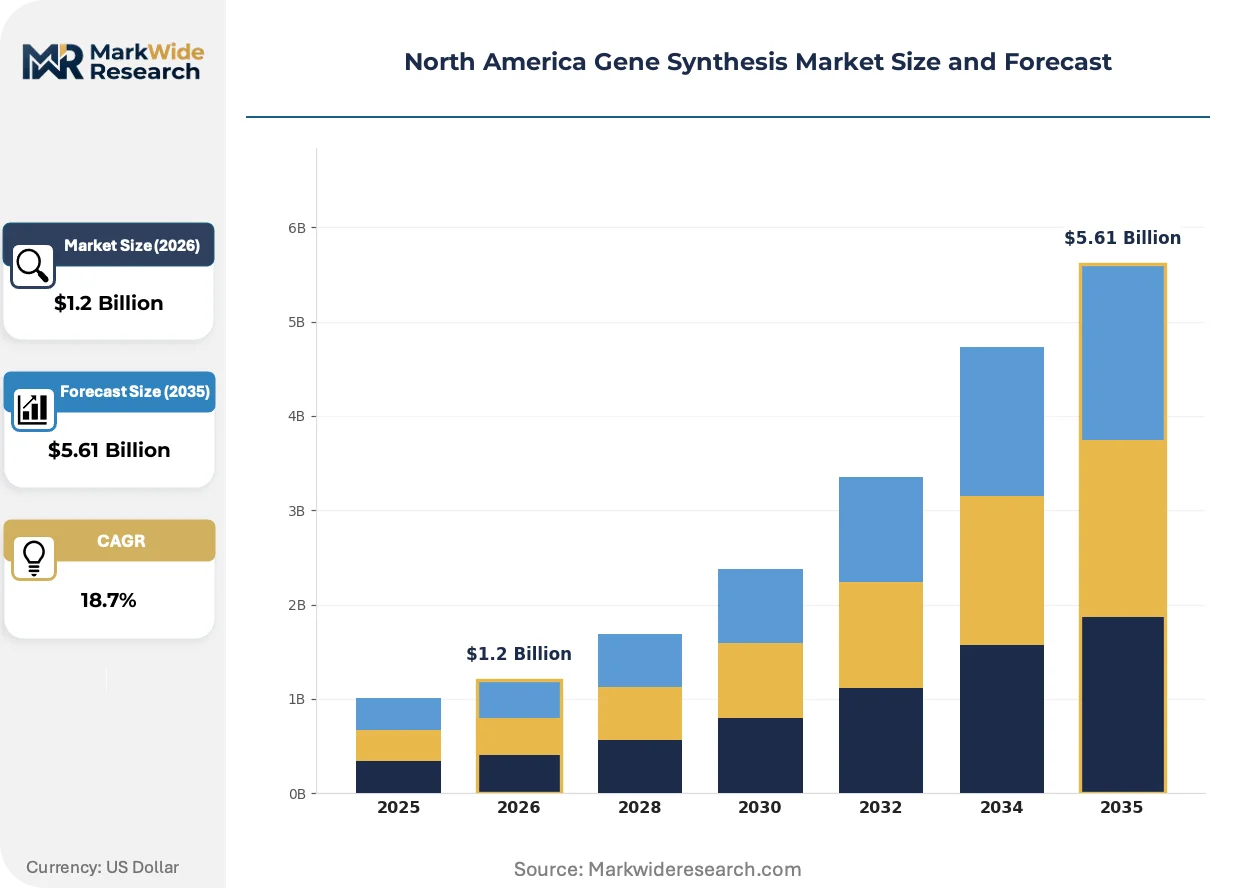
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $5.61 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Fragments, Gene Libraries, Gene Constructs, RNA Products End User: Academic Institutions, Biotechnology Companies, Pharmaceutical Firms, Research Organizations Application: Biotechnology Research, Therapeutics Development, Diagnostic Applications, Agriculture Service Type: Custom Gene Synthesis, Vector Construction, Gene Editing, Consulting Services |
| Companies Covered | Thermo Fisher Scientific, GenScript, Twist Bioscience, Integrated DNA Technologies, Azenta Life Sciences (Genewiz), Eurofins Scientific, Merck KGaA, Bio Basic Inc., OriGene Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gene Synthesis Market Trends and Innovations
Enzymatic synthesis methods are challenging chemical phosphoramidite chemistry across multiple performance dimensions. Platform convergence is compressing the gap between research-grade and clinical-grade production workflows.
Enzymatic DNA synthesis is unifying template-independent polymerase activity with error-correction mechanisms to achieve longer accurate reads without column-based purification. Therapeutic developers are piloting these platforms for clinical-grade material production. The technology is unifying synthesis and sequence verification into single-reaction workflows, eliminating post-synthesis analytical bottlenecks that currently extend turnaround times.
The FDA's emerging guidance on synthetic DNA quality specifications is clarifying documentation requirements for engineered biology products while expanding the definition of "gene therapy" to capture certain synthetic biology applications. CDMOs are restructuring quality management systems to accommodate anticipated lot-release testing harmonization. Canadian developers under Health Canada oversight are tracking US guidance development to preempt regulatory misalignment.
Pharmaceutical procurement teams are consolidating vendor relationships around full-service providers capable of synthesis through GMP manufacturing. Academic accounts and early-stage biotechs are being pushed toward self-service portals or distributor channels as direct sales coverage narrows. The concentration is most visible across the Boston-Cambridge cluster, where three synthesis providers now handle the majority of regional pharmaceutical spending.
North America Gene Synthesis Market Segmentation
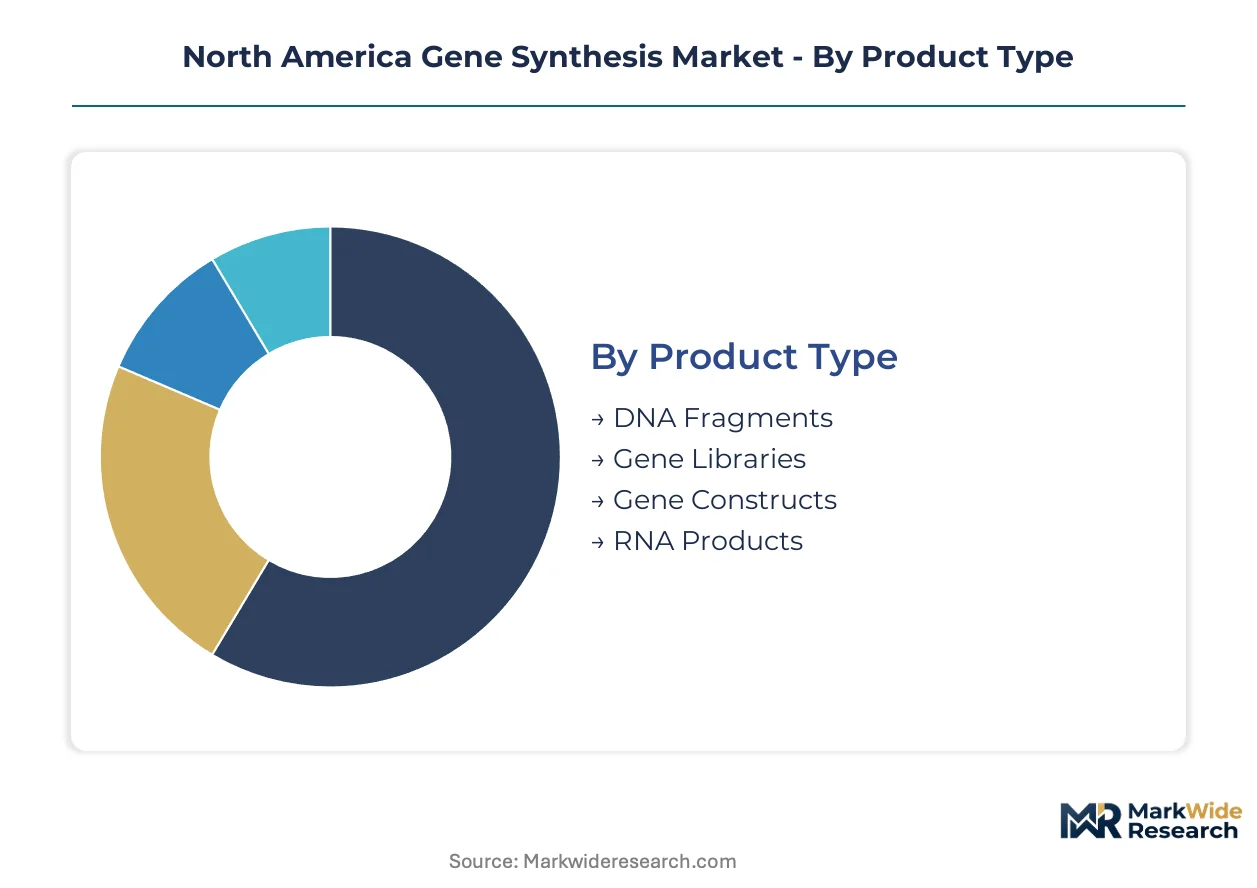
Gene synthesis vendors configure production workflows differently across product tiers, end-user sophistication levels, and regulatory requirements. Segmentation reveals where margin pools concentrate and which customer relationships justify dedicated capacity investments.
Product Type:
Standardization decreases as combinatorial complexity rises, shifting procurement from catalog ordering toward collaborative design engagements.
- Gene Libraries:Combinatorial collections of variant sequences enable directed evolution and high-throughput screening workflows. Pharmaceutical firms in the Boston-Cambridge corridor command the majority of library production capacity, driven by antibody discovery programs requiring billion-variant diversity. Premium pricing reflects intellectual property generation potential and synthesis error-rate tolerances below 0.1%.
- Custom Gene Constructs:Multi-kilobase assemblies with regulatory elements, tags, and codon optimization for heterologous expression. CDMOs serving cell therapy developers in San Diego cluster demand for clinical-grade constructs with full traceability documentation.
- DNA Fragments:Short oligonucleotides and gBlocks for routine cloning and CRISPR guide RNA production. Academic core facilities and early-stage biotechs in Research Triangle Park drive high transaction volumes at compressed margins.
- RNA Products:Synthetic mRNAs, guide RNAs, and modified oligonucleotides for therapeutic and diagnostic applications. In vitro transcription workflows and chemical synthesis routes compete based on modification pattern complexity.
Leading the category by volume: DNA Fragments. Growing fastest: Gene Libraries.
End User:
Procurement sophistication correlates with regulatory exposure, separating price-sensitive academic buyers from quality-system-driven pharmaceutical accounts.
- Pharmaceutical Firms:Integrated drug developers and gene therapy specialists requiring GMP-grade material with validated analytical packages. These accounts consolidate spending around full-service providers capable of synthesis through IND-enabling manufacturing, with FDA pre-submission consultation becoming a standard vendor expectation.
- Biotechnology Companies:Venture-backed developers and established platform companies balancing speed against cost. San Diego and South San Francisco clusters show highest synthesis intensity per R&D dollar, with many firms outsourcing entire vector construction workflows.
- Academic Institutions:University core facilities and individual investigator accounts purchasing research-grade material. Price transparency pressures dominate, with many institutions negotiating system-wide pricing through consortium purchasing agreements.
- Research Organizations:Government laboratories, nonprofit institutes, and contract research organizations. The NIH intramural program and DOE national laboratories maintain dedicated synthesis capacity while supplementing with commercial vendors for specialized chemistries.
Dominant by spending concentration: Pharmaceutical Firms. Expanding most quickly: Biotechnology Companies.
Application:
Clinical proximity determines quality system requirements and pricing power, with therapeutic applications commanding 3-5x research-grade premiums.
- Therapeutics Development:Cell and gene therapy manufacturing, mRNA vaccine production, and gene editing clinical programs. FDA Center for Biologics Evaluation and Research oversight drives vendor qualification depth, with master file references becoming competitive differentiators.
- Biotechnology Research:Protein engineering, metabolic pathway construction, and synthetic biology foundational work. Academic and industrial research groups across the United States and Canada generate the highest transaction frequency, though average order values remain below therapeutic applications.
- Diagnostic Applications:Synthetic controls, reference standards, and probe libraries for molecular diagnostics. CLIA laboratory requirements and FDA IVD regulations create dual quality pathways that specialized synthesis shops exploit.
- Agriculture:Engineered microbial strains for biocontrol, nitrogen fixation, and feed additive production. USDA and EPA coordinated framework compliance adds regulatory layers that favor established vendors with environmental release documentation experience.
Highest revenue per transaction: Therapeutics Development. Steepest volume expansion: Biotechnology Research.
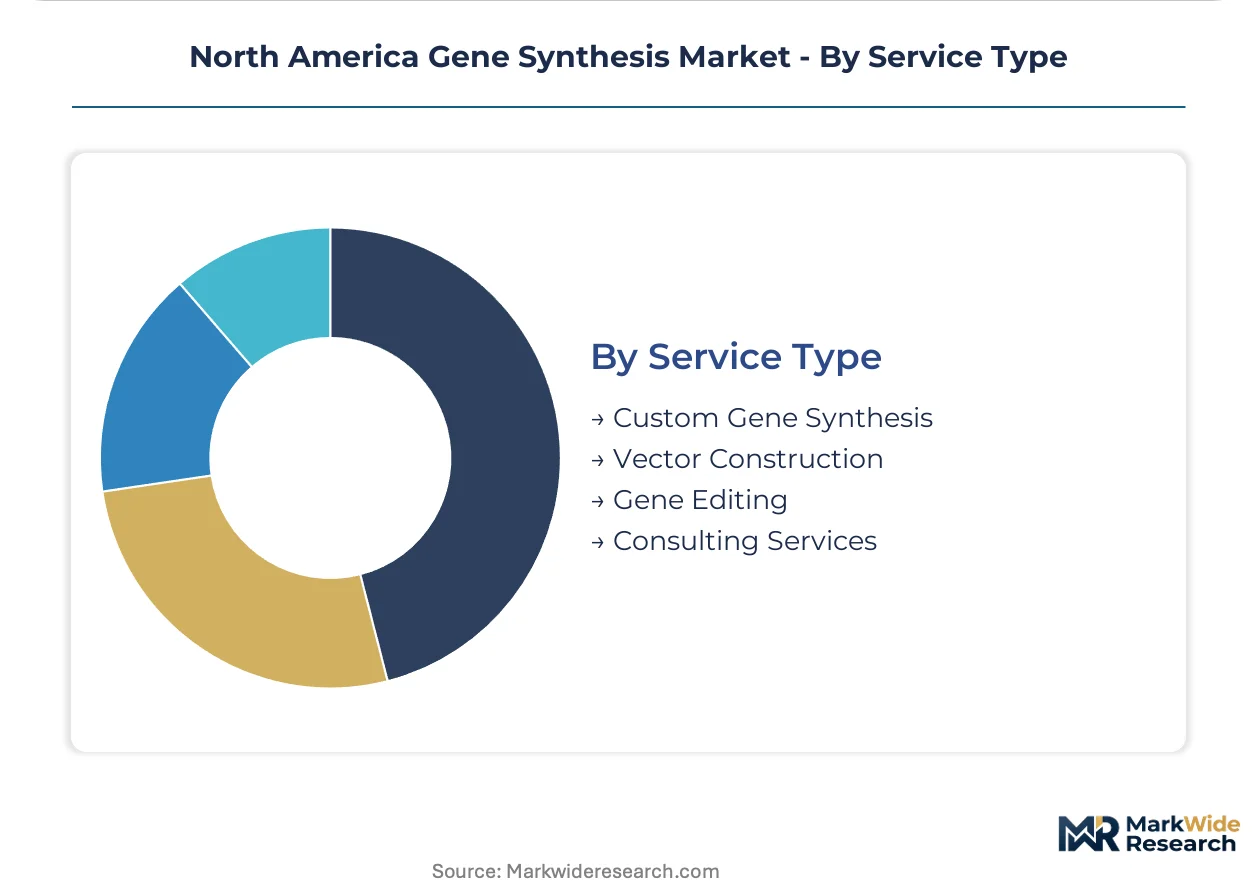
Service Type:
Value capture migrates upstream from commoditized synthesis toward design intelligence and regulatory navigation.
- Custom Gene Synthesis:De novo sequence assembly from customer-provided designs, with codon optimization and regulatory element selection as standard value-adds. Turnaround time compression and error-rate guarantees are primary competitive dimensions.
- Gene Editing:CRISPR guide RNA design, donor template synthesis, and editing validation services. Therapeutic developers are consolidating procurement around validated workflows to ensure reproducibility across manufacturing sites.
- Vector Construction:Plasmid design, cloning, and sequence verification for viral vector production. Lentiviral and AAV packaging demand is pulling capacity toward kilogram-scale plasmid production with GMP documentation.
- Consulting Services:Regulatory strategy, sequence optimization, and intellectual property navigation. FDA pre-submission support and Health Canada alignment consulting command premium day rates from specialized boutiques.
Maximum transaction volume: Custom Gene Synthesis. Gaining share fastest: Gene Editing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research and Development Tax Credit and Opportunity Zone incentives in the United States concentrate gene synthesis capacity along the Interstate 95 corridor and Southern California. Canadian SR&ED tax credits and Mexico's IMMEX maquiladora program pull investment toward cross-border manufacturing clusters.
United States
Cell therapy CDMOs and mRNA vaccine developers drive demand for GMP-grade plasmid production. The FDA Center for Biologics Evaluation and Research maintains evolving guidance on synthetic DNA quality specifications. The Boston-Cambridge cluster anchors the highest synthesis intensity, with pharmaceutical procurement teams consolidating vendor relationships around full-service providers.
Canada
Health Canada oversight of gene therapy products and PMRA environmental release protocols shape vendor qualification requirements. The SR&ED program subsidizes R&D expenditure for synthetic biology developers. Toronto and Vancouver host emerging clusters where academic spinouts contract synthesis services for metabolic engineering programs.
Mexico
Nearshoring incentives under USMCA attract gene therapy developers seeking lower-cost GMP capacity. The IMMEX program enables duty-free import of synthesis reagents for re-export of finished oligonucleotides. Baja California and Querétaro host emerging biotech manufacturing parks targeting North American pharmaceutical supply chains.
Northeast Corridor
Federal procurement preference through the USDA BioPreferred program creates pull-through demand for engineered microbial strains. The National Institutes of Health intramural program maintains dedicated synthesis capacity while supplementing with commercial vendors. Maryland and North Carolina Research Triangle Park generate high transaction volumes for research-grade constructs.
North America Gene Synthesis Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service providers capturing pharmaceutical accounts while boutique shops serve academic markets. The vendor base organizes into three tiers: integrated life science conglomerates with synthesis-through-manufacturing workflows, platform-technology specialists competing on turnaround compression, and regional service labs competing on price. Strategic moves center on capacity expansion for clinical-grade material production and regulatory consulting capabilities to navigate FDA pre-submission requirements.
Within the platform-technology tier, Twist Bioscience and Integrated DNA Technologies exemplify silicon-based and enzymatic synthesis approaches respectively. Thermo Fisher Scientific occupies a position as the integrated conglomerate archetype, anchoring pharmaceutical procurement consolidation through workflow breadth. These three companies represent the competitive spectrum from specialized technology to full-service integration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| GenScript |
| Twist Bioscience |
| Integrated DNA Technologies |
| Azenta Life Sciences (Genewiz) |
| Eurofins Scientific |
| Merck KGaA |
| Bio Basic Inc. |
| OriGene Technologies |
| Others |
Pricing and Supply Chain Analysis
Phosphoramidite precursor costs cascade through three distinct pricing tiers as chemical synthesis workflows differentiate research-grade from clinical-grade output. Academic core facilities in Research Triangle Park absorb compressed margins on high-volume DNA fragment orders, while pharmaceutical procurement teams in Boston-Cambridge pay substantial premiums for validated GMP documentation packages.
Pricing Analysis
Expedited turnaround pricing commands substantial premiums over standard lead-time slots, with pharmaceutical accounts paying differential rates for IND-enabling manufacturing timelines. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified constructs from research-grade assemblies and unverified oligo pools. Pricing pressure stems from enzymatic synthesis platforms entering therapeutic-grade segments with unified synthesis-verification workflows. Academic institutions exhibit highest price sensitivity, while cell therapy CDMOs prioritize quality system depth over unit cost.
Supply Chain Analysis
FDA Center for Biologics Evaluation and Research qualification requirements gate vendor participation in therapeutic-grade material flows, creating tiered supplier eligibility. Phosphoramidite production concentrates in the United States, Germany, and Japan, with three chemical manufacturers controlling majority North American nucleoside supply. Synthesis providers draw from specialized reagent distributors, silicon wafer foundries, and analytical instrumentation suppliers. Single-source vulnerability in long-oligo phosphoramidite chemistries threatens input continuity for complex construct assembly. Distribution runs through direct sales teams for pharmaceutical accounts, self-service portals for academic buyers, and distributor channels for smaller biotechs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America gene synthesis market functions as a cost-of-compliance arena where FDA synthetic biology guidance erects documentation barriers that favor incumbent players with established quality management systems.
For Market Incumbents: Acquire enzymatic synthesis platform capabilities to defend against template-independent polymerase technologies displacing chemical phosphoramidite workflows. Consolidate regulatory consulting capabilities through backward integration into FDA pre-submission support services, capturing pharmaceutical procurement teams that now expect master file references as standard vendor qualifications. For New Entrants and Emerging Players: USMCA nearshoring incentives in Mexico open a window for lower-cost GMP synthesis capacity serving North American pharmaceutical supply chains. Target academic core facilities and early-stage biotechs in Research Triangle Park with price-disruptive self-service portals, leveraging distributor channel partnerships to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor platform-technology specialists with enzymatic synthesis patents in the United States and Canada over asset-heavy chemical synthesis operations. Long-term viability centers on clinical-grade production workflows with validated analytical packages. Watch FDA guidance finalization on synthetic DNA quality specifications as the inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Platform Investment | Template-independent polymerase workflows unify synthesis and verification, eliminating post-synthesis analytical bottlenecks for therapeutic developers. |
| GMP Manufacturing Scale-Up | Kilogram-scale plasmid production capacity captures CDMO demand from lentiviral and AAV vector manufacturing programs. |
| Regulatory Consulting Capability Buildout | FDA pre-submission support and Health Canada alignment consulting command premium day rates from pharmaceutical procurement teams. |
| Cross-Border Manufacturing Footprint | USMCA-compliant facilities in Baja California and Querétaro reduce cost structures for North American pharmaceutical supply chains. |
| DNA Data Storage Partnership | Petabyte-scale oligo pool contracts with archival storage providers open non-biological revenue streams beyond therapeutic applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with gene synthesis platform executives, pharmaceutical procurement directors, academic core facility managers, and regulatory affairs specialists at CDMOs. FDA guidance documents, Health Canada submissions, and PMRA environmental release protocols provided regulatory trajectory inputs. SEC filings from publicly traded life science conglomerates and venture financing databases tracked capacity investment patterns. Bottom-up segment sizing triangulated against top-down market value estimates derived from synthesis provider revenue disclosures.
Shipment volume reconciliation across phosphoramidite import records, oligonucleotide export documentation, and synthesis platform utilization metrics validated demand-side estimates. Segmentation modeling spanned product type, end-user sophistication, application proximity to clinical stages, and service tier across the projection horizon. CAGRs derived from weighted average of historical growth patterns and forward-looking capacity expansion announcements. Enzymatic synthesis adoption curves and FDA guidance implementation timelines served as scenario-dependent forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for enzymatic DNA synthesis would alter the outlook if error-correction mechanisms achieve clinical-grade fidelity faster than anticipated. Forecasts reflect assumptions about regulatory harmonization between FDA and Health Canada that may shift with policy changes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Gene Editing Tools Market
Gene Editing & CRISPR
Knock Out Mouse Model Market
Gene Editing & CRISPR
Knockout Mice Model Market
Gene Editing & CRISPR
Global Plant Breeding and CRISPR Plant Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market