
 Gene Editing Tools Market | 2026-2036
Gene Editing Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Editing Tools Market Analysis
Cloud-based bioinformatics subscriptions for CRISPR guide-RNA design is decoupling software revenue from instrument hardware sales. Thermo Fisher Scientific leverages its end-to-end reagent-instrument-software stack to sustain recurring revenue across academic and pharmaceutical accounts. GenScript anchors its position through custom synthetic biology services that extend beyond catalog products into therapeutic-grade materials.
Gene editing tools comprise engineered nucleases, programmable RNA guides, and delivery vectors that introduce precise DNA modifications at target loci, with CRISPR-Cas9 systems requiring only a 20-nucleotide guide sequence to direct cleavage. These instruments serve biomedical research, agricultural trait development, and human therapeutic manufacturing by enabling heritable or somatic genetic alterations. CRISPR product types dominate current revenue owing to licensing breadth and protocol standardization, while TALEN systems retain specialized demand in agricultural applications requiring high-fidelity edits. Therapeutics application segments command premium pricing due to regulatory validation burdens, whereas biomedical research end users represent the highest volume base across academic institutions and contract research organizations.
The FDA oversees investigational new drug applications and gene therapy manufacturing standards, while the EMA's ATMP framework shapes European clinical trial design and commercial access conditions. China's NMPA has established accelerated review channels for innovative cell and gene therapies, compressing approval timelines relative to conventional biologics. Stakeholders must monitor evolving germline editing prohibitions and intellectual property rulings that could fragment platform access across jurisdictions.
Market Dynamics
CRISPR-Cas9 protocol standardization is compressing vendor differentiation and forcing reagent suppliers toward service-based revenue models anchored by therapeutic-grade manufacturing capabilities.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's regenerative medicine advanced therapy designation compresses gene therapy clinical timelines from 12 years toward 6-8 years, pulling platform investments into oncology pipelines.
- Cloud-Based Guide-RNA Design:Subscription bioinformatics tools decouple software revenue from instrument hardware, creating recurring revenue streams across academic and pharmaceutical accounts.
- Boston-San Francisco Biotech Clusters:Venture-backed firms concentrated in these metropolitan areas generate concentrated demand for GMP-grade editing reagents and viral vector manufacturing services.
Market Restraints
- Plasmid DNA Supply Concentration:GMP-grade plasmid manufacturing concentrates among North American and European contract manufacturers, creating single-source vulnerability for AAV vector production.
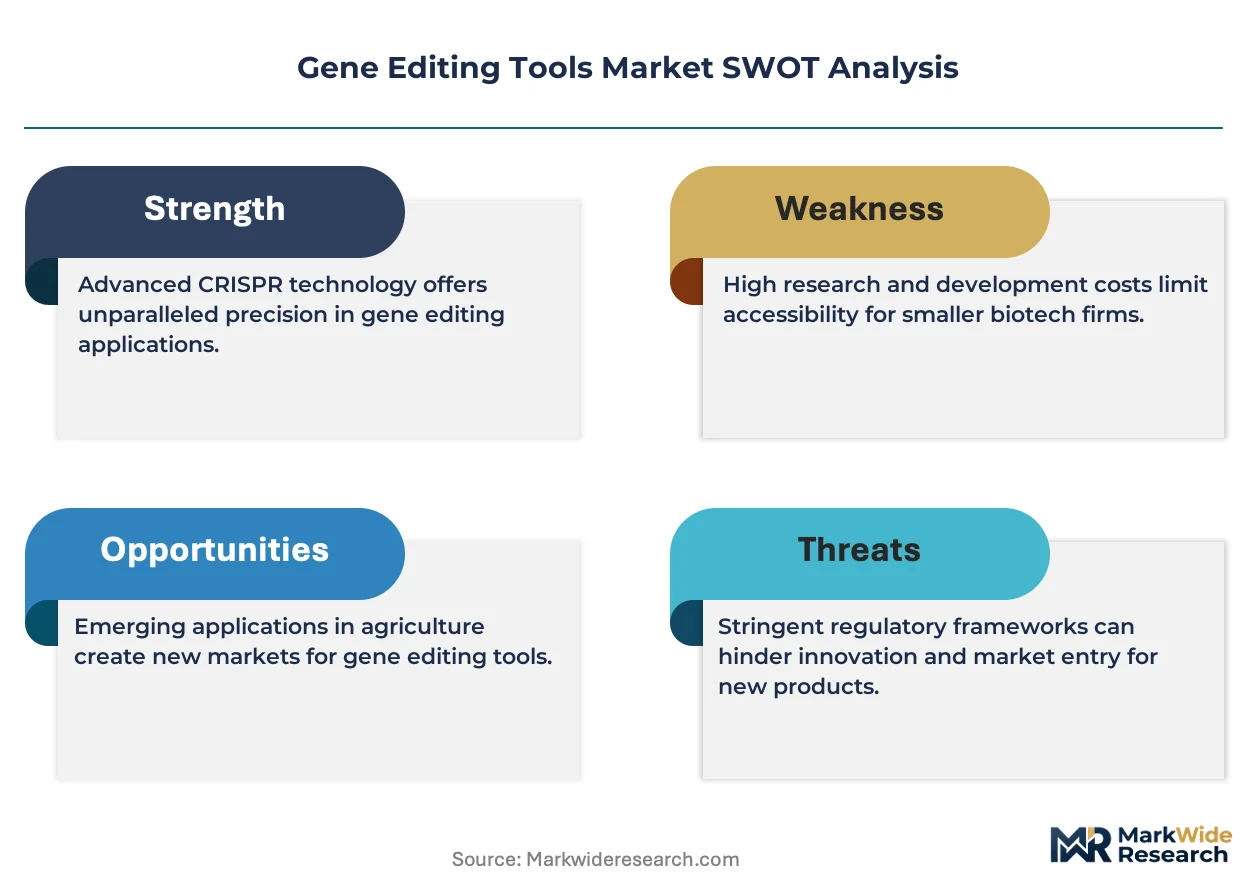
- Germline Editing Prohibitions:The FDA's explicit ban on heritable human genome editing blocks revenue streams in reproductive medicine applications despite technical feasibility.
- Guide-RNA Synthesis Cost Volatility:Phosphoramidite chemical feedstock prices fluctuate with semiconductor industry demand cycles, compressing margins on synthetic RNA guide production.
Strategic Opportunities
- China NMPA Accelerated Channels:The NMPA's breakthrough therapy designation for cell and gene therapies compresses review timelines, opening commercial pathways for CRISPR-based oncology products.
- Agricultural Trait Stacking:TALEN systems retain specialized demand in crop editing where high-fidelity multiplexed edits exceed CRISPR precision requirements, particularly in soybean and maize trait development.
- Direct-to-Researcher Distribution:E-commerce platforms bypass traditional distributor markups for catalog CRISPR reagents, capturing margin in the high-volume academic research segment.
Industry Challenges
- Cell Therapy Manufacturing Workforce Gap:GMP-compliant cell culture and viral vector production expertise concentrates among specialists trained at select academic medical centers, constraining capacity expansion.
- Intellectual Property Licensing Fragmentation:The Broad Institute-Berkeley patent dispute creates jurisdictional uncertainty over CRISPR-Cas9 commercial rights, complicating platform access across US and European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Editing Tools Market |
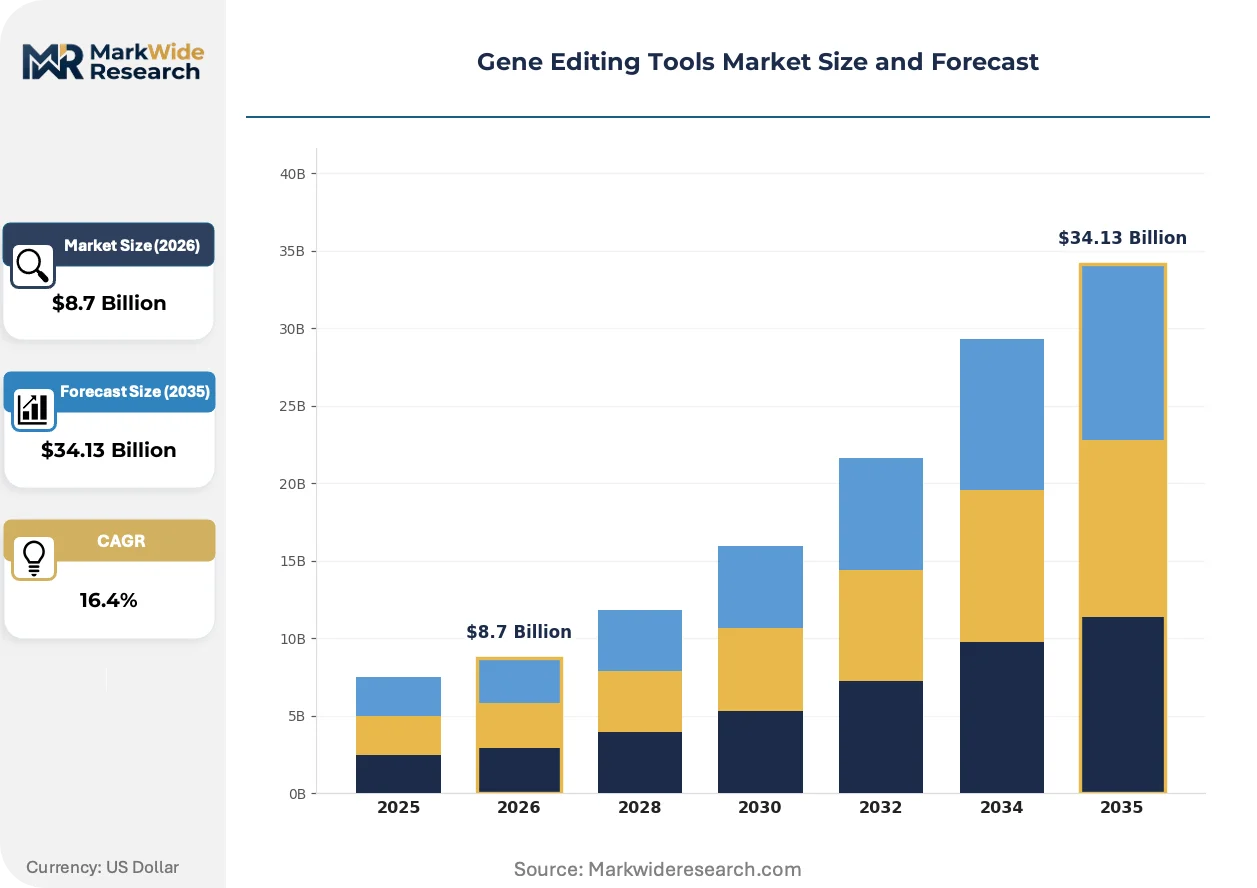
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRISPR, TALEN, ZFN, Other Application: Biomedical Research, Agricultural Development, Therapeutics, Industrial Biotechnology End User: Pharmaceutical Companies, Academic Institutions, Biotech Firms, Research Laboratories Technology: Genome Editing, Gene Synthesis, Vector Design, Other |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, GenScript, Agilent Technologies, CRISPR Therapeutics, Editas Medicine, Intellia Therapeutics, Beam Therapeutics, Synthego, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Editing Tools Market Emerging Trajectories
Base editing and prime editing architectures are displacing conventional double-strand break approaches in therapeutic pipelines, reshaping reagent demand toward deaminase and reverse transcriptase fusion proteins.
Prime editing is consolidating technical leadership in precision medicine applications by enabling all 12 types of point mutations without donor DNA templates or double-strand breaks. Pharmaceutical developers at the preclinical-to-IND transition are adopting prime editor platforms for rare disease targets where single-nucleotide precision determines therapeutic index. This architecture is consolidating intellectual property value around pegRNA design algorithms and engineered M-MLV reverse transcriptase variants.
The EMA's ATMP framework revision tightens comparability requirements for gene therapy manufacturing changes, forcing developers toward locked analytical methods earlier in clinical development. Sponsors must now demonstrate product equivalence across manufacturing scale-up using identical potency assays, compressing timeline flexibility. European clinical-stage programs face the steepest compliance burden, with Germany and France-based developers restructuring quality agreements with contract manufacturers.
Research consortia are displacing individual laboratory procurement for high-complexity editing services, concentrating volume among centralized core facilities at academic medical centers. MIT's Broad Institute and Stanford's Gene Editing Core now capture external service revenue from regional institutions lacking in-house GMP infrastructure. This concentration is most visible in the northeastern United States, where shared resource models reduce per-experiment costs for emerging biotech firms without captive manufacturing.
Gene Editing Tools Market Segmentation
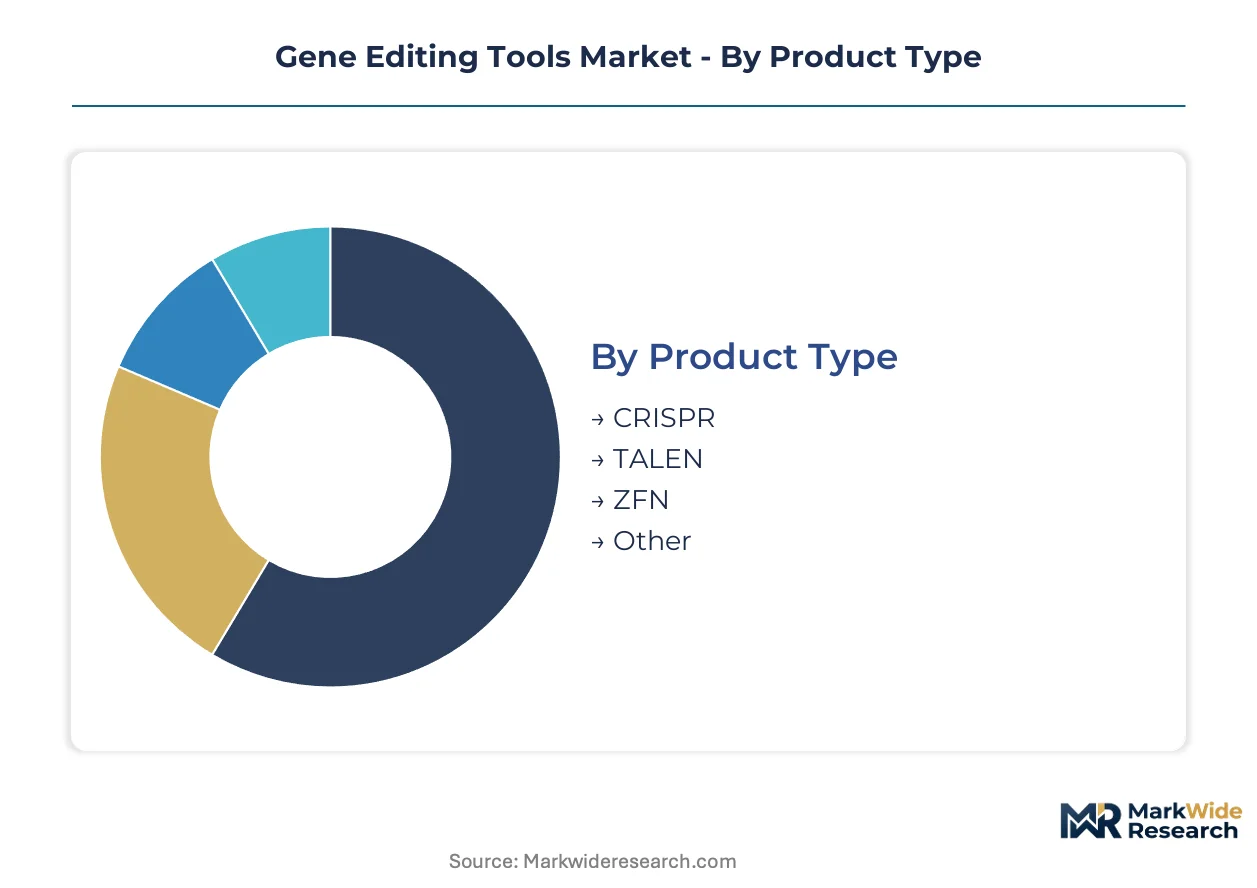
Gene editing tool vendors configure product portfolios around distinct technical specifications, end-use requirements, and regulatory compliance tiers. Segmentation reveals where pricing power concentrates and which customer segments drive volume versus margin.
Product Type:
Supply of engineered nucleases concentrates among three platform architectures, each with distinct manufacturing complexity and intellectual property licensing structures.
- CRISPR:RNA-programmable nuclease systems requiring only synthetic guide-RNA and recombinant Cas protein production. Demand concentrates in academic institutions across the United States, where protocol standardization and broad licensing agreements reduce switching costs between suppliers.
- TALEN:DNA-binding domain nucleases engineered for single-nucleotide precision without off-target activity. Agricultural biotechnology developers in Brazil and Argentina source TALEN reagents for stacked-trait soybean programs where regulatory acceptance of CRISPR-classified products remains unsettled.
- ZFN:Zinc finger nuclease platforms predating CRISPR, now confined to legacy therapeutic programs with established regulatory dossiers. Sangamo Therapeutics maintains the primary commercial ZFN pipeline for HIV and hemophilia indications.
- Other:Base editing and prime editing architectures employing deaminase or reverse transcriptase fusions. Beam Therapeutics and Prime Medicine hold foundational intellectual property for cytosine and adenine base editors.
Today's leader: CRISPR. Tomorrow's challenger: Other.
Application:
Cost tiers separate commodity research reagents from validated therapeutic-grade materials commanding 10-40x price multiples.
- Biomedical Research:Catalog CRISPR reagents for gene knockout and reporter cell line generation. Academic laboratories in Germany and the United Kingdom represent the highest-volume demand segment, purchasing through distributor and direct e-commerce channels.
- Therapeutics:GMP-grade editing components for investigational new drug applications and commercial manufacturing. Pharmaceutical companies developing CAR-T and allogeneic cell therapies source plasmid DNA, mRNA guides, and recombinant proteins under drug master file arrangements.
- Agricultural Development:Trait editing for row crops and specialty produce. Corteva Agriscience and Bayer Crop Science deploy CRISPR and TALEN systems for drought-tolerant maize and high-oleic soybean varieties.
- Industrial Biotechnology:Microbial strain engineering for enzyme production and biofuel pathways. Synthetic biology companies in Denmark and the Netherlands apply CRISPRi and CRISPRa systems for metabolic pathway optimization.
Therapeutics commands the steepest expansion trajectory as FDA regenerative medicine designations compress clinical timelines.
End User:
Customer type determines procurement sophistication, with pharmaceutical accounts demanding audit trails and quality agreements that smaller research laboratories bypass.
- Pharmaceutical Companies:Integrated drug developers with captive process development and GMP manufacturing capabilities. Novartis and Bristol Myers Squibb maintain internal gene editing groups for cell therapy pipeline advancement.
- Academic Institutions:Research universities and medical schools purchasing through institutional procurement contracts. MIT, Stanford, and the University of California system operate centralized gene editing cores serving multiple principal investigators.
- Biotech Firms:Venture-backed development-stage companies without captive manufacturing. Boston and San Francisco clusters generate concentrated demand for contract manufacturing organization partnerships and GMP reagent supply.
- Research Laboratories:Government and nonprofit research institutes including NIH intramural programs and the Broad Institute. These facilities combine internal reagent production with strategic vendor relationships for specialized components.
Pharmaceutical Companies anchor current revenue. Biotech Firms represent the fastest-climbing customer segment as venture financing flows into gene therapy platforms.
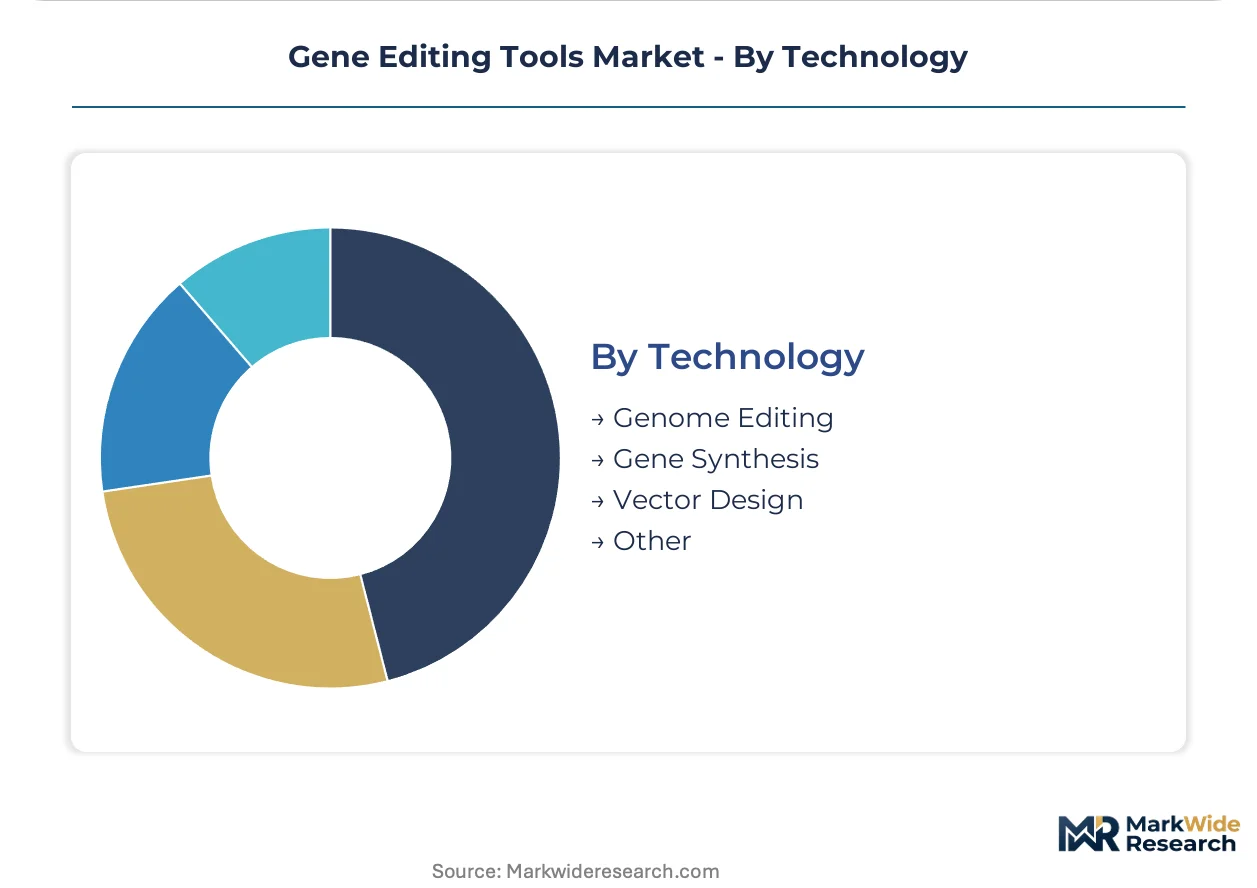
Technology:
Technology maturity separates established workflows from emerging capabilities still consolidating vendor ecosystems and standard protocols.
- Genome Editing:Targeted DNA cleavage and repair using nuclease, base editor, or prime editor architectures. CRISPR-Cas9 dominates current implementation, with next-generation variants displacing first-generation systems in therapeutic applications.
- Gene Synthesis:De novo DNA construction enabling codon-optimized transgenes and synthetic regulatory elements. Twist Bioscience and GenScript capture volume in oligo pool and gene fragment production supporting editing workflows.
- Vector Design:Viral and non-viral delivery system engineering for in vivo and ex vivo applications. AAV capsid engineering and lipid nanoparticle formulation represent the most active development areas.
- Other:Computational tools for guide-RNA design and off-target prediction. Benchling, SnapGene, and proprietary pharmaceutical platforms integrate design algorithms with laboratory information management systems.
Genome Editing leads present adoption. Vector Design holds the strongest expansion outlook as in vivo delivery unlocks new therapeutic modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA approval velocity now exceeds FDA timelines for cell and gene therapies, while Germany's EMA-aligned developers face steeper comparability burdens than their American counterparts.
United States
FDA regenerative medicine advanced therapy designations compress clinical development timelines for oncology and rare disease programs. Boston's Kendall Square and San Francisco's Mission Bay host the densest concentrations of venture-backed gene editing firms, with GMP-grade reagent demand clustering around these coastal innovation hubs.
Germany
EMA's ATMP framework revision tightens manufacturing change controls, forcing sponsors toward locked analytical methods earlier in development. Heidelberg and Munich anchor the country's therapeutic editing ecosystem, with university spinouts sourcing specialized reagents from centralized academic cores.
China
NMPA breakthrough therapy channels accelerate review timelines for innovative cell therapies, pulling CRISPR platform investments into domestic oncology pipelines. Shanghai's Zhangjiang Hi-Tech Park and Beijing's Zhongguancun Life Science Park concentrate contract manufacturing capacity for viral vector production.
United Kingdom
MHRA post-Brexit regulatory autonomy enables streamlined gene therapy trial approvals compared to continental European pathways. London's Golden Triangle institutions and Cambridge's biotech cluster generate concentrated demand for synthetic biology services and guide-RNA design platforms.
Switzerland
Swissmedic's precision medicine frameworks support early-access programs for gene editing therapeutics in rare disease indications. Basel's pharmaceutical corridor and Zurich's ETH spinout ecosystem sustain specialized demand for high-fidelity editing architectures and therapeutic-grade manufacturing partnerships.
Gene Editing Tools Market Vendor Landscape
Top-tier vendors anchor the integrated reagent-instrument-software stack, while mid-tier specialists compete on therapeutic-grade manufacturing capabilities and custom synthetic biology services. The vendor base stratifies across three archetypes: diversified life science conglomerates with end-to-end portfolios, pure-play gene editing technology developers, and contract service providers with GMP infrastructure. Dominant competitive moves include strategic licensing of CRISPR patent estates and backward integration into plasmid DNA manufacturing to secure AAV vector supply chains.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA represent integrated platform providers spanning research through therapeutic manufacturing. GenScript anchors the custom services archetype, occupying a position between catalog reagent supply and therapeutic-grade material production. These three entities exemplify how scale and specialization split competitive positioning in an environment where FDA and EMA compliance requirements favor vendors with captive quality infrastructure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| GenScript |
| Agilent Technologies |
| CRISPR Therapeutics |
| Editas Medicine |
| Intellia Therapeutics |
| Beam Therapeutics |
| Synthego |
| Others |
Supply Flow & Price Mechanics
Prime editing's displacement of conventional CRISPR workflows is simultaneously compressing reagent cost structures and concentrating manufacturing expertise among vendors with captive reverse transcriptase fusion protein capabilities. This platform transition rewards suppliers that have integrated GMP-grade pegRNA synthesis with engineered M-MLV variant production, while marginalizing pure-play guide-RNA catalog providers.
Pricing Analysis
Capacity additions in China are reshaping price floors for phosphoramidite-based guide-RNA synthesis. Three-tier pricing structure across GMP-grade therapeutic, GLP-grade preclinical, and research-grade catalog tiers separates FDA-audited suppliers from standard ISO-certified competitors. Cost compression in the research-grade tier is intensifying because Chinese manufacturers are expanding synthetic RNA capacity. Academic laboratories exhibit the highest price sensitivity, while pharmaceutical companies prioritize audit trail completeness over per-unit cost.
Supply Chain Analysis
Freight costs for temperature-controlled plasmid DNA shipments from North American contract manufacturers to European viral vector facilities have risen substantially. GMP-grade plasmid manufacturing concentrates in the United States, Germany, and Switzerland, drawing from phosphoramidite chemical feedstocks, recombinant protein expression systems, and specialized packaging materials. Single-source vulnerability pervades AAV vector production due to plasmid supply concentration. Distribution runs through direct vendor relationships with pharmaceutical accounts and e-commerce platforms for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gene Editing Tools Market has entered a late-cycle quality phase where therapeutic-grade certification and locked analytical methods command premium positioning. Demand is shifting decisively toward GMP-compliant reagents as FDA regenerative medicine designations pull platforms into commercial manufacturing.
For Market Incumbents: Hedge against base editing and prime editing patent estates by securing non-exclusive licensing agreements with Beam Therapeutics and Prime Medicine before exclusivity windows close. Build backward integration into plasmid DNA manufacturing to secure AAV vector supply chains against single-source concentration risk. Prioritize EMA-aligned quality infrastructure to capture European clinical-stage programs facing steeper comparability burdens.
For New Entrants and Emerging Players: Enter via agricultural trait stacking applications in Brazil and Argentina, where TALEN systems retain specialized demand and regulatory acceptance of CRISPR-classified products remains unsettled. Target biotech firms in Boston and San Francisco clusters lacking captive GMP infrastructure with contract manufacturing partnerships. Pursue direct-to-researcher e-commerce distribution to bypass traditional distributor markups in the high-volume academic segment.
For Investors and Strategic Acquirers: Valuations sit cheapest among custom synthetic biology service providers with therapeutic-grade manufacturing capabilities but limited patent estates. Long-term viability over the next decade hinges on regulatory validation breadth across FDA, EMA, and NMPA jurisdictions. Watch for NMPA breakthrough therapy designation announcements as the signal indicating inflection toward China-centric platform investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA regenerative medicine designations compress oncology timelines toward commercial manufacturing readiness. |
| Manufacturing Scale-Up | GMP-grade plasmid capacity expansion secures AAV vector supply chains for in vivo delivery platforms. |
| Regulatory Approval Pathway | NMPA breakthrough therapy channels accelerate domestic CRISPR-based oncology product commercialization. |
| Licensing Agreement | Prime editing patent access enables single-nucleotide precision applications in rare disease pipelines. |
| Pipeline Diversification | Agricultural trait stacking with TALEN systems hedges against therapeutic regulatory volatility. |
Methodological Framework
Bottom-up therapeutic application modeling reconciled against top-down reagent supply tracking forms the analytical core of this study. Primary interviews with gene therapy development executives, regulatory affairs leads at pharmaceutical sponsors, GMP manufacturing site directors, and academic core facility managers were combined with secondary validation from FDA IND filings, EMA ATMP submissions, ClinicalTrials.gov records, and NMPA breakthrough therapy announcements. Trade data on phosphoramidite imports and recombinant protein expression system deployments provided supply-side cross-checks.
Historical trendline analysis of CRISPR reagent shipments and therapeutic program initiations established baseline growth patterns across the projection horizon. The forecast framework segments by product architecture, application tier, end-user sophistication, and regional regulatory cluster, with CAGRs derived from elasticity modeling against clinical pipeline advancement rates. Inputs included viral vector manufacturing capacity expansion timelines, cloud-based bioinformatics subscription growth curves, and germline editing prohibition enforcement patterns.
Inputs from FDA, EMA, and NMPA regulatory databases were available through the study window; gaps in real-time plasmid manufacturing capacity utilization introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented assumptions regarding clinical trial success rates and manufacturing scale-up feasibility. Patent dispute resolution timelines and phosphoramidite feedstock price volatility represent material revision risks. A model refresh is warranted upon material change in FDA regenerative medicine designation velocity or NMPA breakthrough therapy approval rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
US Gene Editing Market
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
Knock Out Mouse Model Market