

Base Editing Market Size, Share, and Industry Trends Forecast 2026-2036
Base Editing Market Insights
Clinical trial outsourcing channels are rewriting how base-edited therapies reach patients. Beam Therapeutics leverages its proprietary delivery platforms to sustain first-mover positioning in sickle cell programs. Thermo Fisher Scientific anchors global supply of specialized reagents and analytical tools for base editing workflows. Merck KGaA competes across CRISPR and base editing enzyme portfolios with integrated life science distribution.
Base editing employs catalytically impaired nucleases fused to deaminase enzymes to convert single DNA bases without double-strand breaks, achieving C-to-T or A-to-G transitions with precision below 0.1% indel rates. DNA base editors dominate current therapeutic pipelines due to their maturity in hematopoietic stem cell applications, while prime editors represent the fastest-expanding segment for complex genomic rewriting. Delivery technology via lipid nanoparticles captures concentrated margin pools as pharmaceutical developers prioritize non-viral approaches for in vivo liver targeting.
FDA's regenerative medicine advanced therapy designation and EMA's priority medicines scheme shape accelerated development timelines for base-edited candidates, compressing traditional phase transitions. The EU AI Act and GDPR impose computational and data governance standards on predictive off-target scoring platforms used in candidate selection. Stakeholders must monitor evolving germline editing prohibitions and national biosecurity frameworks that could restrict cross-border material transfers.
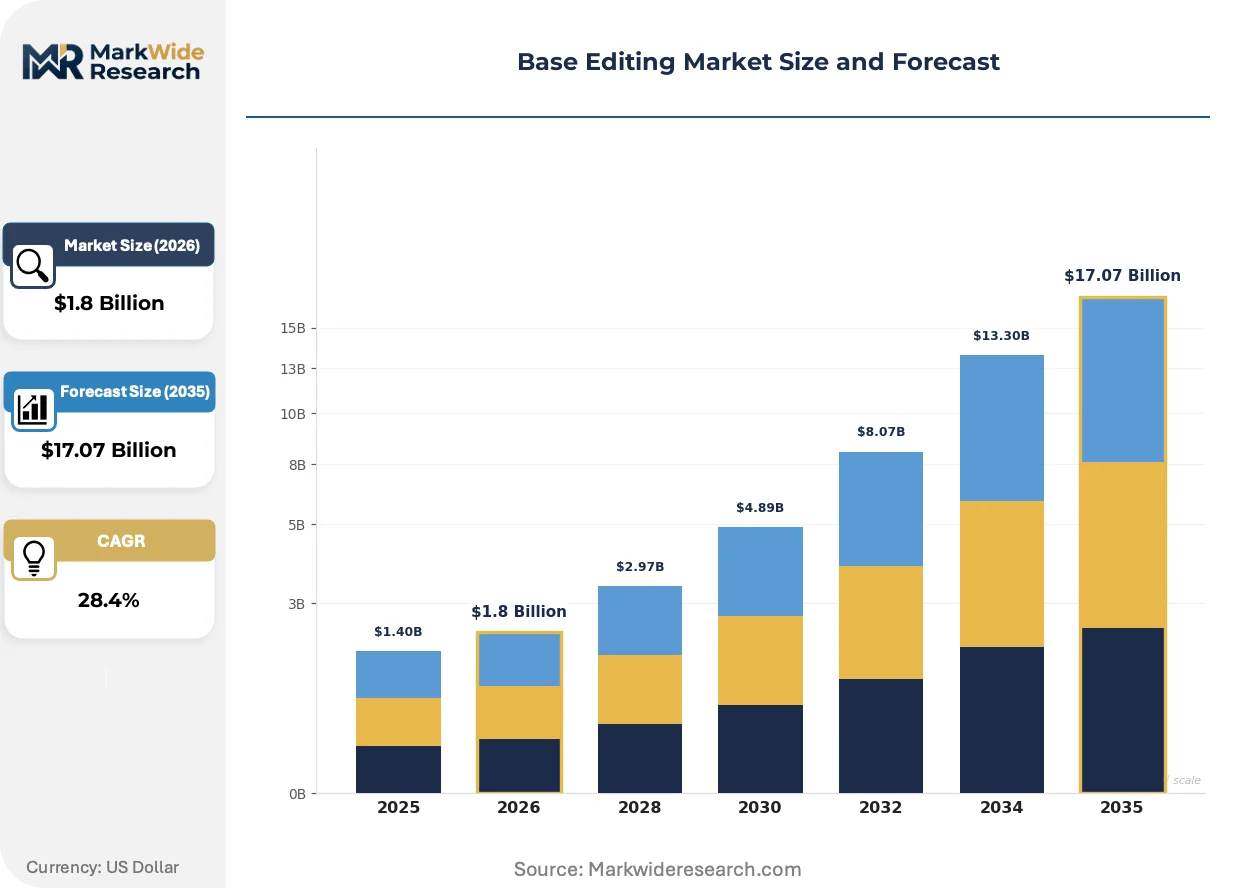
Market Dynamics
Non-viral delivery platforms are compressing development timelines for in vivo base-edited therapies, forcing pharmaceutical developers to reconfigure manufacturing partnerships around lipid nanoparticle supply chains rather than viral vector capacity.
Growth Catalysts
- Regenerative Medicine Advanced Therapy Designation:FDA's expedited pathway compresses phase transitions for base-edited candidates targeting sickle cell disease, accelerating patient access timelines.
- Hematopoietic stem cell editing maturity:DNA base editors demonstrate validated clinical protocols in ex vivo applications, de-risking therapeutic development for blood disorders.
- Germany's biotechnology clusters:Concentrated research infrastructure around Munich and Heidelberg anchors European preclinical development and enzyme engineering talent pools.
Market Restraints
- Specialized reagent supply concentration:Thermo Fisher Scientific and Merck KGaA control critical deaminase enzyme and guide RNA synthesis capacity, creating single-source dependencies.
- GMP manufacturing capex intensity:Commercial-scale base editing requires dedicated cleanroom facilities for cell processing and quality control analytics.
- Off-target liability exposure:Predictive computational platforms face validation gaps against experimental data, complicating regulatory submissions.
Strategic Opportunities
- Prime editing convergence:Integration of reverse transcriptase with base editing architectures enables complex genomic rewriting beyond single-nucleotide transitions.
- India's contract research expansion:CDSCO's streamlined investigational new drug pathways attract outsourced preclinical validation for base-edited candidates.
- In vivo liver targeting:Lipid nanoparticle delivery to hepatocytes opens therapeutic applications for familial hypercholesterolemia and metabolic disorders.
Industry Challenges
- Computational biology talent scarcity:Predictive off-target scoring requires rare cross-training in machine learning and molecular biology.
- Cross-border material transfer friction:National biosecurity frameworks restrict shipment of engineered nucleases and patient-derived cells.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Base Editing Market Trends and Innovations
Base editing workflows are converging with artificial intelligence-driven target prediction, compressing candidate selection from months to weeks while raising new compliance obligations under computational governance frameworks.
Prime editing systems incorporating engineered reverse transcriptase variants are rendering obsolete traditional dual-nickase approaches for complex genomic corrections. Large pharmaceutical developers are adopting these architectures for indications requiring multi-base substitutions. The shift is compressing preclinical validation timelines and reducing reliance on homology-directed repair pathways.
EMA's priority medicines scheme and FDA's regenerative medicine advanced therapy designation are creating parallel accelerated pathways that compress traditional phase transitions. Developers are restructuring clinical trial designs to leverage these frameworks simultaneously. Hematopoietic stem cell applications in sickle cell disease are capturing the majority of designations, concentrating regulatory expertise in specific therapeutic areas.
Academic medical centers are displacing traditional contract research organizations as the primary site for first-in-human base editing studies. These institutions offer integrated cell processing laboratories and direct patient access for rare disease populations. The United States and United Kingdom are witnessing the most pronounced channel migration, with Boston and London clusters anchoring this shift.
Base Editing Market Segmentation
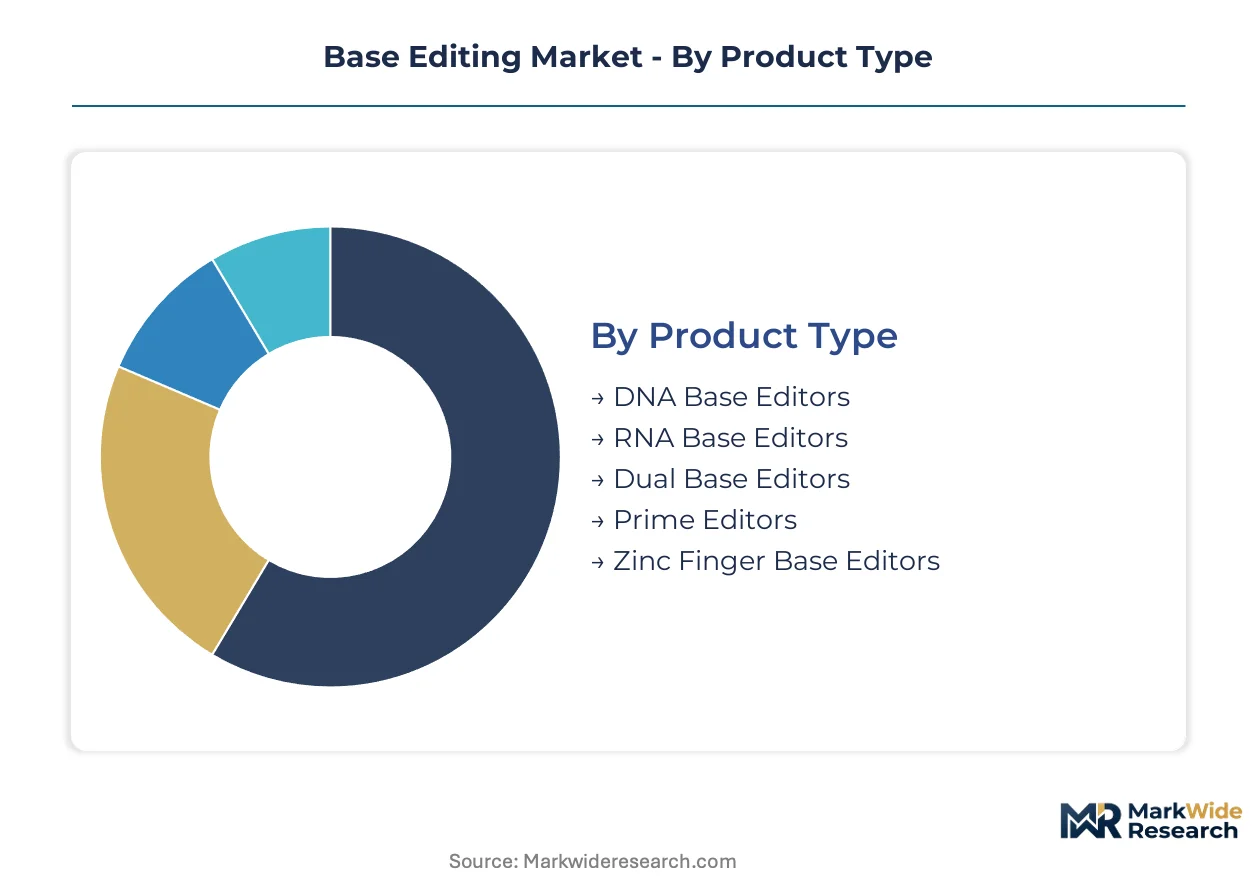
Base editing market segmentation reveals how technical specifications, therapeutic targets, and delivery modalities allocate capital across development pipelines. Understanding these dimensions exposes where manufacturing partnerships concentrate and which platforms command premium pricing.
Product Type:
Cost tier differentiation separates mature enzyme platforms from emerging architectures requiring specialized reagent investments.
- DNA Base Editors:Catalytically impaired Cas9 fused to cytidine or adenine deaminases enables C-to-T and A-to-G transitions without double-strand breaks. Hematopoietic stem cell applications in sickle cell disease drive concentrated demand from United States pharmaceutical developers seeking validated clinical protocols.
- Prime Editors:Engineered reverse transcriptase fused to nickase Cas9 permits all 12 types of point mutations plus small insertions and deletions. Complex genomic rewriting applications in familial hypercholesterolemia are gaining share fastest as developers bypass homology-directed repair limitations.
- RNA Base Editors:Adenosine deaminases acting on RNA enable transient transcript modification without permanent genomic alteration.
- Dual Base Editors:Simultaneous C-to-T and A-to-G conversions reduce multiplexing requirements for compound heterozygous corrections.
- Zinc Finger Base Editors:Smaller DNA-binding domains expand viral packaging capacity for in vivo delivery constraints.
DNA base editors command the established base. The steepest expansion runs through prime editors.
Application:
Application segmentation tracks how regulatory pathway maturity and reimbursement potential allocate R&D expenditure across indication categories.
- Genetic Disease Treatment:Monogenic disorders with well-characterized pathogenic variants offer clearest regulatory endpoints. Sickle cell disease and beta-thalassemia programs in the United States dominate active clinical trials, with FDA regenerative medicine advanced therapy designations compressing development timelines.
- Synthetic Biology:Microbial strain engineering for pharmaceutical precursors and industrial enzymes leverages base editing precision to avoid fitness costs from random mutagenesis. Yeast and bacterial chassis development in Germany's biotechnology clusters anchors European demand.
- Agricultural Crop Improvement:Nutritional enhancement and stress tolerance traits in rice and wheat access CRISPR regulatory exemptions in select jurisdictions.
- Functional Genomics:Pooled screening applications in cancer dependency maps require high-throughput base editing libraries.
- Therapeutic Development:Target validation and lead optimization in early-stage drug discovery programs.
Genetic disease treatment commands the established base. Synthetic biology applications are climbing the fastest.
End User:
Customer type segmentation exposes procurement concentration and technical service requirements that shape vendor pricing power.
- Pharmaceutical Developers:Large-cap companies integrate base editing into rare disease portfolios through internal platforms and asset acquisitions. United States and United Kingdom headquarters dominate late-stage clinical investment, with dedicated cell processing facilities requiring GMP-compliant reagent supply chains.
- Academic Research Institutes:Non-exclusive licensing from Broad Institute and Harvard enables exploratory applications without milestone obligations. Boston and London clusters anchor publication output and talent pipelines for commercial translation.
- Biotechnology Firms:Venture-backed platforms compete on delivery technology and tissue specificity.
- Contract Research Organizations:Preclinical validation services and IND-enabling toxicology studies for base-edited candidates.
- Agricultural Corporations:Seed companies accessing trait development through in-licensed editing platforms.
Pharmaceutical developers command the established base. Academic research institutes are gaining share fastest through technology transfer pipelines.
Delivery Technology:
Supply concentration in specialized manufacturing determines which modalities achieve cost-competitive scale for in vivo versus ex vivo applications.
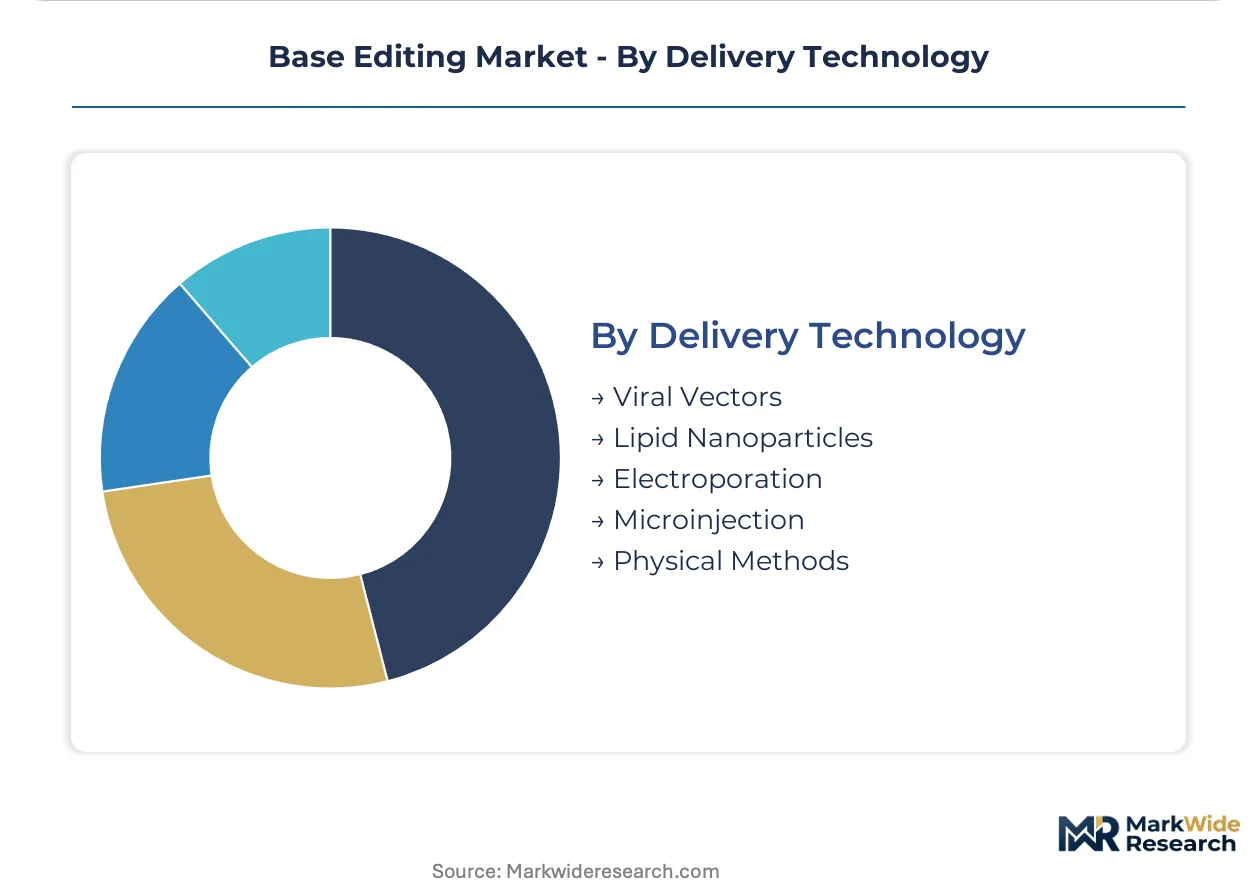
- Lipid Nanoparticles:Ionizable lipids encapsulate mRNA-encoded base editors for transient expression in hepatocytes. Non-viral manufacturing avoids viral vector capacity constraints, with United States and Canada suppliers anchoring global lipid and cholesterol derivative production for liver-targeted metabolic disorders.
- Viral Vectors:Adeno-associated virus serotypes with engineered capsids enable tissue-specific tropism for CNS and ocular indications. AAV manufacturing bottlenecks in United States contract development facilities limit program expansion despite established regulatory familiarity.
- Electroporation:Ex vivo cell engineering for hematopoietic stem cells and T-cell therapies.
- Microinjection:Embryo editing for agricultural and research model organism applications.
- Physical Methods:Cell-penetrating peptide and nanopore-mediated delivery for hard-to-transfect cell types.
Viral vectors command the established base. Lipid nanoparticles are expanding most quickly through manufacturing scalability advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for base editing reagents concentrates in United States and German supply chains, while clinical trial execution gravitates toward United Kingdom and Singapore cost structures. This asymmetry shapes regional investment flows and partnership architectures.
United States
FDA regenerative medicine advanced therapy designations for sickle cell programs concentrate capital in Boston and San Francisco corridors. The agency's adaptive pathway frameworks compress investigational new drug timelines. Beam Therapeutics anchors manufacturing partnerships in Massachusetts while Intellia Therapeutics maintains active clinical infrastructure in California.
Germany
EMA priority medicines schemes accelerate base-edited therapy approvals for hematopoietic stem cell applications. Heidelberg and Munich biotechnology clusters host concentrated enzyme engineering talent pools. Merck KGaA integrates CRISPR and base editing portfolios through life science distribution networks anchored in Darmstadt.
United Kingdom
MHRA post-Brexit regulatory autonomy enables streamlined gene therapy trial initiations. London academic medical centers displace traditional contract research organizations for first-in-human base editing studies. Oxford and Cambridge clusters anchor cell processing laboratory capacity for rare disease patient access.
China
NMPA streamlined pathways for innovative biologics attract base editing preclinical validation outsourcing. Shanghai and Suzhou biotech parks concentrate CDMO capacity for viral vector and lipid nanoparticle manufacturing. GenScript anchors guide RNA synthesis supply chains for regional pharmaceutical developers.
Singapore
HSA regulatory efficiency and IP protection frameworks attract Asia-Pacific clinical trial regionalization. Biopolis research corridor hosts electroporation and cell processing infrastructure for ex vivo base editing applications. Thermo Fisher Scientific maintains specialized reagent distribution hubs serving ASEAN pharmaceutical markets.
Base Editing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and analytical tool supply. The market structures around three concentration nodes: end-to-end therapeutic developers, enzyme and guide RNA suppliers, and delivery technology fabricators. Strategic moves cluster on manufacturing partnerships for lipid nanoparticle capacity and non-exclusive licensing from academic patent estates.
Among platform-integrated developers, Beam Therapeutics and Intellia Therapeutics occupy positions exemplifying the therapeutic application archetype, while Thermo Fisher Scientific represents the upstream reagent and analytical infrastructure tier. These entities anchor competitive dynamics without constituting an exhaustive market map.
| Leading Market Players |
|---|
| Danaher Corporation |
| Beam Therapeutics |
| Merck KGaA |
| Revvity |
| GenScript |
| Thermo Fisher Scientific |
| Intellia Therapeutics |
| Takara Bio |
| Cellectis |
| Others |
Pricing and Supply Chain Analysis
Thermo Fisher Scientific and Merck KGaA concentration in deaminase enzyme synthesis anchors margin capture in downstream therapeutic applications. Pricing power for base-edited therapies flows from this upstream reagent lock-in toward pharmaceutical developers configuring GMP-compliant supply chains.
Pricing Analysis
Configured-to-order GMP reagent suites command 40-60% premiums over research-grade equivalents, while standardized catalog enzymes compete on volume scale. Pricing stratifies across premium, standard, and economy tiers based on certification grade and customization level. Cost compression in lipid nanoparticle manufacturing is intensifying as CDMO capacity expands. Academic research institutes exhibit highest price sensitivity, while pharmaceutical developers absorb premiums for regulatory-compliant documentation.
Supply Chain Analysis
Contract manufacturing concentration sits with Lonza, Catalent, and Thermo Fisher Scientific for GMP cell processing and viral vector production. Supply draws from United States, Germany, and China for specialized enzymes, synthetic guide RNAs, and lipid derivatives. Single-source vulnerability runs through engineered nuclease patents held by academic licensors. Distribution runs through direct sales forces for pharmaceutical accounts and distributor networks for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Base editing represents a high-growth disruption as FDA regenerative medicine advanced therapy designations compress traditional phase transitions from years to months. This regulatory inflection creates asymmetric opportunity for platform-integrated developers.
For Market Incumbents: Harden intellectual property positions around prime editing architectures before patent cliffs erode first-mover advantages. Lock in exclusive lipid nanoparticle manufacturing capacity through multi-year offtake agreements with CDMOs. Beam Therapeutics and Intellia Therapeutics face emerging competition from venture-backed delivery technology platforms. For New Entrants and Emerging Players: Build out RNA base editing capabilities for transient transcript modification applications where permanent genomic alteration triggers regulatory friction. India's CDSCO streamlined pathways offer the most penetrable geography for outsourced preclinical validation. Partner with academic medical centers in Boston or London for first-in-human study execution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract research organizations possessing electroporation and cell processing infrastructure. Long-term viability hinges on therapeutic developers achieving regulatory approval for in vivo liver-targeted applications. Watch for FDA breakthrough therapy designation announcements as inflection indicators for platform validation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses development timelines for sickle cell programs. |
| Manufacturing Scale-Up | Lipid nanoparticle capacity expansion in Massachusetts and California anchors non-viral delivery supply security. |
| Pipeline Diversification | Prime editing integration enables complex genomic corrections beyond single-nucleotide transition limitations. |
| Licensing Agreement | Non-exclusive academic patent access from Broad Institute de-risks therapeutic development for emerging platforms. |
| Clinical Trial Advancement | Academic medical center partnerships in London and Boston accelerate first-in-human base editing study initiation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and GMP manufacturing specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and SEC 10-K disclosures. Bottom-up therapeutic pipeline enumeration triangulated against top-down market sizing from reagent supplier revenue segmentation.
Calibration against historical approval timelines and reimbursement precedent shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled include product type, therapeutic application, delivery technology, and regional regulatory cluster. CAGRs derived from patent expiry curves, clinical trial initiation rates, and manufacturing capacity build-out schedules. Off-target liability exposure and germline editing prohibition enforcement patterns served as scenario-weighting inputs.
Practitioners should monitor regulatory guidance evolution on in vivo editing thresholds and cross-border material transfer restrictions for early signals of forecast revision. Quarterly review of FDA breakthrough therapy designation grants and EMA priority medicines scheme admissions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.