
 Global Gene Expression Market | 2026-2036
Global Gene Expression Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gene Expression Market Foresight
Modular assay bundling is realigning how pharmaceutical buyers configure gene expression workflows. Illumina leverages its integrated sequencing-to-analysis ecosystem to sustain platform loyalty across high-throughput installations. Thermo Fisher Scientific anchors its position through captive supply of reagents, instruments, and cloud analytics. Oxford Nanopore Technologies differentiates via real-time, portable RNA sequencing that competes with centralized lab models.
Gene expression denotes the measurement of RNA transcript abundance, splicing variants, and regulatory dynamics through techniques such as quantitative reverse transcription PCR, hybridization-based microarrays, and massively parallel sequencing, serving primarily to decode cellular states for therapeutic target validation and diagnostic stratification. RNA sequencing occupies the fastest-expanding product tier as declining per-run costs displace microarray workflows in translational research. Among applications, biomarker identification commands premium pricing due to regulatory validation requirements, while drug discovery sustains the largest absolute spend pool across pharmaceutical end users.
The FDA governs gene expression-based companion diagnostics through premarket approval pathways, while the EMA's In Vitro Diagnostic Regulation imposes clinical evidence standards that reshape European product development timelines. China's NMPA accelerates review channels for innovative molecular diagnostics, altering market access sequencing for multinationals. Stakeholders must monitor evolving reimbursement frameworks for transcriptomic tests as payers tighten evidence requirements for coverage decisions.
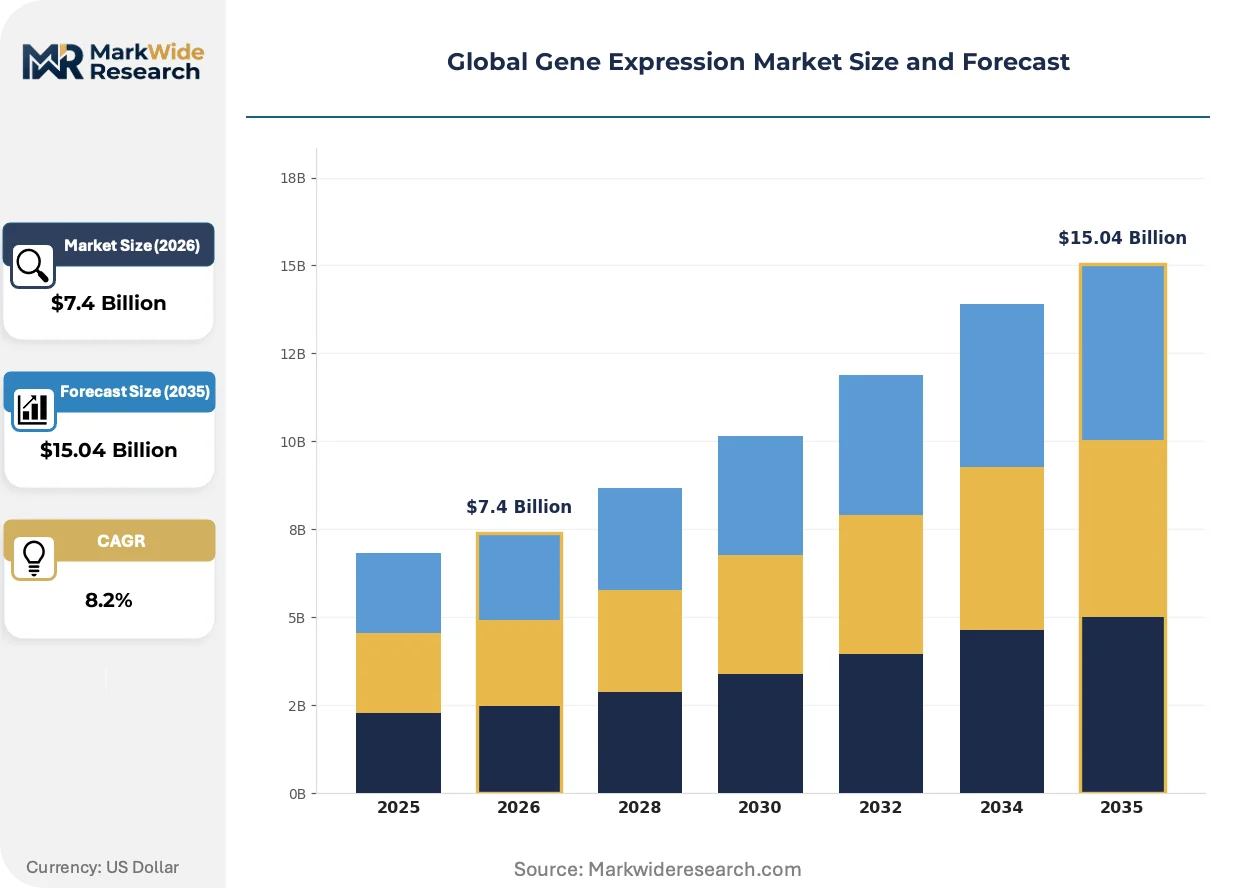
Market Dynamics
Cloud-based delivery architectures and ISO 13485 quality benchmarks are reshaping procurement criteria for research-grade gene expression platforms, compressing vendor qualification cycles while elevating compliance thresholds.
Growth Catalysts
- Companion diagnostic pipelines:Pharmaceutical manufacturers are embedding transcriptomic profiling into precision medicine workflows, expanding contract volumes for validated assay providers.
- NMPA accelerated review channels:China's streamlined molecular diagnostic approvals are shortening market access timelines for multinationals targeting the country's sequencing infrastructure expansion.
- Per-run cost compression in RNA sequencing:Declining reagent and instrument costs are displacing microarray workflows in translational research settings.
Market Restraints
- Reagent supply concentration:Captive supply chains controlled by dominant platform vendors create switching friction for research institutions.
- EMA In Vitro Diagnostic Regulation:Clinical evidence standards are extending European product development timelines and elevating validation costs.
- Specialized bioinformatics talent scarcity:Shortfalls in computational biology expertise constrain deployment of complex sequencing-to-analysis pipelines.
Strategic Opportunities
- Point-of-care transcriptomics:Portable RNA sequencing formats are creating white space outside centralized laboratory models, particularly in Germany's distributed hospital networks.
- Biomarker identification services:Regulatory validation requirements for companion diagnostics command premium pricing tiers with extended contract durations.
- Convergence of artificial intelligence with expression analysis:Machine learning tools for variant interpretation are opening new service revenue streams for platform vendors.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation for research-grade platforms demands 12-18 month validation cycles.
- Legacy data format integration:Proprietary file structures from established microarray systems complicate migration to sequencing-based workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gene Expression Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.04 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microarrays, Real-Time PCR, RNA Sequencing, Northern Blotting, Gene Chips Application: Drug Discovery, Disease Diagnosis, Functional Genomics, Biomarker Identification, Toxicology Studies End User: Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Academic Laboratories, Contract Research Organizations Delivery Mode: Online Platforms, Cloud-Based Solutions, On-Premise Software, SaaS Models, Hybrid Systems |
| Companies Covered | Oxford Nanopore Technologies, Ginkgo Bioworks, Illumina, Lonza Group, Agilent Technologies, Thermo Fisher Scientific, Twist Bioscience, WuXi AppTec, 10x Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gene Expression Market Shifts & Advancements
Real-time analytical capabilities and modular assay architectures are compressing the interval between sample processing and actionable insight, altering competitive differentiation criteria for platform vendors.
Single-cell RNA sequencing is electrifying the resolution standards for cellular heterogeneity analysis. Academic medical centers and pharmaceutical translational groups are adopting droplet-based partitioning methods at accelerating velocity. This capability is compressing the timeline between tissue sampling and therapeutic target identification, compressing traditional bulk-expression workflows into niche retrospective applications.
REACH regulation evolution in the European Union is tightening chemical substance tracking requirements for reagent manufacturing. Suppliers must now document full material composition across oligonucleotide synthesis chains, elevating compliance costs for non-integrated vendors. German and Swiss reagent producers are responding by consolidating backward into controlled supply chains.
Research consortia are consolidating purchasing authority through shared-service agreements that unbundle instrument acquisition from consumable supply contracts. University medical centers in the United States are leading this restructuring, replacing individual laboratory procurement with centralized core facility governance. This concentration is visible most acutely in Boston and San Francisco metropolitan research clusters.
Global Gene Expression Market Segmentation
Gene expression workflows fragment across distinct technology tiers, each carrying different capital intensity and bioinformatics requirements. Pharmaceutical procurement teams now unbundle instrument acquisition from consumable supply, reshaping how vendors capture lifetime value across these categories.
Product Type:
Replacement cycles accelerate as declining per-run costs in sequencing displace legacy hybridization platforms.
- RNA Sequencing:Massively parallel sequencing of transcriptomes delivers base-level resolution of splice variants and fusion transcripts. Demand concentrates in pharmaceutical translational groups validating companion diagnostic targets, driven by FDA premarket approval pathways that require sequencing-grade evidence.
- Real-Time PCR:Quantitative reverse transcription PCR quantifies transcript abundance through fluorescent probe detection with rapid turnaround. Academic laboratories in Germany and China deploy these systems for targeted validation studies, constrained by reagent supply concentration among dominant platform vendors.
- Microarrays:Hybridization-based profiling of predefined transcript sets retains niche use for retrospective cohort studies with legacy sample banks.
- Northern Blotting:Membrane-based RNA detection persists in educational settings and confirmatory workflows requiring transcript size verification.
- Gene Chips:Affymetrix-style oligonucleotide arrays serve regulated environments where assay standardization trumps discovery flexibility.
Volume placements concentrate in Real-Time PCR; the faster expansion belongs to RNA Sequencing.
Application:
Pricing stratifies according to regulatory validation burden and contract duration.
- Biomarker Identification:Discovery and validation of transcriptomic signatures for patient stratification commands premium service tiers due to companion diagnostic evidentiary requirements. Pharmaceutical sponsors in the United States and Switzerland fund multi-year programs spanning discovery through regulatory submission.
- Drug Discovery:Transcriptomic profiling for target validation and mechanism-of-action studies absorbs the largest absolute spend pool across pharmaceutical end users. China's NMPA accelerated review channels compress timelines for multinationals embedding expression analysis into precision medicine pipelines.
- Disease Diagnosis:Clinical transcriptomic testing for infectious and oncologic indications faces tightening payer evidence requirements.
- Functional Genomics:Pathway analysis and gene regulation studies concentrate in academic consortia with shared-service procurement models.
- Toxicology Studies:Compound safety profiling through transcriptomic response monitoring supports regulatory submission packages.
Contract values peak in Biomarker Identification; Drug Discovery sustains the broadest installation base.
End User:
Procurement authority is migrating from individual laboratories toward centralized core facility governance.
- Pharmaceutical Companies:Integrated drug developers deploy expression platforms across discovery, translational, and clinical stages with validated assay requirements. Boston and San Francisco metropolitan clusters host the densest concentrations of sequencing infrastructure and biopharma R&D investment.
- Contract Research Organizations:Outsourced service providers manage variable throughput demands for sponsor programs, capturing volume through ISO 13485-certified quality management systems that demand 12-18 month validation cycles.
- Research Institutes:Government-funded genomic centers consolidate purchasing through shared-service agreements unbundling instruments from consumables.
- Biotechnology Firms:Venture-backed developers prioritize flexible SaaS analytics over capital-intensive on-premise installations.
- Academic Laboratories:Individual investigator grants increasingly access centralized core facilities rather than direct instrument ownership.
Platform loyalty runs deepest in Pharmaceutical Companies; CROs are gaining share fastest through sponsor outsourcing trends.
Delivery Mode:
Cloud migration compresses vendor qualification cycles while elevating compliance thresholds for research-grade deployments.
- Cloud-Based Solutions:Remote computational infrastructure for sequence alignment and variant interpretation eliminates local server capital expenditure. German distributed hospital networks and United States academic medical centers adopt these architectures to pool bioinformatics expertise scarce across individual sites.
- SaaS Models:Subscription-based analytics platforms deliver automated pipelines for standard expression workflows with predictable operational expenditure profiles.
- Hybrid Systems:Split architectures process sensitive primary data on-premise while pushing anonymized analyses to cloud tiers navigate institutional data governance requirements.
- On-Premise Software:Locally installed analysis suites persist in environments with stringent data residency mandates or proprietary algorithm requirements.
- Online Platforms:Browser-based portals for result visualization and collaboration serve distributed research teams with limited computational needs.
Deployment scale favors Cloud-Based Solutions; Hybrid Systems are climbing the fastest as data sovereignty concerns persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sequencing infrastructure concentrates in countries with dense biopharma R&D investment, while consumption spreads through distributed hospital networks and academic consortia. Platform vendors face divergent regulatory timelines across FDA, EMA, and NMPA jurisdictions. Procurement authority migrates toward centralized core facilities in metropolitan research clusters.
United States
Pharmaceutical manufacturers embed transcriptomic profiling into precision medicine pipelines across Boston and San Francisco metropolitan clusters. FDA premarket approval pathways for companion diagnostics command sequencing-grade evidentiary standards. Research consortia in these coastal hubs consolidate purchasing through shared-service agreements unbundling instruments from consumables.
Germany
Distributed hospital networks adopt portable RNA sequencing formats outside centralized laboratory models. EMA In Vitro Diagnostic Regulation imposes clinical evidence standards that reshape European product development timelines. Baden-Württemberg and Bavaria host dense concentrations of ISO 13485-certified reagent producers consolidating backward into controlled supply chains.
China
NMPA accelerated review channels shorten market access timelines for multinationals targeting sequencing infrastructure expansion. The country's national pharmaceutical regulator streamlines molecular diagnostic approvals for innovative transcriptomic platforms. Yangtze River Delta biopharma zones absorb the largest absolute instrument placements for translational research.
Switzerland
Pharmaceutical sponsors fund multi-year biomarker identification programs spanning discovery through regulatory submission. Swissmedic maintains stringent quality benchmarks for research-grade platform procurement. Basel and Zurich anchor contract volumes for validated assay providers serving integrated drug developers.
United Kingdom
Academic medical centers adopt cloud-based delivery architectures to pool scarce bioinformatics expertise across individual sites. MHRA alignment with EMA standards extends validation requirements for expression-based diagnostics. London and Cambridge genomic centers lead shared-service procurement restructuring among university research clusters.
Global Gene Expression Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument, reagent, and analytics tiers. Market structure consolidates around integrated sequencing-to-analysis ecosystems and captive supply chains. Strategic archetypes include platform-locked instrument vendors, modular assay bundlers, and SaaS analytics providers. Dominant competitive moves encompass backward integration into controlled reagent supply and geographic expansion through ISO 13485-certified quality management systems.
Within the integrated platform tier, Illumina and Thermo Fisher Scientific exemplify divergent approaches to ecosystem lock-in. Oxford Nanopore Technologies occupies a position representing portable, real-time sequencing formats that challenge centralized laboratory models. These three anchors illustrate how vendor qualification cycles compress while compliance thresholds elevate across cloud-based and on-premise deployments.
| Leading Market Players |
|---|
| Oxford Nanopore Technologies |
| Ginkgo Bioworks |
| Illumina |
| Lonza Group |
| Agilent Technologies |
| Thermo Fisher Scientific |
| Twist Bioscience |
| WuXi AppTec |
| 10x Genomics |
| Others |
Supply & Pricing Matrix
Bioinformatics specialist scarcity in Germany and Switzerland widens labor-cost differentials between centralized sequencing hubs and distributed laboratory networks, compressing pricing-tier spreads for cloud-based analytics versus on-premise installations.
Pricing Analysis
Price erosion across RNA sequencing consumables traces to per-run cost compression as reagent manufacturers scale oligonucleotide synthesis operations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated companion diagnostic assays from research-grade exploratory panels and educational reagent kits. ISO 13485 certification tiers command 15-40% premiums over uncertified alternatives. Academic laboratories in China exhibit highest price sensitivity; pharmaceutical sponsors in Switzerland show lowest elasticity due to regulatory validation requirements.
Supply Chain Analysis
Instrument refurbishment flows from United States academic medical centers to secondary markets in India and Brazil extend equipment lifecycles while creating reverse-logistics revenue streams for original manufacturers. Reagent supply concentrates in Germany, Switzerland, and China as dominant platform vendors maintain captive oligonucleotide synthesis chains. Critical dependencies include fluorophore-labeled probes, modified nucleotides, and sequencing flow cells. Single-source vulnerability persists for nanopore membrane substrates. Distribution runs through ISO-certified distributors to pharmaceutical procurement teams and shared-service core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EMA In Vitro Diagnostic Regulation creates 12-18 month validation moats that protect ISO 13485-certified incumbents from price-based competition.
For Market Incumbents: Deploy backward integration into controlled reagent supply chains to neutralize switching friction from captive consumable dependencies. Oxford Nanopore Technologies' portable sequencing formats threaten centralized laboratory models; defend through hybrid cloud-on-premise architectures that address data sovereignty concerns in German hospital networks.
For New Entrants and Emerging Players: Enter via point-of-care transcriptomics white space in Germany's distributed hospital networks, where real-time RNA sequencing escapes incumbent platform lock-in. Target biomarker identification services for mid-tier pharmaceutical sponsors seeking alternatives to Illumina-Thermo Fisher ecosystems. Lead with AI-augmented variant interpretation SaaS to bypass capital-intensive instrument manufacturing.
For Investors and Strategic Acquirers: Re-rating potential sits with ISO 13485-certified CROs serving companion diagnostic pipelines given NMPA accelerated review channel expansion in China. Long-term viability hinges on regulatory validation asset durability rather than sequencing technology cycles. Monitor FDA premarket approval pathway backlogs as inflection signal for biomarker identification service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management system validation opens pharmaceutical sponsor contracts and compresses vendor qualification cycles. |
| Backward Integration into Reagent Supply | Captive oligonucleotide synthesis chains neutralize switching friction and protect margin structure. |
| AI-Variant Interpretation Platform Launch | Machine learning tools for transcriptomic analysis create SaaS revenue streams outside instrument hardware. |
| Point-of-Care Sequencing Format Development | Portable RNA sequencing challenges centralized laboratory models in German distributed hospital networks. |
| Cloud-Based Analytics Partnership | Remote computational infrastructure pools scarce bioinformatics expertise across United States academic centers. |
Research Methodology
Multi-period observation of NMPA approval velocities, EMA validation timelines, and per-run sequencing cost trajectories anchored the trend analysis, supplemented by interviews with pharmaceutical development executives, regulatory affairs leads, hospital procurement managers, and cloud platform engineers. Secondary validation drew from FDA premarket approval filings, EMA In Vitro Diagnostic Regulation guidance documents, ClinicalTrials.gov transcriptomic biomarker entries, and ISO 13485 certification registries. Bottom-up instrument placement counts triangulated against top-down pharmaceutical R&D expenditure allocations.
Segment-weighting across product type, application, end user, and delivery mode dimensions structured the analytical framework across the analysis window. CAGRs derived from regression against sequencing infrastructure expansion rates, biopharma precision medicine pipeline counts, and cloud analytics adoption curves. Forecast inputs incorporated NMPA review channel throughput assumptions and REACH regulation compliance cost escalations for European reagent manufacturing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA companion diagnostic evidentiary requirement shifts or EMA MDR implementation delays. Practitioners should monitor NMPA accelerated review channel capacity expansion and single-cell RNA sequencing patent litigation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Whole Plasmid Sequencing Market
Genomics
Animal Genetics Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Genomics Personalized Health Market
Genomics
Nutrigenomics Testing Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
Short-Read Sequencing Market
Genomics
Genomics and Transcriptomics Market
Genomics
Europe Genetic Testing Market
Genomics
NGS Automation Market
Genomics
Alagille Syndrome Market
Genomics
Europe DNA Sequencing Products Market
Genomics
Tumor-Sequencing Blood Testing Market