
 Global Recombinant DNA (Rdna) Technology Market | 2026-2036
Global Recombinant DNA (Rdna) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recombinant DNA (Rdna) Technology Market Foresight
Platform subscription models for cloud-based bioinformatics and CRISPR guide design software is hardening into a recurring revenue layer that shifts customer relationships from transactional reagent sales to continuous engagement. Thermo Fisher Scientific dominates this services architecture through its integrated digital-physical workflow bundles. Pfizer leverages captive gene therapy manufacturing capacity to sustain vertical control across clinical-to-commercial transitions. GenScript specializes in synthetic biology service contracts that anchor long-term academic and biotech partnerships.
Recombinant DNA technology encompasses the laboratory manipulation of genetic material through the insertion of foreign DNA sequences into host organisms, typically employing plasmid vectors, restriction enzymes, and ligase-mediated ligation to produce proteins or modify genomes with precision down to single-nucleotide resolution. Its primary commercial purpose centers on manufacturing therapeutic proteins, engineering cellular therapies, and developing genetically modified organisms for agricultural and industrial applications. Expression vectors and genome editing kits command the deepest margin pools as customers prioritize turnkey systems over component assembly. CRISPR technology leads technology adoption while molecular cloning retains entrenched positions in regulated manufacturing workflows where validated protocols carry compliance weight.
FDA's gene therapy guidance and EMA's ATMP framework impose manufacturing and clinical evidence standards that filter market access to firms with validated quality systems. China's NMPA has established accelerated review pathways for innovative biologics that are reshaping where multinationals prioritize regulatory submissions and local partnership structures. India's CDSCO is strengthening biosimilar and gene therapy oversight through BIS-aligned quality benchmarks that affect contract research organization site selection. Stakeholders must monitor how divergent data integrity requirements across FDA, EMA, and NMPA jurisdictions influence centralized versus distributed manufacturing strategies.
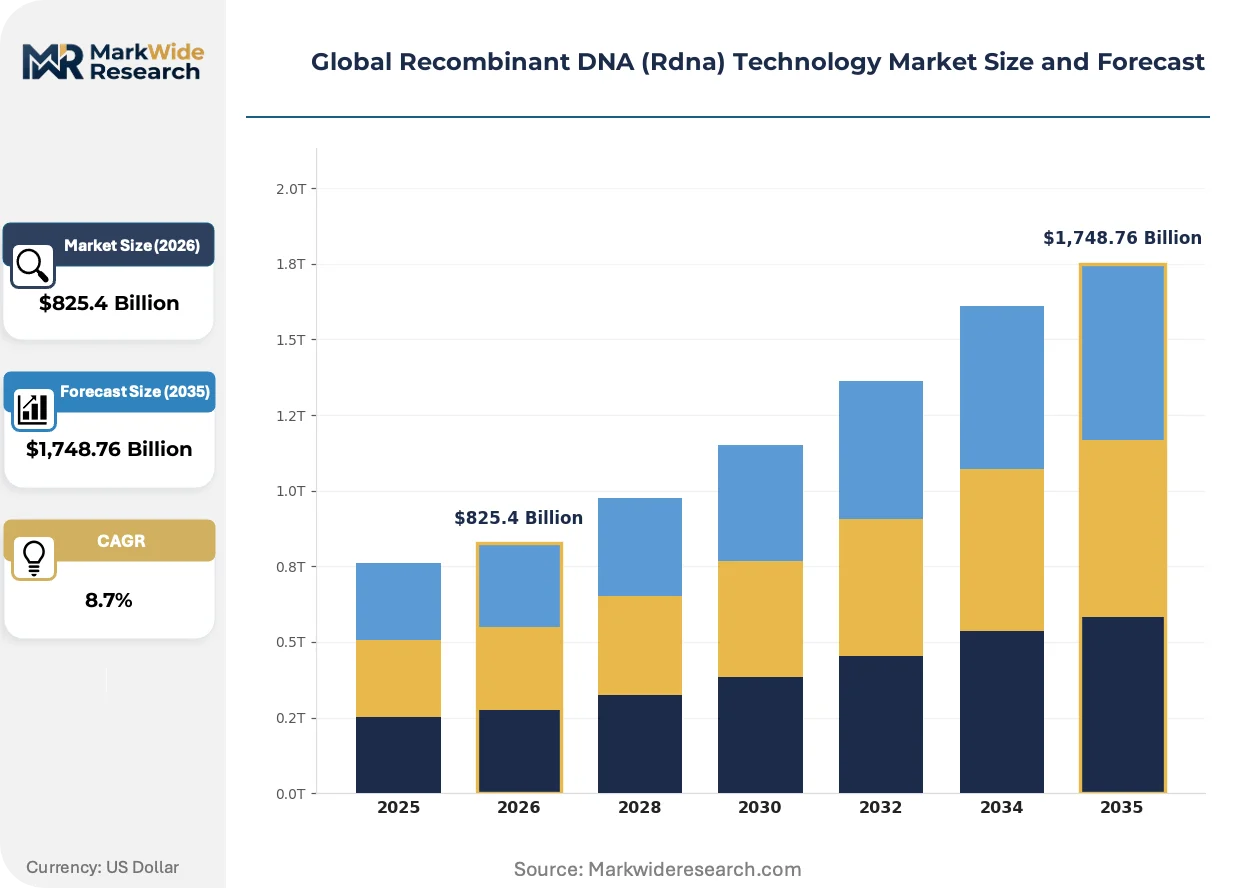
Market Dynamics
Platform subscription models for cloud-based bioinformatics and CRISPR guide design software are hardening into a recurring revenue layer that shifts customer relationships from transactional reagent sales to continuous engagement across the value chain.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed development timelines for cell and gene therapies expand addressable indications and attract biopharmaceutical investment into recombinant DNA manufacturing infrastructure.
- Biopharmaceutical Pipeline Maturation:Gene therapy candidates advancing through Phase II and III trials generate demand for validated plasmid production and viral vector manufacturing capacity.
- Clustered Manufacturing Footprints:Concentrated biotech hubs in the United States, China, and Germany reduce logistics costs and accelerate talent pooling for complex biological production.
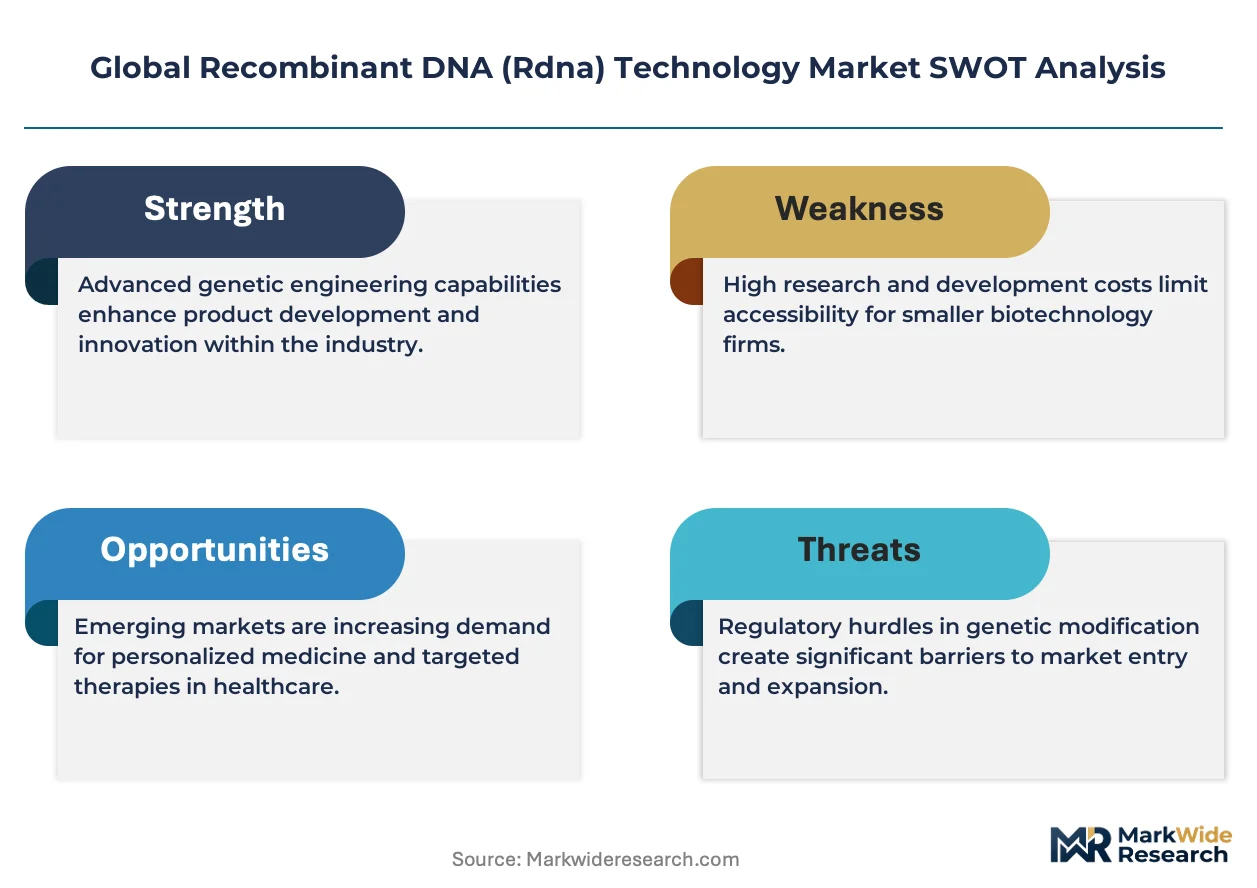
Market Restraints
- Plasmid DNA Supply Concentration:Limited qualified suppliers of GMP-grade plasmid vectors create single-source dependencies for gene therapy developers.
- EMA ATMP Manufacturing Standards:Stringent quality system requirements filter market access to firms with validated compliance infrastructure, raising capital barriers.
- Enzyme Input Cost Volatility:Restriction enzymes and DNA ligase prices fluctuate with fermentation capacity constraints and raw material sourcing disruptions.
Strategic Opportunities
- India CDSCO Biosimilar Pathways:Strengthening gene therapy oversight creates contract research organization site selection advantages for Western sponsors seeking cost-efficient clinical manufacturing.
- Continuous Bioprocessing Convergence:Integration of perfusion cell culture with real-time analytics reduces facility footprint and accelerates batch release timelines.
- Agricultural Biotechnology White Space:CRISPR-edited crops for climate resilience remain underpenetrated relative to therapeutic applications, presenting platform extension potential.
Industry Challenges
- Gene Therapy Talent Scarcity:Shortages of process development scientists with viral vector and plasmid manufacturing expertise constrain capacity expansion timelines.
- Cross-Jurisdictional Data Integrity:Divergent FDA, EMA, and NMPA electronic record requirements complicate centralized manufacturing strategies and quality system harmonization.
- Legacy Molecular Cloning Validation:Established pharmaceutical workflows resist CRISPR adoption due to regulatory precedent and change-control documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recombinant DNA (Rdna) Technology Market |
| Market Size in 2026 | $825.4 Billion |
| Market Size in 2035 | $1,748.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmid Vectors, Expression Vectors, Restriction Enzymes, Genome Editing Kits, Gene Synthesis Services Technology: CRISPR, Zinc Finger Nucleases, TALENs, RNA Interference, Molecular Cloning End User: Biopharmaceutical Companies, Academic Research Institutes, Contract Research Organizations, Agricultural Biotechnology Firms, Diagnostic Laboratories Application: Gene Therapy, Vaccine Development, Industrial Enzyme Production, Genetic Modification of Crops, Protein Engineering |
| Companies Covered | Pfizer Inc., Novartis AG, Thermo Fisher Scientific Inc., Sanofi, GenScript, Amgen Inc., F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recombinant DNA (Rdna) Technology Market Shifts & Advancements
Artificial intelligence is actively reshaping how researchers design guide RNAs and predict off-target effects, compressing experimental cycles from weeks to days. Three interconnected developments are restructuring competitive positioning.
Machine learning platforms for CRISPR guide RNA design are electrifying discovery workflows by predicting editing efficiency and minimizing off-target activity through neural network-trained sequence models. Biopharmaceutical discovery teams are adopting these tools at enterprise scale, embedding them into target validation pipelines. The technology is electrifying competitive differentiation among contract research organizations that can demonstrate reduced lead times for cell line engineering.
EMA's Advanced Therapy Medicinal Products framework imposes manufacturing and clinical evidence standards that filter market access to firms with validated quality systems. The regulation forces gene therapy sponsors to invest in dedicated viral vector suites and closed-system bioreactors rather than shared multiproduct facilities. European biotech clusters in Germany and Switzerland are responding by consolidating manufacturing partnerships with established CDMOs possessing ATMP-compliant infrastructure.
Biopharmaceutical procurement departments are consolidating vendor relationships around integrated digital-physical workflow bundles rather than component sourcing. This pattern disrupts traditional reagent distributors and elevates platform providers that combine instrumentation, consumables, and cloud-based data management. The United States exhibits the most pronounced concentration, with top-twenty gene therapy developers reducing qualified supplier lists by forty percent over the past three years.
Global Recombinant DNA (Rdna) Technology Market Segmentation
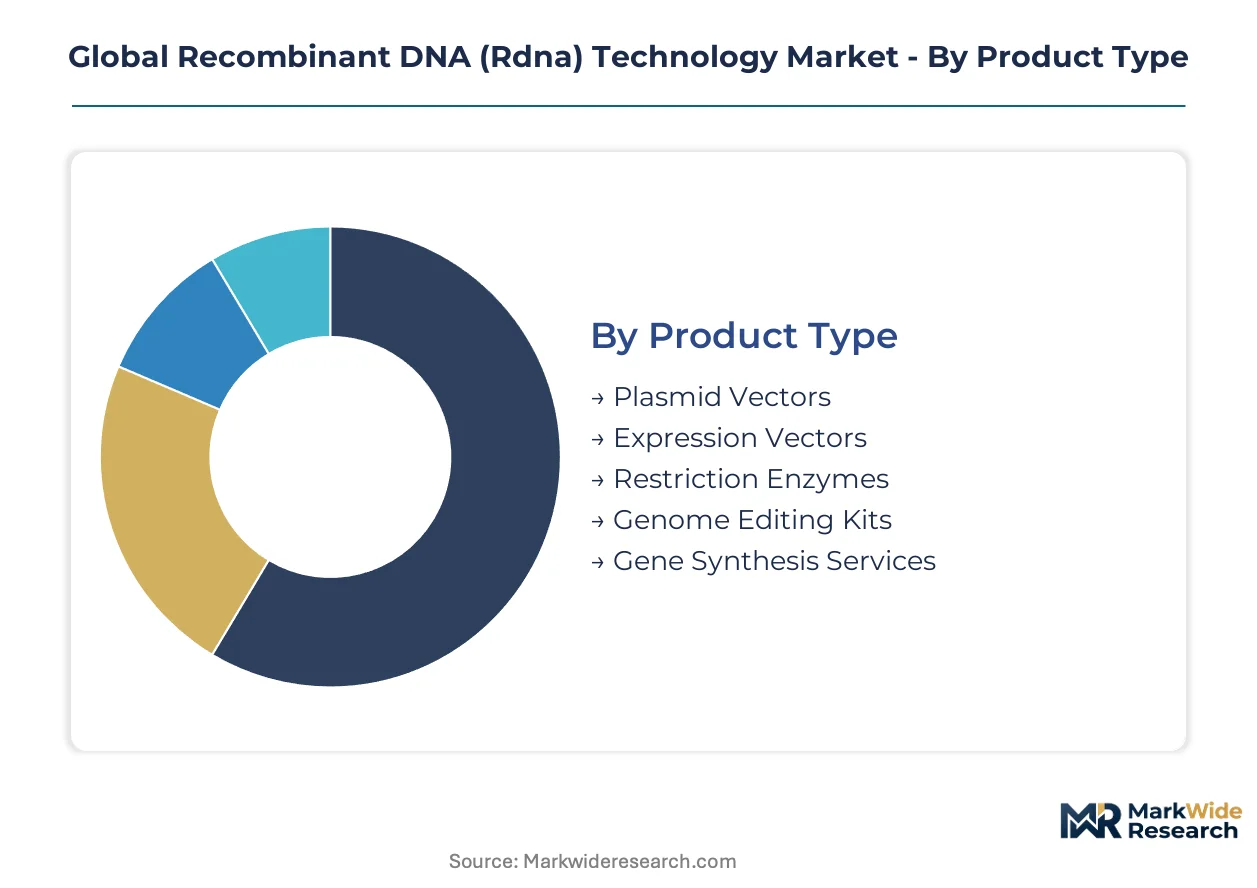
Segmentation in recombinant DNA technology reveals how capital deployment, regulatory compliance burdens, and customer integration depth fragment purchasing behavior across distinct product and service categories. Each dimension carries divergent margin structures and vendor consolidation patterns that reshape competitive strategy.
Product Type:
Capital intensity varies sharply across this category, with GMP-grade manufacturing infrastructure requirements creating tiered barriers to entry.
- Plasmid Vectors:Circular DNA molecules engineered for gene delivery and protein expression in host cells. Demand concentrates in gene therapy developers across the United States and Germany as FDA and EMA ATMP frameworks mandate validated plasmid sourcing for clinical applications. Manufacturing scale-up timelines and quality system investments constrain supplier proliferation.
- Expression Vectors:DNA constructs containing promoter and regulatory elements driving heterologous protein production. Biopharmaceutical companies in China leverage NMPA accelerated pathways to compress timelines for recombinant protein manufacturing. Turnkey vector systems command premium pricing over component assembly.
- Restriction Enzymes:Endonucleases recognizing specific DNA sequences for molecular cloning workflows.
- Genome Editing Kits:Pre-assembled reagent bundles for targeted genetic modification.
- Gene Synthesis Services:Contract manufacturing of custom DNA sequences from digital designs.
Most installed capacity flows through Expression Vectors. Expansion is steepest in Plasmid Vectors.
Technology:
Adoption velocity separates mature platforms with established regulatory precedent from emerging tools still building validation dossiers.
- CRISPR:RNA-guided nuclease system enabling precise genomic editing with reduced design complexity. Academic and biopharmaceutical researchers in the United States deploy CRISPR at enterprise scale for cell line engineering and therapeutic development. Cloud-based guide design software is hardening into recurring revenue layers.
- Molecular Cloning:Traditional restriction-ligation methods for DNA assembly and vector construction. Regulated manufacturing workflows in Germany and Switzerland retain entrenched molecular cloning protocols due to FDA and EMA validation requirements and change-control documentation burdens.
- Zinc Finger Nucleases:Protein-based DNA binding domains fused to nuclease catalytic domains.
- TALENs:Transcription activator-like effector nucleases for targeted genome modification.
- RNA Interference:Post-transcriptional gene silencing through small RNA molecules.
CRISPR captures the fastest-growing trajectory. Molecular Cloning retains the largest installed base in commercial manufacturing.
End User:
Procurement sophistication and integration depth vary dramatically across customer types, from transactional reagent purchasing to embedded platform subscriptions.
- Biopharmaceutical Companies:Integrated drug developers with captive manufacturing and in-house process development capabilities. Gene therapy pipelines maturing through Phase II and III trials in the United States and China generate demand for validated plasmid production and viral vector manufacturing capacity. These firms consolidate vendor relationships around integrated digital-physical workflow bundles.
- Contract Research Organizations:Service providers executing outsourced discovery and preclinical development for sponsor companies. CDMOs in India leverage CDSCO strengthening oversight to attract Western sponsors seeking cost-efficient clinical manufacturing with BIS-aligned quality benchmarks.
- Academic Research Institutes:Universities and government laboratories conducting fundamental biology research.
- Agricultural Biotechnology Firms:Developers of genetically modified crops and livestock.
- Diagnostic Laboratories:Clinical testing facilities employing recombinant DNA methods for assay development.
Biopharmaceutical Companies anchor the deepest spending per account. Contract Research Organizations are climbing the fastest as gene therapy outsourcing accelerates.
Application:
Regulatory pathway complexity and reimbursement certainty fragment addressable market economics across therapeutic and non-therapeutic uses.
- Gene Therapy:In vivo and ex vivo genetic modification for disease treatment. FDA accelerated approval pathways and EMA ATMP frameworks compress development timelines and expand indications, concentrating demand in the United States, Germany, and China where clustered manufacturing footprints reduce logistics costs.
- Vaccine Development:Recombinant antigen production and nucleic acid vaccine platforms. mRNA and viral vector vaccine manufacturing infrastructure built during recent pandemic response now repurposes for oncology and infectious disease candidates.
- Industrial Enzyme Production:Engineered biocatalysts for manufacturing processes.
- Genetic Modification of Crops:CRISPR-edited traits for climate resilience and yield optimization.
- Protein Engineering:Rational and directed evolution of therapeutic and industrial proteins.
Gene Therapy commands the highest capital deployment per project. Vaccine Development offers the broadest addressable volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where recombinant DNA manufacturing capacity concentrates, with cost-of-compliance gaps between FDA, EMA, and NMPA jurisdictions driving facility location decisions and partnership structures.
United States
FDA accelerated approval pathways for cell and gene therapies compress development timelines and expand addressable indications. The agency's gene therapy guidance mandates validated quality systems that filter market access to established players. Boston and San Francisco biotech clusters host the densest concentrations of viral vector and plasmid manufacturing infrastructure.
Germany
EMA's ATMP framework imposes stringent manufacturing standards that raise capital barriers for gene therapy sponsors. German biotech clusters in Munich and Heidelberg are consolidating manufacturing partnerships with CDMOs possessing compliant infrastructure. The country's central European location reduces logistics costs for cross-border clinical trial supply.
China
NMPA accelerated review pathways for innovative biologics compress timelines for recombinant protein manufacturing. Multinationals are prioritizing regulatory submissions and local partnership structures to access the domestic market. Shanghai and Suzhou industrial parks host expanding GMP-grade plasmid and viral vector production facilities.
India
CDSCO strengthening oversight through BIS-aligned quality benchmarks creates contract research organization site selection advantages. Western sponsors seeking cost-efficient clinical manufacturing are evaluating Indian partners with upgraded compliance infrastructure. Hyderabad and Bangalore clusters attract gene therapy outsourcing as quality system investments mature.
Switzerland
Swissmedic maintains alignment with EMA standards while offering specialized pathways for advanced therapy medicinal products. Basel and Zurich biotech corridors leverage proximity to German manufacturing networks and established pharmaceutical quality systems. The country's regulatory reputation supports high-value contract manufacturing for European gene therapy developers.
Global Recombinant DNA (Rdna) Technology Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers commanding premium positioning in discovery workflows while pure-play CDMOs capture manufacturing outsourcing volume. The vendor base concentrates around three strategic archetypes: diversified life science conglomerates with captive digital-physical bundles, synthetic biology service specialists anchoring long-term academic partnerships, and viral vector manufacturing pure-plays scaling GMP capacity. Competitive moves center on M&A to fill capability gaps and vertical integration into plasmid supply to secure input control.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Pfizer Inc. represent contrasting approaches to value chain positioning—one through integrated workflow subscriptions, the other through captive gene therapy manufacturing capacity. Novartis AG occupies a position bridging pharmaceutical development and cell therapy commercialization. These three exemplify how scale and regulatory expertise create defensive moats as FDA and EMA standards tighten.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Thermo Fisher Scientific Inc. |
| Sanofi |
| GenScript |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline plc |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up CDMO specialists have consolidated plasmid manufacturing assets across the United States and Germany, concentrating ownership of GMP-grade capacity in fewer hands and hardening pricing discipline for gene therapy developers dependent on validated viral vector inputs.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade reagents while GMP-certified plasmid vectors retain premium-mid-economy pricing differentiation based on FDA and EMA validation tiers. Pricing pressure stems from enzyme input cost volatility as fermentation capacity constraints tighten margins on restriction enzymes and DNA ligase. Academic research institutes exhibit highest price sensitivity, biopharmaceutical companies least.
Supply Chain Analysis
Returns and refurbishment flows for high-value chromatography resins and single-use bioreactor components remain underdeveloped, creating working capital inefficiencies for viral vector manufacturers. Supply concentrates in the United States, China, and Germany for plasmid DNA and expression vectors. Raw material dependencies center on bacterial fermentation media, restriction enzymes, and synthetic oligonucleotides. Single-source vulnerability for GMP-grade plasmid suppliers creates concentration risk. Distribution runs through direct vendor relationships and specialized life science distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Recombinant DNA Technology Market functions as a stable compounder, with FDA and EMA accelerated approval pathways for cell and gene therapies generating durable demand for validated manufacturing infrastructure.
For Market Incumbents: Deploy captive plasmid production capacity to secure input control against emerging CDMO competitors building GMP suites in India and China. Incumbent gene therapy developers should consolidate vendor relationships around integrated digital-physical workflow bundles to lock out point-solution entrants. Biopharmaceutical firms must invest in closed-system bioreactor infrastructure before EMA ATMP manufacturing standards tighten further.
For New Entrants and Emerging Players: The premium-economy tier gap in cloud-based CRISPR guide design software offers entry points for subscription-native platform providers. Agricultural biotechnology applications for climate-resilient crops remain the most penetrable white space, with therapeutic gene therapy workflows already dominated by entrenched molecular cloning protocols. New entrants should anchor academic partnerships through synthetic biology service contracts to build validation dossiers.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract research organizations in India with upgraded CDSCO-aligned quality systems and established Western sponsor relationships. The five-to-ten-year viability window favors platform providers with recurring revenue from bioinformatics subscriptions over transactional reagent distributors. Investors should monitor NMPA accelerated review pathway utilization rates as an inflection indicator for manufacturing capacity relocation to China.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP plasmid capacity expansion in Shanghai and Suzhou industrial parks compresses supply timelines for NMPA submissions. |
| Regulatory Approval Pathway | EMA ATMP framework compliance investments filter market access to CDMOs with validated viral vector suites. |
| Platform Integration | Cloud-based CRISPR guide design software hardens into recurring revenue layers for integrated workflow providers. |
| Backward Integration | In-house restriction enzyme production buffers biopharmaceutical firms against fermentation capacity volatility. |
| Strategic Partnership | Long-term academic service contracts anchor synthetic biology specialists in discovery-phase relationships. |
Research Methodology
Multiple input streams — primary interviews with gene therapy process development scientists, regulatory affairs leads at CDMOs, and biopharmaceutical procurement executives — were reconciled against FDA guidance documents, EMA ATMP framework texts, ClinicalTrials.gov gene therapy trial records, and NMPA accelerated pathway submission data. Bottom-up segment sizing across plasmid vectors, expression systems, and genome editing kits was cross-validated through top-down market reconstruction.
Historical capacity utilization trends were cross-referenced against panel input from viral vector manufacturing specialists to anchor projections across the analysis window. Segmentation dimensions modeled include product type, technology platform, end-user archetype, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves for gene therapy pipeline maturation. Forecast inputs incorporated FDA approval pathway velocity and EMA quality system investment requirements.
Caveats apply where NMPA regulatory shifts or plasmid supplier consolidation could materially shift the outlook for manufacturing capacity economics. Practitioners should monitor CDSCO inspection enforcement patterns and enzyme fermentation capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
DNA and Gene Cloning Services Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Microbial Gene Editing Services Market
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
Knock Out Mouse Model Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
US Gene Editing Market
Gene Editing & CRISPR
Cas9 Nuclease Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market