
 UK Gene Editing Market | 2026-2036
UK Gene Editing Market Size, Share, and Industry Trends Forecast 2026-2036
UK Gene Editing Market Insights
Biopharmaceutical companies is bifurcating demand away from pure academic contracting toward integrated therapeutic development partnerships. CRISPR Therapeutics AG leverages its vertical integration across discovery and clinical translation to anchor premium partnerships with UK-based innovators. Horizon Discovery competes through specialized cell line engineering services that sustain recurring revenue from contract research organizations. AstraZeneca dominates late-stage therapeutic applications by extending its Cambridge footprint into gene-edited oncology pipelines.
Gene editing encompasses programmable nuclease systems that introduce site-specific DNA modifications through engineered molecular complexes operating at precise chromosomal coordinates. CRISPR-Cas9 systems employ guide RNA-directed Cas endonuclease cleavage with protospacer adjacent motif recognition, enabling therapeutic gene knockout, correction, or insertion in living cells. Base Editors represent the fastest-growing product type as cytosine and adenine base conversion technologies eliminate double-strand break risks in clinical applications. Therapeutic Research captures the deepest margin pools among application segments due to milestone-driven licensing structures and royalty stacking on approved products. Lipid Nanoparticles lead delivery method adoption for in vivo liver-targeted editing, though Electroporation retains dominance in ex vivo hematopoietic cell modification protocols.
The Medicines and Healthcare products Regulatory Agency governs clinical gene editing trials through the advanced therapy medicinal product framework, while the Human Fertilisation and Embryology Authority restricts heritable germline applications. BSI Group administers ISO 13485 and quality management certifications that condition market access for commercial gene editing reagent suppliers. Stakeholders must monitor MHRA divergence from EMA alignment post-Brexit, as autonomous UK approval pathways could accelerate or fragment trial site selection across the Golden Triangle.
Market Dynamics
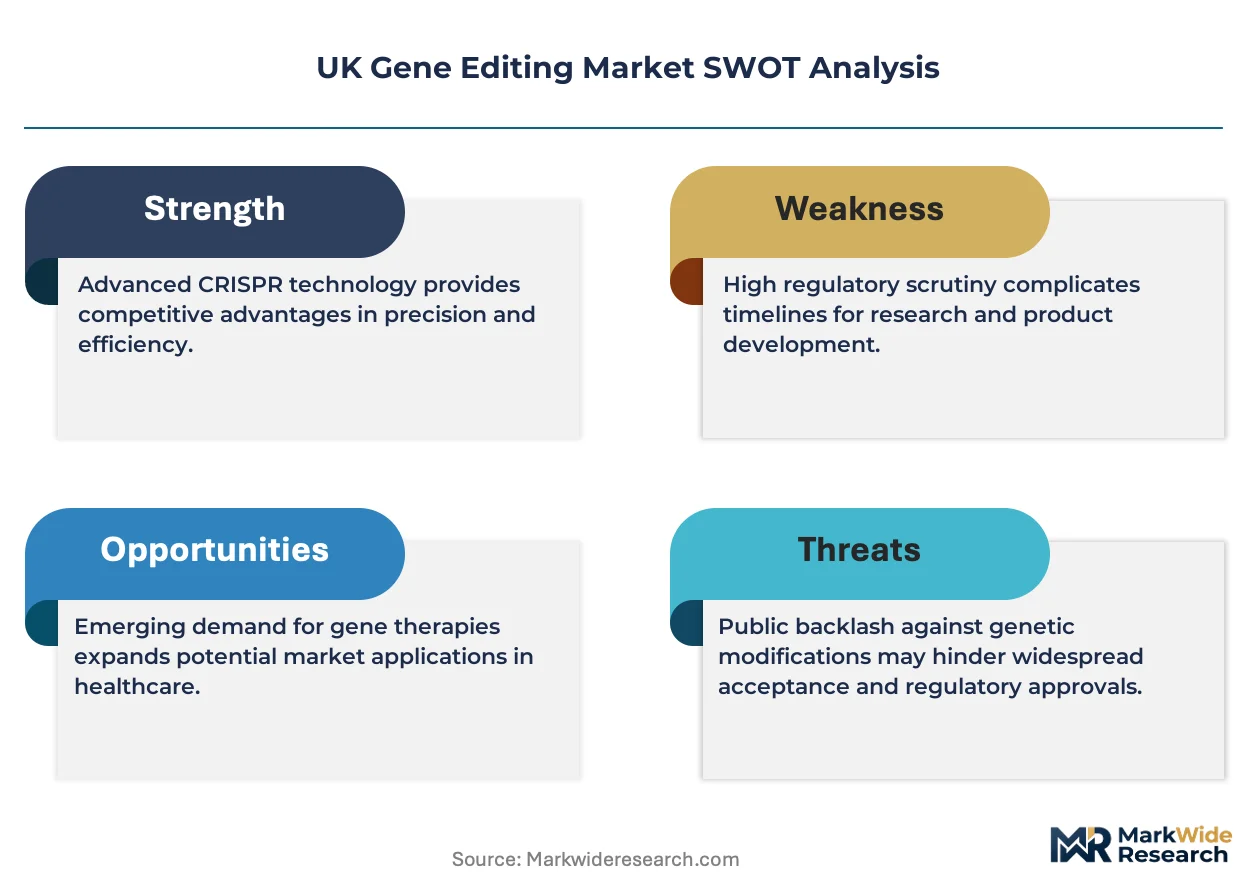
The MHRA's autonomous advanced therapy medicinal product pathway post-Brexit is bifurcating trial site selection between UK and EU jurisdictions, concentrating gene editing service demand within the Golden Triangle corridor.
Growth Catalysts
- ATMP Framework Acceleration:The MHRA streamlined approval timelines for investigational gene editing therapies, reducing regulatory lag between preclinical and Phase I initiation.
- Golden Triangle Cluster Density:Proximity between London, Oxford, and Cambridge creates 45-minute logistics loops for biological samples and specialized reagents.
- Base Editor Maturation:Cytosine and adenine base conversion technologies eliminate double-strand break risks, expanding addressable patient populations for precision therapeutics.
Market Restraints
- Guide RNA Synthesis Concentration:Contract manufacturing for synthetic guide RNAs concentrates among three European suppliers, creating single-source vulnerability for UK developers.
- EMA Divergence Costs:Separate MHRA and EMA filing requirements force duplicate quality documentation and divergent clinical data packages for cross-border trials.
- Electroporation Equipment Lead Times:Ex vivo cell modification protocols depend on specialized electroporation systems with 14-18 month manufacturer backlogs.
Strategic Opportunities
- Scottish Manufacturing Expansion:Underutilized biomanufacturing capacity in Glasgow and Edinburgh offers lower cost-per-batch economics for viral vector production.
- In Vivo Liver Targeting:Lipid nanoparticle delivery optimization for hepatocyte editing opens therapeutic categories beyond hematologic indications.
- BSI Certification Harmonization:ISO 13485 quality management certifications from BSI Group enable streamlined supplier qualification for NHS procurement frameworks.
Industry Challenges
- Translational Biology Talent Scarcity:Shortage of scientists capable of bridging discovery-stage CRISPR optimization and GMP-compliant process development constrains pipeline velocity.
- Multi-Site Trial Coordination:Fragmented ethics committee approvals across NHS trusts create asynchronous site activation timelines that compress enrollment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Gene Editing Market |
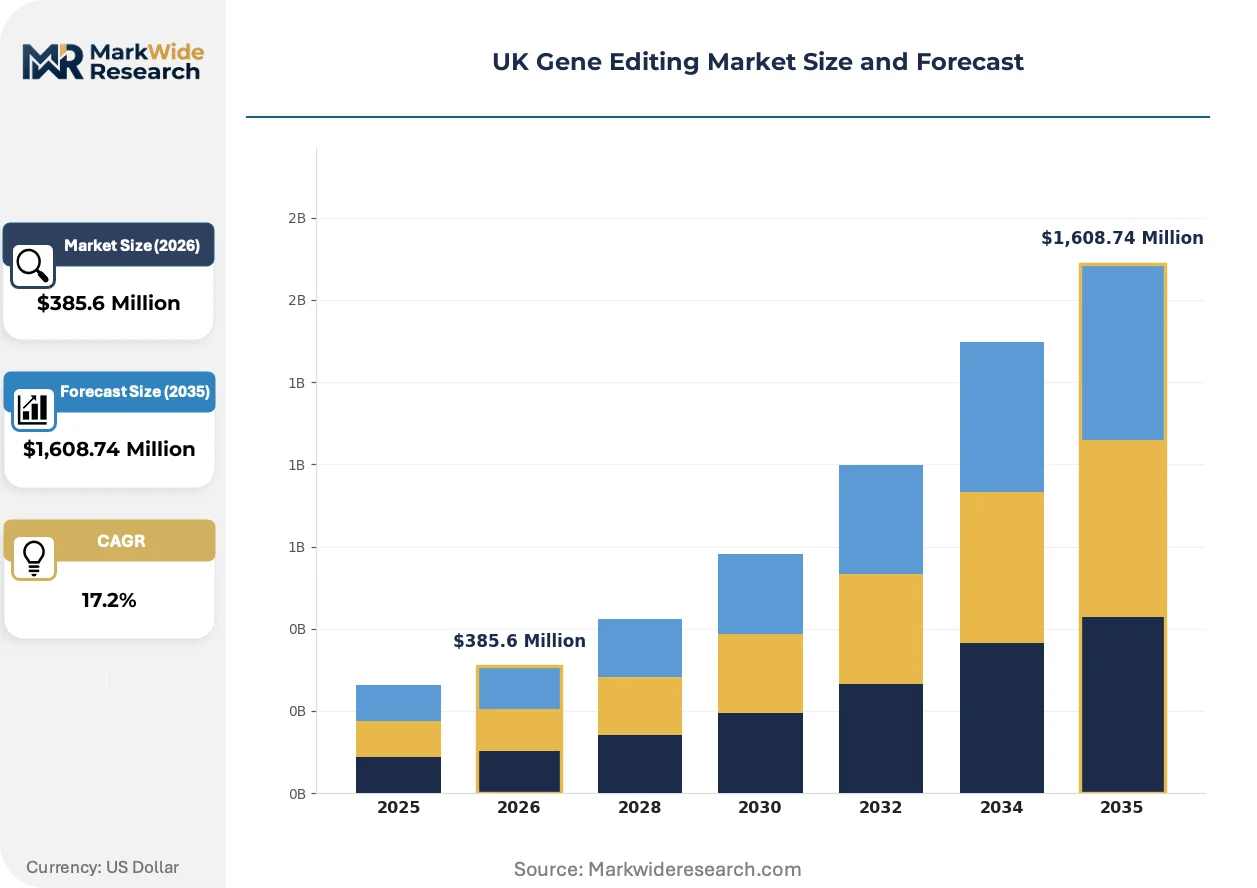
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,608.74 Million |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRISPR-Cas9, TALEN, Zinc Finger Nucleases, Meganucleases, Base Editors Application: Agricultural Biotechnology, Therapeutic Research, Industrial Biotechnology, Synthetic Biology, Diagnostics Development End User: Academic Institutions, Biopharmaceutical Companies, Contract Research Organizations, Government Laboratories, Startups Delivery Method: Viral Vectors, Non-viral Vectors, Lipid Nanoparticles, Electroporation, Microinjection |
| Companies Covered | CRISPR Therapeutics AG, Editas Medicine, Inc., Horizon Discovery, Merck KGaA, Thermo Fisher Scientific, Revvity, AstraZeneca, Lonza, Danaher Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Gene Editing Market Trends and Innovations
Gene editing platforms are converging with synthetic biology toolchains and automated cell processing systems, compressing development timelines from target validation to IND submission.
Prime editing systems incorporating reverse transcriptase fusion proteins are displacing conventional CRISPR-Cas9 knock-in approaches across therapeutic applications requiring precise sequence insertion without double-strand breaks. Biopharmaceutical developers in Cambridge and Oxford are adopting prime editing for correction of single-point mutations in inherited retinal diseases. The technology is displacing homology-directed repair workflows that required donor template co-delivery and suffered from low efficiency in non-dividing cells.
The MHRA's Innovation Passport designation creates accelerated access pathways for gene editing therapies addressing unmet medical needs, compressing the interval between scientific advice and clinical trial authorization. Developers receive integrated regulatory and health technology assessment input earlier in development, reducing downstream reimbursement uncertainty. Oncology and rare disease pipelines within the Golden Triangle cluster are restructuring regulatory strategies around this designation.
Service contracting is consolidating toward integrated therapeutic development partnerships that bundle discovery, manufacturing, and regulatory strategy under single-provider accountability. Academic spinouts and mid-cap biopharmaceutical firms are displacing fragmented vendor management with multi-year platform access agreements. This restructuring concentrates procurement authority within London-based venture capital portfolios and Cambridge anchor institutions.
UK Gene Editing Market Segmentation
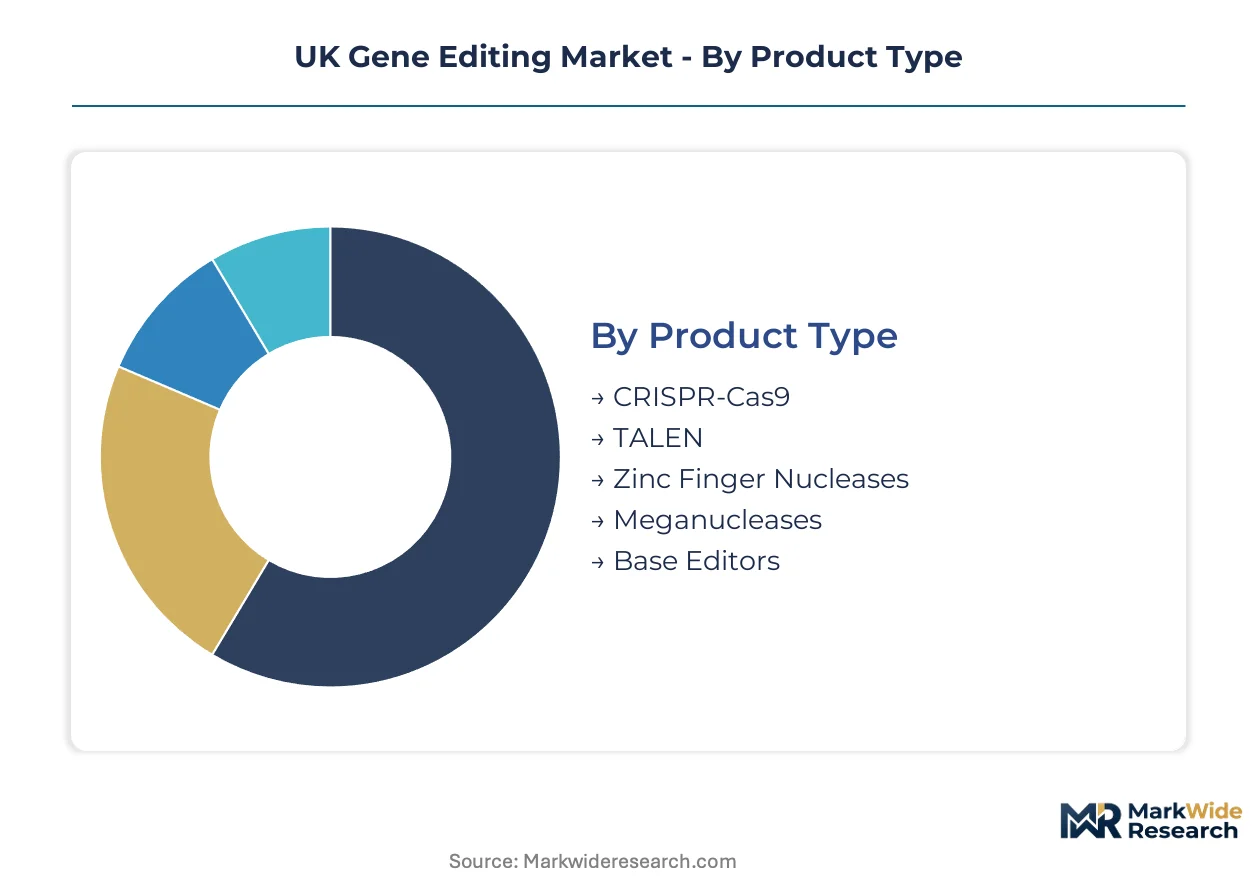
Gene editing market segmentation reveals distinct procurement patterns across the Golden Triangle. Technology maturity, regulatory pathway complexity, and end-user capability gaps determine where value concentrates within each category.
Product Type:
Domestic demand clusters around precision editing platforms with established MHRA approval precedents, while export-led segments target emerging therapeutic modalities with limited regulatory history.
- CRISPR-Cas9:Guide RNA-directed Cas endonuclease systems enable programmable double-strand breaks with protospacer adjacent motif recognition. Cambridge and Oxford biopharmaceutical developers dominate procurement for oncology and rare disease pipelines, driven by streamlined MHRA Innovation Passport access.
- Base Editors:Cytosine and adenine base conversion technologies eliminate double-strand break risks through direct nucleotide modification. London-based contract research organizations are scaling capacity fastest, constrained by limited UK-based guide RNA synthesis infrastructure.
- TALEN:Transcription activator-like effector nucleases offer reduced off-target activity for therapeutic applications.
- Zinc Finger Nucleases:First-generation programmable nucleases retain niche utility in agricultural biotechnology.
- Meganucleases:Rare-cutting endonucleases with extended recognition sites serve specialized industrial enzyme engineering.
CRISPR-Cas9 holds the largest share; momentum sits with Base Editors.
Application:
Milestone-driven licensing structures concentrate margin capture in segments with direct therapeutic revenue potential, while diagnostic and agricultural applications operate on fixed-fee contracting models.
- Therapeutic Research:Clinical-stage gene editing for oncology, rare disease, and inherited disorders generates royalty-stacked revenue on approved products. AstraZeneca's Cambridge expansion and CRISPR Therapeutics partnerships anchor demand, though MHRA-EMA divergence forces duplicate documentation costs.
- Synthetic Biology:Engineered biological systems for bio manufacturing and metabolic engineering attract venture capital deployment. Oxford spinouts and London-based startups drive procurement, constrained by translational biology talent scarcity between discovery and GMP stages.
- Agricultural Biotechnology:Crop trait engineering and livestock improvement for UK and export markets.
- Industrial Biotechnology:Microbial strain optimization for enzyme and chemical production.
- Diagnostics Development:Gene editing-enabled molecular diagnostic platforms for companion testing.
Therapeutic Research captures deepest margins; Synthetic Biology is expanding most quickly.
End User:
Procurement authority is consolidating within integrated therapeutic development partnerships that displace fragmented academic contracting.
- Biopharmaceutical Companies:Mid-cap and large-cap developers with vertical integration across discovery and clinical translation. Golden Triangle anchor institutions command premium partnership terms, driven by MHRA pathway acceleration and NHS reimbursement integration.
- Academic Institutions:University research groups and medical school laboratories with core facility access. Oxford, Cambridge, and Imperial College London sustain demand, constrained by limited GMP-compliant process development capabilities.
- Contract Research Organizations:Horizon Discovery and specialized cell line engineering service providers.
- Startups:Venture-backed spinouts from Golden Triangle academic institutions.
- Government Laboratories:Public sector research institutes with strategic biotechnology mandates.
Biopharmaceutical Companies command largest procurement volumes; Startups are gaining share fastest.
Delivery Method:
Supply concentration in specialized equipment manufacturing creates asymmetric lead time risks across in vivo and ex vivo protocols.
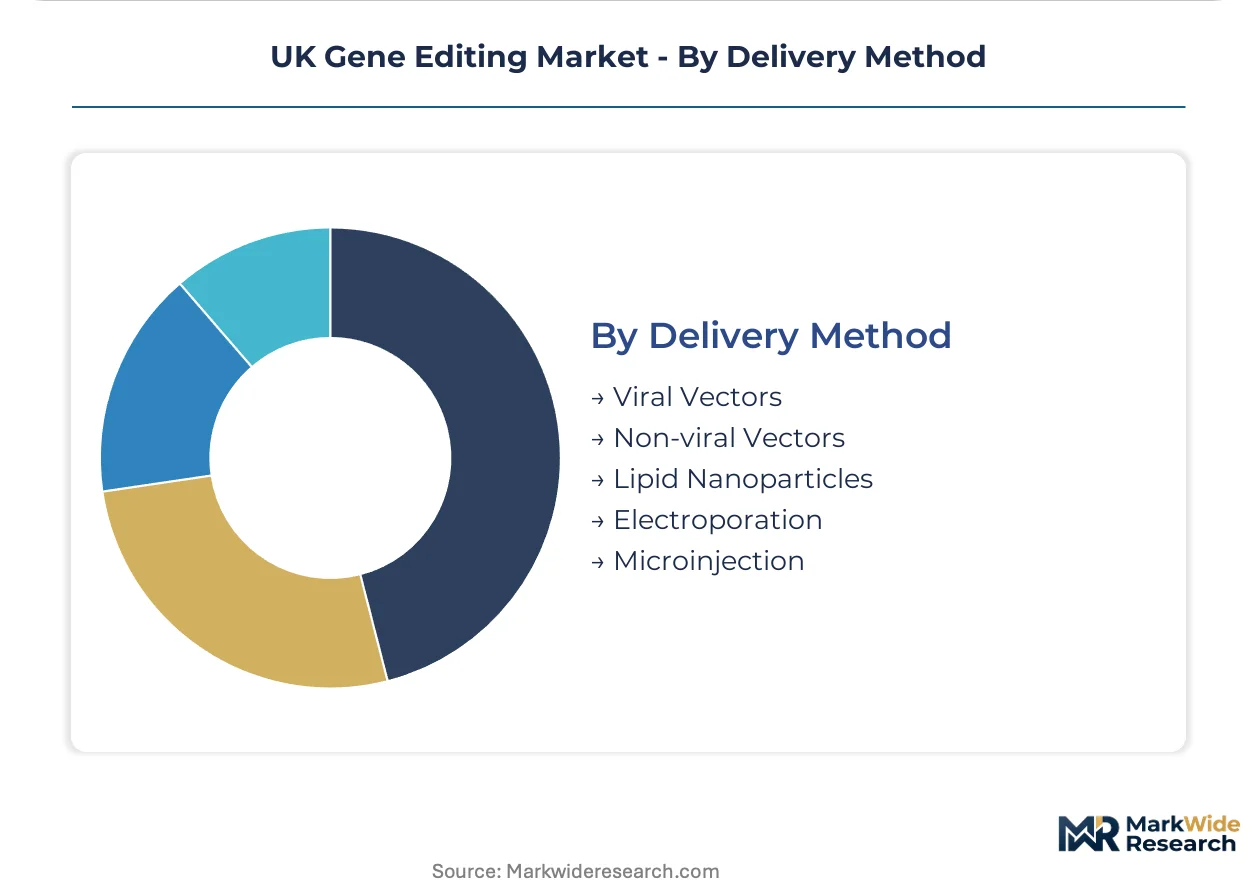
- Lipid Nanoparticles:Synthetic lipid assemblies encapsulating mRNA and guide RNA payloads for hepatocyte-targeted in vivo editing. Cambridge developers optimize liver-targeted oncology applications, constrained by European supplier concentration in ionizable lipid manufacturing.
- Electroporation:Electrical pulse-mediated membrane permeabilization for ex vivo hematopoietic cell modification. NHS trust cell therapy facilities and London-based CMOs dominate UK procurement, limited by 14-18 month equipment manufacturer backlogs.
- Viral Vectors:Adeno-associated and lentiviral delivery systems for persistent transgene expression.
- Non-viral Vectors:Polymer and peptide-based alternatives to viral and lipid delivery.
- Microinjection:Direct physical delivery for embryo editing and agricultural applications.
Electroporation retains largest installed base; Lipid Nanoparticles show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Golden Triangle rail corridor linking London King's Cross, Oxford, and Cambridge underwrites the UK's concentration in gene editing research, compressing logistics cycles for temperature-sensitive biological materials.
England — London/Southeast
Biopharmaceutical headquarters and venture capital deployment concentrate demand for integrated therapeutic development partnerships. The MHRA's Innovation Passport designation accelerates regulatory timelines for investigational therapies. King's Cross and White City clusters host contract research organizations scaling base editor manufacturing capacity.
England — East of England/Cambridge
AstraZeneca's anchor presence drives late-stage oncology pipeline investment in gene-edited cell therapies. The MHRA's autonomous ATMP framework post-Brexit attracts EU-divergent trial protocols. The Cambridge Science Park and Babraham Research Campus concentrate electroporation-equipped cell processing facilities.
England — Oxfordshire
Academic spinouts from the University of Oxford generate startup procurement of prime editing systems for inherited retinal disease applications. The HFEA restricts germline editing while permitting somatic therapeutic research. Oxford Science Park and Milton Park house synthetic biology ventures bridging discovery and GMP stages.
Scotland
Underutilized viral vector manufacturing capacity in Glasgow and Edinburgh offers lower cost-per-batch economics for biopharmaceutical developers. Scottish Enterprise funding supports advanced therapy manufacturing infrastructure expansion. The BioCampus Scotland initiative targets NHS cell therapy supply chain integration.
Wales
Cardiff and Swansea academic medical centers participate in multi-site gene editing trials with asynchronous ethics approvals across NHS trusts. Welsh Government life sciences investment focuses on diagnostic companion testing development. The Cardiff Medicentre hosts early-stage cell line engineering service providers.
UK Gene Editing Market Competitive Landscape
Concentration sits with vertically integrated biopharmaceutical developers and specialized cell line engineering service providers. The market structure bifurcates between anchor institutions commanding premium partnership terms and mid-cap firms displacing fragmented vendor management. Strategic archetypes include discovery-to-clinic integrators, platform technology licensors, and GMP-compliant manufacturing specialists. Competitive moves center on multi-year platform access agreements and backward integration into guide RNA synthesis capacity.
Among Switzerland-anchored biopharmaceutical developers, CRISPR Therapeutics AG exemplifies the vertically integrated archetype spanning discovery and clinical translation. Horizon Discovery occupies a position within the specialized cell line engineering tier, sustaining recurring revenue from contract research organizations. AstraZeneca represents the late-stage therapeutic application anchor, extending manufacturing and regulatory capabilities through its Cambridge footprint. These three entities illustrate the procurement authority consolidation reshaping service contracting patterns across the Golden Triangle.
| Leading Market Players |
|---|
| CRISPR Therapeutics AG |
| Editas Medicine, Inc. |
| Horizon Discovery |
| Merck KGaA |
| Thermo Fisher Scientific |
| Revvity |
| AstraZeneca |
| Lonza |
| Danaher Corporation |
| Others |
Pricing and Supply Chain Analysis
Underutilized viral vector manufacturing capacity in Glasgow and Edinburgh generates asymmetric scale economies that compress per-batch cost floors for UK-based biopharmaceutical developers while elevating price premiums for London and Cambridge service providers operating at full utilization. The Golden Triangle's 45-minute logistics loops for temperature-sensitive biological materials reinforce geographic price stratification between cluster-incumbents and peripheral competitors.
Pricing Analysis
Volume-discount tiering structures stratify across premium GMP-compliant manufacturing partnerships, standard contract research organization engagements, and economy academic core facility access. Price differentiation rests on MHRA certification grade and ISO 13485 quality management tier, with premium tiers commanding substantial markups for integrated therapeutic development accountability. Cost compression in the standard tier is intensifying because European guide RNA synthesis suppliers concentrate contract manufacturing among three dominant players. Academic institutions exhibit highest price sensitivity due to fixed grant funding constraints, while vertically integrated biopharmaceutical developers prioritize quality assurance over unit cost minimization.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container ports create vulnerability for UK gene editing reagent importers dependent on continental European chemical synthesis infrastructure. Geographic supply concentration centers on Germany, Switzerland, and the Netherlands for synthetic guide RNA precursors and specialized Cas enzyme production. Raw material dependencies encompass phosphoramidite chemistries, recombinant protein expression systems, and ionizable lipid formulations. Single-source vulnerability in electroporation equipment manufacturing presents structural risk given 14-18 month manufacturer backlogs. Distribution runs through NHS trust procurement frameworks and direct biopharmaceutical partnerships with Golden Triangle anchor institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK gene editing market constitutes a defensive-moat opportunity anchored in regulatory entrenchment: MHRA's autonomous ATMP pathway post-Brexit creates switching costs for developers seeking trial site activation within the Golden Triangle corridor.
For Market Incumbents: Fortify backward integration into guide RNA synthesis capacity to neutralize European supplier concentration risk. Anchor multi-year platform access agreements with Cambridge and Oxford academic spinouts before venture capital portfolios consolidate procurement authority. The emergence of Scottish viral vector manufacturing capacity threatens margin compression for incumbent service providers lacking geographic diversification. For New Entrants and Emerging Players: Lead with prime editing system specialization targeting inherited retinal disease applications where Oxford spinouts demonstrate unmet demand for precise sequence insertion without double-strand breaks. Scottish biomanufacturing expansion presents the most penetrable white-space for lower cost-per-batch viral vector production. A go-to-market angle centered on BSI certification harmonization enables streamlined NHS procurement qualification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform technology licensors with established MHRA approval precedents over discovery-stage tool developers facing translational biology talent scarcity. Long-term viability hinges on regulatory pathway acceleration sustaining premium partnership terms with biopharmaceutical developers. Acquisition target archetypes include specialized cell line engineering service providers with recurring CRO revenue. The signal to watch is MHRA-EMA divergence deepening, which would fragment trial site selection and concentrate value in UK-exclusive regulatory strategy capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guide RNA Synthesis | Captive supply of critical reagents neutralizes European supplier concentration vulnerability for UK developers. |
| Scottish Manufacturing Footprint Expansion | Underutilized Glasgow and Edinburgh capacity offers lower cost-per-batch economics for viral vector production. |
| MHRA Innovation Passport Designation Pursuit | Accelerated regulatory timelines compress intervals between scientific advice and clinical trial authorization. |
| Prime Editing Platform Specialization | Displacement of homology-directed repair workflows opens therapeutic categories in non-dividing cell applications. |
| BSI Certification Harmonization Investment | ISO 13485 quality management streamlines supplier qualification for NHS procurement frameworks. |
Research Methodology
A standing panel of gene therapy development executives, MHRA regulatory affairs leads, NHS trust procurement managers, and venture capital portfolio directors provided ongoing calibration across primary interview cycles. Secondary validation drew from MHRA advanced therapy medicinal product filings, EMA divergence documentation, ClinicalTrials.gov gene editing protocol registrations, and BSI Group certification databases. Bottom-up segment sizing triangulated against top-down market envelope constraints derived from biopharmaceutical R&D expenditure patterns.
Consistency checks validated volume and value outputs against external benchmarks spanning contract research organization revenue disclosures and venture capital deployment tracking across Golden Triangle academic spinouts. The analytical framework modeled technology type, application segment, end-user archetype, delivery method, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating MHRA pathway acceleration effects and base editor technology maturation curves.
Underlying assumptions cover sustained MHRA autonomy from EMA alignment, stable NHS reimbursement integration for gene editing therapies, and continued Golden Triangle cluster density, with deviation risk concentrated in regulatory divergence costs and guide RNA supply disruption. Practitioners should keep alternative scenarios live as MHRA-EMA relationship dynamics and Scottish manufacturing capacity utilization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Global Plant Breeding and CRISPR Plant Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
US Gene Editing Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
Knock Out Mouse Model Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
Immunodeficient Mouse Models Market